
 Pregabalin Market | 2026-2036
Pregabalin Market Size, Share, and Industry Trends Forecast 2026-2036
Pregabalin Market Intelligence
The development of extended-release formulations is reshaping competitive positioning among manufacturers. Pfizer sustains a brand premium with its legacy products and ongoing clinical data support. Viatris leverages its established distribution network for post-patent products, while Aurobindo Pharma competes aggressively on cost in the high-volume generic capsule segment.
Pregabalin is a gabapentinoid drug that functions by binding to the alpha-2-delta subunit of voltage-gated calcium channels in the central nervous system. It is primarily prescribed for managing neuropathic pain, epilepsy, and generalized anxiety disorder. The capsules product type holds the largest volume share due to early generic entry and cost-effectiveness. Neuropathic pain applications constitute the primary source of revenue for most suppliers.
Regulatory oversight from bodies like the U.S. FDA, which classifies pregabalin as a controlled substance, and the EMA in Europe, which mandates stringent pharmacovigilance, governs market access. In India, the CDSCO enforces manufacturing quality standards critical for the global export market. Future success for market participants will depend on navigating patent cliffs while investing in differentiated, value-added formulations.
Market Dynamics
The central dynamic shaping the pregabalin market is the tension between widespread genericization following patent expiries and the strategic push by innovators toward value-added, extended-release formulations to defend pricing power and market access in specialized therapeutic areas.
Growth Catalysts
- Expanding Clinical Applications:Regulatory approvals for pregabalin in treating conditions like fibromyalgia and generalized anxiety disorder, beyond its initial neuropathic pain indication, have significantly broadened the addressable patient population.
- Chronic Disease Prevalence:The rising global incidence of diabetes and post-herpetic neuralgia, both primary causes of neuropathic pain, directly supports sustained prescription volume for effective pain management agents.
- Improved Healthcare Access:In emerging economies across Asia and Latin America, expanding healthcare infrastructure and insurance coverage are enabling more patients to be diagnosed and treated for neuropathic conditions.
Market Restraints
- Substitution from Alternatives:Competition from other gabapentinoids, particularly the lower-cost gabapentin, as well as from different classes of analgesics and non-pharmacological therapies, limits market penetration in certain patient segments.
- Regulatory Hurdles:The classification of pregabalin as a Schedule V controlled substance by the U.S. FDA and similar controls in other nations create administrative burdens for prescribers and access barriers for patients.
- Intense Price Erosion:The expiration of primary patents has triggered aggressive price competition from a multitude of generic manufacturers, severely compressing revenue and margins for both branded and generic products.
Strategic Opportunities
- Novel Formulation Development:Investing in research for differentiated formulations, such as once-daily extended-release tablets or fixed-dose combinations, can enhance patient compliance and create new intellectual property.
- Geographic Expansion:There is significant potential in targeting undertreated populations in markets within the Middle East and Africa, where awareness and diagnosis of neuropathic pain are increasing.
- New Therapeutic Indications:Exploring the efficacy of pregabalin in off-label or unapproved indications through structured clinical trials could unlock new, patent-protected revenue streams for manufacturers.
Industry Challenges
- Pharmacovigilance Compliance:Adhering to the increasingly stringent and divergent post-marketing surveillance and risk management plan requirements from bodies like the EMA and PMDA presents a significant operational burden.
- API Supply Chain Concentration:Heavy reliance on a few manufacturing hubs, primarily in India and China, for active pharmaceutical ingredients creates vulnerability to geopolitical risks and quality control issues.
- Intellectual Property Defense:Originator companies face constant and costly legal challenges from generic firms attempting to invalidate patents on new formulations and delivery methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pregabalin Market |
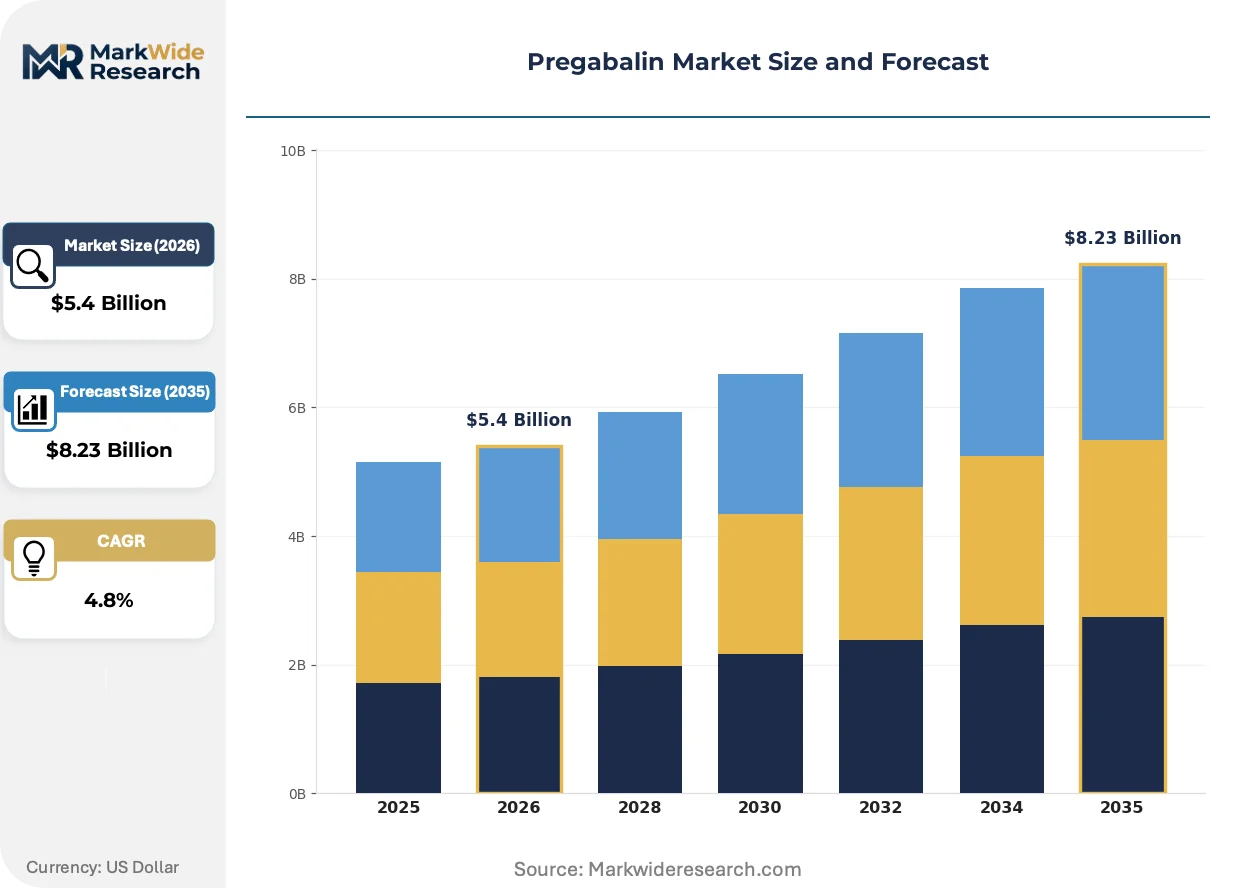
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Oral Solution, Extended-Release Tablets, Injection Powder, Tablets Therapy Area: Neuropathic Pain, Epilepsy, Generalized Anxiety Disorder, Fibromyalgia, Postherpetic Neuralgia End User: Pharmacies, Specialty Clinics, Outpatient Facilities, Long-term Care Centers, Diagnostic Laboratories Distribution Channel: Hospital Pharmacies, E-Pharmacies, Retail Pharmacies, Direct Sales, Authorized Distributors |
| Companies Covered | Aurobindo Pharma, Viatris, Pfizer, Lupin, Amneal Pharmaceuticals, Teva Pharmaceutical Industries, Cipla, Zydus Lifesciences, Sun Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pregabalin Market Strategic Shifts & Innovations
A central theme in the market involves creating clinical value beyond the base molecule. This is a direct response to both the commoditization of standard-release capsules and the growing demand from healthcare providers for treatments that improve patient outcomes and compliance.
Combination therapies that pair pregabalin with another active agent, such as a nonsteroidal anti-inflammatory drug or an opioid, are a key product evolution. Pain management specialists are adopting these products for patients with complex syndromes unresponsive to monotherapy. This approach is hybridizing treatment protocols, shifting from single-agent prescribing to tailored regimens that target multiple pain pathways for enhanced efficacy.
The EMA's stringent pharmacovigilance requirements, mandating comprehensive risk management plans, are establishing a global standard for post-approval safety monitoring. This policy compels all market authorization holders to invest in systems for tracking real-world adverse events. Generic drug manufacturers exporting to the European Union are most affected, as they must now build capabilities traditionally associated with originator companies.
Purchasing decisions within large healthcare systems are increasingly influenced by value-based frameworks that assess total cost of care. This model looks beyond the initial acquisition price to reward formulations that demonstrate superior patient outcomes, such as reduced side effects or better adherence. This trend is most prominent in countries with single-payer healthcare systems, where extended-release products can secure preferential formulary status.
Pregabalin Market Segmentation
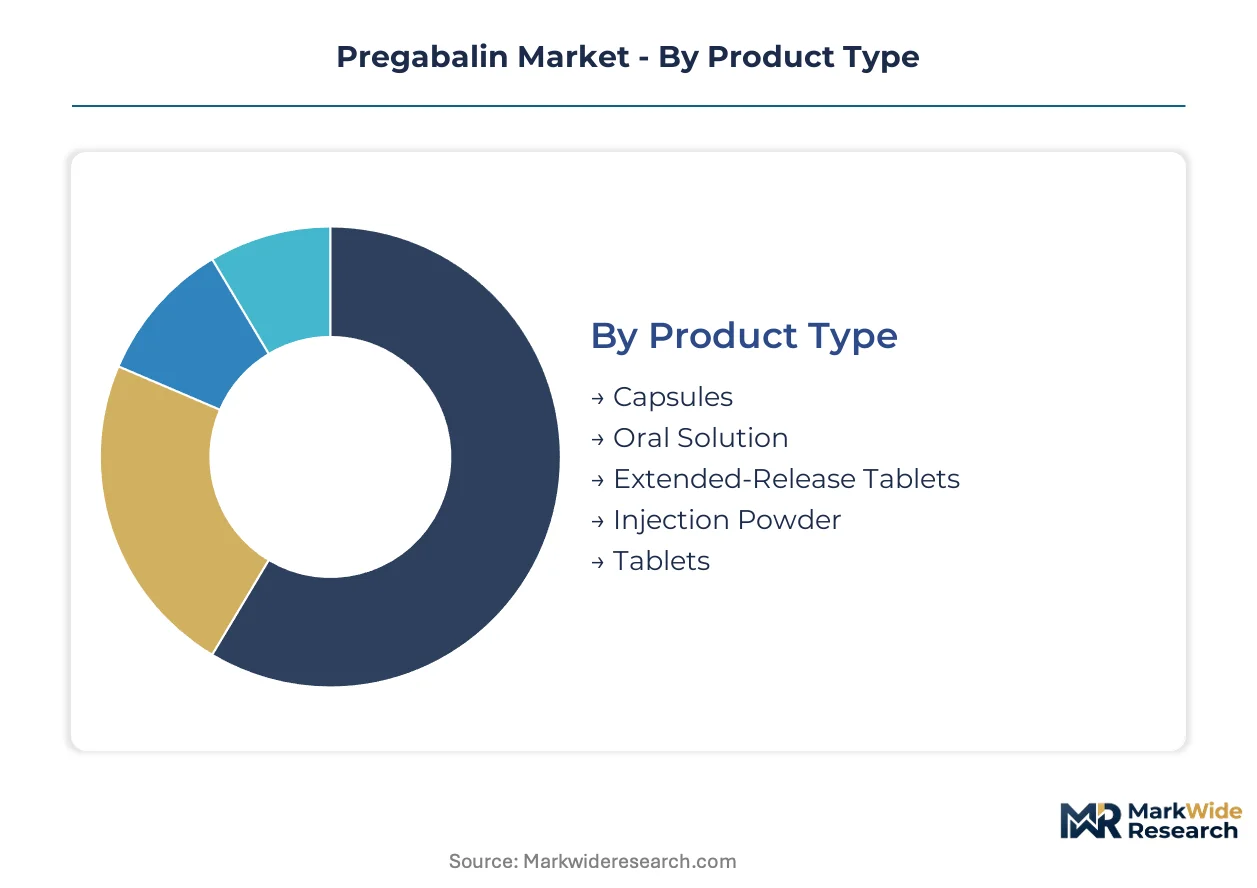
The segmentation of the pregabalin market provides a granular view of product variations, therapeutic applications, and patient access points. Analyzing these distinct categories helps manufacturers align product development and commercial strategies with specific market demands. Understanding these dynamics is crucial for navigating the competitive landscape and identifying growth opportunities.
Product Type:
The varied product types of pregabalin demonstrate differing adoption rates and manufacturing complexities, influencing their market cycle times.
- Capsules:This oral dosage form consists of a powder or gel encased in a soluble shell, offering precise dosing and ease of administration. Demand concentrates in generic markets due to early patent expiry and cost-effectiveness for widespread use.
- Extended-Release Tablets:These formulations are designed to release pregabalin slowly over an extended period, allowing for once-daily dosing and improved patient adherence. Demand is driven by innovator companies seeking to differentiate products and command premium pricing in specialized therapeutic areas.
- Oral Solution:A liquid formulation of pregabalin, typically used for patients who have difficulty swallowing tablets or capsules. This product type serves pediatric and geriatric populations primarily.
- Tablets:Solid oral dosage forms of pregabalin, often scored for dose flexibility, widely available in generic versions. Tablets provide a cost-effective alternative to capsules in many markets.
- Injection Powder:A sterile powder for reconstitution into an injectable solution, reserved for acute or severe cases where oral administration is not feasible. This form addresses critical care settings.
Capsules dominate the installed base. Extended-Release Tablets are where expansion concentrates.
Therapy Area:
Pregabalin's therapeutic utility spans multiple conditions, with certain applications generating the highest prescription volumes.
- Neuropathic Pain:This application addresses chronic pain caused by nerve damage, including diabetic neuropathy and post-herpetic neuralgia. Neuropathic pain constitutes the primary source of revenue for most pregabalin suppliers due to its high prevalence.
- Generalized Anxiety Disorder:Pregabalin is approved for managing chronic and excessive worry, often accompanied by physical symptoms. Expanding clinical applications in this area broaden the addressable patient population.
- Epilepsy:Pregabalin functions as an adjunctive therapy for partial-onset seizures in adult patients. This indication supports a stable, albeit smaller, segment of the market.
- Fibromyalgia:This chronic disorder causes widespread musculoskeletal pain, fatigue, and other symptoms, for which pregabalin offers symptomatic relief. Fibromyalgia represents a significant patient population requiring long-term treatment.
- Postherpetic Neuralgia:A common complication of shingles, this condition involves persistent nerve pain following a herpes zoster infection. Pregabalin effectively manages this specific type of neuropathic pain.
Neuropathic Pain applications command the largest market share. Generalized Anxiety Disorder shows the steepest expansion trajectory.
End User:
Different end-user segments exhibit varying procurement patterns and patient throughput for pregabalin prescriptions.
- Pharmacies:This segment includes retail and hospital pharmacies, serving as the primary dispensing points for outpatient and inpatient prescriptions. Pharmacies ensure broad patient access to pregabalin.
- Specialty Clinics:These facilities, such as pain management clinics and neurology centers, specialize in diagnosing and treating complex conditions. Specialty clinics drive demand for differentiated pregabalin formulations.
- Outpatient Facilities:Ambulatory surgical centers and clinics provide medical services that do not require an overnight stay. These facilities manage short-term and chronic conditions, including those treated with pregabalin.
- Long-term Care Centers:Nursing homes and assisted living facilities cater to elderly or chronically ill patients. These centers require consistent supply for ongoing medication management.
- Diagnostic Laboratories:While not direct prescribers, these laboratories support diagnosis and monitoring of conditions treated by pregabalin. They contribute indirectly to prescription volume by confirming patient needs.
Pharmacies represent the primary dispensing point. Specialty Clinics are increasingly influencing prescribing patterns for complex cases.
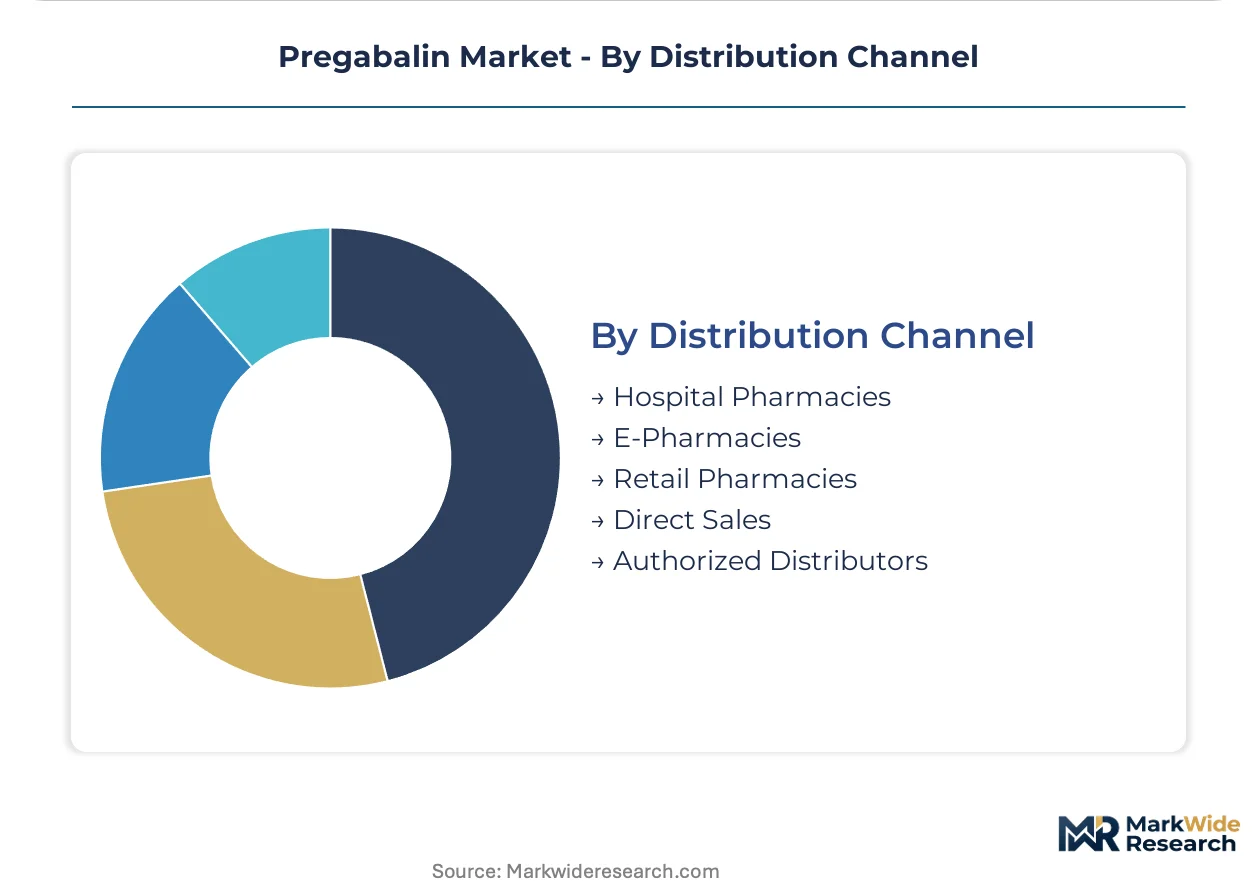
Distribution Channel:
The distribution channels for pregabalin reflect established healthcare logistics alongside emerging digital pathways.
- Retail Pharmacies:These independent and chain pharmacies serve the general public, dispensing the vast majority of outpatient pregabalin prescriptions. Retail pharmacies offer convenience and widespread geographic coverage.
- E-Pharmacies:Online platforms facilitate the purchase and delivery of prescription medications, offering convenience and often competitive pricing. E-pharmacies are gaining traction, particularly for chronic medication refills.
- Hospital Pharmacies:These pharmacies manage medication for inpatients and sometimes outpatients within a hospital setting. Hospital pharmacies ensure immediate access for acute care needs.
- Authorized Distributors:Wholesalers and distributors act as intermediaries between manufacturers and various healthcare providers. These entities ensure efficient bulk supply chain management.
- Direct Sales:Manufacturers sometimes engage in direct sales to large healthcare systems or government institutions. This channel bypasses traditional intermediaries for specific high-volume contracts.
Retail Pharmacies facilitate the majority of pregabalin dispensing. E-Pharmacies are rapidly gaining market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The manufacturing of active pharmaceutical ingredients for pregabalin largely concentrates in specific global hubs. This geographical focus influences pricing dynamics and supply chain resilience for finished formulations. Expanding healthcare access in diverse regions drives varied demand patterns.
United States
Demand for pregabalin in the United States is supported by high prevalence of neuropathic pain and generalized anxiety disorder. The U.S. FDA's classification of pregabalin as a Schedule V controlled substance impacts prescription practices. Research and development for novel formulations are concentrated in biotech hubs like Boston and San Diego.
India
India's large patient population and robust generic manufacturing capabilities drive significant domestic and export demand for pregabalin. The CDSCO enforces stringent manufacturing quality standards, critical for global market access. Pharmaceutical production clusters in Hyderabad and Ahmedabad are key to high-volume generic capsule output.
Germany
Neuropathic pain management and an aging population contribute to steady pregabalin demand in Germany. The EMA's stringent pharmacovigilance requirements shape post-marketing surveillance protocols for all market participants. Major pharmaceutical companies in Frankfurt and Munich are investing in advanced formulation technologies.
Japan
Japan's demand for pregabalin stems from its high incidence of post-herpetic neuralgia and an emphasis on pain management. The PMDA oversees drug approvals and safety, influencing market entry for new products. Pharmaceutical research centers in Tokyo and Osaka are exploring new therapeutic applications.
China
Expanding healthcare access and a rising chronic disease burden fuel growing pregabalin consumption in China. The NMPA regulates drug manufacturing and distribution, ensuring product quality and safety. Manufacturing facilities in the Yangtze River Delta region are increasing capacity for both APIs and finished dosage forms.
Pregabalin Market Key Industry Players
Innovator companies and generic manufacturers split the pregabalin market, each employing distinct strategies to secure market share. The market exhibits a tiered structure, with branded products commanding premium pricing while generics compete on cost-effectiveness. Strategic archetypes include patent-holding innovators, large generic players, and specialized formulation developers. Companies are engaging in geographic expansion and novel formulation development to sustain growth.
Within the innovator tier, Pfizer represents a brand premium with its legacy products and ongoing clinical data support, focusing on differentiated offerings. Viatris exemplifies a post-patent strategy, leveraging its established distribution network for off-patent products and maintaining a broad market presence. Aurobindo Pharma, an India-based generic manufacturer, anchors the high-volume generic capsule segment by competing aggressively on cost and expanding its manufacturing footprint. These companies demonstrate varied approaches to market competition, from defending intellectual property to maximizing generic market penetration and ensuring widespread access.
| Leading Market Players |
|---|
| Aurobindo Pharma |
| Viatris |
| Pfizer |
| Lupin |
| Amneal Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Cipla |
| Zydus Lifesciences |
| Sun Pharmaceutical Industries |
| Others |
Cost & Logistics Intelligence
Heavy reliance on a few manufacturing hubs, primarily in India and China, for active pharmaceutical ingredients creates vulnerabilities that impact pricing power and margin distribution across the value chain.
Pricing Analysis
The differentiated formulation segment, offering extended-release products, drives sustained revenue through improved patient adherence and premium pricing. Pricing operates on a tiered model, with innovator products commanding higher prices based on brand premium and ongoing clinical data support. Novel formulations, such as extended-release tablets, also justify price differentiation. Pricing pressure stems from aggressive generic competition, severely compressing margins for standard capsule products. The generic capsule segment exhibits the highest price sensitivity among buyers, prioritizing cost-effectiveness.
Supply Chain Analysis
Contract manufacturing capacity for generic pregabalin concentrates heavily in India and China, influencing global supply dynamics. The supply chain primarily draws from active pharmaceutical ingredients (APIs) sourced from these concentrated hubs. A structural risk involves single-source vulnerability due to the limited number of API producers, which can lead to supply disruptions. Distribution runs through a dual model, with authorized distributors managing bulk supply to pharmacies, and retail pharmacies serving as the primary dispensing point for outpatient prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pregabalin market presents a defensive moat story, primarily due to significant regulatory entrenchment and stringent pharmacovigilance requirements that create high barriers to entry for new players.
For Market Incumbents: Insulate innovator product lines through continuous clinical data generation and investment in novel, differentiated formulations. This strategy helps defend against intense genericization and price erosion. Strengthening intellectual property defense for new delivery methods is crucial to counter legal challenges from generic firms. Reinforce pharmacovigilance capabilities to meet stringent regulatory requirements from bodies like the EMA, maintaining market access in key regions.
For New Entrants and Emerging Players: Underserved pediatric and geriatric populations requiring oral solutions represent a penetrable entry point. The high-volume generic capsule segment in emerging economies also offers significant opportunity. New entrants can target these areas by competing aggressively on cost and leveraging established local distribution networks. Focusing on manufacturing quality standards, particularly for export to regulated markets, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across differentiated formulation development and manufacturing capacity expansion. Long-term viability hinges on sustained demand from chronic disease prevalence and expanding clinical applications. Acquisition targets should include specialized formulation developers or generic manufacturers with strong distribution networks in high-growth emerging markets. The signal to watch is regulatory approvals for new indications or novel formulations, indicating future revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | New clinical data for pregabalin in niche applications can broaden the addressable patient population. |
| Regulatory Approval Pathway | Securing approvals for extended-release formulations enhances product differentiation and market access. |
| Manufacturing Scale-Up | Increasing capacity in India supports high-volume generic capsule output for global export markets. |
| Licensing Agreement | Partnerships for novel delivery technologies can accelerate product development and market entry. |
| Pipeline Diversification | Exploring fixed-dose combinations with other analgesics targets complex pain syndromes more effectively. |
Research Approach
Initial hypotheses were tested against primary input from pharmaceutical R&D executives, regulatory affairs specialists, pain management clinicians, and hospital procurement managers, then refined. This involved combining insights from these industry stakeholders with secondary validation from U.S. FDA filings, EMA pharmacovigilance reports, CDSCO manufacturing standards, and pharmaceutical trade journals. A comprehensive approach integrated both bottom-up market sizing and top-down validation.
The demand-supply balance over the projection horizon was meticulously analyzed using a robust analytical framework. This framework modeled segmentation dimensions including product type, therapy area, end user, distribution channel, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends, projected market drivers, and competitive dynamics. Chronic disease prevalence data and patent expiry schedules served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare spending or regulatory policy would shift the trajectory of the market. Forecasts reflect underlying assumptions regarding market dynamics and technological advancements. Quarterly review of prescription volumes and pharmacovigilance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Sarcoma Drugs Market