
 Global Rheumatoid Arthritis Therapeutics Market | 2026-2036
Global Rheumatoid Arthritis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rheumatoid Arthritis Therapeutics Market Foresight
Hospital outpatient settings is restructuring rheumatoid arthritis care delivery as health systems shift infusion therapy from inpatient wards to ambulatory centers. AbbVie Inc. leverages its immunology manufacturing scale to dominate adalimumab supply chains across North America and Europe. Pfizer Inc. competes through JAK inhibitor development programs while Bristol-Myers Squibb Company anchors its position with Orencia in the biologic DMARD segment.
Rheumatoid arthritis therapeutics comprise pharmaceutical agents targeting autoimmune joint inflammation through immunomodulation, including synthetic small molecules, recombinant biologics, and targeted synthetic DMARDs formulated for oral, subcutaneous, or intravenous delivery. These agents function primarily to suppress synovial inflammation, halt radiographic joint damage progression, and preserve functional mobility in seropositive and seronegative patient populations. Biologic DMARDs command the largest revenue share due to premium pricing and entrenched prescriber loyalty, while JAK inhibitors represent the fastest-expanding category as oral convenience attracts payer preference and patient adherence. Conventional DMARDs occupy the mature base of therapy algorithms, with methotrexate retaining first-line status despite biosimilar erosion in advanced biologics.
The FDA maintains accelerated approval pathways for breakthrough immunology therapies while EMA pharmacovigilance requirements shape JAK inhibitor risk-benefit labeling across European markets. WHO inclusion of biologic DMARDs in essential medicines lists influences procurement standards in emerging markets and reference pricing frameworks. Stakeholders must monitor evolving FDA boxed warning requirements for JAK inhibitors and corresponding EMA PRAC safety reviews that could redirect prescribing toward IL-6 pathway inhibitors or emerging B-cell targeted therapies.
Market Dynamics
Biologic DMARD supply concentration among contract manufacturing organizations in Switzerland and Ireland is forcing rheumatology clinics to secure multi-year offtake agreements as capacity constraints tighten across sterile injectable production networks.
Growth Catalysts
- FDA Accelerated Approval Pathway:The FDA's breakthrough therapy designation streamlines development timelines for novel IL-6 pathway inhibitors, compressing regulatory review phases for sponsors with robust biomarker data packages.
- Subcutaneous Formulation Migration:Rheumatology clinics in Germany and Japan are converting infusion suites to self-injection training centers as patient preference for home administration intensifies.
- Pharmacovigilance Infrastructure:EMA's PRAC safety monitoring frameworks enhance prescriber confidence in biologic DMARD risk profiles, supporting sustained adoption across European outpatient settings.
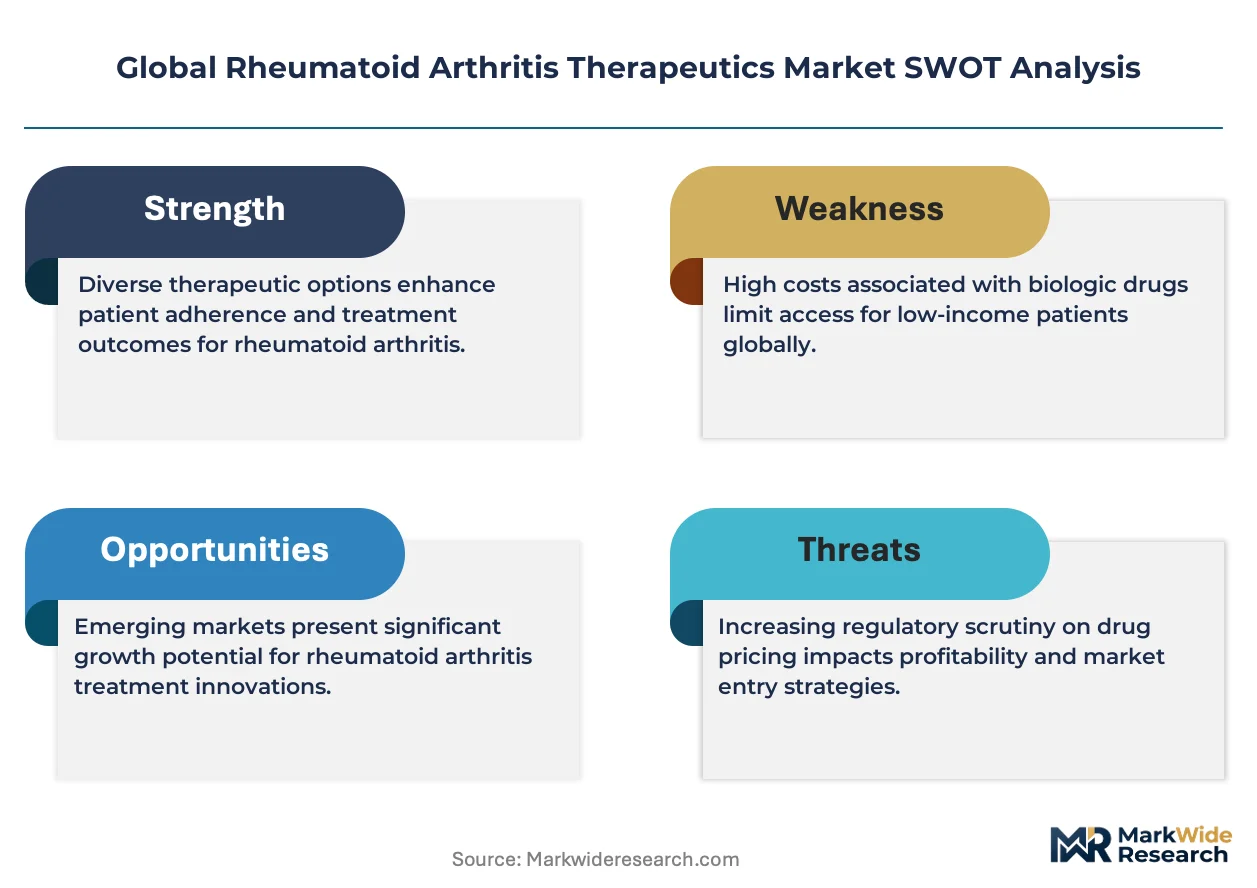
Market Restraints
- Plasma-Derived Input Volatility:Fractionation capacity constraints for immunoglobulin feedstocks elevate production costs for monoclonal antibody therapies sourced from US and European blood plasma networks.
- JAK Inhibitor Label Compression:FDA boxed warning requirements for thromboembolic events restrict prescribing flexibility, redirecting treatment algorithms toward parenteral biologics in cardiovascular-risk patient populations.
- Biosimilar Erosion Dynamics:Adalimumab biosimilar entry across German and French tendering systems compresses reference product pricing, constraining revenue pools for originator maintenance therapies.
Strategic Opportunities
- Brazilian Public Procurement Expansion:ANVISA alignment with WHO essential medicines criteria opens institutional tender pathways for adalimumab and etanercept biosimilars within Brazil's unified health system.
- Digital Therapeutics Convergence:Integration of smartphone-based adherence monitoring with subcutaneous injection devices creates differentiated value propositions for payers managing polypharmacy in seropositive populations.
- Specialty Pharmacy Channel Development:Limited distribution networks in the United States concentrate patient data capture, enabling outcomes-based contracting arrangements with commercial insurers and Medicare Part D plans.
Industry Challenges
- Cold Chain Integrity Requirements:Temperature-controlled logistics for biologic DMARDs demand validated storage infrastructure across ambulatory infusion centers, elevating capital deployment for clinic network expansion.
- Interchangeability Study Burden:Biosimilar developers face extensive switching trial requirements to secure pharmacy-level substitution authority, extending development timelines and regulatory expenditure.
- Legacy EHR Integration Friction:Rheumatology practices struggle to embed patient-reported outcome measures into existing electronic health record workflows, complicating value-based care reporting obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rheumatoid Arthritis Therapeutics Market |
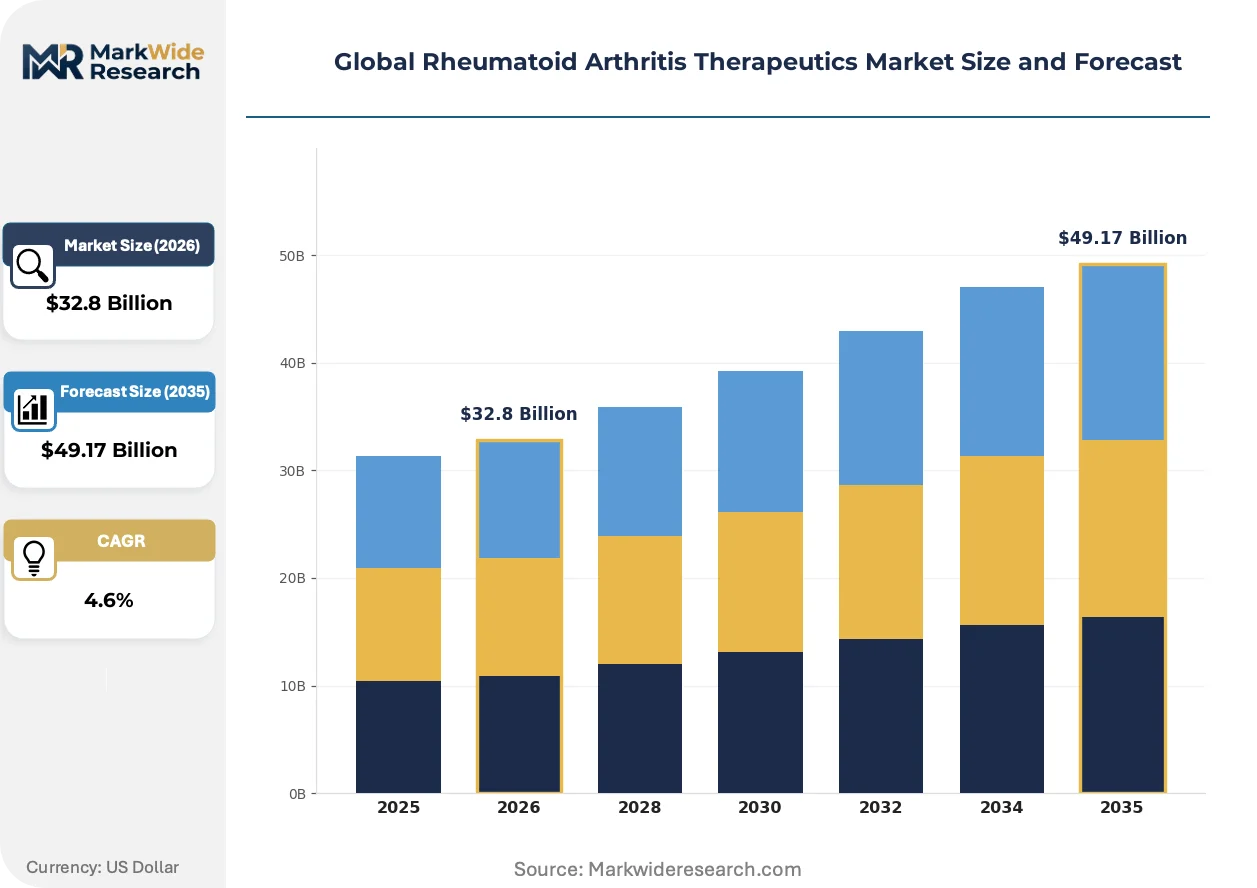
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional DMARDs, Biologic DMARDs, JAK Inhibitors, Glucocorticoids, NSAIDs Therapy Area: Early-Stage Management, Moderate Disease Control, Advanced Disease Management, Remission Induction End User: Rheumatology Clinics, Specialty Hospitals, Outpatient Care Centers, Research Institutions Delivery Mode: Oral Administration, Injectable Solutions, Infusion Therapy, Topical Treatment |
| Companies Covered | AbbVie Inc., Pfizer Inc., Amgen Inc., Johnson & Johnson Services, Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, UCB S.A., Novartis AG, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rheumatoid Arthritis Therapeutics Market Shifts & Advancements
Oral small-molecule therapies are compressing the traditional infusion-center model as prescribing patterns fragment across convenience-driven patient segments and risk-averse payer formularies.
Biosimilar manufacturing is absorbing excess capacity from legacy monoclonal antibody facilities as originator sponsors retool toward next-generation bispecific constructs. Contract development organizations in Switzerland are expanding single-use bioreactor footprints to capture this migration. The technology shift is absorbing price erosion pressure that would otherwise collapse originator margins across European tender markets.
EMA's evolving pharmacovigilance requirements for JAK inhibitor class labeling are tightening risk-benefit documentation standards across European marketing authorization holders. The policy framework compels sponsors to maintain active comparator safety databases beyond initial approval phases. Rheumatology societies in Germany and France are responding by developing standardized cardiovascular risk stratification protocols for treatment-naive patients.
Patient switching behavior between biologic DMARD classes is accelerating as real-world evidence platforms enable rapid comparative effectiveness assessment. Payer pharmacy benefit managers in the United States are leveraging these data to enforce step-therapy protocols that prioritize lower-cost biosimilars. The behavioral shift concentrates most visibly in Medicare Part D formularies, where annual plan redesigns force re-evaluation of established therapy regimens.
Global Rheumatoid Arthritis Therapeutics Market Segmentation
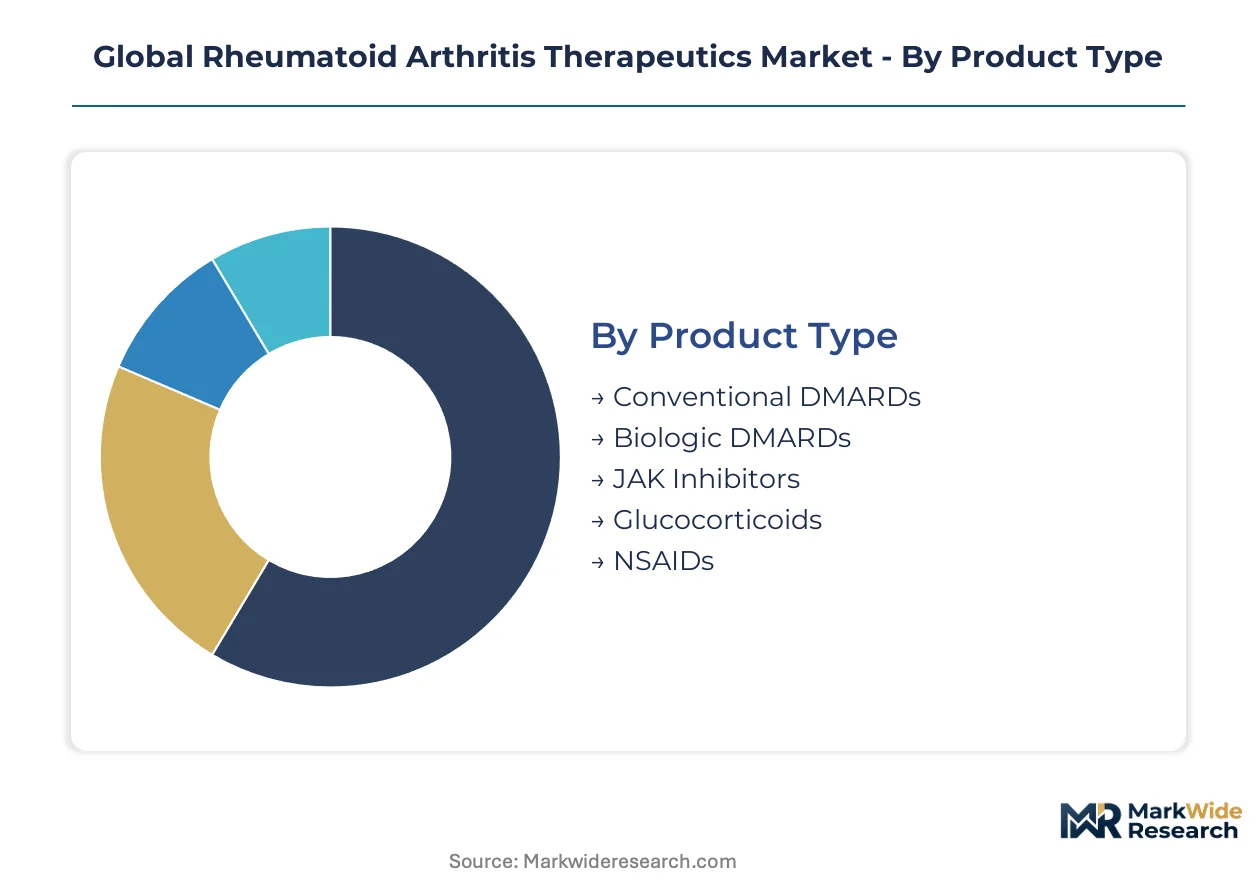
Therapeutic modality selection in rheumatoid arthritis treatment hinges on disease severity stratification, comorbidity profiles, and payer reimbursement tiers. Segmentation reveals how prescriber behavior fragments across convenience-driven oral therapies and clinically intensive biologic interventions.
Product Type:
Prescriber loyalty and payer formulary positioning drive category selection, with administration convenience competing against clinical efficacy documentation.
- Biologic DMARDs:Recombinant monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-6, or CD80/CD86 pathways require cold-chain distribution and infusion center capacity. Demand concentrates in the United States and Germany where specialty pharmacy networks support prior authorization workflows and patient assistance programs.
- JAK Inhibitors:Oral small-molecule agents targeting intracellular signaling pathways offer home administration advantages but carry FDA-mandated cardiovascular risk labeling. Patient preference for pill-based regimens is accelerating uptake in Japan and among Medicare Part D populations seeking to avoid infusion center visits.
- Conventional DMARDs:Synthetic antirheumatic agents led by methotrexate retain first-line positioning across treatment algorithms worldwide.
- Glucocorticoids:Corticosteroid bridging therapy provides rapid symptom control during DMARD initiation or flares.
- NSAIDs:Nonsteroidal anti-inflammatory drugs address symptomatic pain management without disease-modifying activity.
Volume sits with Conventional DMARDs; growth tilts toward JAK Inhibitors.
Therapy Area:
Disease progression staging determines therapeutic intensity, with treat-to-target protocols mandating escalation pathways based on radiographic and laboratory markers.
- Moderate Disease Control:Patients with active disease despite conventional DMARD therapy require biologic or targeted synthetic DMARD escalation. Rheumatology clinics in France and the United Kingdom concentrate resources here as stepped-care protocols dominate national health system formularies.
- Advanced Disease Management:Refractory cases with structural joint damage demand combination biologic therapy or surgical consultation. German and Japanese referral centers attract complex cases requiring multidisciplinary orthopedic-rheumatology coordination.
- Early-Stage Management:Window-of-opportunity intervention aims to prevent irreversible joint damage.
- Remission Induction:Aggressive treatment protocols target sustained low disease activity or remission states.
Clinical investment clusters in Moderate Disease Control; pipeline innovation targets Advanced Disease Management.
End User:
Site-of-care economics and reimbursement mechanics shape channel preference, with ambulatory migration reducing inpatient utilization.
- Rheumatology Clinics:Dedicated autoimmune specialty practices manage longitudinal care and biologic therapy monitoring. Independent clinic networks in the United States and Switzerland are expanding infusion capacity as hospital systems divest outpatient rheumatology services.
- Specialty Hospitals:Academic medical centers handle complex comorbidities and clinical trial enrollment. German university hospitals anchor regional referral patterns for refractory cases requiring tertiary intervention.
- Outpatient Care Centers:Ambulatory infusion facilities offer cost-efficient biologic administration outside hospital cost structures.
- Research Institutions:Clinical trial sites drive pipeline access and real-world evidence generation.
Patient volume flows through Rheumatology Clinics; infrastructure investment favors Outpatient Care Centers.
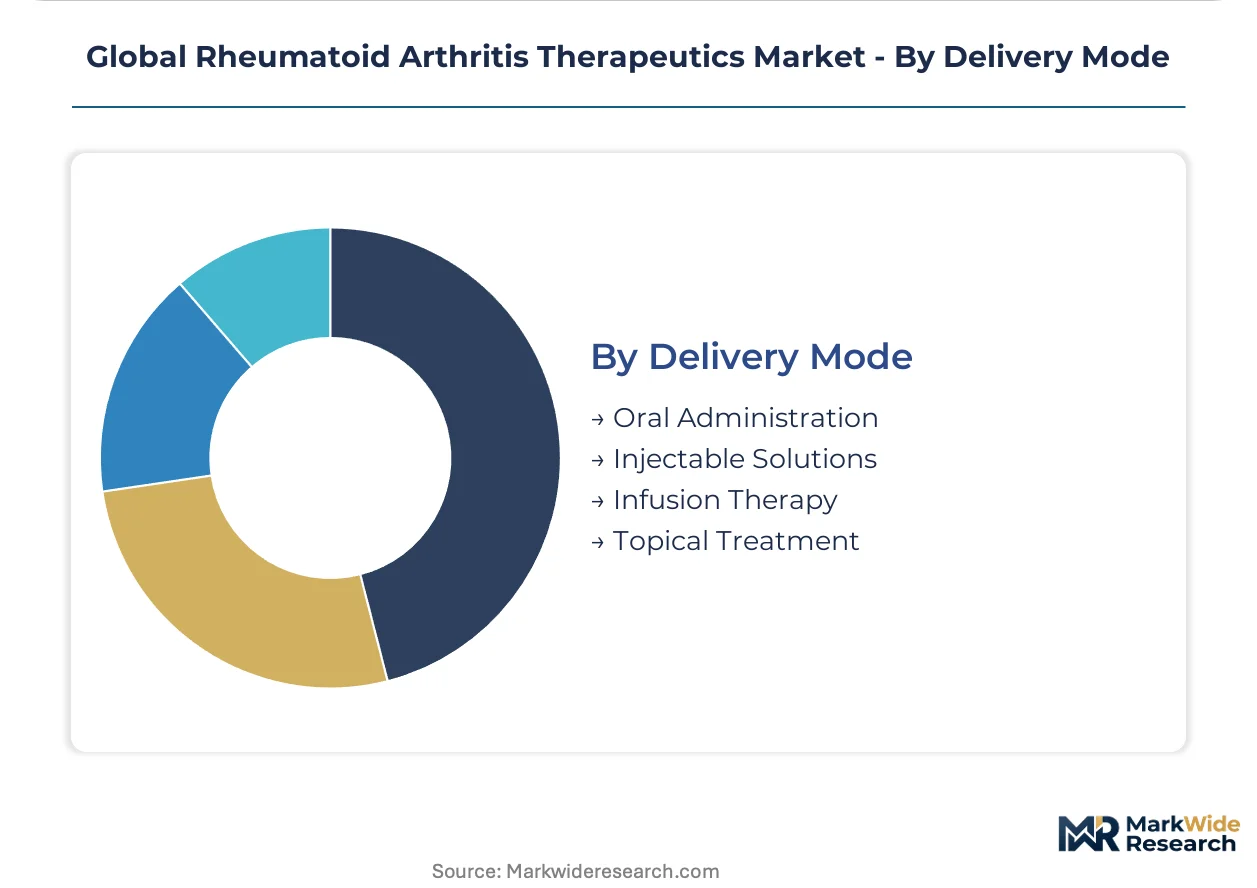
Delivery Mode:
Administration route selection reflects patient autonomy preferences, nursing resource constraints, and pharmacokinetic optimization for specific drug classes.
- Injectable Solutions:Subcutaneous formulations using prefilled syringes or auto-injectors enable home administration with monthly or biweekly dosing. Japanese and German markets show strongest preference as patient training programs and telemedicine support expand.
- Infusion Therapy:Intravenous biologic delivery requires healthcare facility presence but offers dosing flexibility and compliance assurance. United States hospital outpatient departments retain significant volume despite site-of-care policy pressure from commercial payers.
- Oral Administration:Small-molecule therapies eliminate injection burden but demand strict adherence monitoring.
- Topical Treatment:Localized delivery addresses limited joint involvement with minimal systemic exposure.
Revenue concentration remains with Infusion Therapy; patient demand shifts fastest toward Injectable Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Basel pharmaceutical cluster concentrate biologics manufacturing capacity, attracting contract development organizations seeking proximity to FDA review processes and sterile injectable expertise.
United States
Specialty pharmacy networks in Boston and Philadelphia manage prior authorization workflows for biologic DMARDs while Medicare Part D formularies enforce step-therapy protocols favoring biosimilars. FDA boxed warning requirements for JAK inhibitors redirect prescribing toward IL-6 pathway inhibitors in cardiovascular-risk populations. The Research Triangle Park corridor anchors sterile injectable production for North American distribution.
Germany
Rheumatology clinics in Munich and Hamburg convert infusion suites to self-injection training centers as patient preference for home administration intensifies. EMA pharmacovigilance frameworks shape JAK inhibitor risk-benefit labeling across European marketing authorization holders. The Baden-Württemberg region hosts contract manufacturing organizations supplying prefilled syringe formulations to European tender markets.
Japan
PMDA accelerated approval pathways compress development timelines for novel IL-6 pathway inhibitors with robust biomarker data packages. Telemedicine support programs expand patient training for subcutaneous auto-injector administration in Tokyo and Osaka metropolitan areas. The Kansai region concentrates biologics distribution infrastructure serving Asia-Pacific markets.
Switzerland
Contract development organizations in Basel expand single-use bioreactor footprints to capture manufacturing migration from legacy monoclonal antibody facilities. Swissmedic alignment with EMA safety monitoring frameworks supports sustained prescriber confidence in biologic DMARD risk profiles. The Lake Geneva region anchors sterile fill-finish capacity for European outpatient settings.
Brazil
ANVISA alignment with WHO essential medicines criteria opens institutional tender pathways for adalimumab and etanercept biosimilars within the unified health system. São Paulo specialty hospitals anchor regional referral patterns for refractory cases requiring tertiary intervention. The Southeast region concentrates rheumatology clinic networks expanding biologic therapy access.
Global Rheumatoid Arthritis Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator biologics commanding premium pricing in United States and German markets while biosimilar developers absorb tender pressure in European and Latin American procurement systems. The vendor base concentrates among immunology-focused pharmaceutical conglomerates with integrated manufacturing footprints and sterile injectable expertise. Three archetypes dominate: large-cap biologics originators with entrenched prescriber loyalty, mid-scale JAK inhibitor specialists pursuing oral convenience differentiation, and emerging biosimilar manufacturers leveraging excess contract manufacturing capacity. Competitive moves center on portfolio diversification into next-generation bispecific constructs and geographic expansion through emerging market licensing arrangements.
Within the large-cap biologics tier, AbbVie Inc. and Bristol-Myers Squibb Company exemplify archetypes anchored by immunology manufacturing scale and entrenched hospital formulary positioning. Pfizer Inc. occupies a position representing JAK inhibitor development concentration amid FDA safety labeling evolution. These three entities collectively illustrate how competitive positioning fragments across administration convenience vectors and regulatory risk profiles.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Johnson & Johnson Services, Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| UCB S.A. |
| Novartis AG |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Payer pharmacy benefit managers in the United States and Germany anchor procurement volume for rheumatoid arthritis therapeutics, locking in multi-year offtake agreements that privilege contract-based long-term pricing over spot-market transactions. This buyer concentration amplifies price negotiation leverage, compressing margins for originator biologics while rewarding biosimilar developers with volume commitments tied to cold-chain reliability guarantees.
Pricing Analysis
Short lead-time premiums dominate rheumatology clinic procurement, with facilities paying markup differentials for biologic DMARDs delivered within validated cold-chain windows under 72 hours. Three-tier pricing structure across premium, standard, and economy levels stratifies by biosimilar interchangeability status and FDA certification tier, with cardiovascular-risk patient populations commanding premium tier access to IL-6 pathway inhibitors. Cost compression in the JAK inhibitor segment is intensifying because FDA boxed warning requirements have narrowed prescriber discretion, redirecting formulary placement toward parenteral alternatives. Medicare Part D populations demonstrate highest price sensitivity, while academic medical centers with captive infusion capacity exhibit lowest elasticity due to bundled reimbursement mechanics.
Supply Chain Analysis
Plasma-derived immunoglobulin feedstocks rest on fractionation capacity concentrated in the United States, Germany, and Switzerland, where contract manufacturing organizations have retooled legacy monoclonal antibody facilities toward biosimilar production. Single-use bioreactor components, sterile fill-finish vials, and temperature-controlled logistics infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in Swiss and Irish sterile injectable production networks, where capacity constraints force rheumatology clinics into multi-year queue commitments. Distribution runs through specialty pharmacy channels in the United States and hospital outpatient departments in Germany, with direct-to-clinic cold-chain delivery gaining share in Japanese metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA pharmacovigilance requirements for JAK inhibitor labeling have erected a cost-of-compliance barrier that favors incumbents with established safety databases and regulatory affairs infrastructure, marginalizing developers lacking active comparator trial capabilities.
For Market Incumbents: Cement formulary positioning through backward integration into sterile fill-finish capacity in the Research Triangle Park corridor, capturing margin that currently leaks to Swiss contract manufacturers. Expand patient assistance program enrollment to defend against adalimumab biosimilar substitution pressure in Medicare Part D formularies. Prioritize IL-6 pathway inhibitor development to capture prescribing migration away from JAK inhibitors in cardiovascular-risk populations.
For New Entrants and Emerging Players: Rheumatology clinic networks in Brazil's Southeast region present the most penetrable white-space target, where ANVISA alignment with WHO essential medicines criteria has opened institutional tender pathways for adalimumab and etanercept biosimilars. Telemedicine-supported self-injection training programs in Japan's Kansai region offer a second viable entry vector. Pursue go-to-market positioning around digital therapeutics convergence, integrating smartphone-based adherence monitoring with subcutaneous auto-injector devices to differentiate against legacy infusion-center models.
For Investors and Strategic Acquirers: The window for entry favors contract manufacturing organizations with validated sterile injectable capacity and EMA-aligned pharmacovigilance infrastructure. Long-term viability hinges on exposure to next-generation bispecific constructs rather than legacy TNF-alpha monoclonal antibodies. Monitor FDA boxed warning scope expansion for JAK inhibitor class labeling as the critical inflection signal determining prescribing algorithm redirection toward IL-6 or B-cell targeted alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pharmacovigilance Alignment | Swissmedic safety monitoring frameworks sustain prescriber confidence in biologic DMARD risk profiles across European outpatient settings. |
| Subcutaneous Formulation Migration | Rheumatology clinics in Munich and Hamburg convert infusion suites to self-injection training centers capturing patient preference shifts. |
| Biosimilar Manufacturing Scale-Up | Basel contract development organizations expand single-use bioreactor footprints absorbing price erosion pressure from European tender markets. |
| Specialty Pharmacy Channel Development | Limited distribution networks in Boston and Philadelphia concentrate patient data capture enabling outcomes-based Medicare Part D contracting. |
| Digital Therapeutics Integration | Smartphone adherence monitoring paired with auto-injector devices creates differentiated value propositions for payers managing polypharmacy. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from payer access specialist surveys and CMS Medicare Part D utilization data. Bottom-up patient-volume modeling and top-down revenue triangulation anchored market size estimation.
Segmented outputs across therapeutic modality, disease severity staging, end-user channel, and administration route fed into analytical framework development over the projection horizon. CAGRs derived from treatment algorithm evolution assumptions and biosimilar penetration curves. Forecast inputs incorporated FDA boxed warning scope scenarios and EMA PRAC safety review timelines.
Revisions become necessary when FDA regulatory action on JAK inhibitor class labeling materializes or when plasma fractionation capacity constraints trigger supply allocation protocols. Forecasts reflect documented assumptions regarding prescriber behavior shifts and payer formulary redesign cycles. A small set of named triggers—EMA pharmacovigilance framework evolution, ANVISA procurement policy changes, and PMDA accelerated approval pathway expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral & Topical Anaesthetics Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Postmenopausal Vaginal Atrophy Drugs Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Asia-Pacific Contraceptives Market