
 Asia Pacific Cancer Immunotherapy Market | 2026-2036
Asia Pacific Cancer Immunotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cancer Immunotherapy Market Analysis
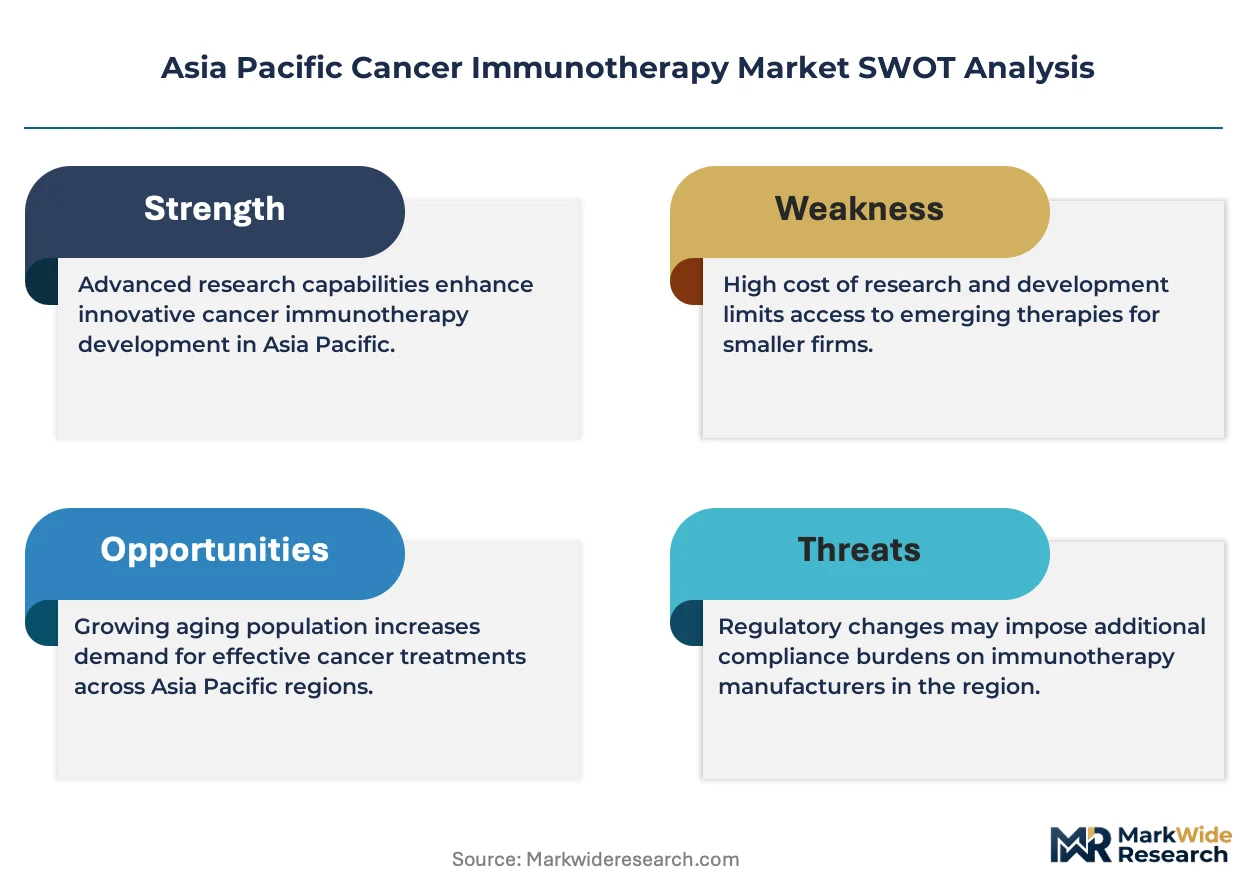
Aftermarket patient monitoring and companion diagnostic revenue is tilting toward biopharma firms with integrated care platforms. Bristol-Myers Squibb leverages its nivolumab franchise to sustain high-margin recurring diagnostics partnerships across Japanese treatment centers. BeiGene anchors its regional position through China-built manufacturing scale and local regulatory expertise. Jiangsu Hengrui Medicine competes aggressively on PD-1 pricing while extending its pipeline into novel bispecific formats.
Cancer immunotherapy comprises biologic agents that mobilize a patient's immune system to recognize and destroy malignant cells, primarily through monoclonal antibodies blocking immune checkpoints or engineering T-cell receptors against tumor antigens. These therapies require cold-chain distribution, sterile intravenous infusion protocols, and biomarker-driven patient stratification to achieve durable responses. Checkpoint inhibitors command the dominant margin pool across the Asia Pacific landscape, while cytokine-based regimens represent a smaller, slower-growing category constrained by toxicity management requirements. Hospitals absorb the majority of infused product volume, though homecare delivery models are gaining traction in Australia and select Japanese prefectures where subcutaneous formulations reduce infusion center burden.
Japan's PMDA operates sakigake designation pathways that compress oncology review timelines, while China's NMPA implements conditional approval frameworks for innovative biologics with China-specific trial data. Australia's TGA aligns its priority review with comparable FDA and EMA decisions, streamlining multinational sponsor access. India's CDSCO has tightened good manufacturing practice inspections for imported immunotherapy products, raising compliance costs for foreign suppliers. Stakeholders must monitor how each regulator's evolving real-world evidence requirements reshape post-market commitment burdens and geographic launch sequencing across the region.
Market Dynamics
Checkpoint inhibitor manufacturing concentration in Chinese CDMO clusters and Japanese biologics facilities is compressing supply timelines while amplifying cold-chain infrastructure demands across the region.
Growth Catalysts
- NMPA conditional approval frameworks:China's biologics reforms accelerate market entry timelines for innovative immunotherapies with China-specific trial data, reducing sponsor capital lock-up periods.
- Subcutaneous formulation adoption:Australian and Japanese prefectures are expanding homecare delivery models that reduce infusion center burden and extend therapy reach into regional patient populations.
- Biomarker-driven stratification:PD-L1 companion diagnostic penetration in China's tier-one oncology centers is improving patient selection precision and durable response rates.
Market Restraints
- Plasma-derived raw material volatility:Fetal bovine serum and recombinant protein input costs fluctuate with livestock supply cycles, squeezing cell therapy production margins.
- Single-source cold-chain dependency:Regional logistics networks concentrate in Shanghai, Tokyo, and Singapore hubs, creating vulnerability to port congestion or temperature excursion events.
- PMDA sakigake eligibility barriers:Japan's accelerated pathway excludes sponsors without prior Japanese clinical presence, filtering out early-stage innovators.
Strategic Opportunities
- India's CDSCO GMP compliance gap:Tightened inspection standards for imported immunotherapies create first-mover advantage for sponsors investing in local manufacturing infrastructure.
- Bispecific antibody pipelines:Novel T-cell engager formats targeting solid tumors represent whitespace beyond saturated PD-1/PD-L1 categories.
- Real-world evidence mandates:Post-market commitment requirements across PMDA and NMPA jurisdictions reward sponsors with integrated data capture platforms and registry partnerships.
Industry Challenges
- Cell therapy manufacturing workforce scarcity:GMP-grade aseptic processing and vector production skills concentrate in Boston and Basel, forcing Asia Pacific sponsors into expensive expatriate hiring or training program buildouts.
- Multi-regional trial coordination complexity:Divergent biomarker assay standards between China's NMPA and Japan's PMDA create protocol amendment burdens and timeline slippage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cancer Immunotherapy Market |
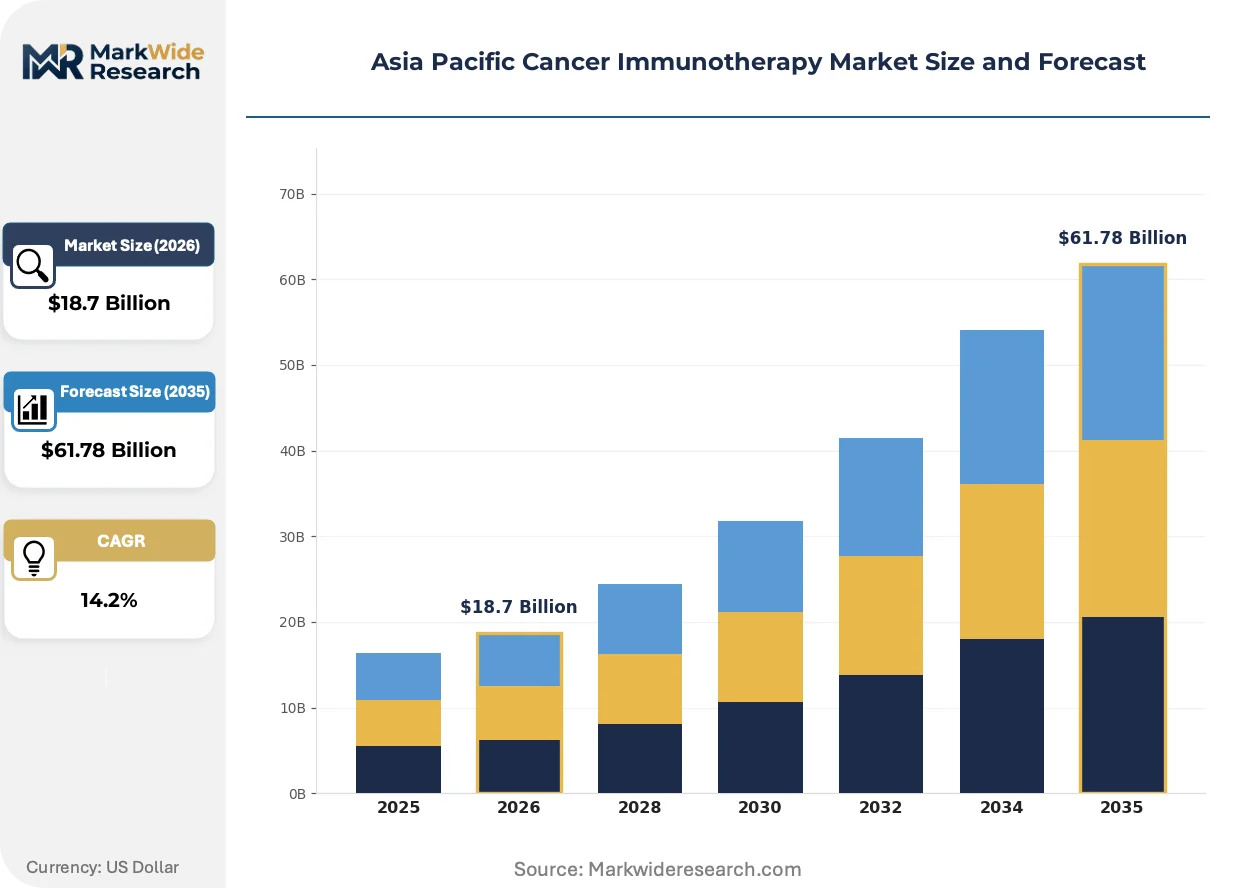
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Checkpoint Inhibitors, Cytokines, Vaccines End User: Hospitals, Research Institutions, Clinics, Homecare Application: Melanoma, Lung Cancer, Lymphoma, Breast Cancer Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | Bristol-Myers Squibb Co, Amgen Inc, AstraZeneca PLC, BeiGene, Eli Lilly and Co, Merck & Co Inc, Pfizer Inc, Jiangsu Hengrui Medicine, Roche Holding AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cancer Immunotherapy Market Emerging Trajectories
Digital infrastructure integration is compressing clinical trial timelines and enabling decentralized patient monitoring across the Asia Pacific immunotherapy landscape. Three developments merit particular attention.
Artificial intelligence-powered patient screening is digitizing biomarker analysis workflows and eligibility matching across Chinese oncology networks. Shanghai and Beijing treatment centers deploy machine learning algorithms to parse genomic sequencing outputs against trial protocols, reducing manual chart review cycles from weeks to days. This compression is digitizing site activation timelines and expanding addressable patient pools for novel mechanism sponsors.
Japan's PMDA sakigake designation pathway now incorporates rolling review mechanisms for companion diagnostic co-submissions, compressing the historical sequential approval sequence. Sponsors with integrated diagnostic strategies gain six-to-twelve month timeline advantages over therapy-only filers. Chinese biotechs with Japan-first regulatory strategies are restructuring development programs to capture this acceleration.
Hospital procurement committees across Australia's public health networks are unbundling immunotherapy purchasing from bundled oncology service contracts, creating direct manufacturer-accountability relationships. Queensland and New South Wales hospital systems now negotiate price-volume agreements separately from infusion service fees, shifting margin pressure onto product suppliers while insulating pharmacy operations. This bifurcation is most visible in checkpoint inhibitor categories where multiple therapeutic alternatives exist.
Asia Pacific Cancer Immunotherapy Market Segmentation
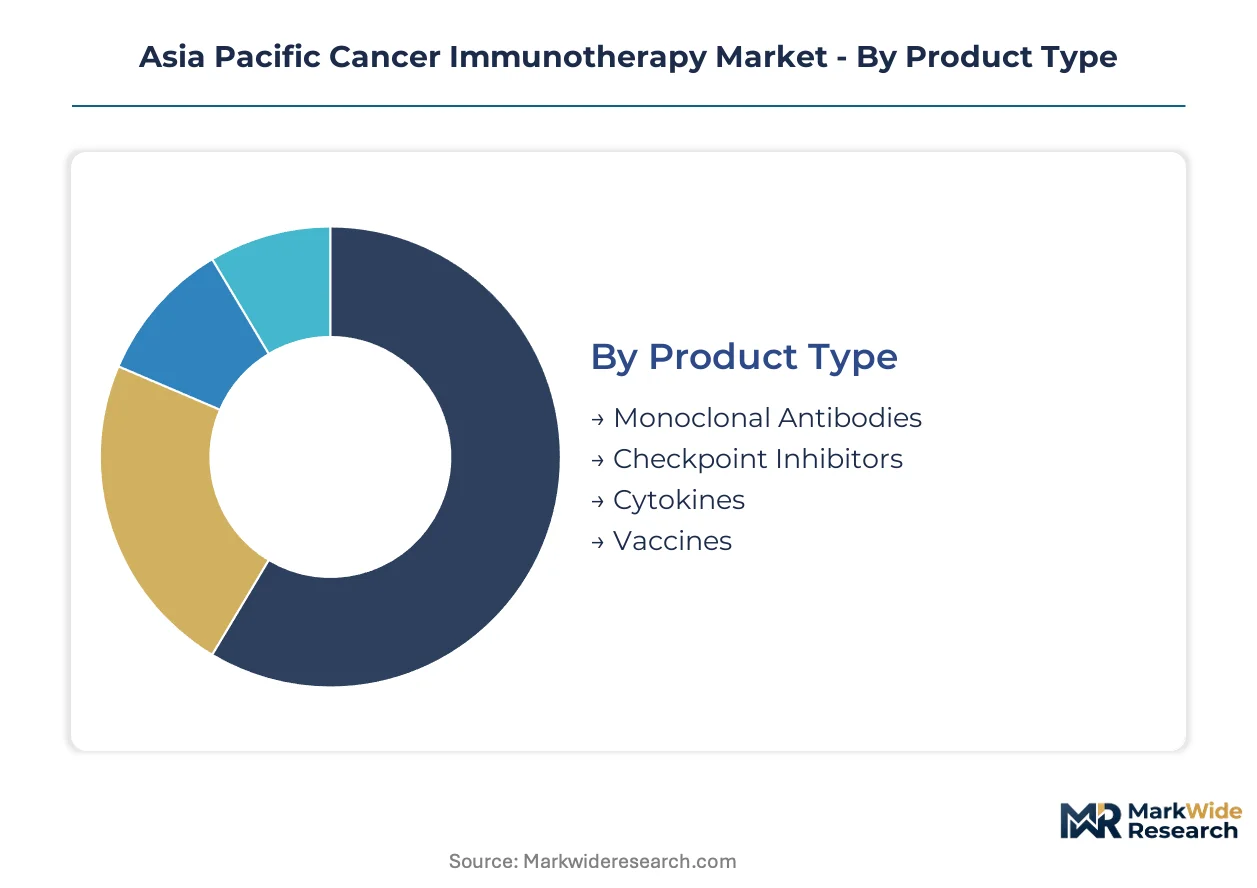
Cancer immunotherapy segmentation reveals how treatment modality, care setting, and disease indication shape procurement patterns across Asia Pacific markets. Each dimension carries distinct reimbursement, infrastructure, and patient access implications that sponsors must navigate.
Product Type:
Use-case spectrum spans curative intent checkpoint blockade to preventive vaccine administration across solid and hematologic malignancies.
- Checkpoint Inhibitors:PD-1 and PD-L1 blocking antibodies dominate infused therapy volume in China's tier-one oncology centers and Japan's university hospitals. PMDA sakigake pathways and NMPA conditional approvals compress development timelines for sponsors with biomarker-integrated strategies.
- Monoclonal Antibodies:Unconjugated and antibody-drug conjugate formats target HER2, CD20, and other tumor-associated antigens with established manufacturing scale. Australian public hospital procurement committees unbundle these from bundled oncology contracts, shifting price-volume negotiation leverage toward manufacturers.
- Cytokines:Interleukin and interferon-based regimens occupy a narrower therapeutic niche constrained by toxicity profiles and infusion monitoring requirements.
- Vaccines:Therapeutic cancer vaccines remain developmental with limited commercial penetration across the region.
Established volume favors checkpoint inhibitors; emerging adoption favors cytokine combinations in select Japanese academic protocols.
End User:
Care delivery infrastructure determines cold-chain investment, reimbursement pathway, and patient stratification capability.
- Hospitals:China's 150+ tier-one oncology centers and Japan's 80 national university hospitals absorb the majority of infused immunotherapy volume. These sites maintain GMP-grade aseptic processing partnerships and biomarker testing laboratories required for checkpoint inhibitor eligibility.
- Homecare:Australian and Japanese prefectural health systems expand subcutaneous administration models that reduce infusion center burden. Queensland's community nursing networks and Tokyo's home-visit nursing associations pilot these programs for stable maintenance-phase patients.
- Research Institutions:Phase I-II trial sites concentrate in Shanghai, Beijing, Osaka, and Melbourne with dedicated early-phase oncology units.
- Clinics:Private oncology day clinics in India and Southeast Asia handle limited immunotherapy volumes pending CDSCO GMP compliance upgrades for imported products.
Hospital concentration anchors current revenue; homecare infrastructure expansion gains share fastest in Australia and select Japanese markets.
Application:
Disease-specific indication drives biomarker testing penetration, regulatory priority review eligibility, and payer coverage determination.
- Lung Cancer:Non-small cell lung carcinoma represents the largest addressable patient pool with established PD-L1 companion diagnostic requirements. Chinese oncology networks deploy AI-powered screening to match EGFR/ALK-negative patients to immunotherapy trials.
- Melanoma:CTLA-4 and PD-1 combination therapy originated in this indication with durable long-term survival data. Australian melanoma incidence rates support specialized treatment center concentration in Sydney and Melbourne.
- Lymphoma:CD19-directed CAR-T and bispecific T-cell engager development concentrates in Japanese and Australian academic medical centers with cell therapy manufacturing partnerships.
- Breast Cancer:Checkpoint inhibitor approval remains restricted to triple-negative subtypes with limited Asia Pacific payer coverage outside Japan.
Lung cancer commands the largest patient volume; melanoma maintains the deepest biomarker integration and longest follow-up datasets.
Delivery Mode:
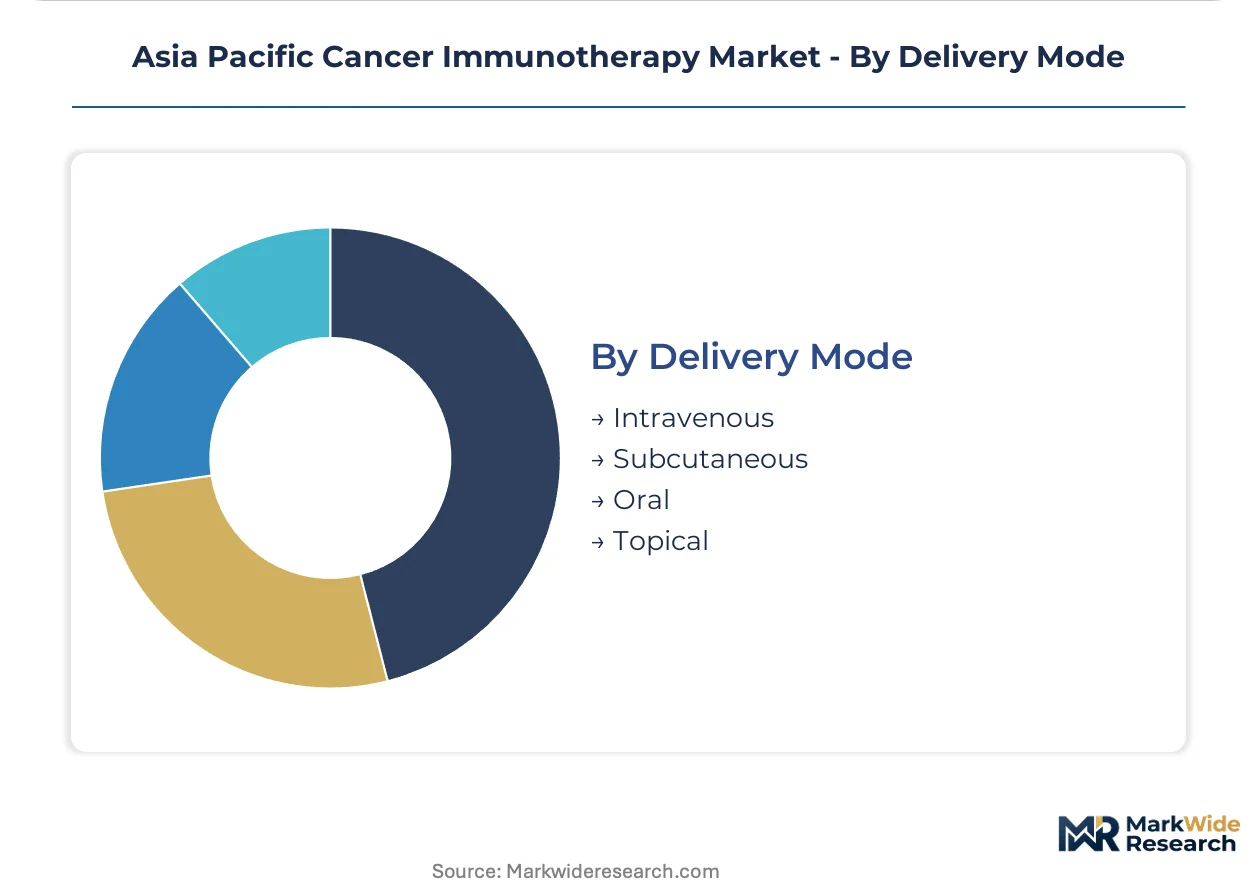
Route of administration shapes cold-chain complexity, nursing labor requirements, and geographic reach into regional patient populations.
- Intravenous:Infusion center-dependent delivery dominates checkpoint inhibitor administration with 30-90 minute dwell times. Shanghai, Tokyo, and Singapore cold-chain hubs concentrate distribution for temperature-sensitive biologics.
- Subcutaneous:Self-administration or community nursing models expand access beyond metropolitan oncology centers. Japanese prefectural health systems and Australian rural health networks pilot these programs to reduce travel burden.
- Oral:Small-molecule immunomodulators occupy limited market presence with distinct regulatory and manufacturing pathways.
- Topical:Localized delivery for cutaneous malignancies remains niche with minimal Asia Pacific commercial penetration.
Intravenous infusion retains infrastructure dominance; subcutaneous formats climb the fastest as homecare delivery models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Checkpoint inhibitor manufacturing clusters in Shanghai, Tokyo, and Singapore anchor regional supply capacity while compressing distribution timelines for temperature-sensitive biologics. Cold-chain infrastructure investments concentrate in these hubs, amplifying vulnerability to port congestion or temperature excursion events that ripple across national markets.
China
Tier-one oncology centers in Beijing and Shanghai absorb the majority of infused immunotherapy volume, with AI-powered patient screening digitizing biomarker analysis workflows. NMPA conditional approval frameworks accelerate market entry for innovative biologics with China-specific trial data. Yangtze River Delta CDMO clusters compress manufacturing timelines while amplifying plasma-derived raw material demand.
Japan
University hospitals in Tokyo and Osaka maintain dedicated early-phase oncology units with GMP-grade aseptic processing partnerships. PMDA sakigake designation pathways incorporate rolling review mechanisms for companion diagnostic co-submissions, compressing historical sequential approval sequences. Kanto region treatment centers deploy machine learning algorithms to parse genomic sequencing outputs against trial protocols.
Australia
Public health networks in Queensland and New South Wales unbundle immunotherapy purchasing from bundled oncology service contracts, creating direct manufacturer-accountability relationships. TGA priority review aligns with comparable FDA and EMA decisions, streamlining multinational sponsor access. Melbourne and Sydney melanoma treatment centers concentrate specialized care infrastructure with deep biomarker integration.
India
Private oncology day clinics in Mumbai and Delhi handle limited immunotherapy volumes pending CDSCO GMP compliance upgrades for imported products. Tightened inspection standards for foreign suppliers raise compliance costs while creating first-mover advantage for sponsors investing in local manufacturing infrastructure. Maharashtra and Gujarat pharmaceutical clusters attract contract manufacturing investments from regional sponsors.
South Korea
Seoul Capital Area academic medical centers partner with cell therapy manufacturing facilities for CD19-directed CAR-T development. MFDS accelerated approval pathways for innovative biologics compress development timelines for sponsors with biomarker-integrated strategies. Busan-Ulsan biologics facilities expand cold-chain distribution capacity across East Asian markets.
Asia Pacific Cancer Immunotherapy Market Vendor Landscape
Multinational biopharma conglomerates and China-built biotech platforms split the market across checkpoint inhibitor and cell therapy categories. The vendor base organizes around three strategic archetypes: Western innovators with established nivolumab and pembrolizumab franchises, Chinese biotechs leveraging local regulatory expertise and manufacturing scale, and diversified pharmaceutical groups extending oncology pipelines through licensing partnerships. Dominant competitive moves include subcutaneous formulation development to enable homecare delivery and integrated diagnostic strategies to capture PMDA sakigake timeline advantages.
Within the Western innovator tier, Bristol-Myers Squibb and Merck occupy positions anchored by PD-1 blocking antibody portfolios with deep reimbursement access across Japanese treatment centers. Among China-based biotech platforms, BeiGene exemplifies the archetype of sponsors combining local manufacturing scale with NMPA regulatory expertise to compress development timelines. Jiangsu Hengrui Medicine sits within the diversified pharmaceutical group category, competing on PD-1 pricing while extending pipeline development into novel bispecific formats.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Co |
| Amgen Inc |
| AstraZeneca PLC |
| BeiGene |
| Eli Lilly and Co |
| Merck & Co Inc |
| Pfizer Inc |
| Jiangsu Hengrui Medicine |
| Roche Holding AG |
| Others |
Supply Flow & Price Mechanics
Shanghai-Tokyo-Singapore cold-chain corridors concentrate freight costs for temperature-sensitive biologics, amplifying margin pressure on sponsors while enabling three-tier pricing stratification across premium checkpoint inhibitors, standard monoclonal antibodies, and economy-tier cytokine regimens.
Pricing Analysis
NMPA conditional approval frameworks dictate the pricing tier structure across China's tier-one oncology centers, separating premium PD-1 inhibitors with companion diagnostic integration from standard monoclonal antibodies and economy-tier cytokine combinations. Price differentiation rests on biomarker stratification capability and reimbursement access depth, with Japanese university hospitals showing lowest sensitivity due to PMDA sakigake-linked premium positioning. Pricing pressure stems from Jiangsu Hengrui Medicine's aggressive PD-1 pricing in domestic Chinese markets, compressing margins for imported alternatives.
Supply Chain Analysis
Fetal bovine serum and recombinant protein feedstocks anchor upstream cost volatility for cell therapy manufacturing across Chinese CDMO clusters and Japanese biologics facilities. Geographic supply concentration centers on Yangtze River Delta production hubs, Osaka-Kobe pharmaceutical corridors, and Singapore distribution nodes. Single-source cold-chain dependency creates vulnerability to port congestion at Shanghai and Tokyo gateways. Distribution runs through hospital-direct procurement channels with limited wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific cancer immunotherapy markets are recovering from cell therapy manufacturing workforce scarcity troughs, with CDMO capacity expansion and GMP-grade training program buildouts now accelerating sponsor pipeline progression.
For Market Incumbents: Insulate nivolumab and pembrolizumab franchise positions through backward integration into companion diagnostic manufacturing, capturing PMDA sakigake rolling review advantages while defending against BeiGene's local manufacturing scale threats. Prioritize subcutaneous formulation R&D to reduce infusion center dependency and extend therapy reach into Australian and Japanese prefectural homecare networks. For New Entrants and Emerging Players: Build out bispecific T-cell engager development programs targeting solid tumor indications beyond saturated PD-1/PD-L1 categories, exploiting whitespace in lung cancer and melanoma combination regimens. India's CDSCO GMP compliance gap offers the most penetrable geography for sponsors investing in Maharashtra and Gujarat manufacturing infrastructure, with direct hospital procurement relationships replacing distributor-dependent models. For Investors and Strategic Acquirers: Cell therapy manufacturing platforms with integrated vector production capabilities represent the priority acquisition archetype, given GMP-grade aseptic processing skill scarcity concentrated in Boston and Basel. Long-term viability hinges on sponsors' ability to capture real-world evidence mandates across PMDA and NMPA jurisdictions. Watch for NMPA biomarker assay standard harmonization with PMDA protocols as the signal indicating multi-regional trial coordination cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | PMDA sakigake rolling review mechanisms compress sequential approval timelines by six-to-twelve months for integrated sponsors. |
| Subcutaneous Formulation Development | Queensland and New South Wales homecare pilots reduce infusion center burden and extend geographic patient reach. |
| CDSCO GMP Local Manufacturing | Maharashtra and Gujarat facilities circumvent tightened inspection standards and import compliance cost escalation. |
| AI-Powered Patient Screening Integration | Shanghai and Beijing treatment centers digitize biomarker analysis workflows, compressing site activation timelines from weeks to days. |
| Bispecific Antibody Pipeline Expansion | Novel T-cell engager formats target solid tumor whitespace beyond commoditized PD-1/PD-L1 checkpoint blockade categories. |
Methodological Framework
Desk research of ClinicalTrials.gov entries, NMPA and PMDA regulatory filings, and hospital procurement databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers across Beijing, Shanghai, Tokyo, and Sydney. Secondary validation drew from EMA submission parallels, SEC 10-K oncology segment disclosures, and AI-powered screening platform vendor documentation. Bottom-up patient volume modeling and top-down revenue triangulation were cross-referenced for consistency.
Assumptions held fixed across the analysis window include NMPA conditional approval framework continuity, PMDA sakigake eligibility criteria stability, and Australian public hospital unbundled procurement persistence. Variables tested across sensitivity bands encompassed plasma-derived raw material cost cycles, CDSCO GMP inspection enforcement intensity, and subcutaneous formulation adoption curves. Segmentation dimensions modeled spanned treatment modality, care setting, disease indication, and regional regulatory cluster. CAGRs were derived from patient volume buildups applied to pricing tier assumptions, with checkpoint inhibitor biomarker penetration and cell therapy manufacturing capacity expansion as primary forecast inputs.
Stress conditions across raw material volatility, cold-chain disruption frequency, and regulatory approval timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers including NMPA-PMDA biomarker assay harmonization, CDSCO manufacturing license granting acceleration, or subcutaneous formulation regulatory pathway expansion. Cross-checking against IQVIA oncology sales audit data and hospital procurement system records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Particle Therapy Market
Oncology
Europe Radiotherapy Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Laser Cancer Therapy Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Pharyngeal Neoplasm Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Colorectal Cancer Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Solid Tumor Market
Oncology
Metastatic Cancer Drug Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Cancer Cachexia Market
Oncology
Cancer Supportive Care Products Market