
 Dermatological Drugs Market | 2026-2036
Dermatological Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatological Drugs Market Intelligence
Fixed-dose combination bundles of topical corticosteroids with calcineurin inhibitors is restructuring how dermatology clinics select first-line therapies for atopic dermatitis. AbbVie Inc. leverages its immunology platform to sustain dominance in systemic psoriasis treatments. GSK plc. anchors its position through R&D intensity in rosacea combination therapies. Sun Pharmaceutical Industries Ltd. competes on manufacturing scale across emerging markets.
Dermatological drugs encompass pharmacologically active formulations designed for cutaneous administration or systemic modulation of skin pathologies, typically requiring specific molecular weights below 500 Da for effective transdermal penetration and stability profiles compatible with keratinocyte interaction. Their primary commercial purpose centers on interrupting inflammatory cytokine cascades, modulating keratinocyte proliferation, or restoring barrier function in conditions such as psoriasis and atopic dermatitis. Biologics command the deepest margin pools among product type categories due to manufacturing complexity and patent-protected monoclonal antibody platforms. Topical delivery mode retains the largest volume footprint across therapy areas, though injectable biologics generate disproportionate value concentration in psoriasis management.
FDA oversight of dermatological biologics through the Center for Drug Evaluation and Research shapes clinical trial design and post-market surveillance requirements for new molecular entities. EMA's MDR-aligned scrutiny of combination-device topical systems limits market access for novel transdermal platforms lacking established equivalence data. Stakeholders must monitor evolving biosimilar interchangeability designations and their cascading effects on formulary positioning and reimbursement negotiations.
Market Dynamics
Hospital procurement of biologic therapies for psoriasis is accelerating across the United States, compressing formulary decision cycles and forcing manufacturers to demonstrate real-world efficacy data earlier in the commercialization timeline. This demand concentration is reshaping competitive entry patterns and reimbursement negotiations simultaneously.
Growth Catalysts
- Biologics Streamlining:The FDA's streamlined biosimilar approval pathway is reducing time-to-market for monoclonal antibody alternatives, expanding patient access to systemic psoriasis treatments through accelerated regulatory review.
- Calcineurin Combination Therapies:Fixed-dose topical corticosteroid-calcineurin inhibitor bundles are displacing monotherapy protocols in atopic dermatitis first-line protocols across dermatology clinic networks.
- German Clinic Network Expansion:Demand concentration within Germany's integrated dermatology clinic system is creating procurement volume pools that attract biologic manufacturers seeking stable reimbursement environments.
Market Restraints
- Cold Chain Complexity:Injectable biologics require continuous 2-8°C temperature maintenance from manufacturing through administration, elevating logistics costs and limiting distribution reach to tertiary care centers.
- EMA MDR Scrutiny:The European Medicines Agency's Medical Device Regulation-aligned equivalence requirements for combination-device topical systems are blocking novel transdermal platforms lacking established clinical comparator data.
- Monoclonal Antibody Substitution:Biosimilar pressure on reference biologics is compressing margin pools for originator manufacturers while payer formularies increasingly mandate step-therapy protocols.
Strategic Opportunities
- Transdermal Penetration Enhancers:Novel molecular weight optimization technologies below 500 Da are enabling systemic drug delivery through topical routes, bypassing injection requirements for moderate psoriasis patients.
- Rosacea Combination Pipelines:R&D intensity in multi-mechanism rosacea therapies targeting both erythema and papulopustular lesions is opening differentiated positioning in an underserved indication.
- IRA Price Negotiation Windows:The Inflation Reduction Act's Medicare price negotiation provisions are creating strategic entry points for biosimilar manufacturers targeting post-exclusivity biologics.
Industry Challenges
- Keratinocyte Interaction Modeling:Predictive in-vitro testing for topical drug stability profiles remains underdeveloped, extending preclinical timelines and elevating failure rates in Phase I dermatology trials.
- Post-Market Surveillance Integration:FDA-mandated long-term safety databases for biologics require specialized pharmacovigilance infrastructure that mid-cap manufacturers struggle to operationalize cost-effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatological Drugs Market |
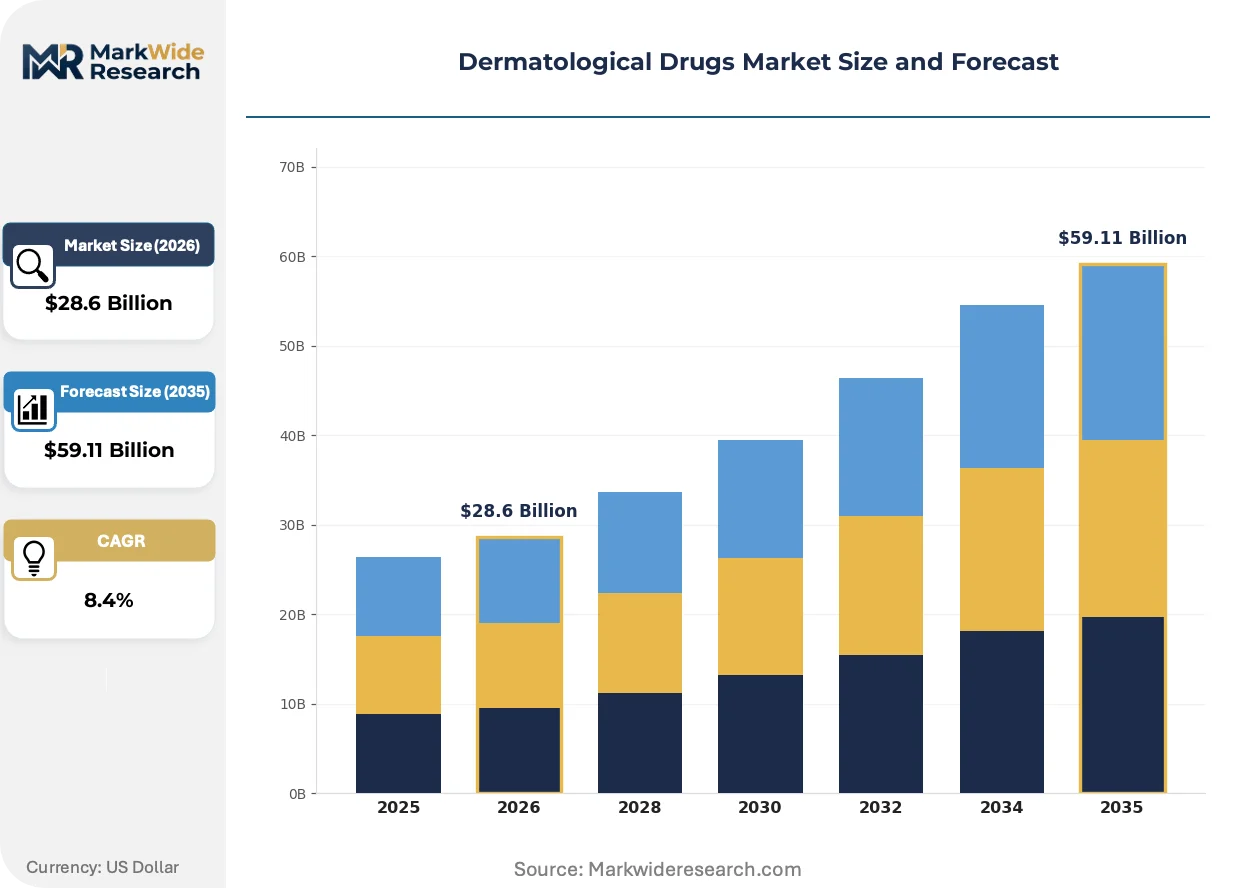
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Systemic Agents, Biologics, OTC Medications Therapy Area: Psoriasis, Atopic Dermatitis, Acne Vulgaris, Rosacea Delivery Mode: Topical, Injectable, Oral, Transdermal End User: Hospitals, Dermatology Clinics, Homecare, Pharmacies |
| Companies Covered | AbbVie Inc., Pfizer Inc., GSK plc., Sun Pharmaceutical Industries Ltd., GALDERMA, Novartis AG, Johnson & Johnson Services, Inc., Eli Lilly and Company, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatological Drugs Market Strategic Shifts & Innovations
Transdermal delivery science and biosimilar manufacturing sophistication are converging to fragment traditional therapy hierarchies. These forces are compressing development timelines while expanding the addressable patient population beyond injection-capable cohorts.
Micro-needle array patches for biologic administration are integrating into outpatient dermatology protocols, enabling self-administration of previously infusion-dependent therapies. Community-based dermatology clinics in the United States are piloting these platforms to reduce hospital dependency. The technology is integrating patient convenience demands with payor cost-containment objectives, creating hybrid care models that split therapy initiation from maintenance dosing.
REACH-registered excipient alternatives are displacing traditional penetration enhancers in European topical formulations, driven by ECHA substance restriction proposals targeting skin-sensitizing compounds. Manufacturers reformulating for compliance are discovering unexpected stability improvements in calcineurin inhibitor emulsions. German and French dermatology clinics are prioritizing these reformulated products in procurement tenders, creating preference premiums for early REACH adaptors.
Specialty pharmacy distribution is consolidating patient access channels for high-cost biologics, displacing traditional wholesale relationships in psoriasis therapy fulfillment. United States payers are mandating specialty pharmacy lock-in for biologic coverage, concentrating dispensing volume with accredited providers. This channel compression is most visible in Medicare Part D plans, where prior authorization requirements now route virtually all systemic dermatology biologics through limited distribution networks.
Dermatological Drugs Market Segmentation
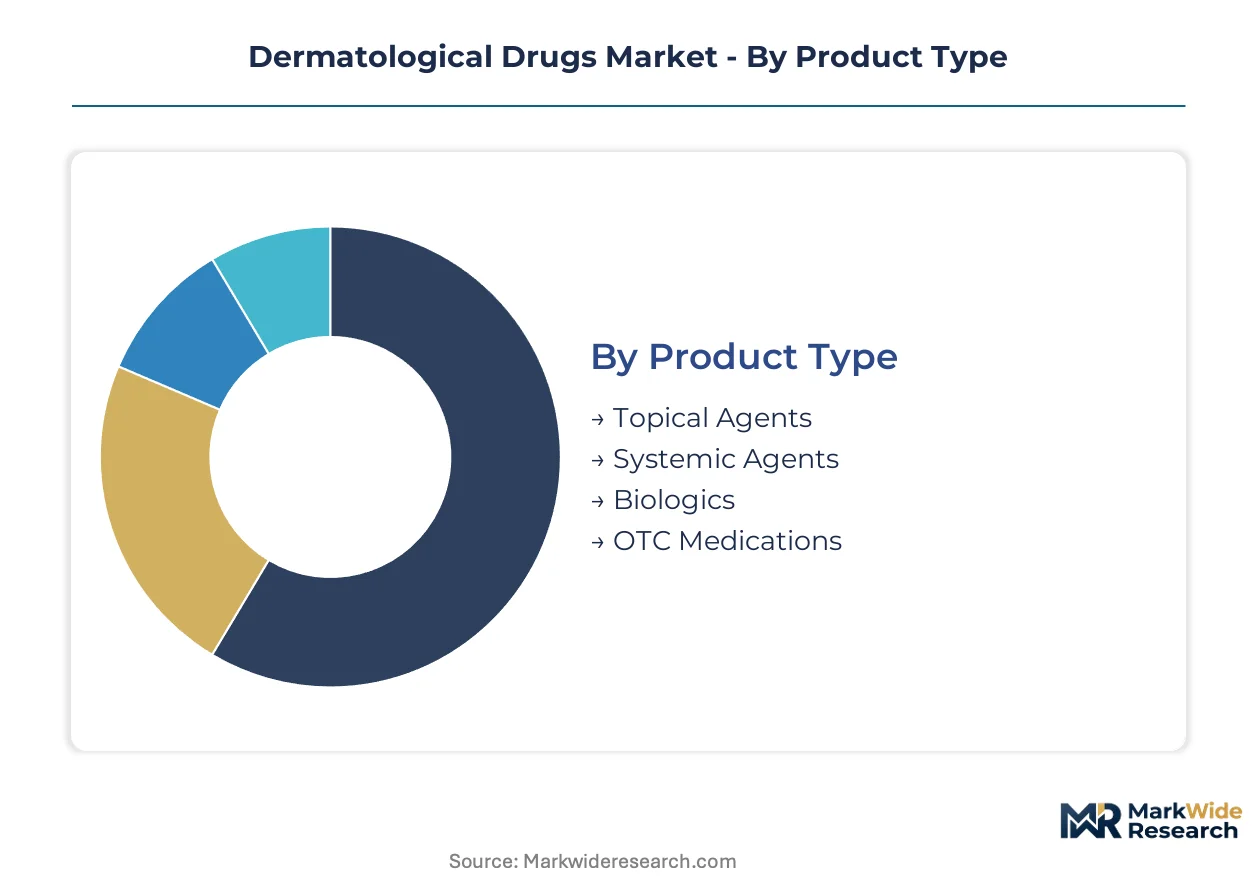
Dermatological drug procurement patterns diverge sharply across patient severity, reimbursement pathways, and administration setting. Understanding these segment boundaries clarifies where manufacturers must build distinct commercial capabilities versus shared infrastructure.
Product Type:
Buyers in this category separate by treatment complexity tolerance and payer authorization requirements.
- Biologics:Monoclonal antibody formulations manufactured through mammalian cell culture demand cold chain integrity and specialized infusion infrastructure. Hospital formularies in the United States concentrate procurement volume here, driven by step-therapy mandates that reserve these agents for moderate-to-severe psoriasis patients who fail conventional systemic therapy.
- Topical Agents:Corticosteroid and calcineurin inhibitor creams, ointments, and lotions formulated for direct cutaneous application dominate prescription volume. Dermatology clinics in Germany prioritize fixed-dose combination bundles of these agents, compressing procurement decisions around efficacy-to-safety ratios in atopic dermatitis management.
- Systemic Agents:Oral immunomodulators and retinoids bridge topical and biologic therapy tiers.
- OTC Medications:Consumer-directed acne and anti-fungal preparations compete through retail pharmacy shelf positioning.
Topical agents lead volumes today; biologics is gaining share fastest through hospital formulary expansion.
Therapy Area:
Segment boundaries here reflect disease prevalence heterogeneity and unmet need intensity across patient populations.
- Psoriasis:Chronic autoimmune condition characterized by keratinocyte hyperproliferation and systemic inflammation. Injectable biologic penetration is deepest here, with United States hospital systems accelerating procurement of IL-17 and IL-23 inhibitors as first-line systemic options.
- Atopic Dermatitis:Barrier dysfunction-driven inflammatory skin disease with high pediatric incidence. Topical calcineurin inhibitor demand concentrates in European dermatology clinic networks, where EMA guidelines emphasize steroid-sparing protocols for long-term maintenance.
- Acne Vulgaris:Androgen-driven sebaceous gland disorder addressed through retinoid and antimicrobial combinations.
- Rosacea:Neurovascular and inflammatory facial condition with limited approved systemic options.
Psoriasis commands the steepest expansion trajectory; atopic dermatitis maintains the broadest addressable patient base.
Delivery Mode:
Route selection determines manufacturing complexity, stability requirements, and patient adherence economics.
- Injectable:Subcutaneous and intravenous biologic administration requiring refrigeration and clinical oversight. United States specialty pharmacy networks now mandate this channel for psoriasis biologics, consolidating dispensing volume with temperature-accredited providers.
- Topical:Direct cutaneous application of semi-solid formulations. REACH-registered excipient alternatives are displacing traditional penetration enhancers in German and French clinic procurement tenders.
- Oral:Systemic small-molecule delivery through gastrointestinal absorption.
- Transdermal:Patch-based drug delivery bypassing hepatic first-pass metabolism.
Topical delivery dominates prescription counts; injectable routes generate disproportionate value concentration.
End User:
Site-of-care selection shapes reimbursement mechanics, patient monitoring intensity, and manufacturer account management investment.
- Dermatology Clinics:Outpatient specialty practices managing chronic disease maintenance. Germany's integrated clinic network creates procurement volume pools that attract biologic manufacturers seeking stable reimbursement environments.
- Hospitals:Acute care institutions handling severe disease initiation and infusion-dependent therapies. United States hospital procurement of biologic therapies is compressing formulary decision cycles and forcing earlier real-world efficacy demonstration.
- Homecare:Self-administration settings for maintenance dosing of subcutaneous therapies.
- Pharmacies:Retail and specialty dispensing channels for outpatient prescription fulfillment.
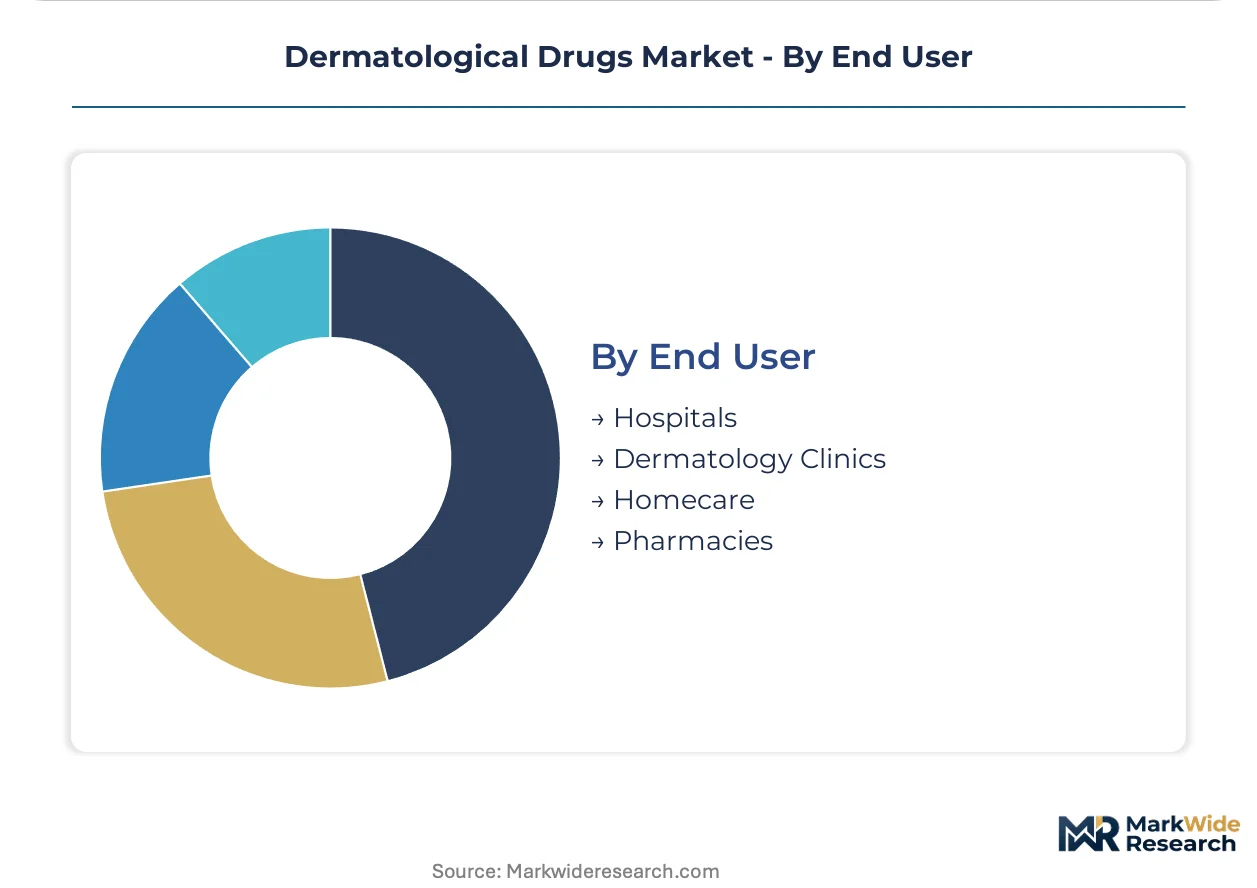
Dermatology clinics anchor volume today; hospital systems are capturing share fastest through biologic initiation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatological drug development traces its commercial origins to mid-20th century European pharmaceutical chemistry, with Basel and Frankfurt emerging as early centers of topical formulation science before biologic manufacturing shifted investment patterns toward North American and Asian biotechnology clusters.
United States
Hospital procurement of IL-17 and IL-23 inhibitors is compressing formulary decision cycles, forcing earlier real-world efficacy demonstrations. The FDA's streamlined biosimilar approval pathway under the BPCIA framework is accelerating monoclonal antibody market entry. Specialty pharmacy networks in Boston and San Francisco are consolidating dispensing volume for temperature-accredited biologic distribution.
Germany
Integrated dermatology clinic networks are creating procurement volume pools that attract biologic manufacturers seeking stable reimbursement environments. EMA MDR-aligned scrutiny of combination-device topical systems is blocking novel transdermal platforms lacking established equivalence data. The Rhine-Main cluster around Frankfurt anchors reformulation activity for REACH-registered excipient alternatives in calcineurin inhibitor emulsions.
Japan
PMDA oversight of biologics post-market surveillance is elevating pharmacovigilance infrastructure requirements for systemic dermatology therapies. METI-supported initiatives for transdermal penetration enhancement are advancing molecular weight optimization below 500 Da. The Kansai region's Osaka-based formulation specialists are piloting micro-needle array patches for outpatient biologic administration.
India
CDSCO accelerated approval pathways for biosimilars are expanding domestic manufacturing scale for reference biologic alternatives. The PLI scheme for pharmaceuticals is incentivizing capacity expansion in active pharmaceutical ingredient production for topical corticosteroids. Gujarat's Ahmedabad-Surat corridor hosts contract manufacturing organizations serving European dermatology clinic procurement tenders.
Switzerland
Swissmedic's alignment with EMA centralized procedures is facilitating parallel market access for biologic therapies across European dermatology networks. Basel's historical concentration of immunology research platforms continues to anchor monoclonal antibody development for psoriasis indications. The country's precision manufacturing infrastructure supports cold chain integrity requirements for injectable biologics destined for German and French hospital systems.
Dermatological Drugs Market Key Industry Players
Premium-margin players sit above commodity-margin players across manufacturing complexity and patent protection dimensions. The market structures around three tiers: originator biologics commanding deep margin pools through monoclonal antibody platforms, biosimilar manufacturers compressing reference product pricing through accelerated regulatory pathways, and topical formulation specialists competing on excipient innovation and REACH compliance. Consolidation pressures favor M&A activity targeting immunology platform assets, while portfolio diversification into rosacea combination therapies represents a secondary competitive vector.
Within the originator biologics tier, AbbVie Inc. and Eli Lilly and Company exemplify platform-leveraged positioning through immunology infrastructure. Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis AG occupy positions spanning both biologic and small-molecule dermatology assets. Sun Pharmaceutical Industries Ltd. represents the emerging-market scale archetype, competing through manufacturing cost structures and contract supply relationships with European procurement networks.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| GSK plc. |
| Sun Pharmaceutical Industries Ltd. |
| GALDERMA |
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| Eli Lilly and Company |
| Amgen Inc. |
| Others |
Cost & Logistics Intelligence
API commodity indices for corticosteroid precursors and monoclonal antibody cell culture media cascade through three distinct pricing tiers, compressing margins for standard topical generics while insulating premium biologics from cost pass-through pressures in United States hospital procurement.
Pricing Analysis
Three-tier pricing structure across premium biologics, standard topical brands, and economy generics dominates the market. Price differentiation hinges on FDA biosimilar interchangeability designation and cold chain certification tier. Cost compression in the economy tier is intensifying because CDSCO-approved Indian manufacturers are flooding European tender markets. Dermatology clinics in Germany exhibit lowest price sensitivity due to stable reimbursement pools, while United States specialty pharmacy networks drive hardest bargain on post-IRA biologics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese heparin-derived excipient suppliers and Swiss precision fermentation capacity for monoclonal antibody production. Manufacturing gravity centers on India for topical API synthesis, Switzerland for biologic drug substance, and Germany for finished dose formulation. Raw material dependencies span recombinant cell lines, REACH-registered penetration enhancers, and borosilicate glass vials. Tariff exposure on Chinese-sourced excipients is elevating reformulation costs. Distribution runs through specialty pharmacy networks for temperature-controlled biologics and wholesale for standard topicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital formulary directors are prioritizing real-world efficacy databases over legacy clinical trial metrics, compressing competitive advantage into demonstrable outcomes infrastructure.
For Market Incumbents: Hedge biosimilar margin erosion by backward integration into cell culture media production and captive fill-finish capacity in the Rhine-Main corridor. Lock in German dermatology clinic networks through outcomes-based contracting that preempts step-therapy mandates. Defensive patent thickets around IL-23 inhibitor dosing regimens offer temporary shelter from monoclonal antibody substitution.
For New Entrants and Emerging Players: Enter via rosacea combination therapy white space where GSK plc. anchors but pipeline gaps persist for erythema-papulopustular dual-mechanism approaches. Target United States community dermatology clinics piloting micro-needle array patches for biologic self-administration. Lead with patient convenience data that splits therapy initiation from maintenance dosing.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap topical formulation specialists possessing REACH-registered excipient portfolios and established European procurement relationships. Five-to-ten year viability favors assets with immunology platform optionality beyond dermatology. Watch FDA biosimilar interchangeability designation velocity as inflection signal for originator margin compression timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA streamlined biosimilar designation accelerates IL-17 inhibitor market entry timelines. |
| Manufacturing Scale-Up | CDSCO accelerated approvals enable Indian CMOs to capture European tender volumes. |
| Pipeline Diversification | Rosacea combination R&D opens positioning in underserved neurovascular-inflammatory indication. |
| Long-term Supply Agreement | REACH-registered excipient contracts secure preference in German clinic procurement. |
| Strategic Partnership | Specialty pharmacy lock-ins consolidate United States biologic dispensing channel control. |
Research Approach
Bottom-up dermatology clinic procurement modeling reconciled against top-down biologic manufacturing capacity tracking forms the analytical core of this study. Primary interviews with hospital formulary directors, regulatory affairs leads at monoclonal antibody developers, payer access specialists, and German clinic network procurement managers combined with secondary validation against FDA 351(k) biosimilar filings, EMA centralized procedure outcomes, ClinicalTrials.gov dermatology trial registries, and United States specialty pharmacy dispensing databases. Triangulation across stakeholder perspectives and documentary sources resolves data conflicts through documented assumption hierarchies.
Historical trendline analysis of biologic price erosion curves and topical generic tender patterns anchored forward projections across the analysis window. Segmentation dimensions modeled include product type tier, therapy area severity stratification, delivery mode infrastructure requirements, and regional regulatory cluster. CAGRs derived from slope-consistency testing against comparable immunology market maturation curves. Forecast inputs incorporated FDA biosimilar approval velocity assumptions and EMA MDR equivalence requirement evolution.
Inputs from hospital procurement databases and specialty pharmacy dispensing records were available through the study window; gaps in real-world efficacy outcome standardization introduce uncertainty bands around formulary adoption timelines. Forecasts reflect documented assumptions regarding biosimilar interchangeability designation rates and REACH substance restriction implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Global Pericarditis Drugs Market