
 Automated Visual Field Analyzer Market | 2026-2036
Automated Visual Field Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Visual Field Analyzer Market Intelligence
LED illumination modules are restructuring cost profiles across automated visual field analyzer production, displacing legacy tungsten-halogen light sources that carried higher replacement burdens and calibration drift. Carl Zeiss Meditec leverages in-house optical component manufacturing to sustain margin control across its perimetry portfolio. Haag-Streit Group anchors its competitive stance through Swiss precision engineering heritage in ophthalmic diagnostics. Topcon Corporation extends its presence across Asia-Pacific through integrated distribution networks spanning optometry and ophthalmology channels.
An automated visual field analyzer is a diagnostic instrument that maps a patient's visual sensitivity across defined retinal locations using standardized light stimulus presentation and threshold detection algorithms, typically operating at luminance ranges from 0.08 to 10,000 apostilbs with automated eye tracking to ensure fixation compliance. The device generates quantitative field indices including mean deviation and pattern standard deviation to support objective progression monitoring in glaucoma and neuro-ophthalmic conditions. Static perimetry occupies the dominant revenue position due to its established reimbursement coding and universal protocol compatibility across clinical trials, while frequency doubling technology penetrates screening workflows where throughput speed commands priority over spatial resolution granularity. Optical coherence tomography integration represents the fastest-expanding technology segment as manufacturers bundle structural and functional metrics into unified diagnostic platforms.
FDA Class II device regulations govern 510(k) clearance requirements for automated visual field analyzers marketed in the United States, with predicate device comparisons shaping development roadmaps and commercialization timelines. The EU Medical Device Regulation imposes enhanced clinical evidence standards and notified body oversight for perimetry systems sold in European member states, directly influencing R&D resource allocation and post-market surveillance obligations. Stakeholders must monitor convergence between standalone perimetry hardware and multimodal diagnostic platforms as reimbursement frameworks evolve to reward integrated disease management pathways over discrete test reimbursement.
Market Dynamics
LED illumination modules are restructuring cost profiles across automated visual field analyzer production, displacing legacy tungsten-halogen light sources that carried higher replacement burdens and calibration drift.
Growth Catalysts
- EU Medical Device Regulation:Enhanced clinical evidence standards for perimetry systems sold in European member states are accelerating R&D investment in integrated diagnostic platforms that bundle structural and functional metrics.
- Ophthalmology clinics:Expansion of automated perimetry adoption for glaucoma management in the United States is driving demand for devices with automated eye tracking and standardized threshold detection protocols.
- Germany manufacturing cluster:Concentration of specialized production around Heidelberg and Wetzlar anchors supply capacity for precision optical components serving global diagnostic instrument demand.
Market Restraints
- Optical component supply concentration:Dependence on German and Swiss precision engineering clusters creates vulnerability to regional production disruptions and extended lead times for critical illumination modules.
- 510(k) predicate device requirements:FDA clearance pathways for Class II diagnostic devices impose lengthy commercialization timelines as manufacturers must demonstrate substantial equivalence to existing perimetry systems.
- Frequency doubling technology limitations:Screening-focused devices sacrifice spatial resolution granularity, restricting their utility in neuro-ophthalmic applications requiring detailed field mapping.
Strategic Opportunities
- Optical coherence tomography convergence:Integration of OCT with perimetry hardware creates unified diagnostic platforms that align with evolving reimbursement frameworks rewarding integrated disease management.
- Asia-Pacific distribution networks:Integrated optometry and ophthalmology channels spanning Japan, South Korea, and Australia present underpenetrated pathways for automated perimetry system deployment.
- Static perimetry protocol standardization:Universal compatibility with clinical trial endpoints positions established test algorithms for expansion into pharmaceutical development partnerships.
Industry Challenges
- Multimodal platform integration complexity:Bundling structural and functional diagnostic metrics requires harmonization of data formats and workflow interfaces across legacy hospital information systems.
- Post-market surveillance obligations:EU MDR mandates for enhanced clinical evidence and notified body oversight demand sustained regulatory affairs staffing and documentation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Visual Field Analyzer Market |
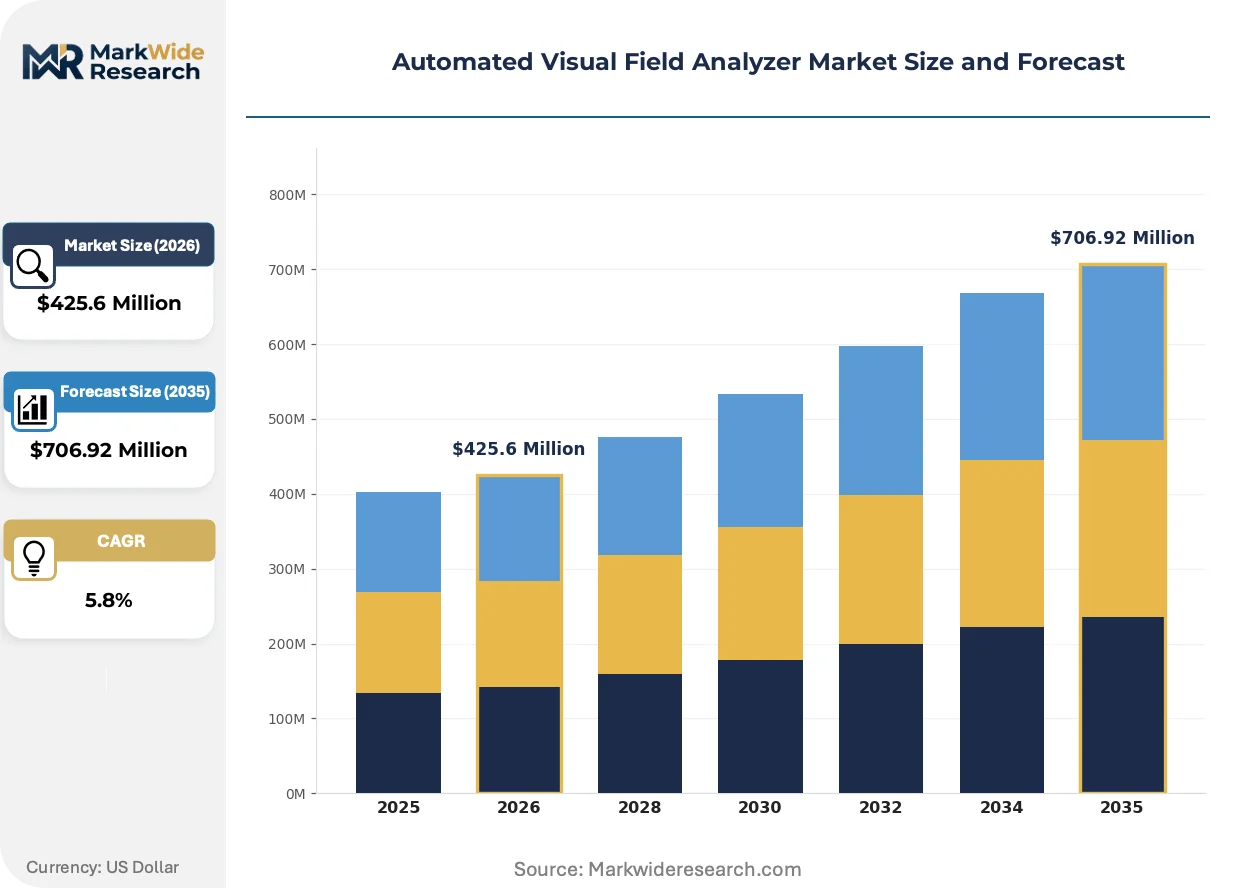
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $706.92 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Perimetry, Kinetic Perimetry, Frequency Doubling Technology, 3D Perimetry End User: Ophthalmology Clinics, Hospitals, Research Institutions, Eye Care Centers Technology: Laser-Based, Digital Imaging, Optical Coherence Tomography, Automated Software Application: Glaucoma Diagnosis, Retinal Disorders, Neurological Disorders, Screening |
| Companies Covered | Carl Zeiss Meditec, Haag-Streit Group, Topcon Corporation, Heidelberg Engineering, OCULUS Optikgeräte, NIDEK Co., Ltd., Kowa Company Ltd., Optopol, Metrovision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Visual Field Analyzer Market Strategic Shifts & Innovations
Diagnostic instrument architectures are converging around unified platforms that merge functional and structural assessment capabilities, compressing the traditional separation between standalone perimetry and imaging modalities.
Optical coherence tomography is integrating into automated visual field analyzer architectures as manufacturers bundle retinal nerve fiber layer measurements with sensitivity threshold mapping. Ophthalmology clinics in Germany and the United States are adopting these converged systems to streamline glaucoma progression monitoring workflows. This technology compression is enabling single-visit diagnostic protocols that reduce patient chair time while maintaining clinical trial-grade data integrity.
EU Medical Device Regulation enforcement is tightening clinical evidence requirements for perimetry systems marketed in European member states, extending development timelines and elevating post-market surveillance obligations. Manufacturers must now submit comprehensive technical documentation and performance validation studies to notified bodies before CE marking approval. Small and mid-sized diagnostic firms face disproportionate compliance burdens, driving consolidation pressure across the European supply base.
Reimbursement frameworks are pivoting toward integrated disease management pathways that reward comprehensive diagnostic episodes over discrete test billing. Hospital purchasing committees in the United States are prioritizing perimetry platforms capable of generating both functional indices and structural correlates within unified reports. This behavioral shift favors vendors with software ecosystems that aggregate multi-modal data into actionable clinical decision support.
Automated Visual Field Analyzer Market Segmentation
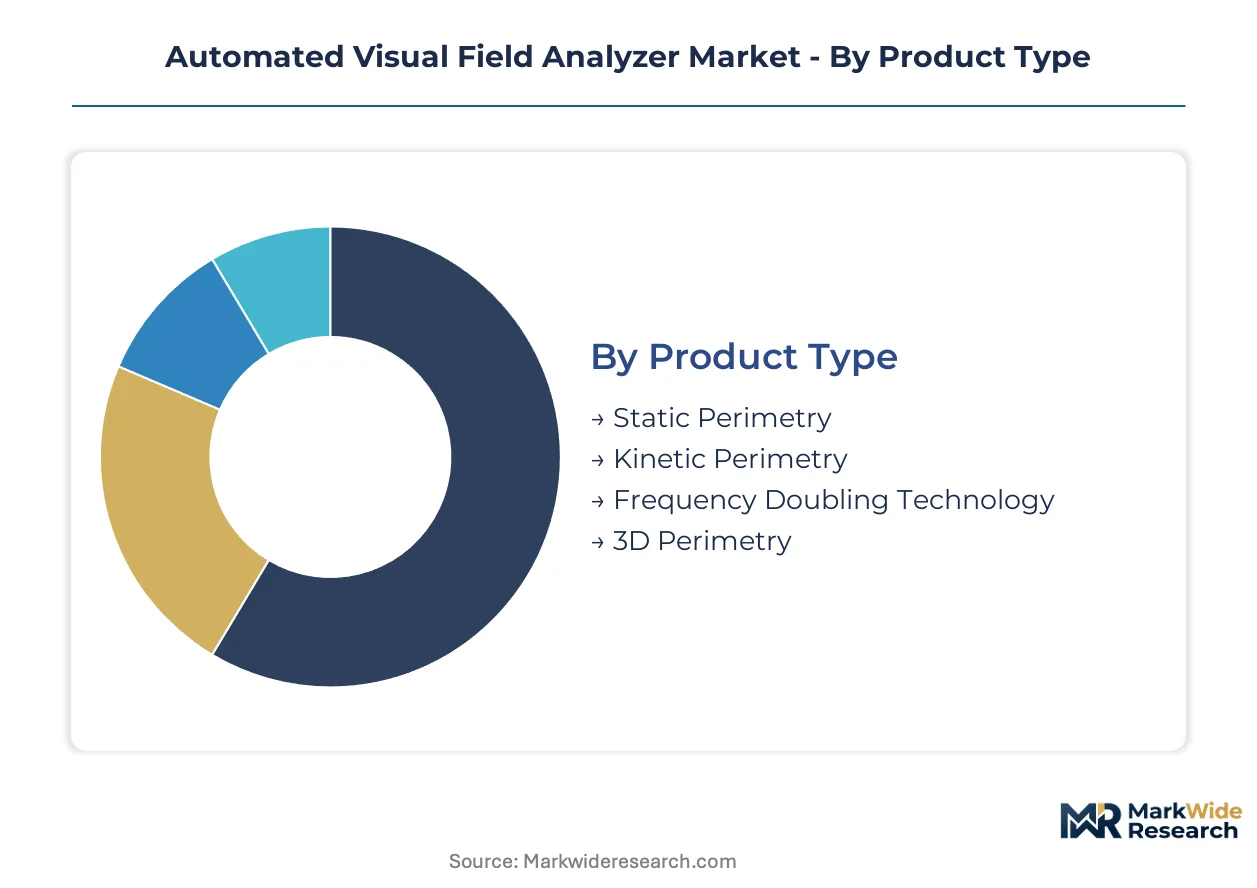
Automated visual field analyzer segmentation reveals how regulatory pathways, reimbursement structures, and clinical workflows fragment demand across distinct hardware configurations and service settings. Each category carries specific certification burdens that shape vendor investment priorities and customer procurement timelines.
Product Type:
FDA 510(k) clearance requirements apply uniformly across all product types, though predicate device availability varies—static perimetry leverages the deepest pool of approved predicates, while 3D perimetry faces scarcer equivalence pathways and extended review cycles.
- Static Perimetry:Maps visual sensitivity at fixed retinal locations using standardized threshold algorithms operating across 0.08 to 10,000 apostilb luminance ranges. Demand concentrates in United States ophthalmology clinics where established CPT reimbursement codes and clinical trial protocol compatibility sustain procurement volume. FDA predicate device abundance accelerates commercialization timelines for new entrants.
- Frequency Doubling Technology:Employs counterphase flicker stimuli to isolate magnocellular pathway function for rapid screening workflows. German eye care centers deploy these systems for high-throughput glaucoma detection programs where speed commands priority over spatial resolution granularity. EU MDR clinical evidence requirements impose heavier documentation burdens than FDA pathways for this segment.
- Kinetic Perimetry:Tracks moving stimulus detection across the visual field using dynamic boundary mapping protocols.
- 3D Perimetry:Generates depth-resolved sensitivity maps through advanced stimulus presentation geometries requiring specialized optical calibration.
Static perimetry sits at the top of the volume ranking, with frequency doubling technology climbing the fastest.
End User:
Purchasing authority and reimbursement access create sharp tiering across end-user categories, with hospitals commanding capital equipment budgets and eye care centers operating on tighter per-procedure economics.
- Ophthalmology Clinics:Drive replacement demand for legacy tungsten-halogen systems with LED-equipped platforms that reduce calibration drift and maintenance intervals. United States private practice networks prioritize devices with automated eye tracking and EMR integration to streamline Medicare documentation requirements. Procurement committees evaluate total cost of ownership over 7-10 year equipment lifecycles.
- Hospitals:Require multimodal diagnostic platforms that bundle perimetry with OCT and fundus imaging within unified workstation footprints. German university hospitals anchor demand for research-grade systems supporting pharmaceutical trial endpoints. Integrated device contracts favor vendors with established service infrastructure across multiple hospital sites.
- Research Institutions:Specify customized stimulus protocols and raw data export capabilities for academic study designs.
- Eye Care Centers:Focus on screening-optimized configurations with simplified operator interfaces and minimal training requirements.
Ophthalmology clinics maintain the largest installed base, though hospitals are expanding share fastest through centralized diagnostic service consolidation.
Technology:
Component sourcing strategies diverge sharply across technology categories, with laser-based systems dependent on specialized German optical suppliers and digital imaging platforms leveraging broader semiconductor supply chains.
- Optical Coherence Tomography:Converges structural retinal nerve fiber layer measurements with functional sensitivity mapping within single-visit diagnostic protocols. United States hospital purchasing committees prioritize these unified platforms as reimbursement frameworks shift toward bundled disease management episodes. EU MDR notified body oversight extends development timelines for OCT-integrated systems versus standalone perimetry hardware.
- Automated Software:Governs threshold detection algorithms, fixation monitoring, and progression analysis reporting across all hardware configurations. German manufacturers anchor competitive positioning through proprietary algorithm validation against clinical trial datasets. Software-as-medical-device classification under FDA and EU MDR imposes distinct quality management system requirements from hardware components.
- Laser-Based:Utilizes coherent light sources for precise stimulus presentation with minimal spectral variation.
- Digital Imaging:Captures and archives field maps through standardized image formats for longitudinal comparison.
Automated software underpins every installed system, while OCT integration is gaining share fastest through platform convergence strategies.
Application:
Clinical evidence requirements and reimbursement coding density vary dramatically by application, with glaucoma diagnosis commanding the most mature regulatory and payment infrastructure.
- Glaucoma Diagnosis:Represents the foundational use case for automated perimetry, with mean deviation and pattern standard deviation indices serving as progression monitoring standards. United States Medicare reimbursement sustains procedure volume across ophthalmology clinics and hospital outpatient departments. FDA 510(k) submissions for glaucoma-focused devices access the richest predicate literature, compressing clearance timelines.
- Neurological Disorders:Requires high-resolution field mapping to detect chiasmal and post-chiasmal pathway lesions with precise hemifield correlation. German neuro-ophthalmology centers specify kinetic and static combined protocols for pituitary adenoma and stroke evaluation. Reimbursement coding fragmentation across neurology and ophthalmology specialties creates billing complexity that constrains volume expansion.
- Retinal Disorders:Localizes functional deficits corresponding to structural macular and peripheral pathology.
- Screening:Emphasizes throughput velocity and operator independence for population-scale detection programs.
Glaucoma diagnosis commands the dominant procedure volume, with neurological disorders applications expanding most quickly through subspecialty referral network development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German precision optics cluster around Heidelberg and Wetzlar anchors global manufacturing capacity for automated visual field analyzers, with specialized suppliers feeding assembly operations across three continents. United States ophthalmology networks drive replacement demand for LED-equipped platforms. Japanese and South Korean distributors expand integrated diagnostic channels throughout Asia-Pacific.
United States
Medicare reimbursement codes sustain procedure volume across private practice networks and hospital outpatient departments. FDA 510(k) clearance pathways for Class II diagnostic devices compress commercialization timelines through predicate device abundance. The Greater Boston corridor hosts research-grade system deployments supporting pharmaceutical trial endpoints.
Germany
EU Medical Device Regulation enforcement tightens clinical evidence requirements for perimetry systems marketed throughout European member states. Notified body oversight extends development timelines and elevates post-market surveillance obligations. The Heidelberg-Wetzlar manufacturing corridor concentrates precision optical component production serving global diagnostic instrument demand.
Japan
PMDA regulatory frameworks govern medical device approval timelines for perimetry systems distributed across domestic ophthalmology channels. METI industrial policy supports precision manufacturing capabilities in optical instrumentation. The Kanto region around Tokyo anchors distribution networks spanning optometry and hospital procurement committees.
South Korea
MFDS medical device regulations shape certification requirements for automated perimetry systems entering domestic eye care markets. National health insurance reimbursement structures influence purchasing decisions across ophthalmology clinic networks. The Seoul Capital Area concentrates demand for screening-optimized configurations in high-throughput diagnostic settings.
Australia
TGA medical device regulations establish conformity assessment pathways for perimetry systems imported from German and Japanese manufacturers. Medicare Benefits Schedule item numbers sustain procedure reimbursement across ophthalmology practices. The Sydney-Melbourne corridor drives adoption of multimodal diagnostic platforms bundling structural and functional assessment capabilities.
Automated Visual Field Analyzer Market Key Industry Players
Global majors compete with regional champions across regulatory certification and distribution infrastructure, creating a tiered structure where scale-driven vendors face specialized precision engineering houses. The vendor base clusters around German-Swiss optical heritage and Japanese integrated electronics capabilities. Two strategic archetypes dominate: diversified diagnostic conglomerates with multimodal platform portfolios, and focused perimetry specialists leveraging proprietary algorithm validation. M&A activity targets software-as-medical-device capabilities, while capacity expansion concentrates in German precision manufacturing clusters.
Among diversified diagnostic conglomerates, Carl Zeiss Meditec and Topcon Corporation occupy positions exemplifying scale-driven platform strategies, while Heidelberg Engineering represents the focused precision engineering archetype. These three entities anchor competitive dynamics across reimbursement-heavy markets in the United States and Germany, with each sitting within distinct strategic postures regarding vertical integration into optical component supply and software ecosystem development.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| Haag-Streit Group |
| Topcon Corporation |
| Heidelberg Engineering |
| OCULUS Optikgeräte |
| NIDEK Co., Ltd. |
| Kowa Company Ltd. |
| Optopol |
| Metrovision |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in German precision optics anchor supply discipline through captive manufacturing of LED illumination modules and proprietary calibration protocols, enabling pricing power that resists commoditization pressure from Asian electronics assemblers. This ownership structure sustains long-term supplier relationships and shields margin structures from quarterly earnings volatility that pressures publicly traded competitors.
Pricing Analysis
Input-cost pass-through from LED module sourcing and precision optical component fabrication determines pricing trajectories across automated visual field analyzer tiers. Three-tier pricing structure across premium, standard, and economy levels separates research-grade systems with OCT integration from screening-focused frequency doubling devices and entry-level static perimeters. Pricing pressure stems from hospital procurement consolidation demanding bundled diagnostic platforms over standalone perimeters. Eye care centers exhibit highest price sensitivity due to per-procedure reimbursement economics, while German university hospitals absorb premium positioning for trial-grade equipment.
Supply Chain Analysis
Warehouse-distribution layers concentrate around regional hubs in Germany, Japan, and the United States serving ophthalmology clinic networks with calibrated equipment requiring specialized handling. Component sourcing draws from German precision engineering clusters for optical modules, Japanese semiconductor suppliers for imaging sensors, and Taiwanese electronics manufacturers for LED drivers. Single-source vulnerability concentrates in Heidelberg-Wetzlar precision optics capacity serving multiple competing diagnostic brands. Distribution runs through direct sales forces for hospital accounts and specialized medical device distributors for private practice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated visual field analyzer market operates as a regulatory compounder where EU Medical Device Regulation enforcement and FDA 510(k) pathway complexity continuously elevate barriers against unvalidated entrants, consolidating demand around certified incumbents.
For Market Incumbents: Deepen backward integration into LED illumination module production to capture cost compression from tungsten-halogen displacement while securing supply continuity against German optics cluster bottlenecks. Anchor defensive positioning through software-as-medical-device certification investments that extend ecosystem lock-in beyond hardware replacement cycles.
For New Entrants and Emerging Players: Begin with screening-optimized frequency doubling configurations targeting South Korean and Australian eye care centers where national health insurance structures favor throughput economics over spatial resolution granularity. Pursue regulatory arbitrage through TGA or MFDS certification pathways that compress timelines relative to FDA or EU MDR routes.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized algorithm specialists lacking integrated hardware platforms but holding validated progression analysis software. Long-term viability favors targets with proprietary clinical trial datasets that defend against platform convergence. Watch reimbursement framework shifts toward bundled disease management episodes as the decisive inflection signal for multimodal diagnostic consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device abundance compresses clearance timelines for static perimetry entrants against scarce 3D perimetry pathways. |
| CE Marking Pathway | EU MDR notified body oversight extends development timelines but creates defensive moats against uncertified competitors. |
| Hospital System Partnership | Integrated device contracts with German university hospitals anchor research-grade demand and pharmaceutical trial access. |
| Software Companion Development | EMR integration and automated eye tracking algorithms streamline Medicare documentation for United States ophthalmology clinics. |
| Reimbursement Strategy | CPT code maintenance and bundled episode alignment determine procurement priority across hospital purchasing committees. |
Research Approach
Multiple input streams — executive interviews with diagnostic device manufacturers, hospital purchasing committee discussions, and regulatory affairs documentation — were reconciled against secondary validation from FDA 510(k) databases, EU MDR notified body filings, and hospital procurement contract records. Primary fieldwork encompassed ophthalmology clinic administrators, biomedical engineers, GPO contracts managers, and precision optics suppliers. Bottom-up equipment shipment analysis and top-down reimbursement procedure volume estimates were triangulated to anchor market sizing.
Data-stream reconciliation across product type, technology integration level, end-user setting, and regional regulatory cluster informed the analytical framework throughout the projection horizon. CAGRs were derived from installed base replacement cycles and procedure volume elasticity to reimbursement rate changes. Forecast inputs incorporated LED cost curves, EU MDR compliance cost escalation, and OCT convergence adoption patterns across hospital consolidation trends.
Several conditions sit outside the modeled scope, including patent litigation outcomes affecting frequency doubling technology access and sovereign tariff actions disrupting German-Japanese component trade flows. Forecasts reflect documented assumptions regarding regulatory timeline stability and reimbursement code maintenance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
Europe Point of Care Diagnostics Market