
 Diuretic Drugs Market | 2026-2036
Diuretic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Diuretic Drugs Market Analysis
Hospital procurement of diuretic therapies is consolidating as integrated delivery networks centralize formularies under value-based contracts. Pfizer Inc. leverages its manufacturing scale to supply bulk loop diuretic contracts to national hospital chains. Novartis AG anchors its position through specialized heart failure portfolios that bundle diuretics with complementary cardiovascular agents. Sanofi S.A. competes across European and Latin American markets with a diversified thiazide and potassium-sparing product range.
Diuretic drugs are pharmaceutical agents that increase renal excretion of sodium and water, typically achieving natriuresis through inhibition of ion transporters in specific nephron segments such as the thick ascending limb or distal convoluted tubule. These compounds serve primary clinical purposes in managing hypertension, reducing fluid overload in heart failure, and correcting edema states across inpatient and ambulatory settings. Loop diuretics dominate acute care settings where rapid volume removal is essential, while thiazide derivatives sustain the largest chronic therapy volume for essential hypertension. Oral delivery mode captures the majority of prescriptions, though intravenous formulations command premium positioning in hospitalized decompensated heart failure.
The FDA governs bioequivalence standards for generic diuretic substitutions, directly influencing payer preference and pharmacy-level dispensing patterns. The EMA's centralized marketing authorization process shapes competitive entry timelines for novel potassium-sparing agents across EU member states. India's CDSCO and PLI scheme for active pharmaceutical ingredients are expanding domestic manufacturing capacity for diuretic raw materials. Stakeholders must monitor how tightening pharmacovigilance requirements for electrolyte disturbance warnings will reshape labeling obligations and prescribing behavior across major markets.
Market Dynamics
Hospital procurement consolidation is compressing diuretic supplier margins as integrated delivery networks centralize formularies under value-based reimbursement contracts, forcing manufacturers to compete on total cardiovascular bundle economics rather than standalone drug pricing.
Growth Catalysts
- CMS bundled payment models:Medicare reimbursement incentives for heart failure readmission reduction are expanding inpatient diuretic protocol standardization across US health systems.
- Ambulatory surgical centers:Same-day discharge protocols for edema management are creating new outpatient infusion demand for intravenous loop diuretics.
- Continuous renal replacement therapy:ICU adoption of CRRT machines is integrating automated ultrafiltration with pharmacologic diuresis in critical care workflows.
Market Restraints
- Active pharmaceutical ingredient concentration:China dominates furosemide and hydrochlorothiazide raw material production, exposing formulators to geopolitical supply disruption.
- Electrolyte monitoring costs:Mandatory serum potassium and sodium surveillance protocols add nursing labor burden that offsets generic drug savings.
- Fixed-dose combination substitution:Single-pill antihypertensive combinations containing thiazides are displacing standalone diuretic prescriptions in primary care.
Strategic Opportunities
- Rural health clinic expansion:Federally qualified health centers in underserved US counties lack cardiology specialist access, creating telemedicine-integrated diuretic titration service demand.
- EMA pediatric investigation plans:Regulatory incentives for neonatal diuretic formulations are opening development pathways for adjusted-dose oral solutions.
- Remote patient monitoring:Bluetooth-enabled home weight scales and implantable pulmonary artery pressure sensors are enabling algorithm-guided diuretic dosing outside hospital walls.
Industry Challenges
- Pharmacovigilance signal management:FDA requirements for real-world electrolyte disturbance surveillance demand investment in post-market data infrastructure that mid-tier generic manufacturers struggle to fund.
- Legacy EHR integration:Hospital diuretic order sets require custom programming within Cerner and Epic platforms, creating implementation friction that delays protocol adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diuretic Drugs Market |
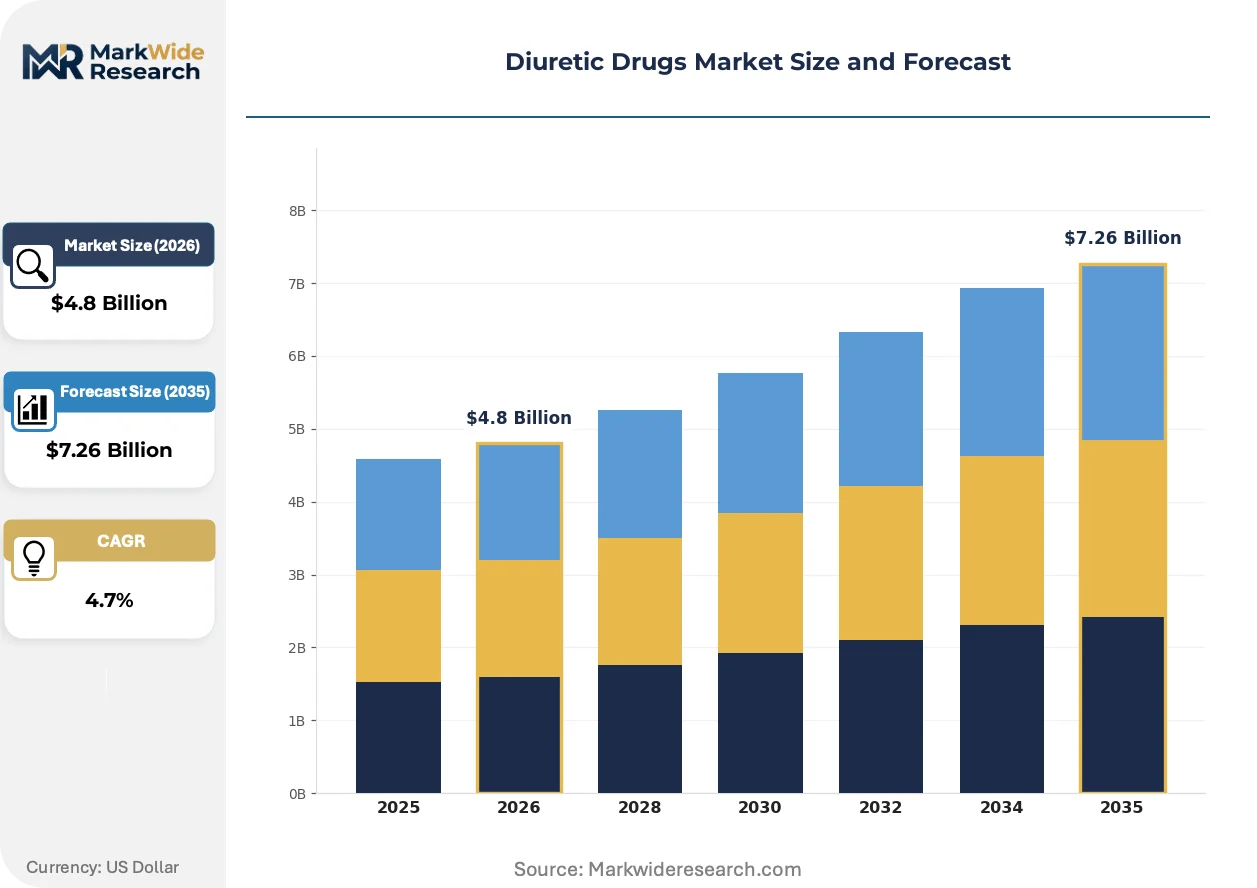
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thiazide, Loop, Potassium-Sparing, Osmotic End User: Clinics, Hospitals, Home Care, Ambulatory Surgery Centers Therapy Area: Hypertension, Heart Failure, Edema, Kidney Disorders Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., GlaxoSmithKline plc, Sanofi S.A., AstraZeneca plc, Teva Pharmaceutical Industries Ltd., Novartis AG, Sun Pharmaceutical Industries Ltd., Aurobindo Pharma Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diuretic Drugs Market Emerging Trajectories
Digital biomarker integration is transforming how clinicians titrate diuretic therapy, with implantable sensors and wearable devices enabling precision fluid management that reduces emergency department utilization.
Implantable pulmonary artery pressure monitors are electrifying heart failure care by transmitting daily hemodynamic data that triggers automated diuretic adjustment protocols. Cardiology practices in the United States are adopting these devices at accelerating rates for high-risk ejection fraction patients. The technology is electrifying traditional volume assessment methods, compressing reliance on physical examination and patient-reported symptoms.
The FDA's ongoing bioequivalence guidance revisions for narrow therapeutic index diuretics are tightening dissolution profile requirements for generic furosemide tablets. This regulatory friction is extending ANDA review timelines and elevating development costs for prospective market entrants. Generic manufacturers with pre-2018 approved products face retrospective compliance pressure that favors incumbents with established quality systems.
Integrated delivery networks are consolidating specialty pharmacy dispensing for chronic heart failure patients, displacing traditional retail channel volume. Hospital-owned pharmacies are capturing 90-day supply fulfillment through discharge prescription capture programs. This channel shift concentrates most visibly in Medicare Advantage populations across southeastern and midwestern US states where vertical health system integration is deepest.
Diuretic Drugs Market Segmentation
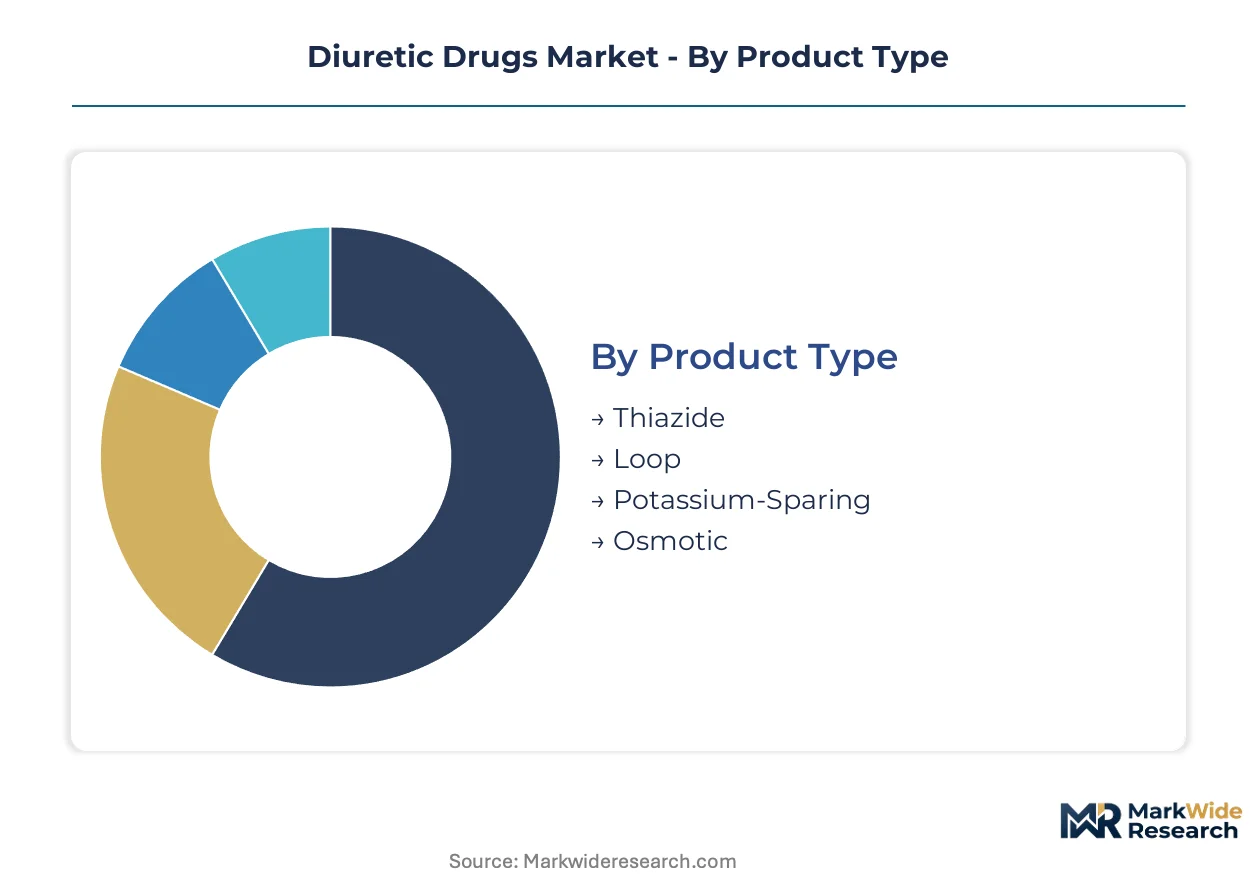
Diuretic drug segmentation reveals how clinical setting, pharmacology, and delivery complexity fragment purchasing authority across healthcare systems. Manufacturers must align formulation portfolios with distinct reimbursement pathways and prescriber workflows.
Product Type:
Volume concentrates in legacy oral agents, while premium positioning attaches to specialized formulations with electrolyte-sparing profiles.
- Thiazide:Hydrochlorothiazide and chlorthalidone dominate ambulatory hypertension management through once-daily oral dosing. Medicare Part D formularies in the United States drive substantial prescription volume toward these first-line agents.
- Loop:Furosemide and torsemide achieve rapid volume removal through thick ascending limb inhibition. Hospital procurement contracts for injectable loop diuretics command pricing premiums in acute decompensated heart failure protocols.
- Potassium-Sparing:Spironolactone and eplerenone minimize hypokalemia risk in resistant hypertension regimens.
- Osmotic:Mannitol reduces intracranial pressure in neurocritical care and ophthalmic surgical preparation.
Mature deployment sits with Thiazide agents in primary care. Newer deployment is concentrated in Potassium-Sparing combinations for heart failure with reduced ejection fraction.
End User:
Procurement authority shifts from centralized hospital pharmacy committees toward distributed outpatient settings as value-based contracts expand.
- Clinics:Federally qualified health centers and cardiology practices titrate oral diuretics for chronic hypertension. Remote patient monitoring integration is reshaping refill authorization workflows in rural United States counties.
- Hospitals:Integrated delivery networks consolidate formulary decisions under cardiovascular bundle contracts. Epic and Cerner order set standardization is compressing supplier choice in decompensated heart failure pathways.
- Home Care:Infusion nursing services administer intravenous loop diuretics for post-acute volume management.
- Ambulatory Surgery Centers:Same-day discharge protocols generate demand for perioperative edema control.
Volume leadership belongs to Hospitals. Steepest expansion trajectory is occurring in Home Care as telehealth-integrated diuretic titration programs proliferate.
Therapy Area:
Reimbursement intensity varies sharply across indications, with heart failure commanding bundled payment premiums that hypertension lacks.
- Hypertension:Thiazide monotherapy and combination products sustain the largest prescription base. Fixed-dose antihypertensive combinations containing thiazides are displacing standalone prescriptions in United States primary care.
- Heart Failure:Loop diuretics anchor acute decompensation protocols while mineralocorticoid receptor antagonists reduce mortality in chronic management. CMS readmission penalties are standardizing inpatient diuretic escalation order sets.
- Edema:Cirrhosis, nephrotic syndrome, and venous insufficiency generate specialized dosing requirements.
- Kidney Disorders:Dosing adjustments for glomerular filtration rate complicate nephrology prescribing.
Established utilization patterns center on Hypertension. Emerging utilization is concentrating in Heart Failure as implantable hemodynamic monitoring enables precision diuresis.
Delivery Mode:
Route selection tracks acuity, with oral formulations capturing chronic therapy and parenteral routes reserved for acute intervention.
- Oral:Tablets and solutions dominate chronic hypertension and stable heart failure maintenance. Bioequivalence requirements under FDA guidance shape generic substitution patterns at pharmacy benefit managers.
- Injectable:Intramuscular and subcutaneous formulations serve patients with unreliable gastrointestinal absorption. Ambulatory infusion centers are expanding subcutaneous furosemide programs for post-acute heart failure.
- Intravenous:Rapid onset volume removal in ICU and emergency department settings commands premium pricing.
- Subcutaneous:Emerging delivery technology enables outpatient loop diuretic administration without vascular access.
Oral delivery maintains volume dominance. Subcutaneous innovation is gaining share fastest as home infusion capabilities expand beyond traditional intravenous models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems drive the largest diuretic procurement volume globally, with Medicare reimbursement policies shaping prescription patterns toward oral formulations for chronic hypertension management.
United States
Hospital procurement consolidation under value-based contracts compresses supplier margins as integrated delivery networks centralize cardiovascular bundle economics. FDA bioequivalence requirements for generic loop diuretics extend ANDA review timelines and elevate compliance costs for prospective entrants. The Southeast and Midwest regions exhibit deepest vertical health system integration, concentrating Medicare Advantage prescription capture through hospital-owned specialty pharmacies.
Germany
Ambulatory care physicians prescribe thiazide combinations at substantial volume within the statutory health insurance framework. EMA centralized marketing authorization shapes competitive entry timelines for novel potassium-sparing agents across EU member states. The Rhine-Ruhr metropolitan cluster anchors pharmaceutical distribution infrastructure serving Central European hospital networks.
India
Domestic manufacturing capacity for diuretic active pharmaceutical ingredients expands under CDSCO oversight and the PLI scheme for API production. CDSCO pharmacovigilance requirements for electrolyte disturbance warnings reshape labeling obligations for both export and domestic formulations. Gujarat and Maharashtra states concentrate contract manufacturing operations supplying generic furosemide to regulated markets.
Japan
Aging demographics sustain chronic heart failure therapy demand requiring precision diuretic titration protocols. PMDA marketing authorization processes govern entry for mineralocorticoid receptor antagonists in resistant hypertension regimens. The Kanto region surrounding Tokyo concentrates cardiology specialist practices adopting implantable hemodynamic monitoring for outpatient volume management.
Brazil
Public health system procurement through ANVISA-regulated tenders drives volume toward affordable thiazide and loop diuretic formulations. ANVISA bioequivalence requirements for generic substitutions influence pharmacy-level dispensing patterns in the unified health system. São Paulo state anchors pharmaceutical manufacturing and distribution infrastructure serving Latin American export markets.
Diuretic Drugs Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized formulations and digital therapeutics integration. The competitive structure consolidates around multinational pharmaceutical conglomerates with cardiovascular portfolios, mid-tier generic manufacturers with API backward integration, and regional formulators serving tender-driven public health systems. Three archetypes dominate: scale-driven bulk suppliers, heart failure portfolio bundlers, and electrolyte-sparing specialists. Capacity expansion and strategic portfolio diversification represent the primary competitive vectors as manufacturers respond to hospital procurement centralization.
Within the scale-driven tier, Pfizer Inc. and Novartis AG exemplify contrasting strategic positions. Pfizer leverages manufacturing infrastructure to anchor bulk supply contracts with national hospital chains. Novartis occupies the portfolio-bundling archetype through integrated heart failure offerings. Sun Pharmaceutical Industries Ltd. represents the emerging market specialist archetype with API-to-formulation integration serving cost-sensitive procurement channels.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| AstraZeneca plc |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| Aurobindo Pharma Limited |
| Others |
Supply Flow & Price Mechanics
Backward integration into active pharmaceutical ingredient production anchors competitive positioning for generic diuretic manufacturers, compressing margins for formulators lacking captive furosemide or hydrochlorothiazide supply. This structural choice determines pricing power across hospital procurement contracts and retail pharmacy channels.
Pricing Analysis
Volume-margin splits concentrate prescription volume in oral thiazide generics where price erosion runs through tender-driven public health systems, while intravenous loop diuretics retain premium positioning through acute care bundle economics. Three-tier pricing structure across premium, standard, and economy levels reflects bioequivalence certification tiers under FDA guidance, with Medicare Advantage plans showing highest price sensitivity and hospital-owned specialty pharmacies least. Cost compression in oral generics intensifies because of China's API export pricing and Indian contract manufacturing competition.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of furosemide and hydrochlorothiazide intermediates, exposing global formulators to geopolitical disruption. Raw material dependencies rest on acetazolamide precursors, sulfonamide intermediates, and potassium chloride for electrolyte-sparing combinations. Regulatory restriction risk centers on FDA bioequivalence enforcement tightening dissolution profile requirements. Distribution runs through integrated delivery network central pharmacies consolidating cardiovascular bundle procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation is forcing a consolidation play as value-based contracts compress supplier margins and eliminate mid-tier generic manufacturers lacking scale or API control.
For Market Incumbents: Anchor manufacturing scale through backward integration into furosemide API production, securing supply positions against Chinese import volatility. Deepen hospital system partnerships by embedding diuretic protocols within Epic and Cerner order sets, creating switching costs that defend against emerging portfolio bundlers. For New Entrants and Emerging Players: The price-point gap between premium intravenous loop diuretics and economy oral thiazides opens white-space targeting for subcutaneous infusion technologies enabling home-based heart failure management. Penetrate rural health clinic networks lacking cardiology specialist access through telemedicine-integrated diuretic titration services. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by cardiovascular portfolio bundlers seeking diuretic assets to complete heart failure offerings. Long-term viability favors manufacturers with FDA-established quality systems and pre-2018 ANDA approvals avoiding retrospective compliance costs. Watch FDA bioequivalence guidance revisions as the inflection signal for generic entry timeline extensions.| Strategic Initiative | Industry Significance |
|---|---|
| API Backward Integration | Captive furosemide production insulates margins from Chinese supply disruption and FDA import alerts. |
| Hospital System Partnership | Epic order set integration locks in formulary positioning under cardiovascular bundle contracts. |
| Subcutaneous Formulation Development | Home infusion capability captures post-acute heart failure volume shifting from inpatient settings. |
| Remote Patient Monitoring Integration | Bluetooth-enabled weight scales enable algorithm-guided diuretic dosing outside hospital walls. |
| Pediatric Investigation Plan Filing | EMA regulatory incentives open development pathways for adjusted-dose oral solutions. |
Methodological Framework
Document review covered FDA ANDA filings, EMA centralized marketing authorization decisions, and hospital procurement databases, complemented by interviews with formulary directors, hospital pharmacy executives, generic manufacturing regulatory affairs leads, and cardiology practice administrators. Secondary sources included CMS Medicare Part D utilization data, ClinicalTrials.gov diuretic protocol registrations, and GPO contract award records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing provided triangulation checks.
Cross-referencing historical generic substitution patterns against expert panel input on bioequivalence enforcement trends shaped volume projections across the analysis window. Segmentation dimensions encompassed pharmacologic class, delivery mode, therapy area, and end-user setting. CAGRs derived from regression analysis of Medicare reimbursement policy impacts and hospital consolidation trajectories, with electrolyte monitoring cost burdens and fixed-dose combination substitution rates as key forecast inputs.
Inputs from FDA guidance documents and EMA pediatric investigation plan filings were available through the study window; gaps in real-world evidence for subcutaneous diuretic adoption introduce uncertainty bands around home care expansion trajectories. Forecasts reflect assumptions on value-based contract penetration and generic manufacturer compliance capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Global Hepatitis a Vaccine Market