
 Gemcitabine Hydrochloride Market | 2026-2036
Gemcitabine Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Gemcitabine Hydrochloride Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is pivoting procurement standards toward lower-carbon manufacturing of cytotoxic injectables. Pfizer leverages its integrated active pharmaceutical ingredient production to control cost structures across European hospital networks. Fresenius Kabi anchors European supply through specialized aseptic filling capacity for oncology formulations. Eli Lilly and Company sustains brand recognition in pancreatic carcinoma protocols despite generic erosion in other therapy areas.
Gemcitabine hydrochloride is a nucleoside analog chemotherapeutic agent, typically formulated as a sterile lyophilized powder for reconstitution or ready-to-use injectable solution, functioning through DNA chain termination after intracellular phosphorylation. Its primary purpose is first-line treatment of locally advanced or metastatic pancreatic carcinoma, with established protocols in non-small cell lung cancer and bladder cancer regimens. The lyophilized powder segment retains dominant share due to extended shelf stability and flexible dosing in hospital compounding pharmacies, while injectable solutions gain traction in outpatient oncology clinics seeking reduced preparation time. Pancreatic carcinoma anchors therapy area demand, though lung cancer applications represent the fastest-expanding protocol segment as combination regimens with platinum agents proliferate.
FDA bioequivalence standards for generic oncology injectables, EMA's Good Manufacturing Practice inspections for cytotoxic facilities, and WHO prequalification requirements for procurement eligibility collectively shape manufacturing investment and market access trajectories. These frameworks elevate barrier costs for new entrants while rewarding established producers with inspection histories and dedicated containment infrastructure. Stakeholders must monitor evolving biosimilar competition and payer consolidation effects on tender pricing dynamics.
Market Dynamics
The gemcitabine hydrochloride market pivots on the tension between accelerated generic entry pathways and the capital intensity of cytotoxic manufacturing containment. FDA's abbreviated new drug application streamlining for oncology injectables compresses competitive windows while EMA's tightened environmental discharge rules for aseptic cytotoxic facilities elevate fixed costs for producers.
Growth Catalysts
- Medicare reimbursement frameworks:The United States sustains high-volume hospital purchasing through prospective payment system carve-outs for pancreatic carcinoma protocols. This reimbursement certainty anchors demand concentration.
- Combination regimen expansion:Platinum-agent pairing protocols in non-small cell lung cancer are electrifying volume growth beyond pancreatic applications. Oncology clinics are adopting these regimens at accelerating pace.
- Outpatient clinic migration:Ready-to-use injectable solutions reduce compounding pharmacy burden. This format shift captures ambulatory care center demand seeking preparation time compression.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in India and China. Geopolitical friction or export licensing delays disrupt finished dose availability.
- EMA environmental compliance:Cytotoxic facility wastewater discharge thresholds under the EU Green Deal impose retrofit capex. Smaller manufacturers face facility consolidation pressure.
- Biosimilar pipeline maturation:Follow-on biologics for PD-1 and PARP inhibitors threaten gemcitabine's position in combination protocols. These substitutes compete for the same patient populations.
Strategic Opportunities
- Latin American tender markets:WHO prequalification eligibility opens procurement in Brazil and Mexico. Manufacturers with inspection histories capture volume through PAHO pooled purchasing.
- Lyophilized-to-solution conversion:Hospital pharmacy automation investments favor ready-to-use formats. This technology convergence reduces nursing preparation error liability.
- Bladder cancer protocol expansion:Intravesical administration guidelines in European urology associations are expanding addressable patient pools beyond systemic indications.
Industry Challenges
- Aseptic containment engineering talent:Isolator technology and restricted access barrier system design expertise concentrates with legacy cytotoxic manufacturers. New entrants face recruitment friction for specialized cleanroom architects.
- Multi-site inspection coordination:FDA and EMA synchronized audit scheduling creates compliance timeline compression. Facilities must maintain simultaneous readiness for divergent documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gemcitabine Hydrochloride Market |
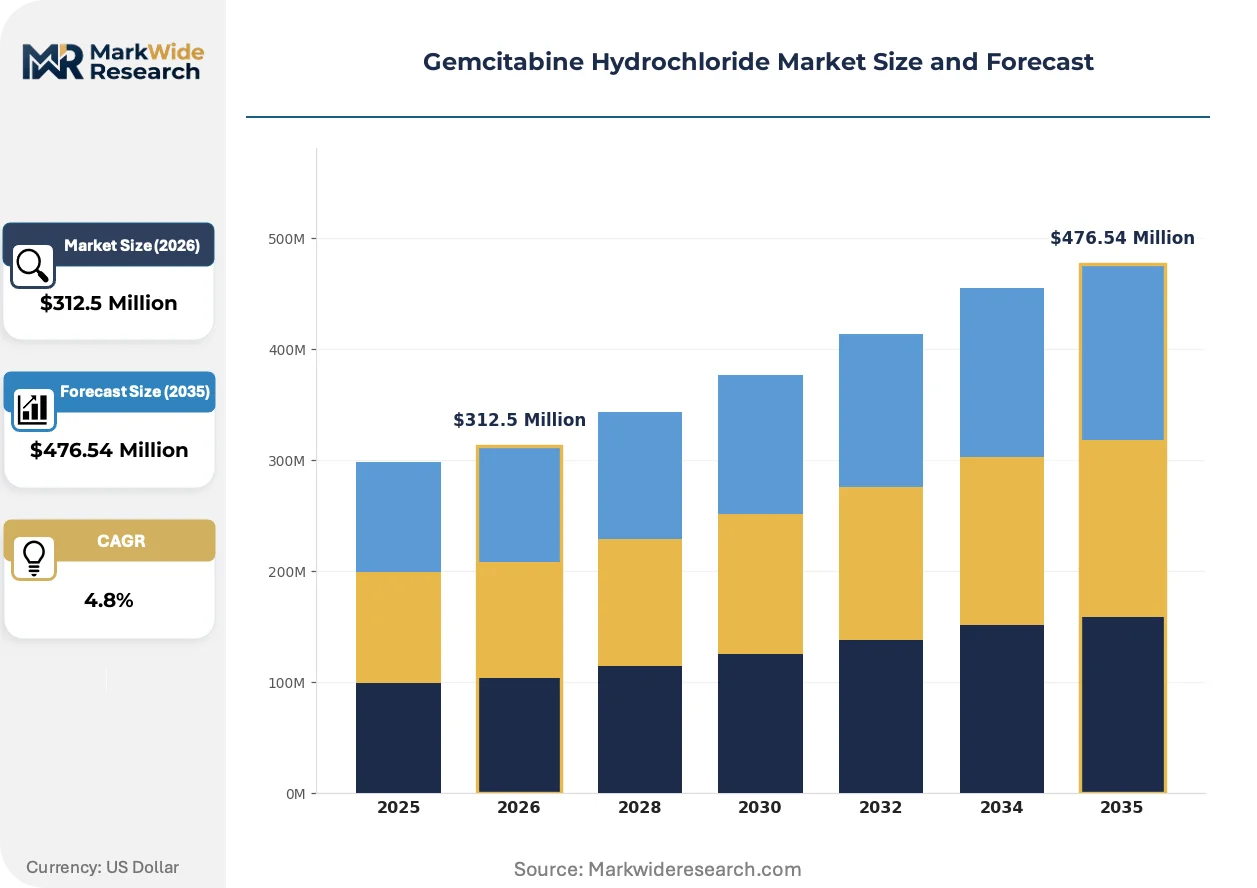
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Lyophilized Powder, Injectable Solution, Oral Formulation Therapy Area: Lung Cancer, Pancreatic Carcinoma, Bladder Cancer, Breast Carcinoma, Ovarian Neoplasm End User: Hospitals, Oncology Clinics, Research Institutes, Specialty Pharmacies Delivery Mode: Intravenous Infusion, Intramuscular Injection, Subcutaneous Injection, Oral Administration |
| Companies Covered | Accord Healthcare, Fresenius Kabi, Dr. Reddy's Laboratories, Pfizer, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Aurobindo Pharma, Apotex, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gemcitabine Hydrochloride Market Shifts & Advancements
Continuous manufacturing technologies and closed-system transfer devices are compressing contamination risk profiles while regulatory frameworks harden around environmental accountability. These forces are reshaping capital allocation priorities across the value chain.
Closed-system drug transfer devices (CSTDs) for hazardous drug handling are electrifying compounding safety standards. Hospital pharmacies in the United States and Germany are mandating CSTD integration for all cytotoxic preparation. This technology is electrifying demand for compatible vial adapters and syringe systems, compressing market share for legacy open-system suppliers.
The EU Green Deal's pharmaceutical sustainability criteria is tightening embodied carbon thresholds for imported oncology injectables. Manufacturers must now document Scope 3 emissions across API synthesis and aseptic filling. European hospital networks are responding by inserting carbon intensity scoring into tender evaluation matrices alongside unit price.
Consolidated purchasing organizations in the United States are unbundling drug procurement from infusion service contracts. Large oncology practice networks now source gemcitabine through specialty distributors rather than integrated health system formularies. This channel disintermediation is most visible in Florida and Texas, where independent oncology groups have captured significant patient volume from hospital outpatient departments.
Gemcitabine Hydrochloride Market Segmentation
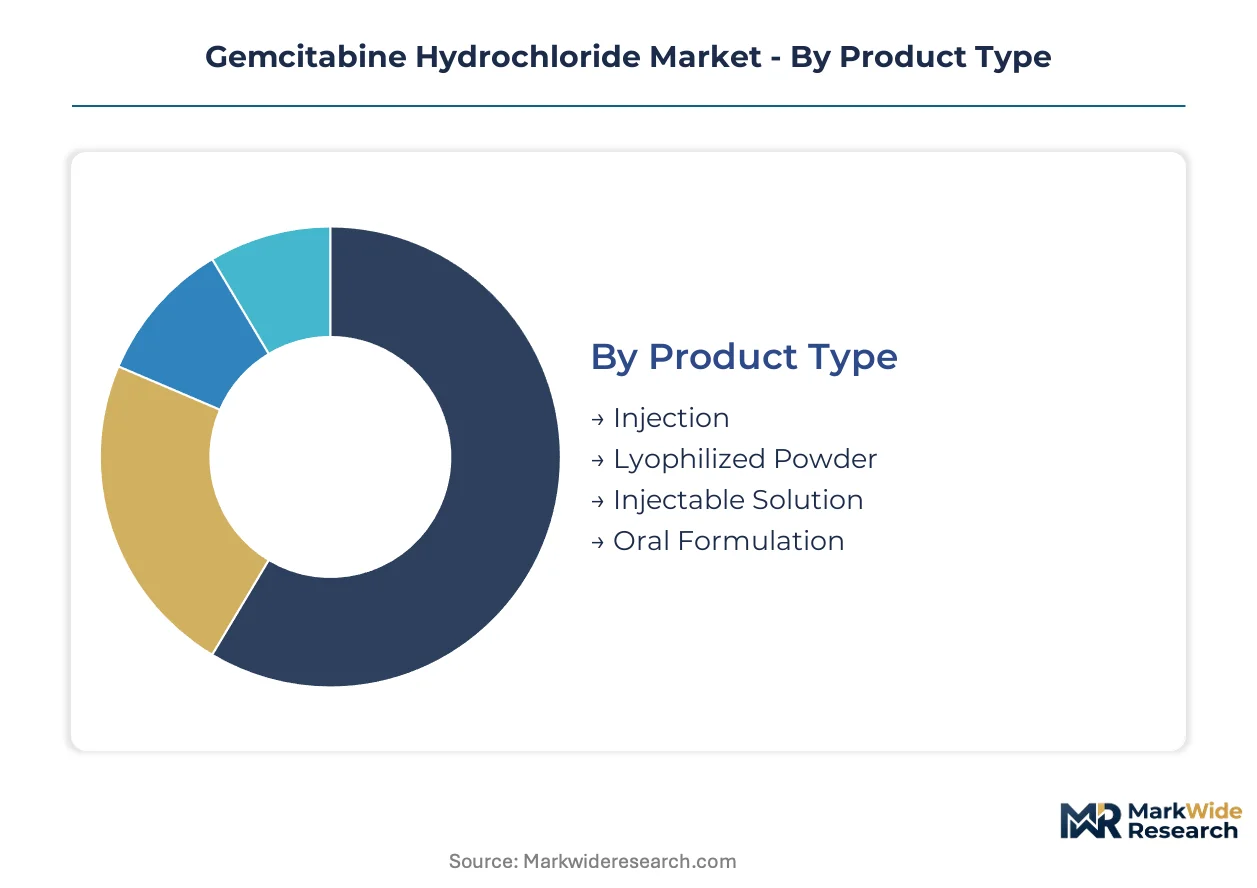
Formulation stability and administration setting dictate procurement patterns across the gemcitabine hydrochloride market. Hospital pharmacy directors weigh shelf-life economics against nursing preparation burden when selecting between lyophilized and liquid formats.
Product Type:
Procurement committees prioritize total cost of ownership spanning cold-chain logistics, compounding labor, and waste reduction.
- Lyophilized Powder:Freeze-dried crystalline formulation requiring sterile water reconstitution before administration. Hospital compounding pharmacies in Germany and France favor this format for batch preparation flexibility and extended stability at controlled room temperature. The powder's 36-month shelf life reduces inventory obsolescence risk for low-volume oncology centers.
- Injectable Solution:Ready-to-use liquid formulation in single-dose vials or prefilled syringes. Outpatient oncology clinics in the United States are migrating toward this format to compress nursing preparation time and minimize exposure risk during hazardous drug handling. The solution eliminates reconstitution error variables that trigger medication safety incidents.
- Injection:General parenteral category encompassing both reconstituted powders and manufactured solutions for intravenous delivery.
- Oral Formulation:Experimental tablet or capsule presentations under limited clinical investigation; bioavailability challenges have constrained commercial adoption.
Lyophilized powder leads on scale; injectable solution leads on momentum.
Therapy Area:
Protocol expansion velocity varies sharply across malignancy types, with combination regimen adoption rates determining volume trajectories.
- Pancreatic Carcinoma:First-line standard-of-care indication where gemcitabine anchors FOLFIRINOX and gemcitabine-nab-paclitaxel protocols. Academic medical centers in the United States sustain the highest per-facient dosing intensity globally.
- Lung Cancer:Non-small cell lung cancer applications are expanding most quickly as platinum-gemcitabine doublets penetrate community oncology practices. The segment benefits from ESMO guideline endorsements for squamous histology subtypes.
- Bladder Cancer:Intravesical administration for non-muscle-invasive disease represents a distinct usage pattern with specialized urology clinic demand.
- Breast Carcinoma:Metastatic triple-negative protocols incorporate gemcitabine in salvage regimens after taxane failure.
- Ovarian Neoplasm:Platinum-resistant recurrence settings employ gemcitabine as monotherapy or in combination with bevacizumab.
Pancreatic carcinoma dominates current volume; lung cancer displays the steepest expansion trajectory.
End User:
Site-of-care migration is fragmenting purchasing authority away from centralized hospital formularies.
- Hospitals:Inpatient oncology units and hospital outpatient departments command the largest procurement volumes through group purchasing organization contracts. Medicare reimbursement carve-outs for pancreatic carcinoma sustain high-volume purchasing in United States academic medical centers.
- Oncology Clinics:Independent and hospital-affiliated ambulatory infusion centers are capturing patient volume through convenience positioning. These clinics favor ready-to-use formulations that minimize pharmacy infrastructure investment.
- Specialty Pharmacies:Dispensing pharmacies serving oral oncology agents; limited relevance for injectable gemcitabine.
- Research Institutes:Phase I-II clinical trial sponsors sourcing investigational supplies for combination protocol development.
Hospitals retain volume leadership; oncology clinics are gaining share fastest.
Delivery Mode:
Administration route selection follows tumor biology, with vascular access requirements influencing patient eligibility.
- Intravenous Infusion:Standard 30-minute infusion via peripheral or central venous access. The vast majority of gemcitabine administration occurs through this route across all approved indications.
- Intramuscular Injection:Not employed for gemcitabine; listed for completeness in delivery taxonomy.
- Subcutaneous Injection:Not employed for gemcitabine; listed for completeness in delivery taxonomy.
- Oral Administration:Preclinical and early clinical investigation only; enzymatic degradation in the gastrointestinal tract limits systemic exposure.
Intravenous infusion commands absolute scale; no alternative route demonstrates meaningful momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology pharmacy specialists concentrate in academic medical centers across five countries where pancreatic carcinoma protocols drive procurement intensity. These clusters anchor gemcitabine hydrochloride demand through Medicare reimbursement frameworks and national cancer institute funding.
United States
MD Anderson Cancer Center and Memorial Sloan Kettering sustain the highest per-facility dosing volumes globally for FOLFIRINOX protocols. FDA accelerated approval pathways for generic oncology injectables compress manufacturer time-to-market windows. Philadelphia and Boston corridor hospitals anchor group purchasing organization contracting for cytotoxic formulations.
Germany
University hospitals in Heidelberg and Munich favor lyophilized powder formats for batch preparation flexibility in compounding pharmacies. EMA tightened environmental discharge thresholds under EU Green Deal pharmaceutical sustainability criteria. The Rhine-Main industrial cluster hosts specialized aseptic filling capacity for oncology injectables.
India
Active pharmaceutical ingredient synthesis clusters in Hyderabad and Ahmedabad supply global finished dose manufacturers. CDSCO manufacturing facility inspections align with WHO prequalification requirements for export eligibility. Gujarat's pharmaceutical special economic zones concentrate cytotoxic containment infrastructure investment.
Japan
PMDA oncology drug pricing negotiations sustain hospital reimbursement for gemcitabine-nab-paclitaxel combination regimens. Tokyo and Osaka metropolitan cancer centers drive intravenous infusion protocol standardization. The Kansai region maintains legacy nucleoside analog manufacturing expertise.
Brazil
ANVISA streamlined registration pathways for WHO-prequalified oncology generics expand procurement access. São Paulo state oncology networks anchor PAHO pooled purchasing volume for injectable cytotoxics. The Campinas pharmaceutical corridor concentrates Latin American distribution logistics for temperature-controlled injectables.
Gemcitabine Hydrochloride Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as integrated API manufacturers face contract formulation specialists. The market structure consolidates around three tiers: originators with brand recognition in pancreatic protocols, integrated generic houses with captive API supply, and regional injectable specialists with aseptic containment expertise. Dominant competitive moves include backward integration into API synthesis and geographic expansion through WHO prequalification procurement eligibility.
Within the integrated generic tier, Fresenius Kabi and Dr. Reddy's Laboratories exemplify manufacturers combining European aseptic filling capacity with Indian API sourcing economics. Pfizer occupies a position bridging originator brand equity and generic portfolio breadth. These three anchors represent divergent responses to EMA environmental compliance costs and FDA bioequivalence standard harmonization pressures.
| Leading Market Players |
|---|
| Accord Healthcare |
| Fresenius Kabi |
| Dr. Reddy's Laboratories |
| Pfizer |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Aurobindo Pharma |
| Apotex |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient synthesis costs in Hyderabad and Ahmedabad flow through to finished dose pricing tiers, with EMA environmental compliance capex separating premium European aseptic filling from economy Indian contract manufacturing. Hospital procurement committees in the United States and Germany weigh total cost of ownership across cold-chain logistics, compounding labor, and waste reduction when selecting between lyophilized powder and ready-to-use injectable formats.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes pricing models across the gemcitabine hydrochloride market. Large oncology practice networks in Florida and Texas now source gemcitabine through specialty distributors rather than integrated health system formularies, compressing margins for manufacturers dependent on hospital outpatient department contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence certification status, WHO prequalification eligibility, and aseptic containment infrastructure investment. Community oncology practices display the highest price sensitivity, while academic medical centers anchor premium tier demand through protocol standardization and brand loyalty in pancreatic carcinoma regimens.
Supply Chain Analysis
Workforce availability constraints in isolator technology and restricted access barrier system design concentrate with legacy cytotoxic manufacturers in Germany and the United States, elevating recruitment friction for new entrants. API production clusters in India and China feed finished dose manufacturers in Europe and North America, with CDSCO and NMPA inspections determining export eligibility. Supply chain risk centers on single-source vulnerability for nucleoside analog synthesis expertise and geopolitical friction affecting export licensing timelines. Distribution runs through hospital group purchasing organizations in the United States and PAHO pooled purchasing mechanisms in Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gemcitabine hydrochloride market functions as a geographic-arbitrage play between Indian API synthesis economics and European aseptic filling premiums, with EMA environmental discharge thresholds under the EU Green Deal widening the cost differential.
For Market Incumbents: Anticipate biosimilar pipeline maturation for PD-1 and PARP inhibitors threatening gemcitabine's position in combination protocols by deepening backward integration into API synthesis and securing WHO prequalification eligibility for Latin American tender markets. Capture volume through PAHO pooled purchasing in Brazil and Mexico while defending margin position in European hospital networks through specialized aseptic filling capacity investments. For New Entrants and Emerging Players: The price-point gap between premium European-origin lyophilized powder and economy Indian contract manufacturing creates white-space opportunity in outpatient oncology clinics migrating toward ready-to-use injectable solutions. Target ambulatory infusion centers in the United States seeking preparation time compression and reduced nursing error liability. Establish go-to-market presence through specialty distributor relationships rather than hospital group purchasing organization contracts. For Investors and Strategic Acquirers: Roll-up economics work for regional injectable specialists with aseptic containment expertise because FDA and EMA synchronized audit scheduling creates compliance timeline compression that favors established producers with inspection histories. Target manufacturers combining Indian API sourcing economics with European filling capacity over a five-to-ten year viability window. Monitor WHO prequalification pipeline maturation as inflection indicator for procurement access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive supply of nucleoside analog precursors insulates margin from Indian export licensing volatility. |
| WHO Prequalification Pathway | PAHO pooled purchasing eligibility opens procurement access in Brazil and Mexico oncology networks. |
| Lyophilized-to-Solution Format Conversion | Outpatient clinic automation investments favor ready-to-use formats reducing nursing preparation burden. |
| EMA Environmental Compliance Investment | EU Green Deal pharmaceutical sustainability criteria inserts carbon intensity scoring into tender evaluations. |
| Closed-System Transfer Device Integration | CSTD compatibility captures hospital pharmacy mandates in the United States and Germany for hazardous drug handling. |
Research Methodology
Bottom-up oncology clinic and hospital procurement modeling reconciled against top-down API synthesis and finished dose production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Cross-referencing manufacturer inspection histories with WHO prequalification status and CMS Medicare reimbursement data enables demand-side and supply-side triangulation.
Historical trendline analysis of pancreatic carcinoma protocol adoption rates and platinum-gemcitabine doublet expansion in non-small cell lung cancer anchors the forecast framework. Segmentation dimensions modeled include formulation type, therapy area, end-user setting, and regional regulatory cluster across the projection horizon. CAGRs derive from protocol expansion velocity, site-of-care migration patterns, and tender pricing dynamics. Forecast inputs incorporate EMA environmental compliance cost trajectories and biosimilar pipeline maturation timelines.
Caveats apply where FDA bioequivalence standard revisions, EMA Good Manufacturing Practice inspection scheduling changes, or WHO prequalification requirement updates could materially shift the outlook. Forecasts reflect assumptions regarding Medicare reimbursement framework stability and geopolitical friction in API export licensing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Blood Coagulants Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Hospital Pharmaceuticals Market