
 Nasal Antihistamines Market | 2026-2036
Nasal Antihistamines Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Antihistamines Market Outlook
Prescription volume among pediatric allergy specialists is pivoting toward intranasal antihistamines as preferred first-line therapy over oral alternatives. GlaxoSmithKline leverages its respiratory franchise infrastructure to sustain shelf presence across hospital formularies. Novartis AG anchors its position through specialized ophthalmic-allergy crossover expertise that extends into nasal delivery. Bayer Healthcare LLC competes on brand recognition in direct-to-consumer channels.
Nasal antihistamines constitute a class of locally acting H1-receptor antagonists formulated for mucosal administration, typically delivered as aqueous or aerosolized suspensions with particle sizes optimized for turbinate deposition between 10-50 microns. These agents block histamine-mediated vasodilation and parasympathetic reflexes in the nasal mucosa, providing rapid symptom relief for allergic rhinitis without systemic first-pass metabolism. Azelastine formulations occupy the dominant revenue position due to established efficacy in both seasonal and perennial indications, while olopatadine nasal spray represents the fastest-expanding segment driven by dual antihistamine-mast cell stabilizing activity. Nasal spray delivery mode leads volume share, though multi-dose pump mechanisms concentrate margin pools through device patent protection and patient compliance advantages.
FDA bioequivalence requirements for locally acting nasal sprays, including scintigraphy or pharmacodynamic endpoint studies, elevate barriers for generic entrants and preserve branded pricing power. EMA's MDR and CE marking frameworks for drug-device combination products shape European market access timelines and clinical data requirements. REACH compliance for propellant and preservative chemistry influences formulation decisions across manufacturing networks. Stakeholders must monitor evolving FDA guidance on comparative clinical endpoint studies for complex generic nasal sprays, as this regulatory trajectory will determine competitive intensity and investment allocation across the development pipeline.
Market Dynamics
FDA bioequivalence standards for locally acting nasal sprays are compressing generic entry timelines and preserving branded pricing power through elevated clinical endpoint requirements.
Growth Catalysts
- Seasonal allergic rhinitis prevalence:United States prescription volume sustains consistent demand across pediatric and adult patient populations.
- REACH compliance frameworks:European formulation standards for propellant chemistry are accelerating preservative-free suspension development.
- Dual-action pharmacology:Mast cell stabilizing antihistamines expand formulary adoption in allergy clinics seeking rapid symptom control.
Market Restraints
- Scintigraphy study costs:FDA pharmacodynamic endpoint requirements for generic nasal sprays impose substantial clinical trial burdens.
- Device patent concentration:Multi-dose pump mechanisms face supply constraints from specialized European component manufacturers.
- Oral antihistamine substitution:Over-the-counter loratadine and cetirizine formulations compete on price in first-line therapy decisions.
Strategic Opportunities
- Pediatric formulary expansion:Allergy specialists in Germany and France are prioritizing intranasal first-line protocols for children under twelve.
- MDR harmonization:CE marking convergence for drug-device combinations streamlines multi-country European market access.
- Telehealth prescribing channels:Direct-to-patient platforms in the United States reduce traditional pharmacy intermediation.
Industry Challenges
- Aerosol engineering talent scarcity:Particle size optimization for turbinate deposition requires specialized pharmaceutical formulation expertise.
- Legacy system integration:Hospital formulary management platforms resist rapid updates to intranasal therapeutic protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Antihistamines Market |
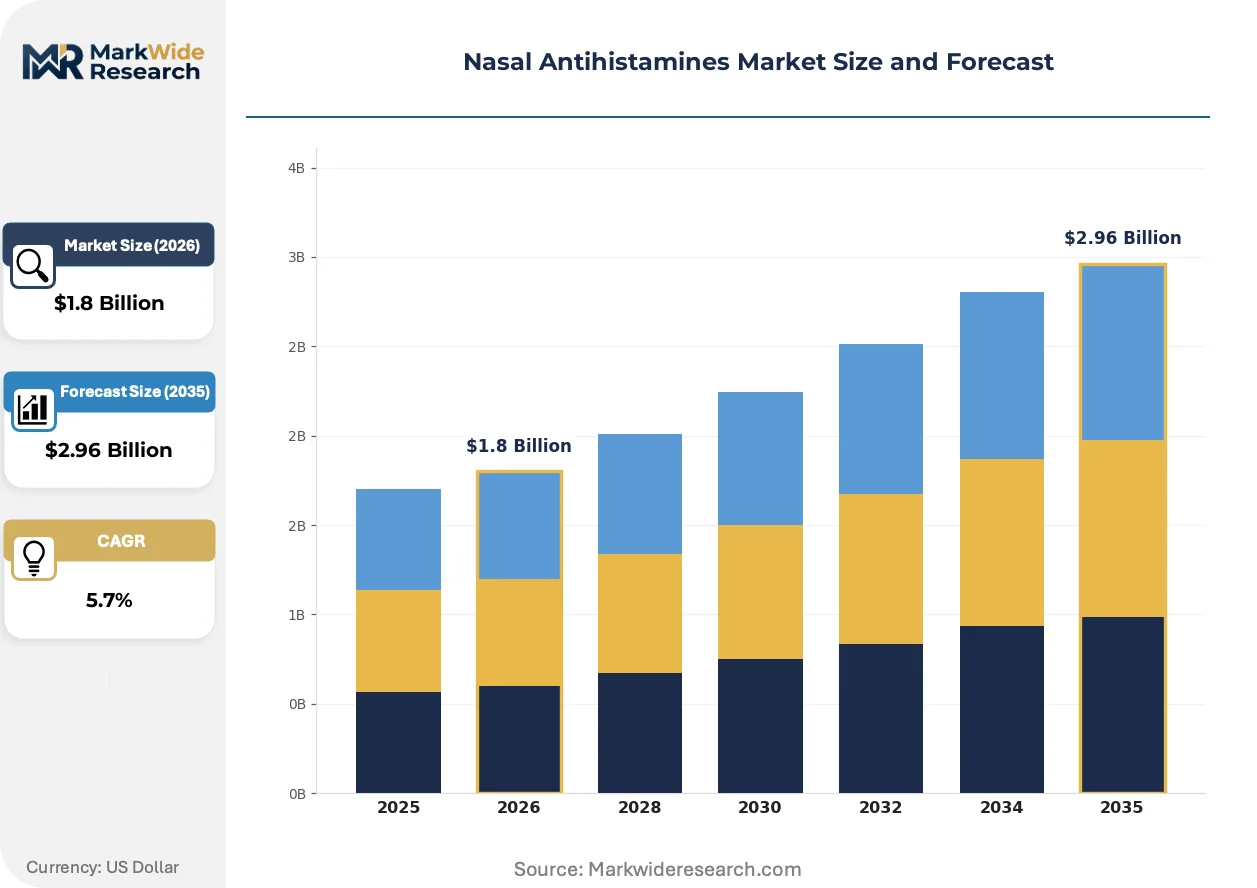
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azelastine, Olopatadine, Levocabastine, Others Delivery Mode: Nasal Spray, Nasal Drop, Powder, Others End User: Pharmacies, Hospitals, Clinics, Online Retail Packaging Type: Single-dose, Multi-dose, Boxed, Others |
| Companies Covered | Bayer Healthcare LLC, Novartis AG, Glenmark Pharmaceuticals, GlaxoSmithKline, Sun Pharmaceuticals, Cipla, Viatris, Merck & Co., Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Antihistamines Market Strategic Shifts
Device engineering and regulatory science are converging to reshape competitive positioning in nasal delivery systems, with particle engineering and combination pharmacology driving differentiation.
Dual-mechanism antihistamine-mast cell stabilizers are unifying rapid onset with sustained prophylaxis in single formulations. Pediatric allergy clinics in the United States and Germany are adopting these agents at accelerated rates for seasonal prophylaxis. This unification is compressing the market space for single-mechanism alternatives and rewarding developers with ophthalmic-nasal crossover expertise.
EMA's MDR implementation for drug-device combination products is extending clinical data requirements and market access timelines across European manufacturing networks. Manufacturers must now submit device-specific biocompatibility studies alongside pharmaceutical dossiers. Nasal spray categories with pump mechanisms face the steepest compliance curves in France and Italy.
Direct-to-consumer channel expansion is fragmenting traditional pharmacy distribution for maintenance therapy prescriptions. Telehealth platforms and subscription models are displacing retail pharmacy fulfillment for chronic rhinitis patients in the United States. This shift is most visible among urban millennials managing perennial allergic symptoms through automated refill programs.
Nasal Antihistamines Market Segmentation
Segmentation in nasal antihistamines reveals how formulation chemistry, device engineering, and channel economics partition commercial opportunity. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
Product Type:
Replacement cycles in allergic rhinitis therapy accelerate as dual-mechanism formulations displace single-action predecessors in formulary protocols.
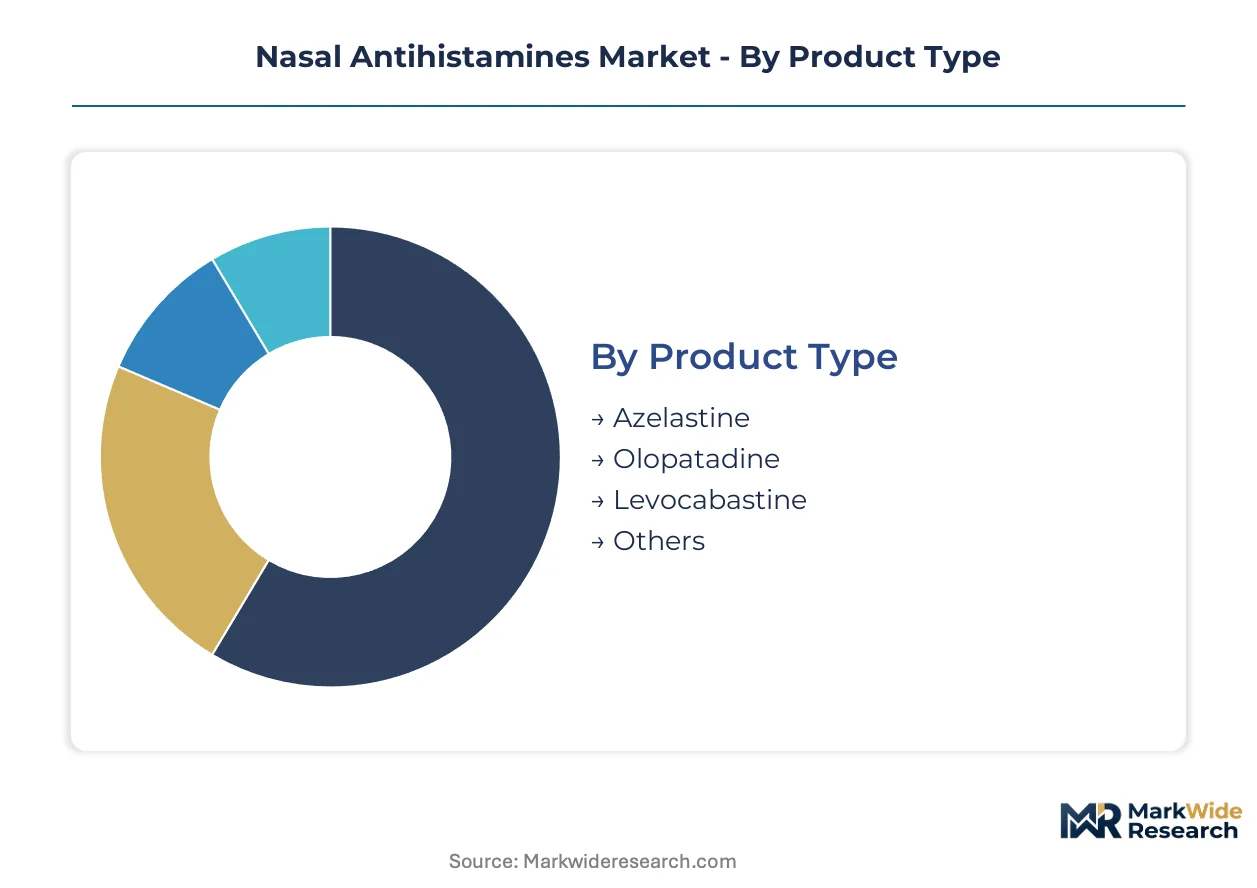
- Azelastine:H1-receptor antagonist with established efficacy in seasonal and perennial indications commands the largest prescription volume. United States allergy clinics favor this agent for rapid symptom relief, though bitter taste remains a compliance constraint in pediatric populations.
- Olopatadine:Dual antihistamine-mast cell stabilizing activity delivers both immediate relief and prophylactic coverage. German and French pediatric specialists are adopting this formulation fastest for children requiring sustained seasonal protection.
- Levocabastine:Highly selective H1 antagonist with minimal sedation profile serves niche demand in occupational settings requiring alertness maintenance.
- Others:Emerging H1 antagonists and combination therapies in development pipelines target refractory patient subsets.
Azelastine sits at the top of the volume ranking, with Olopatadine climbing the fastest.
Delivery Mode:
Cost tier differentiation separates premium device-engineered systems from commodity spray mechanisms in procurement decisions.
- Nasal Spray:Aqueous or aerosolized suspensions with 10-50 micron particle optimization for turbinate deposition dominate unit volume. Multi-dose pump patents concentrate margin pools through device exclusivity and patient compliance advantages.
- Nasal Drop:Gravity-dependent instillation suits pediatric and geriatric patients with coordination limitations. Lower manufacturing complexity competes on price in emerging markets.
- Powder:Dry particle formulations eliminate preservative concerns and extend stability profiles for tropical distribution.
- Others:Novel delivery mechanisms including breath-actuated systems and connected devices in clinical evaluation.
Nasal Spray leads absolute volume, with Powder gaining share fastest in preservative-sensitive segments.
End User:
Application-driven channel segmentation separates acute intervention settings from chronic maintenance management in reimbursement design.
- Pharmacies:Retail and community dispensaries handle the majority of seasonal prescription fulfillment. United States independent pharmacies face margin pressure from telehealth platform displacement.
- Hospitals:Inpatient and emergency departments utilize intranasal antihistamines for acute allergic reactions requiring rapid intervention without intravenous access.
- Clinics:Allergy and ENT specialist practices drive formulary adoption decisions through direct therapeutic protocol influence.
- Online Retail:Direct-to-consumer platforms and subscription models fragment traditional pharmacy intermediation for chronic rhinitis maintenance.
Pharmacies anchor volume leadership, with Online Retail expanding most quickly among urban millennial demographics.
Packaging Type:
Supply concentration in European pump component manufacturing shapes multi-dose availability and pricing stability.
- Single-dose:Unit vials eliminate preservative requirements and cross-contamination risk in immunocompromised patients. Higher per-dose cost limits volume to hospital and specialty clinic procurement.
- Multi-dose:Pump mechanisms with device patent protection deliver superior patient compliance and manufacturer margin retention. REACH compliance for propellant chemistry accelerates preservative-free suspension development.
- Boxed:Retail-oriented secondary packaging supports direct-to-consumer channel expansion and brand differentiation.
- Others:Blister packs, travel kits, and compliance-enhancing packaging for specific demographic segments.
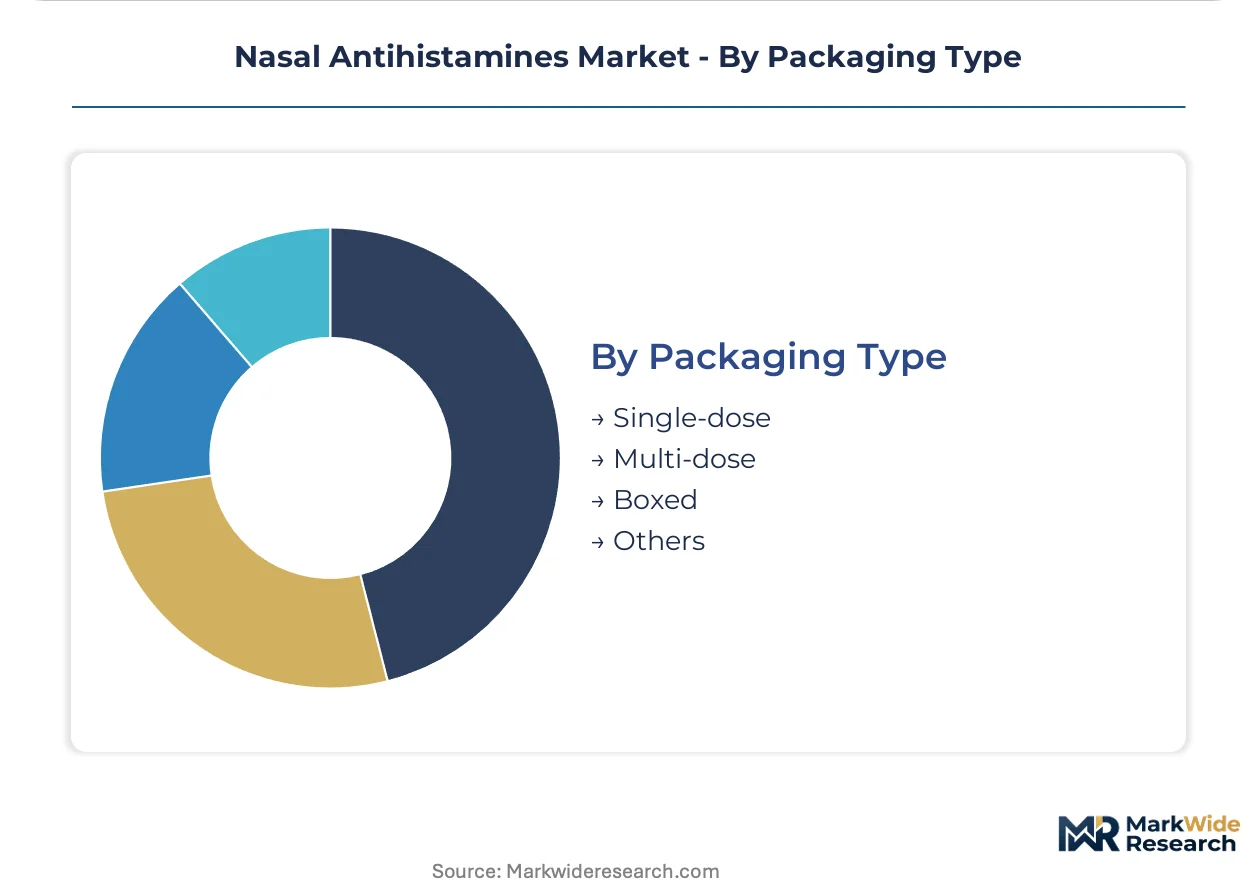
Multi-dose packaging commands volume primacy, with Single-dose climbing fastest in hospital infection-control protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Allergist workforce density in the United States anchors the highest prescription volume globally. German pharmaceutical formulation clusters supply multi-dose pump mechanisms across European markets. Japanese regulatory science expertise shapes bioequivalence study standards for complex nasal generics.
United States
Seasonal allergic rhinitis prevalence drives consistent prescription volume across pediatric and adult populations. FDA bioequivalence standards for locally acting nasal sprays elevate clinical endpoint requirements for generic entrants. The Research Triangle Park corridor in North Carolina concentrates contract research organizations conducting scintigraphy studies for ANDA submissions.
Germany
Pediatric allergy specialists in Bavaria and Baden-Württemberg prioritize intranasal first-line protocols for children under twelve. EMA's MDR implementation for drug-device combinations extends clinical data requirements for pump mechanism manufacturers. Stuttgart's precision engineering cluster supplies specialized multi-dose pump components to formulation companies across the Rhine-Neckar metropolitan region.
France
Allergy clinic expansion in Île-de-France accelerates formulary adoption of dual-mechanism antihistamine-mast cell stabilizers. ANSM oversight of CE marking for drug-device combinations shapes market access timelines for preservative-free suspensions. Lyon-based pharmaceutical packaging specialists develop compliance-enhancing multi-dose systems for pediatric populations.
Japan
PMDA guidance on pharmacodynamic endpoint studies for locally acting nasal products influences global bioequivalence methodology. Tokyo-Osaka pharmaceutical corridors host formulation scientists specializing in particle size optimization for turbinate deposition. Kansai region device manufacturers engineer breath-actuated delivery systems for geriatric patient segments.
India
CDSCO accelerated approval pathways for generic nasal sprays attract contract manufacturing investment from European marketers. Maharashtra's pharmaceutical formulation belt in Mumbai-Pune corridor scales aqueous suspension production for tropical distribution. Hyderabad's active pharmaceutical ingredient cluster supplies azelastine hydrochloride to multi-national spray manufacturers.
Nasal Antihistamines Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation and device engineering vectors. The market structure concentrates margin pools among entities controlling multi-dose pump patents and respiratory franchise infrastructure. Three archetypes dominate: respiratory-diversified pharmaceutical majors, ophthalmic-nasal crossover specialists, and generic spray manufacturers with device sourcing capabilities. Competitive moves center on formulary anchoring through allergy clinic relationships and preservative-free suspension launches targeting REACH-compliant European procurement.
Among diversified pharmaceutical majors, GlaxoSmithKline and Novartis AG occupy positions reflecting respiratory and ophthalmic-allergy crossover expertise respectively. Bayer Healthcare LLC anchors the direct-to-consumer channel vector through brand recognition infrastructure. Glenmark Pharmaceuticals exemplifies the generic-specialist archetype with integrated formulation and device sourcing capabilities. These three entities represent distinct competitive positioning strategies: franchise leverage, therapeutic area extension, and cost-optimized manufacturing scale.
| Leading Market Players |
|---|
| Bayer Healthcare LLC |
| Novartis AG |
| Glenmark Pharmaceuticals |
| GlaxoSmithKline |
| Sun Pharmaceuticals |
| Cipla |
| Viatris |
| Merck & Co. |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Propellant chemistry costs for preservative-free aqueous suspensions cascade through multi-dose pump procurement tiers, with REACH-compliant European component sourcing anchoring premium pricing bands while Asian contract manufacturers compete on standard-grade aqueous formulations.
Pricing Analysis
Bundled device-and-formulation contracts separate premium pump-patent holders from unbundled generic spray competitors. Three-tier pricing structure across patented multi-dose systems, branded standard sprays, and economy aqueous generics reflects device exclusivity and bioequivalence study barriers. Pricing pressure stems from telehealth platform subscription models compressing retail pharmacy margins. Pediatric allergy clinics show lowest price sensitivity due to formulary protocol rigidity, while direct-to-consumer channels face acute substitution pressure from over-the-counter oral alternatives.
Supply Chain Analysis
Regional distribution centers in Stuttgart and Lyon coordinate hub-and-spoke delivery of precision-engineered pump mechanisms to formulation facilities across Germany, France, and Italy. Active pharmaceutical ingredient production draws from Hyderabad's azelastine hydrochloride cluster and Maharashtra's aqueous suspension belt. Single-source vulnerability concentrates in specialized European pump component manufacturers. Distribution runs through hospital formulary procurement platforms and direct-to-patient telehealth fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasal antihistamines market represents a late-cycle quality story as pediatric formulary protocols pivot toward preservative-free dual-mechanism formulations with superior compliance profiles.
For Market Incumbents: Hedge against generic spray erosion by securing backward integration into multi-dose pump manufacturing and accelerating preservative-free suspension launches ahead of REACH enforcement tightening. Device patent cliffs in European component supply threaten margin compression without captive production capacity.
For New Entrants and Emerging Players: Begin with telehealth-integrated subscription models targeting urban millennial chronic rhinitis patients in the United States, where pharmacy intermediation displacement creates white-space acquisition economics. Direct-to-consumer channel control offers faster formulary bypass than hospital procurement penetration.
For Investors and Strategic Acquirers: Consolidation pressure builds where ophthalmic-nasal crossover expertise overlaps with respiratory franchise infrastructure. Long-term viability favors acquirers of specialized aerosol engineering talent pools and CE marking capabilities under EMA MDR implementation. Watch FDA guidance evolution on comparative clinical endpoint studies for complex generics as the inflection signal determining competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Suspension Launch | REACH compliance accelerates European procurement preference for preservative-free aqueous formulations in pediatric segments. |
| Multi-Dose Pump Patent Acquisition | Device exclusivity anchors margin retention against generic spray competitors lacking formulation-device integration. |
| Telehealth Platform Partnership | Direct-to-patient subscription models displace retail pharmacy intermediation for chronic maintenance prescriptions. |
| EMA MDR Compliance Investment | CE marking convergence for drug-device combinations streamlines multi-country European market access timelines. |
| Dual-Mechanism Formulation Development | Antihistamine-mast cell stabilizer unification captures pediatric formulary adoption seeking rapid plus prophylactic coverage. |
Study Parameters
Bottom-up allergy clinic prescribing modeling reconciled against top-down pharmaceutical manufacturing tracking forms the analytical core of this study. Primary interviews with formulary directors, pediatric allergy specialists, regulatory affairs leads at nasal spray manufacturers, and hospital procurement managers combined with secondary validation against FDA ANDA filings, EMA drug-device combination submissions, ClinicalTrials.gov protocols, and European hospital procurement databases. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map active pharmaceutical ingredient throughput from Indian and Chinese manufacturing clusters through European pump component integration to end-use consumption across pharmacy, hospital, clinic, and online retail channels. Segmentation dimensions include product type chemistry, delivery mode engineering, end-user channel economics, and packaging format compliance requirements. CAGRs derive from patient population epidemiology, prescription volume trends, and pricing trajectory analysis across the projection horizon.
Several conditions sit outside the modeled scope, including pipeline products in preclinical development, regulatory approval timing uncertainty, and macroeconomic shocks to healthcare reimbursement. Forecasts reflect documented assumptions regarding formulary adoption rates and generic entry timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Middle East and Africa Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market