
 Global Autoimmune Drugs Market | 2026-2036
Global Autoimmune Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autoimmune Drugs Market Foresight
Buyer concentration among hospital systems and specialty clinic chains is shifting as outpatient infusion centers fragment the traditional hospital-centric model. AbbVie Inc. leverages its immunology portfolio depth to anchor physician loyalty across dermatology and gastroenterology practices. Johnson & Johnson competes through integrated patient support services that sustain adherence rates for its biologic franchises. Pfizer Inc. differentiates via manufacturing scale that controls supply security for global monoclonal antibody distribution.
Autoimmune drugs comprise therapeutics that modulate pathological immune responses through targeted protein inhibition, receptor blockade, or cytokine neutralization, typically requiring cold-chain distribution at two to eight degrees Celsius and subcutaneous or intravenous administration. These agents serve to induce remission, prevent tissue destruction, and maintain functional status in chronic conditions where conventional immunosuppression proves inadequate. Biologics and monoclonal antibodies occupy the dominant margin pools given their patent-protected positioning and infusion-based administration protocols that lock in site-of-care revenue. Small molecule Janus kinase inhibitors represent the fastest-expanding structural segment as oral convenience displaces injection burden in rheumatology and dermatology patient populations. Biosimilars are maturing fastest in European markets where tender-based procurement erodes originator pricing power across tumor necrosis factor inhibitor categories.
The FDA's accelerated approval framework and the EMA's adaptive pathways program shape development economics by permitting earlier revenue recognition based on surrogate endpoints. REACH compliance and EMA good manufacturing practice audits constrain contract manufacturing organization selection for European market access. Japan's PMDA sakigake designation accelerates domestic review timelines for autoimmune biologics addressing lupus erythematosus and inflammatory bowel disease unmet need. Stakeholders must monitor how CMS price negotiation authority and EU joint clinical assessment procedures reshape indication-specific commercial viability before committing to late-phase development programs.
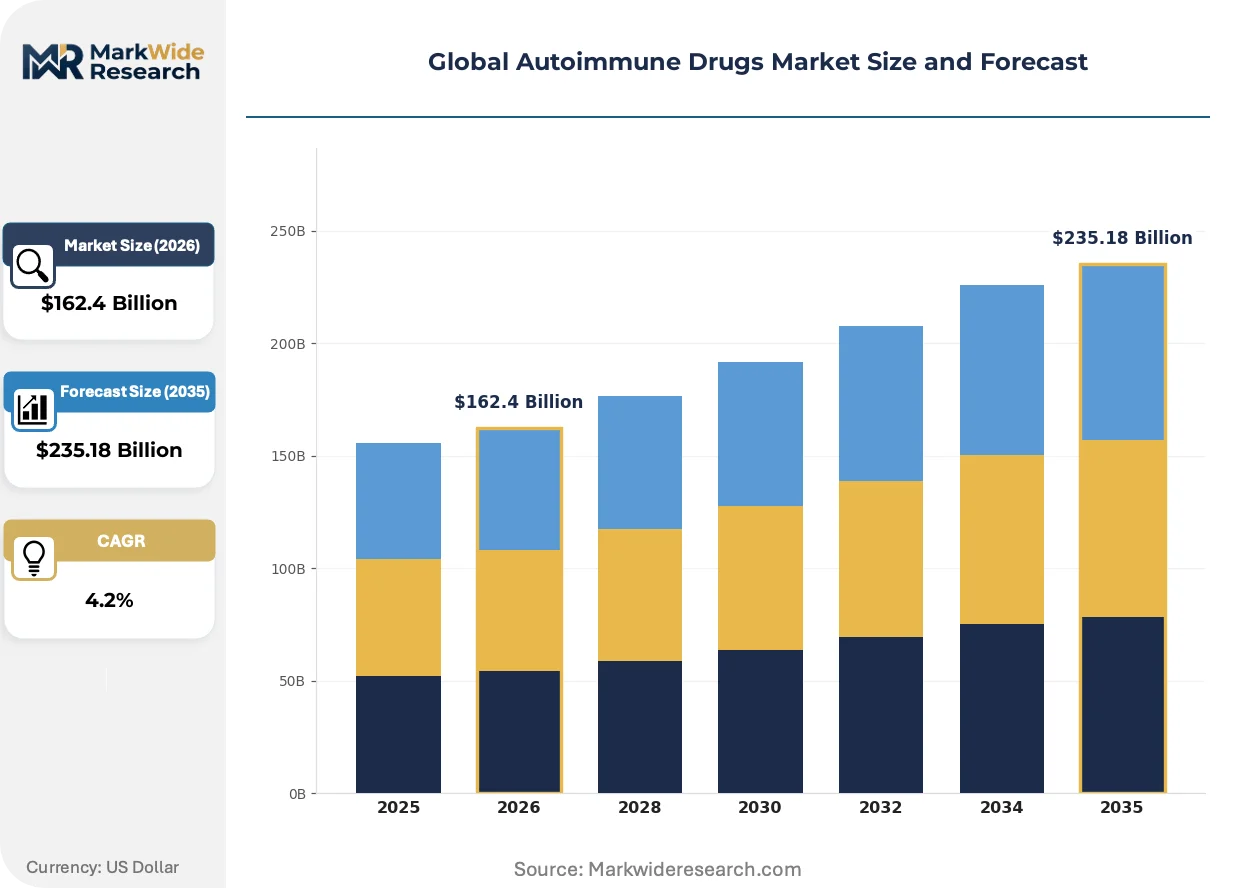
Market Dynamics
Biologic cold-chain infrastructure concentration and outpatient infusion center fragmentation are compressing traditional hospital revenue capture while redistributing site-of-care economics toward specialty clinic chains.
Growth Catalysts
- FDA Accelerated Approval:The FDA's breakthrough therapy designation compresses Phase III-to-commercial timelines for novel monoclonal antibodies, permitting revenue recognition on surrogate endpoints in rheumatoid arthritis and inflammatory bowel disease indications.
- Subcutaneous formulation migration:Auto-injector device platforms are displacing intravenous infusion burden, expanding patient self-administration in dermatology and gastroenterology practices and reducing site-of-care dependency.
- Japan PMDA Sakigake:Japan's priority review scheme for lupus erythematosus and inflammatory bowel disease biologics accelerates domestic market entry, creating parallel revenue streams outside US-EU pricing pressure.
Market Restraints
- EMA Joint Clinical Assessment:The EU's Health Technology Assessment harmonization creates centralized pricing benchmarks that compress indication-specific commercial viability across member states.
- Biosimilar tender procurement:European hospital system tender-based purchasing erodes originator tumor necrosis factor inhibitor pricing power and locks out non-winning manufacturers from multi-year contracts.
- Plasma-derived input volatility:Immunoglobulin and albumin feedstock supply concentrates in US and European collection networks, exposing manufacturing cost structures to donor recruitment cyclicality and pathogen screening protocol changes.
Strategic Opportunities
- India CDSCO fast-track:India's streamlined approval pathway for biologics addressing unmet autoimmune need creates first-mover positioning in a market where private insurance expansion is lifting biologic access.
- Oral JAK inhibitor convergence:Small molecule Janus kinase inhibitor technology is converging with companion diagnostic development, enabling precision patient selection that preserves reimbursement in crowded rheumatology categories.
- Home infusion channel innovation:Specialty pharmacy direct-to-patient distribution is bypassing traditional hospital outpatient departments, capturing margin from infusion administration fees and adherence monitoring services.
Industry Challenges
- Cell line development talent scarcity:Mammalian expression system expertise and biosimilar analytical characterization capabilities concentrate in Boston, Basel, and Singapore hiring markets, constraining CMO capacity expansion timelines.
- Legacy ERP integration friction:Biologic batch record systems and temperature excursion tracking platforms require multimillion-dollar validation cycles to interface with modern serialization and blockchain traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autoimmune Drugs Market |
| Market Size in 2026 | $162.4 Billion |
| Market Size in 2035 | $235.18 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecule Drugs, Janus Kinase Inhibitors, Monoclonal Antibodies, Biosimilars Indication: Rheumatoid Arthritis, Lupus Erythematosus, Psoriasis, Multiple Sclerosis, Inflammatory Bowel Disease End User: Hospitals, Specialty Clinics, Research Laboratories, Outpatient Care Centers Distribution Channel: Pharmacies, Hospital Pharmacies, Online Retailers, Direct Sales, Medical Representatives |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Pfizer Inc., Roche Holding AG, Novartis AG, Amgen Inc., Eli Lilly and Company, Bristol-Myers Squibb Company, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autoimmune Drugs Market Shifts & Advancements
Modular manufacturing platforms and adaptive trial designs are compressing development economics while patient administration preferences pull formulation innovation toward self-injection modalities.
Continuous bioprocessing technology is modularizing upstream cell culture and downstream purification operations, enabling 2000-liter single-use bioreactor trains that slash facility capital intensity. Contract development organizations in Switzerland and Massachusetts are adopting these skid-mounted units to serve mid-tier biopharma clients without dedicated plant investment. The technology is modularizing capacity deployment decisions, allowing production scale to follow clinical success rather than requiring pre-commitment to blockbuster-scale infrastructure.
REACH compliance and EMA good manufacturing practice audit reciprocity agreements are reshaping contract manufacturing organization selection criteria for European market access. Facilities without centralized European Medicines Agency inspection history face 18-24 month qualification delays that disqualify them from commercial supply agreements. Small molecule active pharmaceutical ingredient manufacturers in India and China are responding by acquiring distressed European facilities to inherit inspection credentials rather than building greenfield compliant capacity.
Specialty clinic chains are consolidating infusion capacity into ambulatory settings that displace hospital outpatient department economics, with United States dermatology and gastroenterology practices leading the migration. These centers capture site-of-care revenue through administration fee stacking and biosimilar switching incentives that hospital systems cannot match operationally. The behavioral shift is most visible in Texas, Florida, and North Carolina metropolitan corridors where certificate-of-need restrictions on hospital expansion created regulatory arbitrage for independent infusion investment.
Global Autoimmune Drugs Market Segmentation
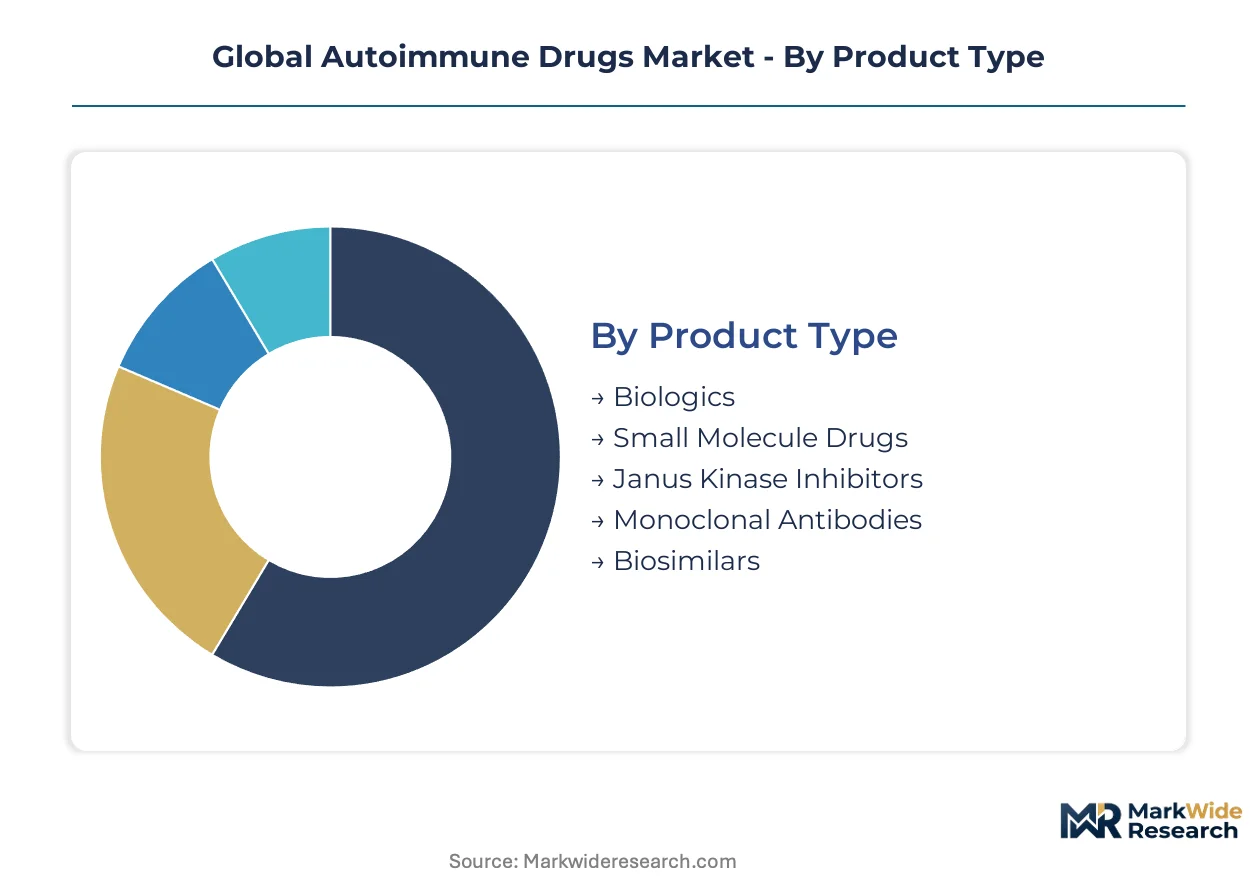
Autoimmune drug segmentation reveals how formulation technology, site-of-care economics, and reimbursement pathways fragment commercial opportunity. Each category captures distinct buyer priorities that reshape competitive positioning across chronic disease management.
Product Type:
Buyers differentiate by administration burden, cold-chain requirements, and patent protection runway rather than mechanism alone.
- Biologics:Protein-based therapeutics manufactured in mammalian cell cultures require continuous refrigeration and intravenous or subcutaneous delivery. Demand concentrates in United States and German hospital systems where reimbursement premiums offset infusion center infrastructure costs and originator patent thickets deter switching.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific cytokines or cell surface receptors dominate rheumatology and gastroenterology formularies. Japanese and Swiss prescribing patterns favor these agents for lupus erythematosus where diagnostic precision supports targeted therapy selection and maintenance dosing protocols.
- Small Molecule Drugs:Synthetic chemical compounds with oral bioavailability and ambient storage requirements.
- Janus Kinase Inhibitors:Oral small molecules interrupting intracellular signaling cascades; expanding fastest in dermatology practices seeking to displace injection burden.
- Biosimilars:Reverse-engineered biologics approved through abbreviated pathways; European tender procurement accelerates uptake against originator tumor necrosis factor inhibitors.
Volume sits with biologics; growth tilts toward Janus kinase inhibitors.
Indication:
Disease prevalence and unmet need severity determine pricing power and development priority across therapeutic areas.
- Rheumatoid Arthritis:Chronic synovial inflammation driving joint destruction attracts the deepest development pipeline and densest prescriber specialization. United States Medicare Part D formularies and German statutory health insurance funds allocate disproportionate budgets to this indication given functional status preservation metrics.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis require lifelong immunomodulation with high discontinuation costs. United Kingdom and Danish health technology assessment bodies scrutinize biologic value here most intensively, compressing indication-specific commercial viability through outcome-based reimbursement pilots.
- Lupus Erythematosus:Heterogeneous systemic autoimmunity with high unmet need; Japanese PMDA sakigake designation accelerates novel mechanism review.
- Psoriasis:Visible skin disease with patient-reported outcome sensitivity; dermatology practices in Spain and Italy drive oral JAK adoption for moderate cases.
- Multiple Sclerosis:Neurodegenerative autoimmunity with distinct relapse-remitting versus progressive phenotypes; specialty pharmacy distribution dominates in Canada and Australia.
Revenue concentrates in rheumatoid arthritis; pipeline investment flows fastest into lupus erythematosus.
End User:
Site-of-care selection hinges on infusion infrastructure, biosimilar switching incentives, and patient adherence monitoring capabilities.
- Specialty Clinics:Ambulatory centers consolidating dermatology and gastroenterology infusion capacity capture administration fee revenue that hospital outpatient departments forfeit. Texas, Florida, and North Carolina metropolitan corridors exhibit the most aggressive independent infusion investment where certificate-of-need restrictions created regulatory arbitrage.
- Hospitals:Academic medical centers retain complex biologic initiation and immunogenicity monitoring for rituximab and other lymphocyte-depleting agents. German and French public hospital systems maintain formulary control through centralized pharmacy and therapeutics committees that resist biosimilar switching without head-to-head trial data.
- Outpatient Care Centers:Community-based infusion suites with lower overhead structures; expanding in Indian private healthcare networks as biologic access broadens beyond tier-1 cities.
- Research Laboratories:Clinical trial sites and biomarker discovery facilities; concentrated in Boston, Basel, and Singapore talent clusters.
Patient volume remains hospital-anchored; margin capture shifts toward specialty clinics.
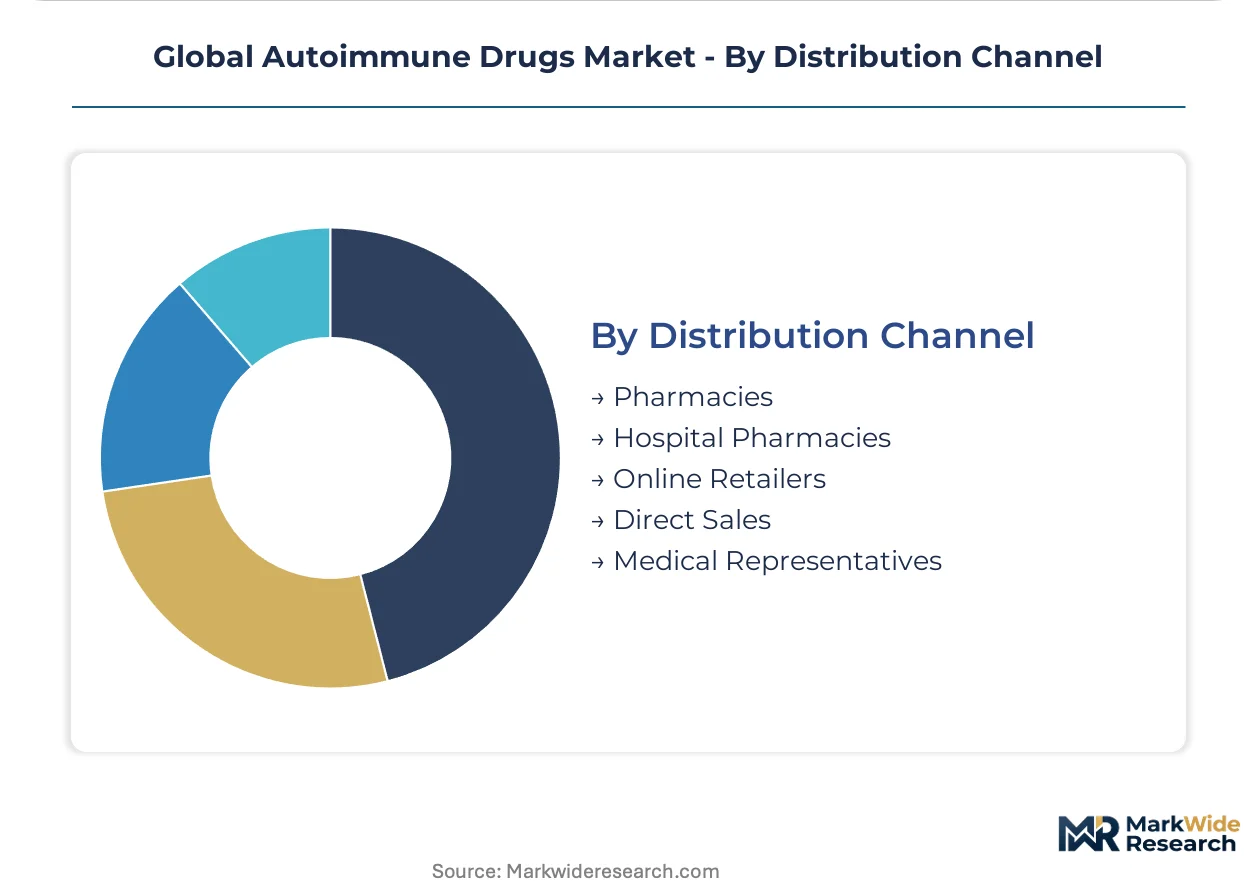
Distribution Channel:
Channel selection reflects cold-chain integrity requirements, patient education burden, and payer pharmacy benefit design.
- Hospital Pharmacies:Captive distribution within integrated delivery networks controls formulary compliance and 340B pricing leverage. United States health systems with substantial 340B program participation use hospital pharmacy ownership to subsidize uncompensated care through biologic margin capture.
- Specialty Pharmacies:Direct-to-patient shipment with adherence monitoring and prior authorization management; fastest-expanding channel for subcutaneous auto-injector formulations in United Kingdom and Netherlands where home administration protocols reduce site-of-care costs.
- Retail Pharmacies:Limited to oral small molecules with ambient storage; Walgreens and CVS chains compete on JAK inhibitor co-pay assistance program integration.
- Online Retailers:Emerging in Indian and Brazilian markets where private insurance expansion outpaces brick-and-mortar specialty pharmacy infrastructure.
- Direct Sales:Manufacturer field forces detailing to academic prescribers for novel mechanism launches; concentrated in Japan and Switzerland where key opinion leader relationships determine formulary adoption speed.
Biologic volume flows through hospital pharmacies; oral agent growth tilts toward specialty pharmacy direct distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Japan concentrate autoimmune drug demand through reimbursement frameworks that favor high-cost biologic maintenance therapy. Specialty clinic chains in Texas, Florida, and North Carolina metropolitan corridors exploit certificate-of-need restrictions to capture infusion revenue from hospital systems.
United States
Medicare Part D formularies and commercial pharmacy benefit designs allocate disproportionate budgets to rheumatoid arthritis and inflammatory bowel disease biologics. The FDA's accelerated approval pathway permits revenue recognition on surrogate endpoints, compressing Phase III-to-commercial timelines for novel monoclonal antibodies. Boston and San Francisco talent clusters concentrate mammalian cell line development expertise and biosimilar analytical characterization capabilities.
Germany
Statutory health insurance funds maintain deep reimbursement for functional status preservation metrics in chronic autoimmune conditions. EMA joint clinical assessment procedures create centralized pricing benchmarks that compress indication-specific commercial viability across member states. The Rhine-Ruhr and Munich metropolitan regions host concentrated biologic manufacturing infrastructure and hospital pharmacy networks that resist biosimilar switching without head-to-head trial data.
Japan
PMDA sakigake designation accelerates domestic review timelines for lupus erythematosus and inflammatory bowel disease biologics addressing unmet need. Tokyo and Osaka academic medical centers anchor prescriber specialization in targeted immunomodulation. The Kanto region concentrates infusion capacity within dermatology and gastroenterology practices that favor maintenance dosing protocols.
India
Private insurance expansion in tier-1 and tier-2 cities is lifting biologic access beyond traditional cash-pay constraints. CDSCO fast-track approval for biologics addressing unmet autoimmune need creates first-mover positioning in an underpenetrated market. Maharashtra and Karnataka metropolitan corridors exhibit the most aggressive specialty pharmacy infrastructure investment.
Switzerland
Swissmedic regulatory efficiency and proximity to Basel-based contract manufacturing organizations attract mid-tier biopharma development programs. The country's diagnostic precision infrastructure supports targeted therapy selection in lupus erythematosus where biomarker stratification determines reimbursement. Geneva and Zurich academic networks anchor key opinion leader relationships that accelerate formulary adoption.
Global Autoimmune Drugs Market Competitive Landscape
United States producers anchor one tier; Swiss and German specialists hold differentiated positions in biologic manufacturing scale and precision diagnostics. The market structure concentrates around integrated immunology portfolios, patient support service ecosystems, and manufacturing scale advantages. Three archetypes dominate: originator biologic developers with patent-protected monoclonal antibodies, diversified pharmaceutical conglomerates with cross-therapeutic manufacturing infrastructure, and emerging biosimilar specialists with analytical characterization capabilities. Competitive moves center on subcutaneous formulation migration and specialty clinic chain partnerships that lock in site-of-care revenue.
Among US-based developers, AbbVie Inc., Johnson & Johnson, and Pfizer Inc. occupy positions that exemplify distinct strategic archetypes within the competitive landscape. AbbVie Inc. represents the immunology portfolio depth model, anchoring physician loyalty across dermatology and gastroenterology practices through concentrated therapeutic focus. Johnson & Johnson exemplifies the integrated patient support ecosystem approach, sustaining adherence rates through service infrastructure rather than product differentiation alone. Pfizer Inc. sits within the manufacturing scale tier, controlling supply security for global monoclonal antibody distribution through validated cold-chain networks.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Pfizer Inc. |
| Roche Holding AG |
| Novartis AG |
| Amgen Inc. |
| Eli Lilly and Company |
| Bristol-Myers Squibb Company |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
EMA good manufacturing practice audit reciprocity gates qualified supply access and premium-tier pricing eligibility for European market entry. Contract manufacturing organizations without centralized inspection history face extended qualification delays that disqualify them from originator biologic supply agreements, concentrating pricing power among validated facility networks.
Pricing Analysis
Volume concentrates in tumor necrosis factor inhibitor originators while margin capture tilts toward oral Janus kinase inhibitors and subcutaneous auto-injector formulations. Price differentiation rests on patent protection runway and cold-chain infrastructure requirements, with infusion-based biologics commanding administration fee premiums in hospital outpatient settings. Cost compression in European tender procurement is intensifying as biosimilar switching incentives erode originator pricing power. Hospital systems exhibit highest price sensitivity due to formulary budget constraints, while specialty clinic chains demonstrate lowest sensitivity through biosimilar margin capture mechanisms.
Supply Chain Analysis
Single-source vulnerability sits with plasma-derived immunoglobulin and albumin feedstock networks concentrated in United States and European collection infrastructure. Mammalian cell line development expertise draws from Boston, Basel, and Singapore talent clusters, constraining contract manufacturing organization capacity expansion timelines. Tariff exposure runs through Chinese-sourced single-use bioreactor components and Indian active pharmaceutical ingredient intermediates. Distribution runs through validated cold-chain networks anchored in hospital pharmacy ownership and specialty pharmacy direct-to-patient shipment with temperature excursion tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mammalian expression system talent scarcity props pricing for qualified biologic manufacturing capacity, creating supply-constrained market dynamics that favor incumbents with validated facility networks.
For Market Incumbents: To counter biosimilar tender procurement erosion, anchor formulary loyalty through subcutaneous formulation migration and auto-injector device platform investments that lock in site-of-care revenue. Deepen backward integration into plasma collection networks to secure immunoglobulin feedstock supply against donor recruitment cyclicality. For New Entrants and Emerging Players: Launch via specialty pharmacy direct-to-patient distribution in Indian tier-2 metropolitan corridors where private insurance expansion outpaces brick-and-mortar infrastructure. Target lupus erythematosus biologics with CDSCO fast-track positioning to exploit unmet need and first-mover pricing before originator entry. For Investors and Strategic Acquirers: FDA accelerated approval pathway expansion for breakthrough therapy designation is the leading indicator that novel monoclonal antibody revenue recognition timelines will compress further. Long-term viability centers on acquiring contract development organizations with mammalian expression system capabilities and EMA inspection credentials in the Swiss or Massachusetts clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Migration | AbbVie and Johnson & Johnson auto-injector platforms reduce hospital dependency and capture administration fees. |
| Biosimilar Analytical Characterization Investment | Roche and Amgen capabilities in Boston and Basel clusters accelerate European tender procurement eligibility. |
| Specialty Clinic Chain Partnership | Pfizer and Eli Lilly alliances in Texas and Florida corridors lock in site-of-care revenue against hospital systems. |
| Plasma Collection Network Integration | Grifols and CSL Behring upstream control over US and European donor bases secures immunoglobulin cost structures. |
| Companion Diagnostic Convergence | Novartis and Bristol-Myers Squibb precision patient selection preserves reimbursement in crowded rheumatology categories. |
Research Methodology
Independent corroboration across drug development executives, formulary directors, hospital procurement managers, and payer access specialists underwrites the qualitative findings. Primary interviews with regulatory affairs leads and specialty pharmacy operations heads combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored the market sizing across the projection horizon.
Comparable-period anchoring to historical biologic launch trajectories and biosimilar erosion curves shaped the forecast window. The analytical framework segmented by product type, indication, end user, and distribution channel throughout the forecast period, with treatment line and regional regulatory cluster as additional dimensions. CAGRs derived from patent expiry schedules, biosimilar entry assumptions, and subcutaneous formulation adoption curves, incorporating immunology portfolio depth and manufacturing scale as forecast inputs.
Regulatory approval delays, biosimilar tender procurement acceleration, and plasma-derived input supply disruptions are the dominant revision risks to the modeling assumptions. Forecasts reflect documented assumptions about reimbursement framework stability and cold-chain infrastructure investment trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market