
 US Residential and Commercial Roofing Materials Market | 2026-2036
US Residential and Commercial Roofing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential and Commercial Roofing Materials Market Insights
Commercial building owners is rotating toward high-performance roofing systems as lifecycle cost analysis displaces first-cost procurement. Owens Corning leverages its fiberglass mat supply chain to dominate asphalt shingle distribution. GAF sustains brand pull through contractor certification programs. Elevate anchors its position in thermoplastic polyolefin membranes for flat commercial applications.
US residential and commercial roofing materials encompass protective envelope systems installed on sloped and flat structures, typically composed of asphalt-impregnated fiberglass mats, coated steel coils, or extruded polymer membranes engineered to achieve wind ratings up to 150 mph and thermal emissivity below 0.75. These assemblies shield structural substrates from moisture intrusion, UV degradation, and thermal cycling while supporting HVAC efficiency targets. Asphalt shingles retain the largest installed base though metal roofing captures the fastest growth trajectory as standing-seam profiles penetrate residential retrofit channels. Tile roofing commands premium positioning in coastal and Mediterranean-style submarkets where clay and concrete products satisfy aesthetic and durability requirements. Polymer-based materials concentrate margin pools in commercial retrofitting applications where single-ply membranes reduce labor intensity and extend service intervals.
The EPA Energy Star program and California Title 24 building standards enforce minimum solar reflectance thresholds that disqualify conventional dark-pigmented materials from compliance pathways in major metropolitan zones. OSHA fall protection mandates elevate contractor training costs and reshape installation crew composition across state licensing regimes. Stakeholders must monitor evolving municipal electrification ordinances that integrate rooftop solar readiness into new construction specifications.
Market Dynamics
California Title 24 building codes and EPA cool roof standards are compressing specification freedom for dark-pigmented materials, forcing manufacturers to reformulate coatings and substrates while Sun Belt climate stress accelerates replacement velocity across the installed base.
Growth Catalysts
- Energy-efficient membrane systems:Commercial property developers in Texas and Florida prioritize thermoplastic polyolefin membranes that reduce HVAC loads and satisfy utility rebate programs.
- OSHA fall protection mandates:Enhanced contractor training requirements elevate barrier-to-entry for installation crews, consolidating demand toward certified national contractors with compliance infrastructure.
- Sun Belt climate stress:Accelerated thermal cycling and hail damage in Arizona, Nevada, and New Mexico compress roof replacement cycles from twenty-year intervals toward twelve-year averages.
Market Restraints
- Petroleum-based asphalt volatility:Shingle manufacturers face margin compression when crude oil feedstock prices spike, with limited pass-through elasticity in residential retrofit channels.
- Polymer membrane supply concentration:Thermoplastic polyolefin resin production clusters along Gulf Coast petrochemical corridors, exposing membrane fabricators to hurricane-related supply interruptions.
- Dark-pigment regulatory disqualification:EPA Energy Star solar reflectance thresholds above 0.25 eliminate conventional black shingles from compliance pathways in Los Angeles, San Diego, and Phoenix metropolitan zones.
Strategic Opportunities
- Solar-ready roofing integration:Municipal electrification ordinances in San Jose, Austin, and Denver mandate structural load capacity and electrical conduit pre-installation for future photovoltaic attachment.
- Metal roofing retrofit penetration:Standing-seam profiles capture share in residential channels as homeowners in hurricane-prone Southeast states prioritize wind ratings above 140 mph.
- Building-integrated photovoltaics convergence:Tesla Solar Roof and competing thin-film technologies merge energy generation with waterproofing function, creating premium positioning in California new construction.
Industry Challenges
- Skilled installer scarcity:Complex membrane welding and standing-seam metal fabrication require specialized crews that training programs in Texas and Florida cannot replenish at replacement-cycle velocity.
- Multi-jurisdiction compliance fragmentation:Contractors operating across state lines must maintain separate OSHA fall protection certifications, California Title 24 documentation, and municipal solar-ready permitting workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential and Commercial Roofing Materials Market |
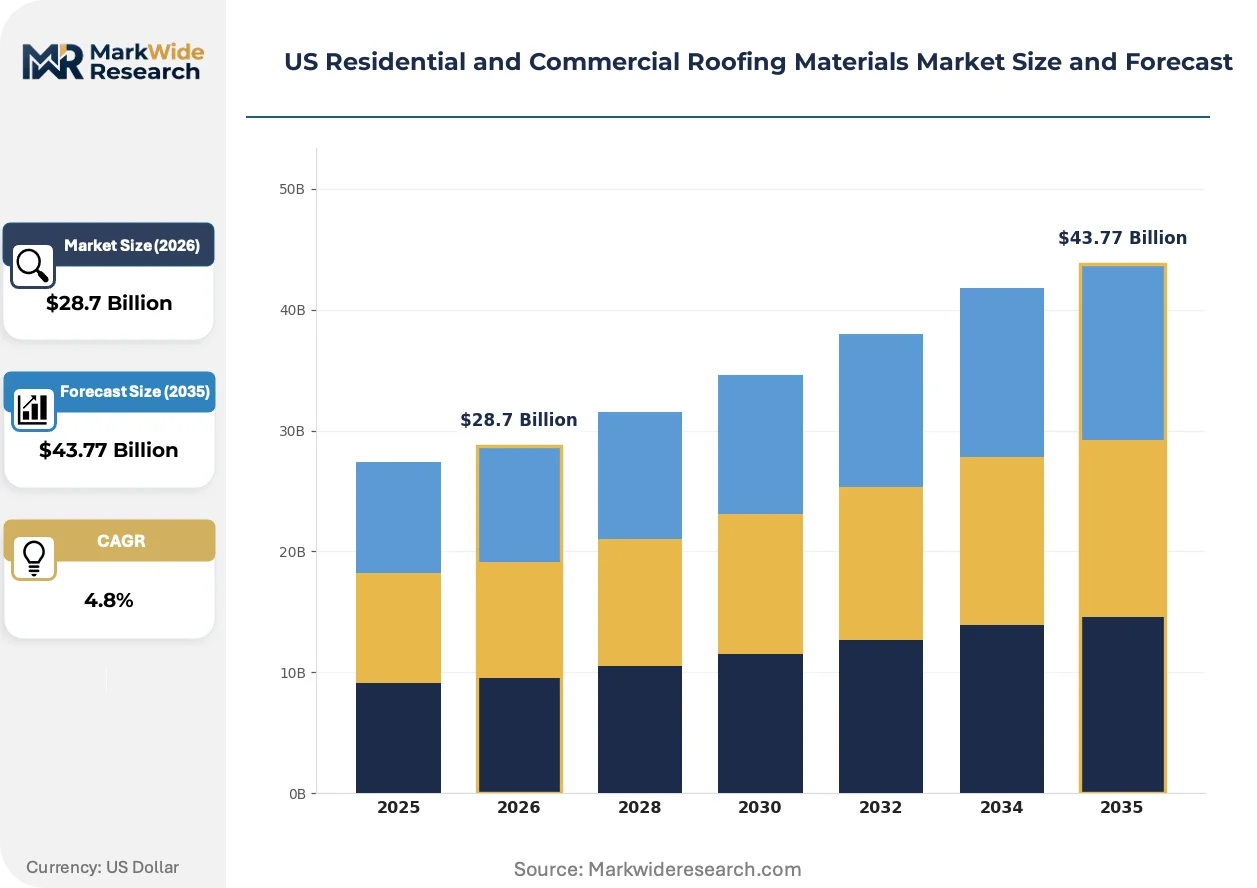
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asphalt Shingles, Metal Roofing, Tile Roofing, Slate Roofing Installation Method: New Construction, Roof Replacement, Repair, Retrofitting Material: Fiberglass, Steel, Aluminum, Polymer End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Municipal Structures |
| Companies Covered | Atlas Roofing Corporation, Elevate, Owens Corning, MBCI, McElroy Metal, CERTAINTEED, IKO Industries Ltd., CENTRIA, GAF, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential and Commercial Roofing Materials Market Trends and Innovations
Material science advances and regulatory stringency are converging to fragment the specification landscape, with performance-rated assemblies displacing commodity categories and digital tools compressing the design-to-installation timeline.
Cool roof coatings with ceramic microsphere additives are decomposing the traditional tradeoff between solar reflectance and mechanical durability. Commercial facilities managers in Phoenix and Las Vegas specify these formulations to satisfy California Title 24 export compliance for satellite locations. The technology is decomposing asphalt shingle dominance in low-slope commercial retrofits by extending membrane service intervals beyond twenty-five years.
EPA Energy Star Version 3.1 criteria tighten thermal emissivity thresholds for steep-slope residential products effective 2025. Manufacturers must reformulate granule chemistry or forfeit eligibility in utility rebate territories spanning Sacramento, Austin, and Miami-Dade County. Shingle producers with in-house mineral coating capabilities capture specification priority while commodity competitors face portfolio obsolescence.
Lifecycle cost analysis displaces first-cost procurement in commercial owner-operator segments. Institutional buyers with ten-year hold periods now require energy modeling that quantifies HVAC savings against membrane premium pricing. This behavioral pivot concentrates volume with national contractors offering bundled design-build-finance packages, compressing regional distributor influence in Atlanta, Dallas, and Los Angeles metropolitan markets.
US Residential and Commercial Roofing Materials Market Segmentation
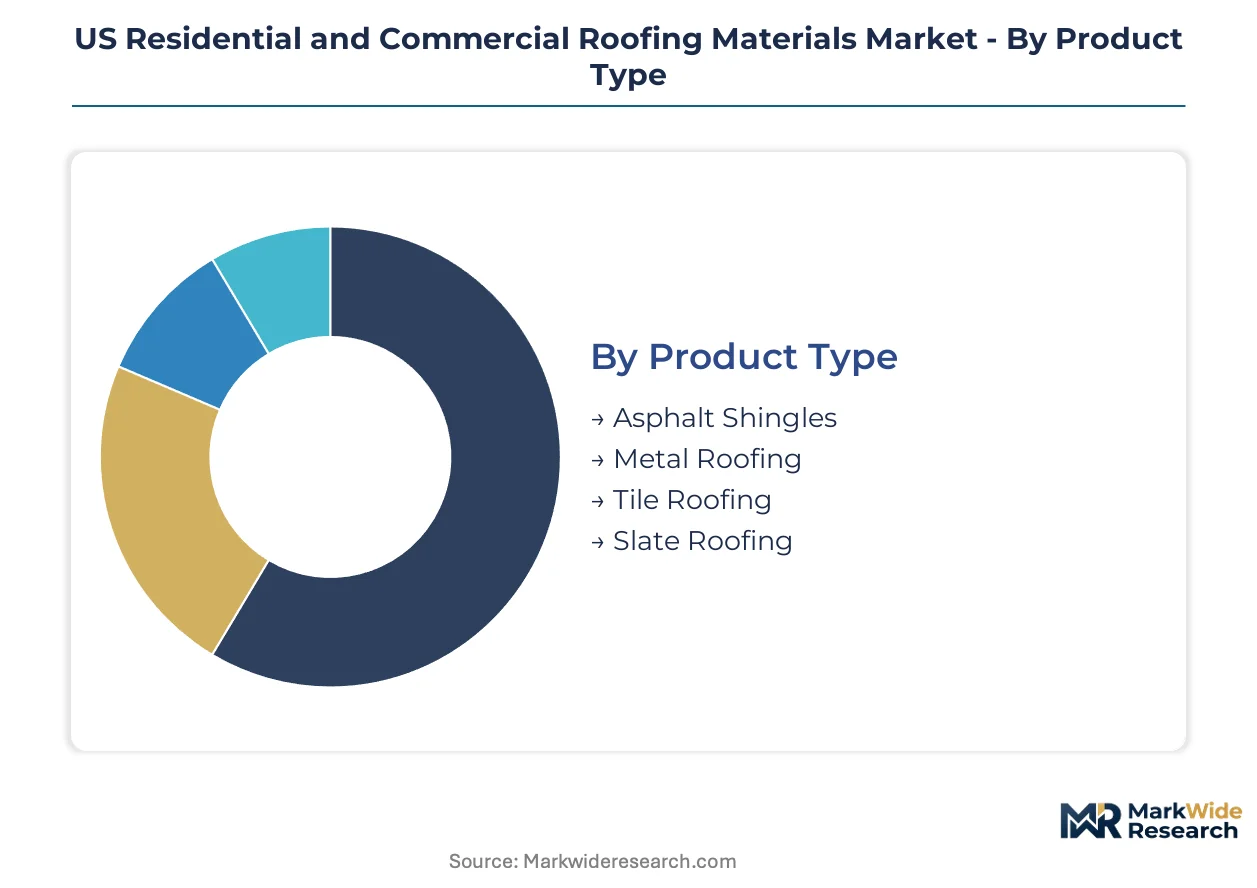
Material specification pathways in US roofing diverge sharply between residential retrofit channels and commercial new-build procurement. Channel concentration determines margin capture, with national distributors controlling asphalt shingle flows while specialized contractors dominate membrane and metal segments.
Product Type:
Asphalt shingles and metal roofing command distinct distribution infrastructures, with the former flowing through lumberyard networks and the latter requiring certified installer relationships.
- Asphalt Shingles:Fiberglass-reinforced mats saturated with asphalt and surfaced with mineral granules deliver wind ratings to 130 mph at economy price points. Demand concentrates in Midwest and Southeast residential retrofit channels where Owens Corning and GAF maintain shelf-space dominance through contractor loyalty programs.
- Metal Roofing:Standing-seam and modular panel systems fabricated from coated steel or aluminum achieve 150 mph wind ratings and 50-year service intervals. Florida and Texas coastal markets prioritize these specifications as insurance carriers mandate higher performance thresholds for hurricane-prone ZIP codes.
- Tile Roofing:Clay and concrete profiles satisfy aesthetic requirements in Mediterranean-style submarkets across California and Arizona. Weight constraints limit retrofit applicability to structures engineered for 10-12 psf dead loads.
- Slate Roofing:Natural stone quarried in Vermont and Pennsylvania commands premium positioning in historic preservation and luxury residential segments. Labor intensity and structural requirements restrict volume to sub-2% of residential installations.
By volume, asphalt shingles leads. By growth pace, metal roofing is ahead.
Installation Method:
Procurement patterns separate new construction—where builders optimize first-cost— from replacement cycles where lifecycle economics and insurance mandates reshape material selection.
- New Construction:Production homebuilders in Texas and Florida specify commodity asphalt shingles through national distributor contracts, prioritizing schedule certainty over performance tiering. California Title 24 compliance drives cool-roof membrane specification in commercial ground-up development.
- Roof Replacement:Insurance claim volume in hail-prone Colorado and Minnesota accelerates asphalt shingle turnover, with carriers steering policyholders toward impact-resistant Class 4 products. Residential replacement cycles compress from 20-year intervals toward 12-year averages in Sun Belt states.
- Repair:Storm damage response generates spot demand for matching shingles and membrane patches. Contractor backlogs in Houston and Phoenix extend lead times for repair work to 8-14 weeks during peak season.
- Retrofitting:Commercial facilities in Chicago and Atlanta deploy TPO membrane overlays to extend service intervals without full tear-off. Solar-ready structural assessments now accompany 40% of commercial retrofit specifications in municipal electrification jurisdictions.
Replacement work generates the highest absolute volume. Retrofitting commands the steepest margin expansion trajectory.
Material:
Feedstock geography and tariff exposure differentiate margin stability across substrate categories, with domestic fiberglass supply insulating against resin price volatility.
- Fiberglass:Owens Corning's vertically integrated mat production anchors asphalt shingle supply chains, with Corpus Christi and Newark manufacturing hubs serving regional distribution networks. E-glass formulations achieve 30-year warranties through oxidation-resistant binder chemistry.
- Steel:Galvalume-coated coils from Nucor and Steel Dynamics fabricators supply standing-seam and corrugated profiles. Section 232 tariff exposure on imported substrate compresses margins when domestic mill capacity tightens.
- Aluminum:Lightweight coil stock from Alcoa and Novelis facilities enables coastal applications where salt corrosion accelerates steel degradation. Premium pricing reflects energy-intensive smelting costs and scrap recovery value.
- Polymer:Thermoplastic polyolefin and PVC resins concentrate along Gulf Coast petrochemical corridors, exposing membrane fabricators to hurricane-related supply interruptions. TPO formulations now dominate commercial low-slope specification in California and Texas.
Fiberglass substrates command the largest installed base. Polymer membranes are climbing the fastest in commercial specification share.
End User:
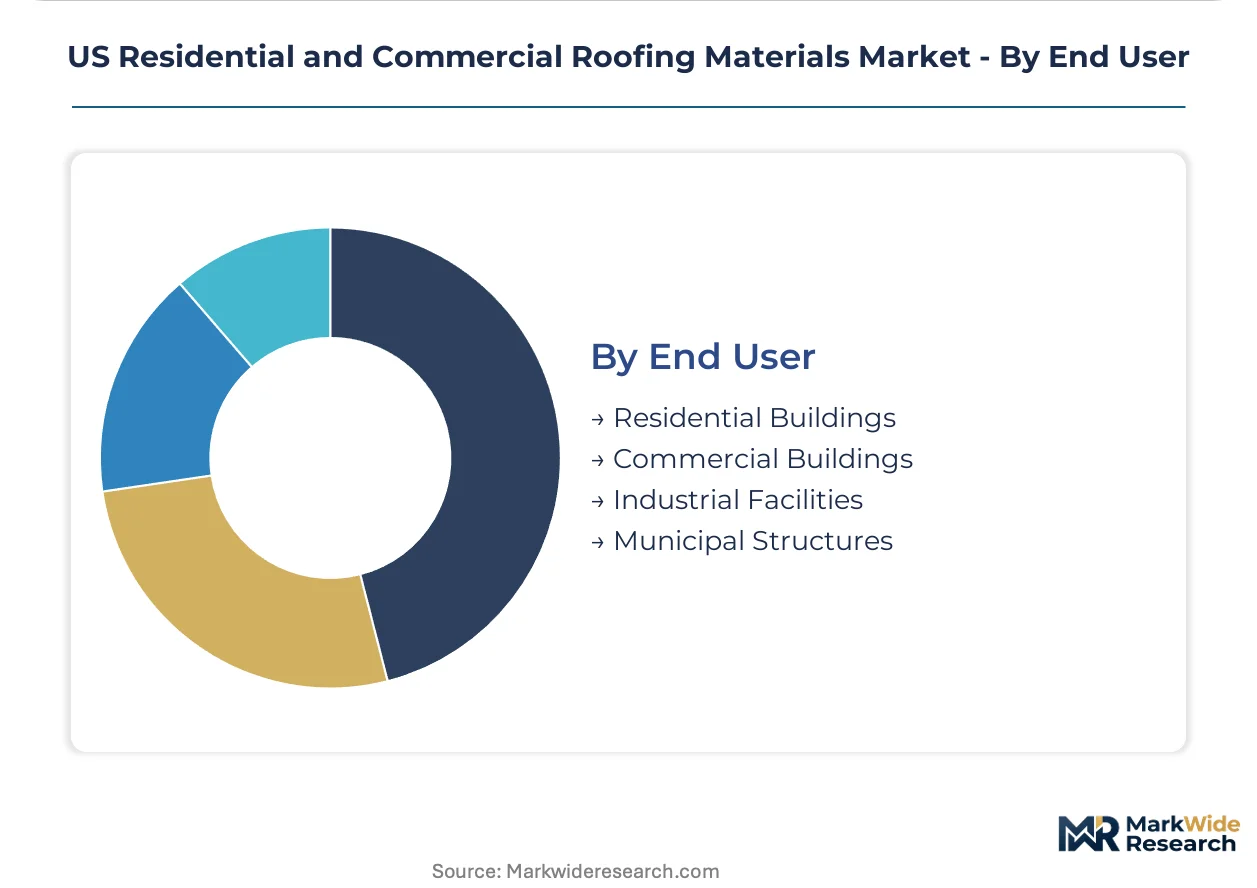
Customer type determines specification complexity, with institutional buyers demanding energy modeling and warranty bundling that commodity residential channels cannot support.
- Residential Buildings:Single-family and multifamily owners in Sun Belt states prioritize wind and impact ratings as insurance underwriting tightens. HOA aesthetic guidelines in Arizona and Florida submarkets restrict color and profile selection.
- Commercial Buildings:Office and retail property managers in Dallas and Los Angeles specify cool-roof membranes to satisfy California Title 24 export compliance and utility rebate thresholds. Lifecycle cost analysis now dominates procurement decisions for assets with 10-year hold periods.
- Industrial Facilities:Manufacturing plants and warehouses in Ohio and Pennsylvania deploy standing-seam metal for structural load-bearing integration and thermal expansion tolerance. Chemical resistance requirements favor fluoropolymer coatings in aggressive environments.
- Municipal Structures:School districts and government buildings in Denver and Austin face solar-ready mandates that pre-install electrical conduit and structural capacity for future photovoltaic attachment. Prevailing wage requirements elevate installed costs 15-25% above private-sector equivalents.
Residential channels generate the highest unit volume. Commercial specification is gaining share fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor and its pipeline networks supply resin feedstocks that anchor membrane production capacity. Interstate highway distribution grids connect manufacturing clusters in Texas, Ohio, and Georgia to Sun Belt demand centers. Regional specification divergence intensifies as California export codes reshape procurement in neighboring states.
Texas
Hurricane exposure and hail frequency drive demand for impact-resistant Class 4 shingles and standing-seam metal in Houston and Dallas-Fort Worth. The Texas Department of Insurance mandates windstorm certification for coastal counties, compressing contractor eligibility. Petrochemical complexes along the Houston Ship Channel supply TPO resin to membrane fabricators serving commercial retrofit markets.
California
California Title 24 building codes enforce cool-roof solar reflectance thresholds that disqualify conventional dark-pigmented materials from Los Angeles and San Diego metropolitan zones. The California Energy Commission updates thermal emissivity standards effective 2025, forcing granule reformulation. Silicon Valley electrification ordinances in San Jose mandate solar-ready structural pre-installation for new commercial construction.
Florida
Miami-Dade County's HVHZ wind codes require missile-impact testing for all roofing products, elevating specification barriers for residential retrofit channels. Insurance carriers in Tampa and Orlando steer policyholders toward metal roofing with 150 mph ratings. The Florida Building Commission coordinates adoption of ASCE 7 wind load standards across Panhandle to Keys jurisdictions.
Arizona
Thermal cycling stress in Phoenix and Tucson compresses asphalt shingle service intervals toward twelve-year averages, accelerating replacement velocity. EPA Energy Star rebate programs administered through Salt River Project and Arizona Public Service favor cool-roof membranes with thermal emissivity below 0.75. Clay tile dominates Scottsdale and Paradise Valley submarkets where HOA aesthetic guidelines restrict profile selection.
Colorado
Hail damage claims in Denver and Colorado Springs drive asphalt shingle turnover through insurance-mandated replacement cycles. Front Range municipalities including Boulder and Fort Collins adopt solar-ready ordinances requiring electrical conduit pre-installation. The Colorado Energy Office administers rebates for cool-roof commercial retrofits meeting California Title 24 export compliance thresholds.
US Residential and Commercial Roofing Materials Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and contractor loyalty programs. The market structures around three tiers: integrated fiberglass mat producers commanding asphalt shingle distribution, membrane specialists anchoring commercial flat-roof specification, and metal fabricators penetrating hurricane-prone coastal markets. Competitive moves concentrate on backward integration into resin and mineral supply, plus geographic expansion through certified installer network density.
Among integrated manufacturers, Owens Corning and GAF exemplify archetypes of captive supply chain control and contractor certification dominance respectively. Elevate occupies a position within the membrane specialist tier, representing the shift toward thermoplastic polyolefin specification in commercial retrofit channels. These three anchors illustrate how raw material access, installation certification, and product performance tiering define competitive positioning across residential and commercial segments.
| Leading Market Players |
|---|
| Atlas Roofing Corporation |
| Elevate |
| Owens Corning |
| MBCI |
| McElroy Metal |
| CERTAINTEED |
| IKO Industries Ltd. |
| CENTRIA |
| GAF |
| Others |
Pricing and Supply Chain Analysis
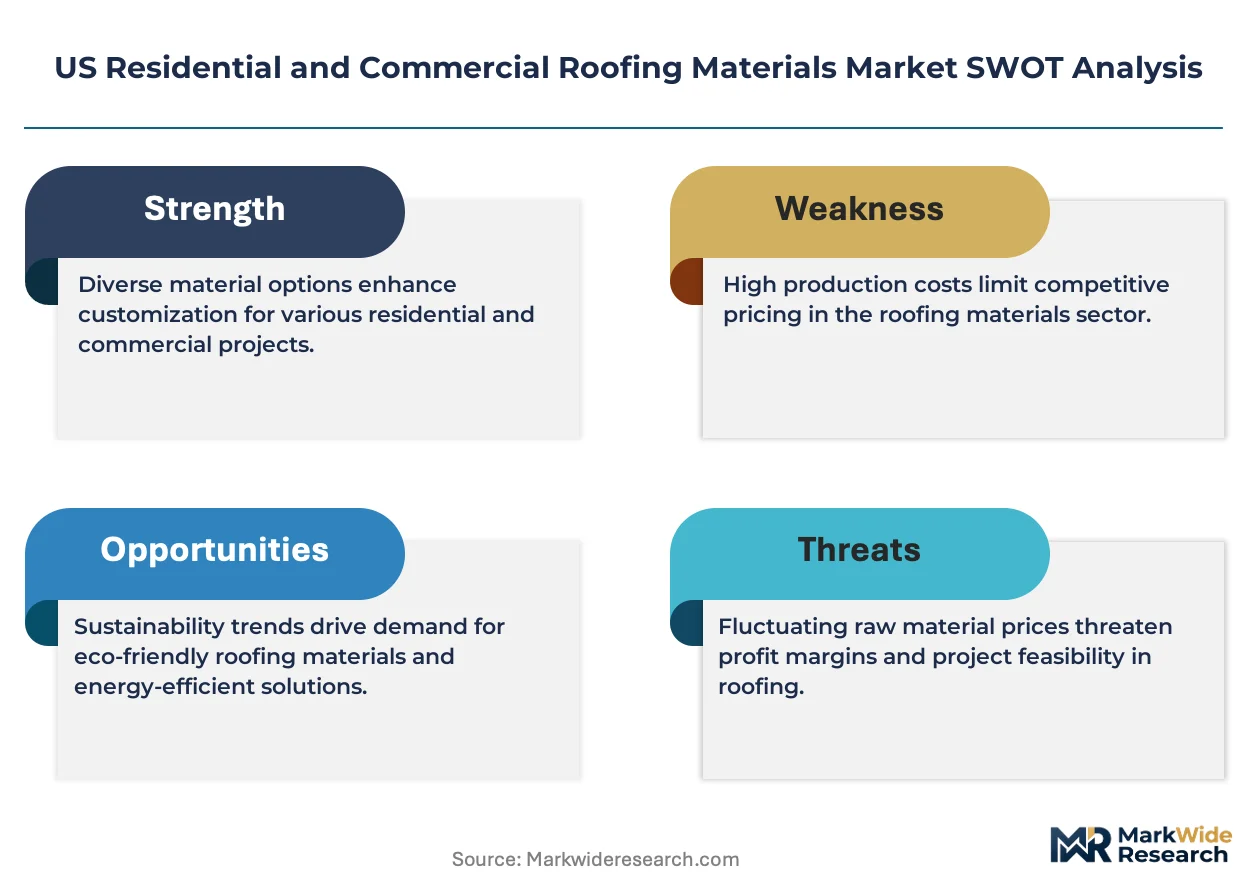
Thermoplastic polyolefin membrane substitution for built-up asphalt roofing simultaneously redistributes supply chain gravity toward Gulf Coast petrochemical corridors and compresses installed-cost premiums in commercial retrofit channels. This displacement dynamic concentrates pricing power among resin-integrated fabricators while fragmenting bargaining leverage for regional distributors dependent on commodity shingle flows.
Pricing Analysis
Volume-discount tiering structures stratify across national account, regional contractor, and spot-buyer segments. Owens Corning and GAF extract premium positioning through certified installer network density and warranty bundling, while commodity competitors compete on freight-adjusted unit economics in lumberyard channels. Pricing pressure intensifies in residential retrofit segments where insurance carriers steer policyholders toward impact-resistant Class 4 products with limited pass-through elasticity. Production homebuilders exhibit highest price sensitivity through first-cost procurement mandates, whereas institutional commercial buyers prioritize lifecycle cost modeling over initial outlay.
Supply Chain Analysis
Houston Ship Channel resin production anchors thermoplastic polyolefin membrane supply, with Corpus Christi and Lake Charles petrochemical complexes feeding fabricators in Texas and Georgia. Gulf Coast hurricane exposure creates single-source vulnerability for polymer-dependent commercial roofing contractors. Raw material flows draw from domestic fiberglass mat production in Ohio and Newark, Galvalume-coated steel from Nucor and Steel Dynamics mills, and ceramic granule supply from Minnesota mining operations. Distribution runs through national distributor networks for asphalt shingles and certified contractor direct relationships for membrane and metal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where California Title 24 compliance infrastructure and Miami-Dade HVHZ certification create switching costs that cement incumbent positioning against commodity challengers.
For Market Incumbents: Compound certification advantage by deepening California Title 24 documentation capabilities and expanding solar-ready structural assessment bundling in municipal electrification jurisdictions. Elevate barrier-to-entry through proprietary granule chemistry investments that satisfy EPA Energy Star Version 3.1 thermal emissivity thresholds. Prioritize captive resin supply agreements along Gulf Coast corridors to isolate membrane fabrication from hurricane-related interruption.
For New Entrants and Emerging Players: Complex membrane welding training capacity scarcity in Texas and Florida opens white-space for specialized contractor certification programs targeting TPO installation crews. Target commercial retrofit specification in Colorado and Arizona where cool-roof rebate administration creates demand for energy modeling services that national distributors under-serve. Pursue solar-ready structural assessment partnerships with municipal building departments in Denver, Austin, and San Jose as the go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated membrane specialists with captive Gulf Coast resin access and California Title 24 compliance documentation infrastructure. Long-term viability hinges on regulatory stringency persistence across Sun Belt states and solar-ready mandate expansion into secondary metropolitan markets. Monitor EPA Energy Star criteria tightening and OSHA fall protection mandate enforcement intensity as inflection indicators for consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Gulf Coast petrochemical corridor access insulates membrane fabricators from hurricane-related feedstock interruption. |
| Certified Installer Network Expansion | OSHA fall protection compliance infrastructure consolidates demand toward national contractors with training scale. |
| Solar-Ready Structural Assessment Bundling | Municipal electrification ordinances in San Jose, Austin, and Denver mandate photovoltaic pre-installation capacity. |
| Cool-Roof Granule Chemistry Reformulation | EPA Energy Star Version 3.1 thermal emissivity thresholds force portfolio obsolescence for commodity competitors. |
| Commercial Retrofit Design-Build-Finance Packaging | Lifecycle cost analysis displaces first-cost procurement in institutional buyer segments across Dallas and Los Angeles. |
Research Methodology
A spread of perspectives from roofing contractor operations managers, commercial facilities directors, building code officials in California and Florida, national distributor procurement leads, and polymer resin supply planners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through California Energy Commission Title 24 documentation, EPA Energy Star product listings, OSHA compliance enforcement records, and SEC filings from publicly traded building materials manufacturers. Bottom-up volume triangulation across product type, installation method, and end-user segments was cross-checked against top-down construction spending and replacement-cycle velocity estimates.
Segmentation dimensions modeled encompass material substrate, installation channel, end-user category, and regional regulatory cluster across the projection horizon. Analytical frameworks derived CAGRs through replacement-cycle compression analysis in Sun Belt states, cool-roof mandate adoption curves, and membrane penetration rates in commercial retrofit channels. Industry-specific forecast inputs incorporated insurance carrier impact-resistant product steering intensity and municipal solar-ready ordinance proliferation patterns.
Forecasts assume regulatory continuity in EPA Energy Star enforcement, California Title 24 building code stringency, and OSHA fall protection mandate administration; material policy shifts would require re-modeling across compliance-driven specification pathways. Supply interruption scenarios from Gulf Coast hurricane exposure and petroleum feedstock volatility represent specific risk factors that could compress margins or accelerate substitution dynamics. Practitioners should keep alternative scenarios live as municipal electrification ordinance adoption and insurance underwriting criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Global Steel Pipe Piles Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Foldable Container House Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Concrete Repair Product Market