
 Waterproofing Systems Market | 2026-2036
Waterproofing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproofing Systems Market Outlook
China's polymer-modified bitumen capacity build-out is rewriting regional supply economics for membrane producers. Sika AG leverages its integrated mortar-to-membrane technology stack to capture specification-driven projects. BASF SE anchors its position through polyurethane liquid formulations that command premium positioning in complex geometries.
Waterproofing systems encompass engineered barriers—typically comprising modified bitumen, synthetic rubber, cementitious crystalline compounds, or bentonite clay—applied to structural substrates to prevent liquid water ingress while managing vapor transmission. These systems protect concrete and steel reinforcement from chloride-induced corrosion, hydrostatic pressure damage, and mold proliferation in below-grade and exposed applications. Liquid membranes lead specification value due to seamless monolithic coverage in irregular substrates, while sheet membranes dominate volume in large-scale roofing and tunnel projects where factory-controlled thickness ensures predictable performance. Cementitious systems occupy a mature, cost-sensitive niche in emerging market basement applications where application simplicity outweighs elastomeric recovery requirements.
REACH restrictions on polycyclic aromatic hydrocarbons in bitumen modifiers are elevating formulation costs for European manufacturers while creating compliance barriers for imported products. The EPA's stormwater management rules under the Clean Water Act are intensifying green roof and plaza deck specifications in US commercial construction. China's GB standards for underground engineering waterproofing are mandating multi-layer systems in rail and utility tunnel projects. Stakeholders must monitor how evolving embodied-carbon regulations for construction materials reshape polymer sourcing and recycled content thresholds across major building codes.
Market Dynamics
Multi-layer specification mandates in underground rail construction are compressing procurement cycles and elevating technical qualification barriers for membrane suppliers across Asia-Pacific infrastructure corridors.
Growth Catalysts
- Metro Rail Expansion:Underground construction in Indian cities is accelerating membrane specification for tunnel lining and station box structures. BIS certification requirements are tightening product qualification standards for imported systems.
- REACH PAH Restrictions:European polycyclic aromatic hydrocarbon limits on bitumen modifiers are forcing formulation upgrades that favor compliant domestic producers over non-compliant imports.
- Saline Soil Corrosion:Coastal megacities in China face accelerated waterproofing replacement cycles due to chloride-induced substrate degradation, creating recurring demand for high-performance membrane systems.
Market Restraints
- Polymer Feedstock Volatility:Styrene-butadiene and APP modifier costs fluctuate with crude oil derivatives, compressing margins for bitumen membrane manufacturers without captive petrochemical supply.
- Technical Limitation in Crystalline Systems:Cementitious crystalline waterproofing lacks elastomeric recovery under structural movement, restricting application to static basement environments and excluding dynamic joint conditions.
- Regional Supply Concentration:Polymer-modified bitumen capacity build-out in China is rewriting regional supply economics, marginalizing smaller membrane producers in Southeast Asia without scale advantages.
Strategic Opportunities
- Green Roof Specification:EPA stormwater management rules under the Clean Water Act are intensifying plaza deck and vegetated roof requirements in US commercial construction, opening specification value for liquid membrane systems.
- Recycled Content Integration:Evolving embodied-carbon regulations for construction materials across EU member states are creating competitive differentiation for membrane producers with verified recycled polymer feedstocks.
- Complex Geometry Applications:Liquid polyurethane formulations command premium positioning in irregular substrates where sheet membrane seaming creates failure risk, particularly in Middle Eastern podium structures.
Industry Challenges
- Applicator Certification Bottlenecks:Multi-layer system mandates in Chinese GB standards for underground engineering require specialized installation crews, creating capacity constraints during peak infrastructure construction windows.
- Cross-Border Compliance Complexity:Divergent national standards for membrane thickness, adhesion testing, and fire classification force manufacturers to maintain parallel product variants, inflating inventory and R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproofing Systems Market |
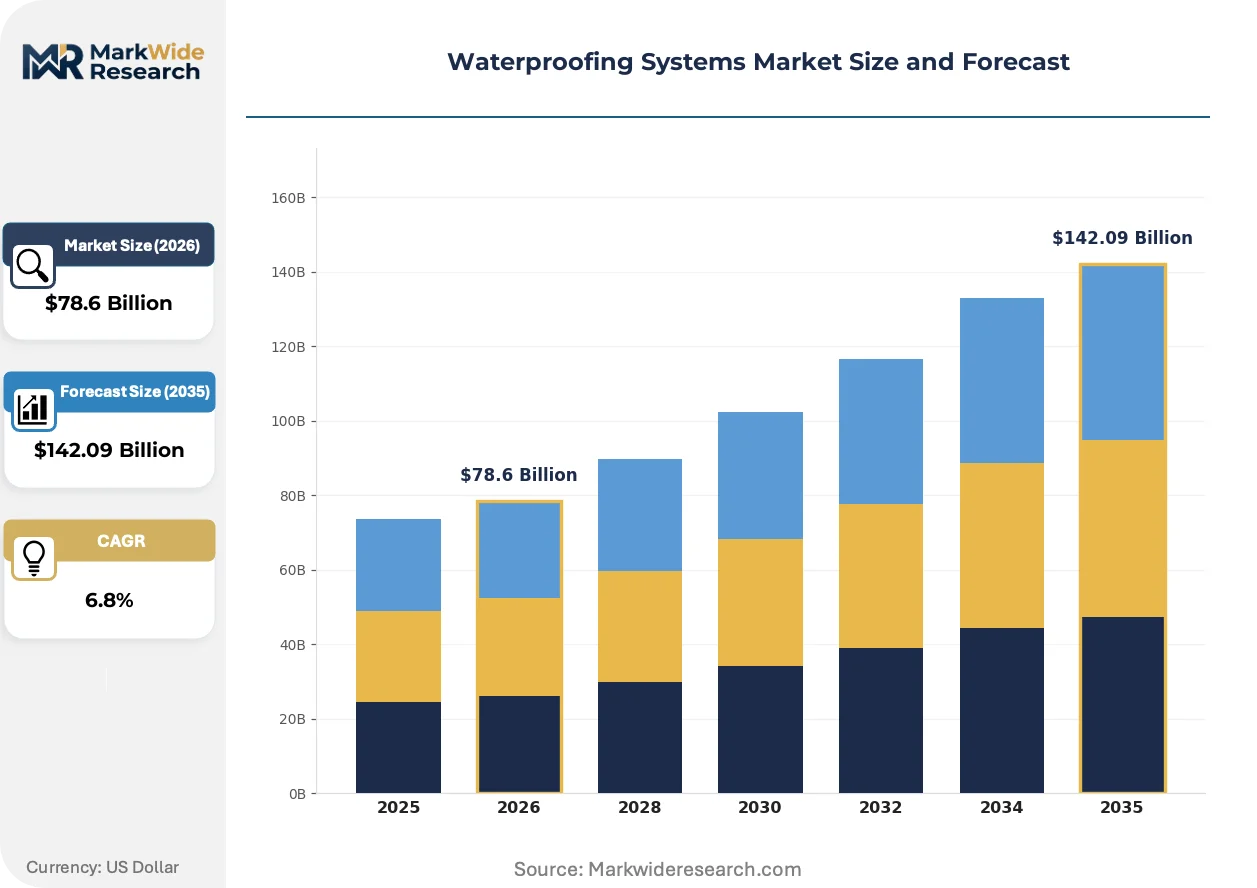
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Membranes, Sheet Membranes, Bentonite, Cementitious Application: Roofing, Basements, Bridge Decks, Tunnels End User: Construction, Automotive, Marine, Industrial Form: Roll, Liquid, Sheet, Coating |
| Companies Covered | Sika AG, BASF SE, Soprema Group, Carlisle Companies, Mapei S.p.A., Fosroc, Tremco Incorporated, GAF, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproofing Systems Market Strategic Shifts
Digital specification tools and predictive performance modeling are compressing traditional material selection cycles while elevating technical documentation requirements across membrane categories.
Self-healing polymer technologies are virtualizing maintenance planning for critical infrastructure owners. Japanese rail operators and Nordic tunnel authorities are piloting microcapsule-based bitumen modifiers that autonomously seal hairline cracks under thermal cycling. This capability is virtualizing the traditional inspection-to-repair workflow, compressing lifecycle cost models and reshaping warranty structures toward performance guarantees rather than material replacement.
China's GB standards for underground engineering waterproofing are mandating redundant membrane layers in rail and utility tunnel specifications. MEE enforcement of these multi-barrier requirements is disqualifying single-layer systems from state-funded infrastructure bids. Contractors are responding by pre-qualifying integrated membrane-and-drainage composite suppliers capable of warranting complete envelope performance.
Asset owner procurement teams are consolidating specification authority from project-level consultants to centralized technical standards departments. This concentration is displacing brand-agnostic engineer specifications with approved vendor lists in German and Dutch commercial construction. The shift is most visible in healthcare and data center verticals where facility operators demand single-source accountability for envelope performance across multi-year build programs.
Waterproofing Systems Market Segmentation
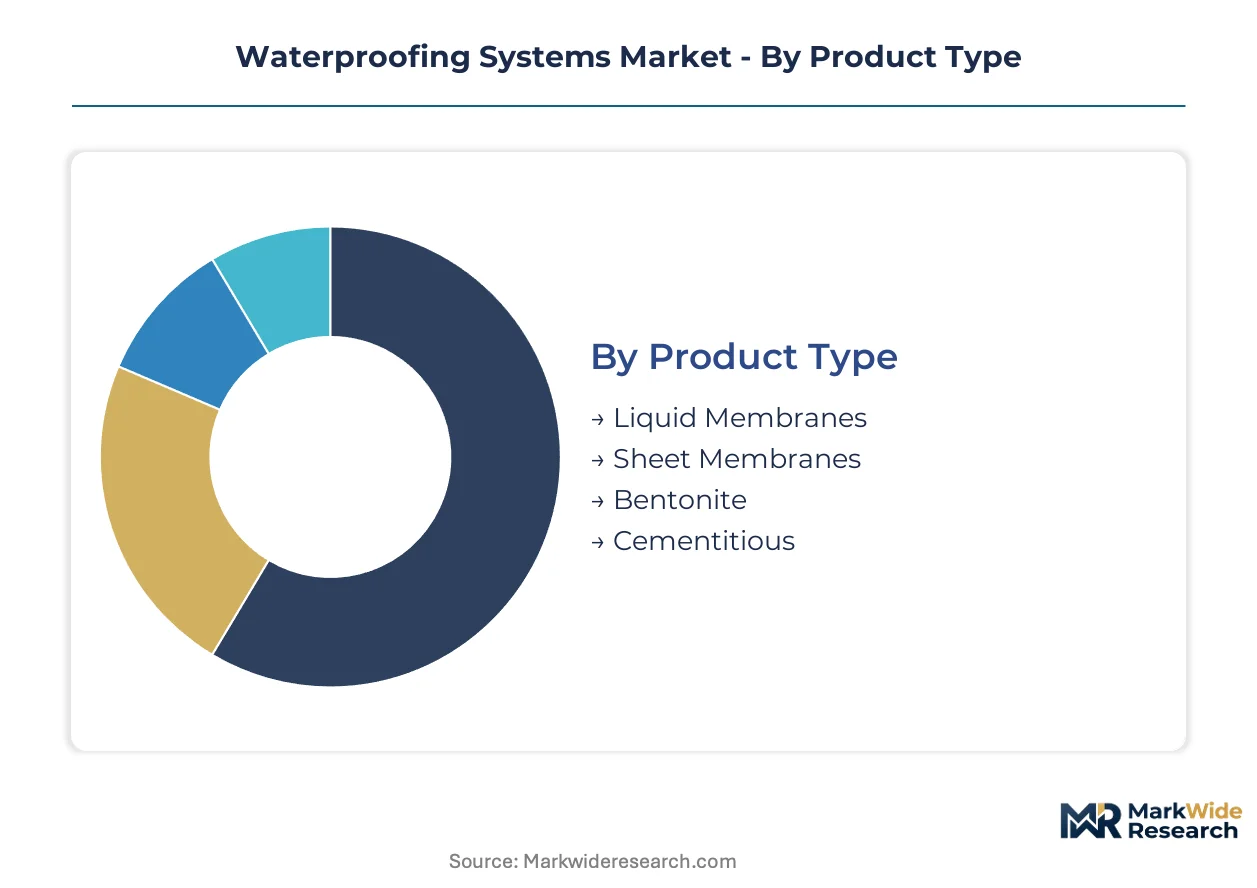
Waterproofing specification diverges sharply across structural applications, with membrane chemistry and installation geometry dictating performance thresholds. Procurement teams segment choices by substrate complexity, hydrostatic pressure exposure, and lifecycle cost models rather than upfront material expenditure alone.
Product Type:
Cost tier stratification separates premium seamless systems from commodity sheet alternatives, with formulation chemistry driving specification authority.
- Liquid Membranes:Polyurethane and hybrid polymer formulations cure into monolithic barriers without seams, eliminating failure points at penetrations and transitions. Demand concentrates in Middle Eastern podium structures and complex roof geometries where sheet seaming creates vulnerability, with premium positioning sustained by applicator certification requirements.
- Sheet Membranes:Factory-controlled thickness in modified bitumen and synthetic rubber rolls ensures predictable performance in high-volume tunnel and roofing deployments. China's GB standards for underground rail construction mandate multi-layer sheet systems, compressing procurement cycles toward pre-qualified integrated suppliers.
- Bentonite:Sodium bentonite clay systems swell upon hydration to seal construction joints in below-grade applications.
- Cementitious:Crystalline compounds penetrate concrete pores for static basement environments where elastomeric recovery is unnecessary.
Liquid Membranes commands the established base. The steepest expansion runs through Sheet Membranes.
Application:
Volume concentration tracks infrastructure investment cycles, with underground construction outpacing above-grade replacement demand.
- Roofing:Exposed membrane systems must balance UV resistance with thermal cycling durability across commercial and residential building stock. Green roof specifications under EPA stormwater rules are intensifying plaza deck requirements in US commercial construction, favoring liquid systems for drainage integration.
- Tunnels:Hydrostatic pressure and groundwater chemistry impose the most severe performance demands on membrane specification. Indian metro rail expansion and Chinese rail utility projects are accelerating membrane adoption for tunnel lining and station box structures with redundant barrier mandates.
- Basements:Below-grade waterproofing addresses soil moisture and vapor transmission in residential and commercial foundations.
- Bridge Decks:Traffic-bearing waterproofing protects structural concrete from chloride ingress and freeze-thaw degradation.
Roofing retains volume leadership. Tunnels delivers the fastest share gains.
End User:
Customer type determines specification authority, with infrastructure agencies consolidating procurement standards away from project-level consultants.
- Construction:Building envelope specification spans residential, commercial, and civil infrastructure with divergent performance thresholds. Asset owners in German and Dutch healthcare and data center verticals are centralizing technical standards departments, displacing brand-agnostic engineer specifications with approved vendor lists.
- Industrial:Chemical processing and power generation facilities demand corrosion-resistant barriers for containment structures and secondary containment. REACH PAH restrictions on bitumen modifiers are elevating formulation costs while creating compliance barriers for non-European suppliers.
- Automotive:Manufacturing facilities and battery assembly plants require cleanroom-compatible envelope systems.
- Marine:Shipbuilding and port infrastructure face saltwater corrosion acceleration of substrate degradation.
Construction anchors established demand. Industrial shows the steepest specification value climb.
Form:
Supply chain configuration determines geographic sourcing patterns, with roll and liquid formats dominating distinct regional production clusters.
- Liquid:Site-mixed or factory-blended fluid application enables seamless coverage of irregular substrates without factory fabrication constraints. Complex geometry premiums in Middle Eastern podium structures and US green roof specifications sustain positioning above sheet alternatives.
- Roll:Pre-manufactured membrane rolls with controlled thickness and reinforcement dominate high-volume tunnel and roofing projects. China's polymer-modified bitumen capacity build-out is rewriting regional supply economics, marginalizing smaller Southeast Asian producers.
- Sheet:Factory-fabricated panels and composite systems target specific dimensional requirements.
- Coating:Brush or spray-applied thin-film barriers serve remedial and maintenance applications.
Roll maintains volume dominance. Liquid captures the fastest specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer-modified bitumen capacity concentrates in China's coastal provinces, while specification authority shifts toward centralized procurement departments in German and Dutch healthcare construction. Regulatory divergence across major building codes forces manufacturers to maintain parallel product variants.
China
Coastal megacities in the Yangtze River Delta and Pearl River Delta face accelerated waterproofing replacement cycles from saline soil corrosion. MEE enforcement of GB standards for underground engineering mandates multi-layer membrane systems in state-funded rail and utility tunnel projects. Zhengzhou and Shanghai host expanding polymer-modified bitumen production clusters serving domestic infrastructure demand.
India
Underground metro construction in Mumbai, Delhi, and Bangalore accelerates membrane adoption for tunnel lining and station box structures. BIS certification requirements tighten product qualification standards, creating compliance barriers for non-certified imported systems. The Delhi-Mumbai Industrial Corridor concentrates specification demand in transit-oriented development zones.
Germany
Healthcare and data center verticals centralize technical standards departments, displacing brand-agnostic engineer specifications with approved vendor lists. REACH restrictions on polycyclic aromatic hydrocarbons in bitumen modifiers elevate formulation costs while favoring compliant domestic producers. The Rhine-Ruhr and Stuttgart regions anchor specification authority for complex envelope performance.
United States
EPA stormwater management rules under the Clean Water Act intensify green roof and plaza deck specifications in commercial construction. Liquid membrane systems capture premium positioning in irregular substrates where sheet seaming creates failure risk. The Northeast Corridor and Pacific Northwest concentrate demand for vegetated roof assemblies.
United Arab Emirates
Middle Eastern podium structures and complex roof geometries sustain premium positioning for liquid polyurethane formulations. MOHAP and local building codes emphasize performance guarantees for envelope systems in high-salinity coastal environments. Dubai and Abu Dhabi anchor specification demand for seamless monolithic coverage in landmark developments.
Waterproofing Systems Market Competitive Environment
Integrated technology providers and specialized membrane fabricators split the market along specification complexity lines. Tier-1 players leverage captive polymer supply and applicator certification networks to capture infrastructure mandates. Three archetypes dominate: vertically integrated chemical conglomerates with bitumen-to-polymer control, regional membrane specialists with deep installer relationships, and construction chemicals providers bundling waterproofing with complementary envelope systems. Competitive moves concentrate on M&A for geographic coverage and backward integration into polymer modifiers.
Within the integrated chemical tier, Sika AG and BASF SE exemplify technology-stack positioning. Sika leverages its Swiss AG structure to anchor specification-driven projects across European infrastructure corridors. BASF SE represents the German conglomerate archetype with polyurethane liquid formulation capabilities. Soprema Group occupies a position among specialized membrane fabricators with French S.A.S. governance.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Soprema Group |
| Carlisle Companies |
| Mapei S.p.A. |
| Fosroc |
| Tremco Incorporated |
| GAF |
| RPM International |
| Others |
Value Chain & Pricing Dynamics
REACH PAH restrictions on bitumen modifiers compress margins for European manufacturers while elevating compliance premiums for non-compliant imports, simultaneously widening the spread between certified premium formulations and commodity sheet alternatives and forcing procurement teams toward pre-qualified integrated suppliers with captive polymer supply.
Pricing Analysis
REACH polycyclic aromatic hydrocarbon limits dictate the pricing tier structure across European membrane markets. Three-tier pricing structure across certified premium, standard compliant, and non-compliant economy levels separates Sika AG and BASF SE formulations from regional specialists and import-dependent distributors. Price differentiation hinges on BIS certification grade and applicator network density rather than raw material cost alone. Pricing pressure stems from styrene-butadiene feedstock volatility, with Indian infrastructure contractors showing highest price sensitivity and German healthcare asset owners demonstrating lowest sensitivity due to lifecycle cost modeling.
Supply Chain Analysis
Styrene-butadiene rubber and APP modifier feedstock concentration in China's Zhengzhou and Shanghai production clusters anchors global membrane economics. Raw material dependencies rest on crude oil derivatives, bentonite clay from Wyoming and Turkey deposits, and polyurethane isocyanates from BASF's Ludwigshafen complex. Supply chain risk centers on single-source vulnerability for APP modifiers amid MEE enforcement of multi-layer system mandates. Distribution runs through certified applicator networks and construction chemicals distributors rather than direct specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproofing specification is becoming a service-attach business where performance guarantees and applicator certification generate recurring revenue streams expanding faster than commodity membrane sales.
For Market Incumbents: Build installer certification moats by acquiring regional applicator training centers and pre-qualifying crews for Chinese GB standard multi-layer mandates. Defend against polymer-modified bitumen capacity build-out in Zhengzhou by securing captive SBR supply through backward integration into petrochemical partnerships. Anchor specification authority through centralized technical standards departments in German healthcare and Dutch data center verticals. For New Entrants and Emerging Players: Build out crystalline waterproofing-plus-drainage composite offerings for Indian metro rail station box structures where BIS certification barriers filter established competitors. Target Middle Eastern podium structure applications with liquid polyurethane formulations commanding complex geometry premiums. Pursue green roof specification in US commercial construction through EPA stormwater compliance bundling. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated membrane-and-mortar technology stacks over standalone sheet producers. Long-term viability rests on captive polymer supply and applicator network control rather than manufacturing scale alone. Watch MEE enforcement intensity on multi-layer mandates as the signal for accelerated procurement centralization toward integrated envelope suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Certification Network Expansion | Pre-qualifies installation crews for Chinese GB standard multi-layer mandates in rail tunnels. |
| Backward Integration into Polymer Modifiers | Secures captive SBR and APP supply against feedstock volatility from crude oil derivatives. |
| Green Roof System Bundling | Captures EPA stormwater-driven plaza deck specification in US commercial construction. |
| Recycled Content Verification Program | Creates competitive differentiation under evolving EU embodied-carbon regulations. |
| Self-Healing Polymer R&D Partnership | Positions for Japanese rail and Nordic tunnel authority microcapsule-based warranty structures. |
Study Parameters
Cross-validation between primary interviews with waterproofing applicators, membrane procurement managers at Indian metro rail authorities, and German healthcare facility operators anchors the qualitative findings. Secondary validation draws from BIS certification databases, MEE enforcement bulletins on GB standards, REACH PAH restriction compliance filings, and EPA Clean Water Act stormwater rulemaking records. Bottom-up demand modeling from tunnel and roofing application volumes triangulates against top-down construction chemicals market estimates.
Calibration against historical capacity build-out patterns in China's polymer-modified bitumen sector informs elasticity assumptions across the projection horizon. Segmentation dimensions include membrane chemistry, application substrate complexity, end-user specification authority, and regional regulatory cluster. CAGRs derive from infrastructure investment cycle correlation with membrane specification intensity, incorporating hydrostatic pressure exposure thresholds and replacement cycle acceleration from saline soil corrosion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed petrochemical conglomerates into downstream membrane fabrication would shift outcomes. Cross-checking against Indian Ministry of Housing and Urban Affairs metro rail procurement timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Red Brick Market