
 Calcium Sulphate Board Raised Access Floor Market | 2026-2036
Calcium Sulphate Board Raised Access Floor Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Sulphate Board Raised Access Floor Market Analytics
Maintenance and lifecycle service contracts is repositioning how calcium sulphate board raised access floor vendors capture recurring revenue alongside panel sales. Lindner Group leverages its European installed base to secure long-term service agreements in German data center corridors. Kingspan Group anchors its competitive stance through backward integration into steel pedestal production. MERO-TSK International GmbH & Co. KG dominates precision-engineered panel systems for cleanroom environments where tolerance specifications exceed standard commercial grades.
Calcium sulphate board raised access floor consists of a gypsum-based core panel bonded to galvanized steel sheets, typically manufactured in 600 mm square modules with load ratings from 3 kN to 12 kN, designed to create an underfloor plenum for cable management and conditioned air distribution in commercial buildings. Fire-rated panels command premium positioning due to EN 13501-1 certification requirements in European commercial construction, while heavy-duty panels sustain the fastest trajectory as AI data centers specify 10 kN-plus concentrated load capacities. Standard panels retain volume leadership in office fit-outs where cost sensitivity overrides performance margins.
Germany's EnEV standards, the EU Construction Products Regulation, and local building codes across multiple member states collectively shape panel thickness, fire resistance, and recycled content thresholds for market access. The EU Green Deal's embodied carbon tracking provisions are forcing manufacturers to document gypsum sourcing and steel recycling rates in environmental product declarations. Stakeholders must monitor evolving load specifications from hyperscale data center operators against the certification lag in national building code adoption cycles.
Market Dynamics
Hyperscale data center operators are compressing procurement cycles for heavy-duty calcium sulphate board raised access floor systems as AI infrastructure thermal loads force immediate facility retrofits. This demand surge from cloud computing facilities is restructuring manufacturer capacity allocation and certification priorities.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Environmental product declaration mandates are accelerating specification of recycled-content calcium sulphate panels in German and French commercial construction.
- Hyperscale data center expansion:Concentrated demand from United States cloud operators for 10 kN-plus load-rated panels is pulling capacity toward heavy-duty manufacturing lines.
- EnEV energy efficiency standards:Germany's updated building envelope requirements are mandating improved thermal performance in raised floor plenum systems for new commercial builds.
Market Restraints
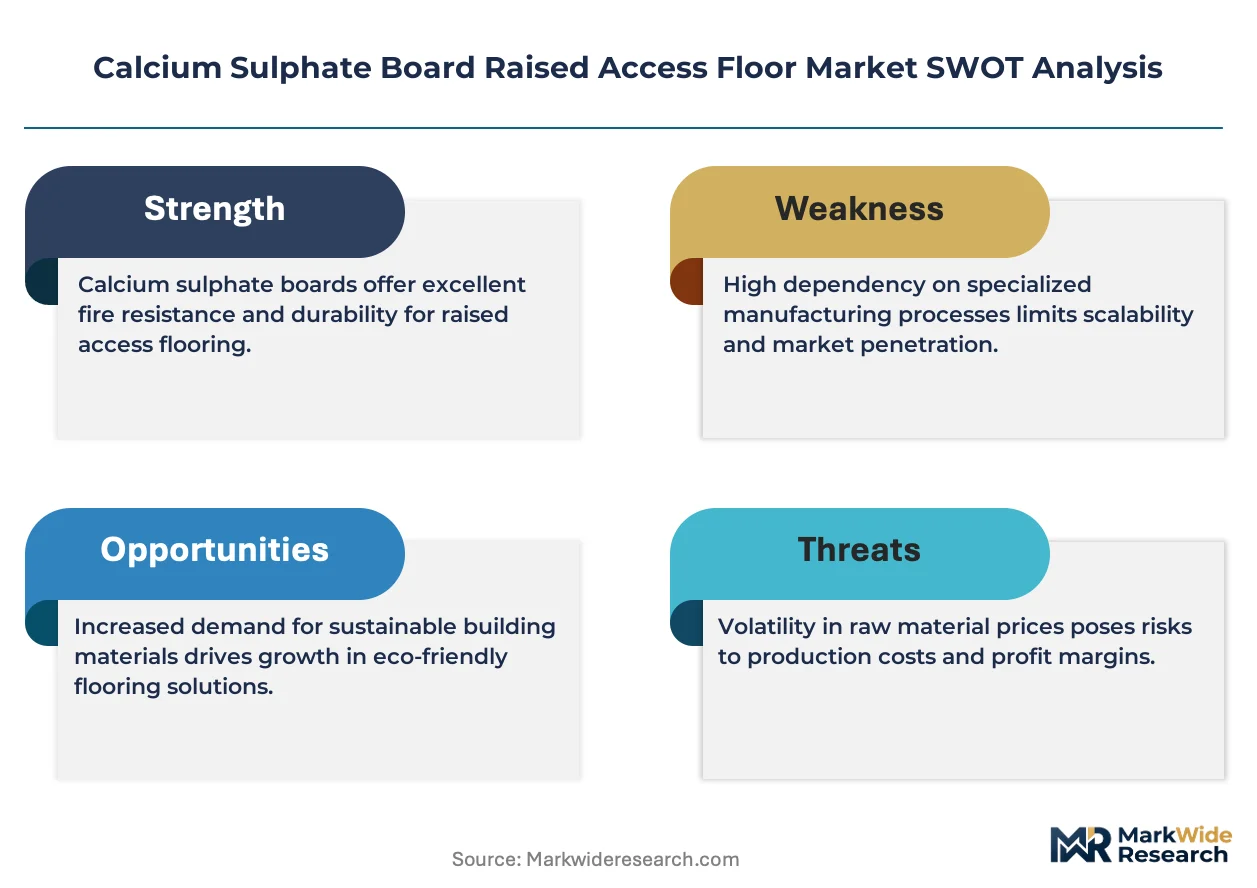
- Gypsum supply concentration:European calcium sulphate board production depends on synthetic gypsum flows from coal-fired power plant flue-gas desulfurization, creating input vulnerability as coal capacity retires.
- Steel price volatility:Galvanized steel sheet costs for panel bonding fluctuate with energy-intensive European steel mill output and scrap metal availability.
- Prefabricated modular flooring substitution:All-steel panel systems are capturing share in data center applications where fire ratings are secondary to electromagnetic shielding requirements.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland data center construction is accelerating without mature local raised access floor supply chains, creating import substitution potential.
- Cleanroom-grade panel specialization:Pharmaceutical and semiconductor manufacturing facilities require precision-tolerance panels exceeding standard commercial specifications.
- Lifecycle service contract bundling:Maintenance and panel replacement agreements tied to initial installation contracts are opening recurring revenue streams beyond one-time hardware sales.
Industry Challenges
- Fire certification timeline compression:EN 13501-1 testing and national building code adoption cycles lag behind hyperscale operator project schedules, creating specification mismatches.
- Skilled installation labor scarcity:Precision leveling and pedestal grid alignment for high-load systems requires specialized contractor expertise that is concentrated in mature European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Sulphate Board Raised Access Floor Market |
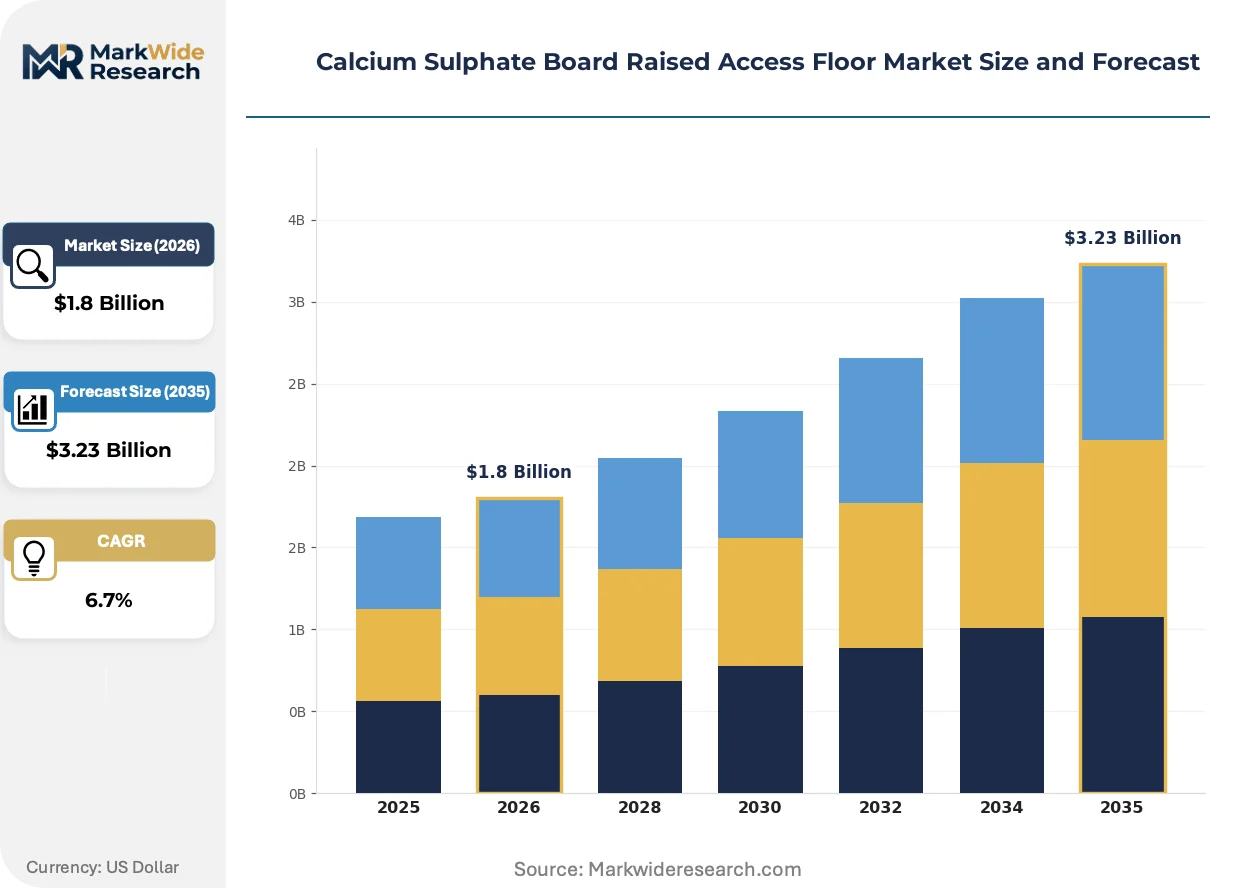
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Panels, Security Panels, Fire-Rated Panels, Heavy-Duty Panels Application: Data Centers, Office Spaces, Retail Stores, Industrial Facilities End User: Commercial, Educational Institutions, Government, Healthcare Facilities Installation Type: Permanent, Temporary, Retrofit, Modular |
| Companies Covered | Lindner Group, Exyte Technology GmbH, Kingspan Group, Knauf, GAMMA Industries SAS, Armstrong World Industries, MERO-TSK International GmbH & Co. KG, Bathgate Flooring Limited, USG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Sulphate Board Raised Access Floor Market Evolving Landscape
Calcium sulphate board raised access floor technology is fragmenting into application-specific performance tiers as end-use requirements diverge between standard commercial fit-outs and specialized infrastructure deployments. Manufacturers are reconfiguring product portfolios around certification grade rather than generic load rating.
Factory-applied edge banding and corner reinforcement systems are modularizing panel construction for field-configurable load rating upgrades. Data center operators in the Netherlands and Ireland are specifying these adaptive systems to accommodate future rack density increases without full floor replacement. The technology is modularizing procurement from capital expenditure toward staged infrastructure investment.
REACH chemical substance restrictions and the EU Construction Products Regulation are tightening formaldehyde emission limits and heavy metal content thresholds for panel adhesives and galvanized coatings. German manufacturers are reformulating bonding agents and steel pretreatment processes to maintain CE marking compliance. Heavy-duty panel lines face the steepest reformulation costs due to thicker adhesive layers required for steel-gypsum bonding.
Specification authority is migrating from general contractors to data center engineering teams who demand load-test documentation and plenum airflow modeling before panel approval. This shift is compressing distributor influence and forcing manufacturers to maintain direct technical sales presence in major cloud computing clusters. The United States hyperscale corridor from Northern Virginia to Dallas exhibits the most pronounced buying pattern transformation.
Calcium Sulphate Board Raised Access Floor Market Segmentation
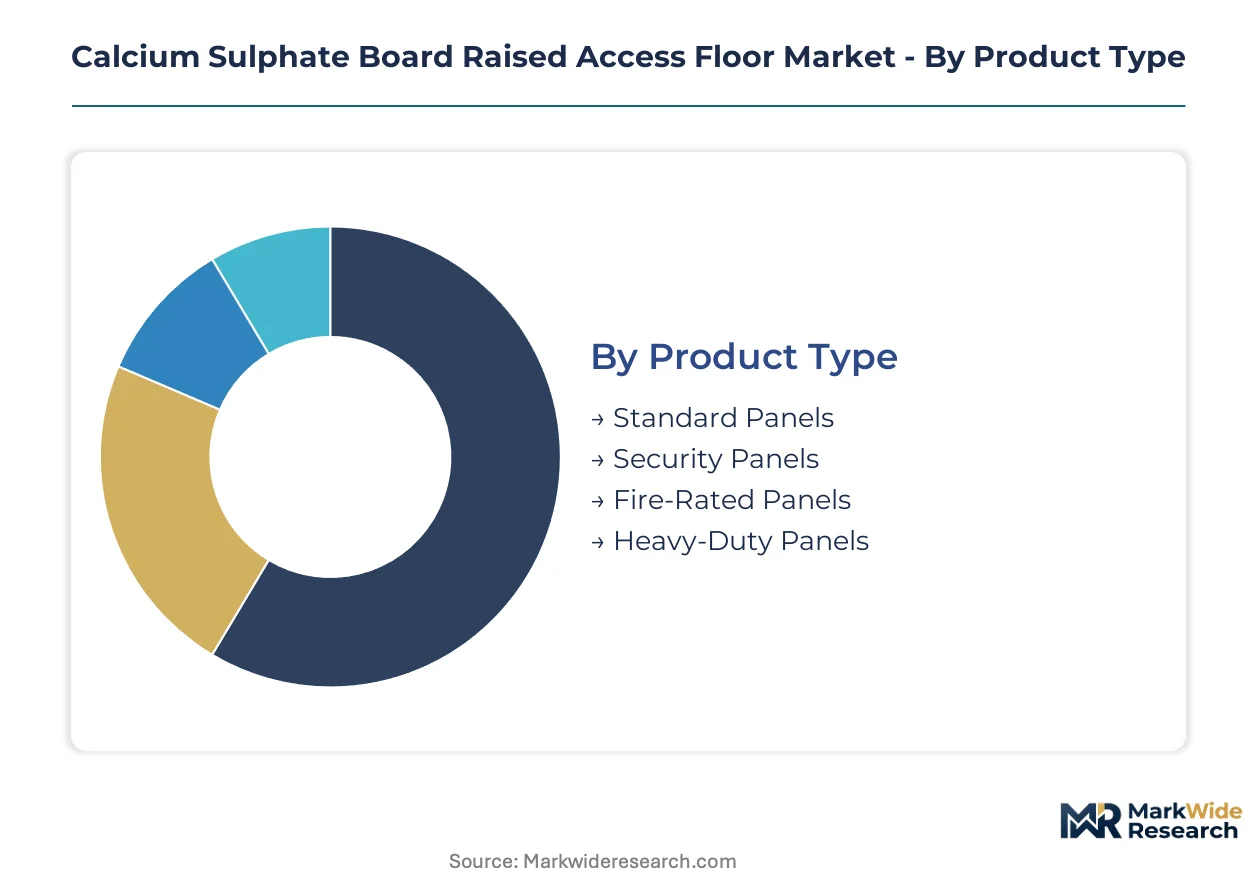
Calcium sulphate board raised access floor procurement splits sharply between generic commercial fit-outs and specialized infrastructure deployments. Specification authority now rests with engineering teams who prioritize certification grade over nominal load rating, fragmenting what was once a commoditized product category.
Product Type:
Panel engineering diverges around fire performance, load-bearing capacity, and security integration rather than core gypsum composition.
- Heavy-Duty Panels:Engineered with reinforced steel bonding and denser gypsum cores to achieve 10 kN-plus concentrated load ratings. Demand concentrates in United States hyperscale data centers retrofitting facilities for AI rack densities, though EN 13501-1 certification lag creates specification friction against compressed procurement timelines.
- Fire-Rated Panels:Incorporate intumescent edge treatments and enhanced gypsum formulations to achieve EN 13501-1 Class A2-s1,d0 ratings. German commercial construction mandates these for plenum applications, with premium positioning sustained by regulatory compliance rather than performance differentiation.
- Standard Panels:Basic 600 mm modules with 3-5 kN ratings dominate office fit-out volumes where cost sensitivity overrides extended performance specifications.
- Security Panels:Reinforced edge profiles and tamper-resistant locking mechanisms for government and financial sector installations requiring controlled access to underfloor infrastructure.
Mature deployment sits with Standard Panels. Newer deployment is concentrated in Heavy-Duty Panels.
Application:
End-use requirements range from thermal load management in mission-critical facilities to aesthetic flexibility in consumer-facing environments.
- Data Centers:Hyperscale operators in Northern Virginia and Dallas corridors specify adaptive panel systems with factory-applied edge banding for future rack density upgrades. Underfloor plenum airflow modeling precedes panel approval, compressing distributor influence.
- Office Spaces:Tenant improvement cycles drive replacement demand for legacy systems, with specification gravitating toward recycled-content panels under EU Green Deal embodied carbon tracking mandates.
- Retail Stores:Visual finish requirements and frequent layout reconfiguration favor temporary installation systems over permanent pedestal grids.
- Industrial Facilities:Chemical resistance and washdown compatibility constraints limit calcium sulphate penetration, with all-steel alternatives capturing share where moisture exposure is routine.
Volume leadership rests with Office Spaces. Steepest expansion trajectory is occurring in Data Centers.
End User:
Budget authority and compliance obligation shape procurement patterns across institutional buyer categories.
- Commercial:Corporate real estate teams balance LEED certification targets against fit-out cost constraints, with lifecycle service contracts gaining traction as procurement evaluation criteria.
- Healthcare Facilities:Infection control protocols and equipment load requirements drive specification of sealed-edge panels with enhanced cleanability, though pharmaceutical manufacturing cleanrooms demand precision tolerances exceeding standard commercial grades.
- Educational Institutions:Public funding cycles and extended facility lifespans favor durable permanent installations over modular alternatives.
- Government:Security clearance requirements and federal procurement regulations segment demand toward certified installers with established facility clearance credentials.
Procurement concentration centers on Commercial end users. Regulatory compliance complexity peaks with Government installations.
Installation Type:
Capital deployment models range from irreversible construction to staged infrastructure investment enabling future reconfiguration.
- Modular:Factory-configured pedestal grids with field-adjustable height systems allow data center operators to defer full build-out until rack deployment schedules clarify. Netherlands and Irish facilities are specifying these for phased AI infrastructure rollouts.
- Retrofit:Panel replacement without structural modification of existing pedestal grids addresses legacy facility upgrades, with load rating upgrades constrained by original subfloor capacity.
- Permanent:Fixed-height installations with cementitious infill dominate markets where future reconfiguration probability is discounted in net present value calculations.
- Temporary:Exhibition and event applications utilize lightweight panel systems with rapid deployment and removal characteristics, though calcium sulphate core weight limits mobility advantages.
Installation type selection increasingly favors Modular approaches. Permanent installations retain share in cost-constrained public sector procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor drives the heaviest specification activity for calcium sulphate board raised access floor systems, with hyperscale operators retrofitting legacy facilities for AI rack densities. Germany's commercial construction sector anchors European demand through stringent energy efficiency mandates. The Netherlands and Ireland emerge as critical deployment zones for modular flooring systems in phased infrastructure rollouts.
United States
Hyperscale cloud providers in Northern Virginia and Dallas corridors specify 10 kN-plus load-rated panels for AI infrastructure retrofits. The EPA's energy efficiency guidelines for federal data centers indirectly shape procurement standards for private operators. Dallas-Fort Worth's expanding cloud cluster is absorbing heavy-duty manufacturing capacity as operators compress project timelines.
Germany
Commercial construction mandates under EnEV energy efficiency standards require improved thermal performance in raised floor plenum systems. The EU Construction Products Regulation's CE marking requirements enforce EN 13501-1 fire certification for panel installations. Frankfurt's financial district and Berlin's tech corridors concentrate specification authority with engineering teams prioritizing compliance documentation.
Netherlands
Data center operators specify factory-applied edge banding systems to accommodate future rack density upgrades without full floor replacement. The EU Green Deal's embodied carbon tracking provisions accelerate demand for recycled-content panels in Amsterdam and Rotterdam commercial builds. Eindhoven's cleanroom manufacturing base sources precision-tolerance panels exceeding standard commercial grades.
United Kingdom
Tenant improvement cycles in London's financial district drive replacement demand for legacy raised floor systems. The UK's building regulations enforce fire resistance standards comparable to EN 13501-1 through Approved Document B compliance. Slough's data center cluster is specifying adaptive panel systems for phased AI infrastructure deployment.
Ireland
Hyperscale operators in Dublin's data center corridor utilize modular pedestal grids with field-adjustable height systems for staged capital deployment. The EU Green Deal mandates environmental product declarations documenting gypsum sourcing and steel recycling rates. Cork's emerging data center zone is attracting specification activity from cloud providers seeking European capacity expansion.
Calcium Sulphate Board Raised Access Floor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the calcium sulphate board raised access floor market, with integrated manufacturers controlling steel pedestal supply chains while specialist engineering firms focus on cleanroom-grade precision systems. The vendor base clusters around three strategic archetypes: diversified building materials conglomerates with backward integration into raw material production, precision-engineering specialists serving contamination-controlled environments, and regional fabricators competing on installation service bundling. Dominant competitive moves include captive supply integration for galvanized steel components and lifecycle service contract anchoring to secure recurring revenue beyond initial panel sales.
Within the precision-engineering tier, MERO-TSK International GmbH & Co. KG exemplifies cleanroom-grade specialization, while Lindner Group represents the European service-contract anchoring model. Kingspan Group occupies a position among building materials conglomerates with upstream control over steel pedestal production. These three entities illustrate how competitive positioning fragments across manufacturing integration depth, specification authority capture, and geographic installed base leverage rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Lindner Group |
| Exyte Technology GmbH |
| Kingspan Group |
| Knauf |
| GAMMA Industries SAS |
| Armstrong World Industries |
| MERO-TSK International GmbH & Co. KG |
| Bathgate Flooring Limited |
| USG Corporation |
| Others |
Value Network & Pricing Analysis
Factory-applied edge banding systems for field-configurable load upgrades are compressing unit economics while concentrating manufacturing capability among German and Dutch producers with certified heavy-duty lines. This production-method transition simultaneously elevates capital barriers for new entrants and tightens margin structures across standard-grade panel tiers.
Pricing Analysis
Value-based pricing anchored to plenum airflow throughput and rack density uptime is displacing pure materials-cost models in data center procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by EN 13501-1 certification grade and 10 kN-plus load-test documentation, with hyperscale operators least sensitive and office fit-out contractors most price-responsive. Cost compression in standard-grade panels is intensifying because recycled-content gypsum sourcing commands premium feedstock pricing under EU Green Deal mandates.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Belgium coordinate hub-and-spoke patterns for just-in-time delivery to data center construction corridors. Manufacturing draws from synthetic gypsum flows from coal-fired power plant flue-gas desulfurization in Poland and Germany, plus galvanized steel sheet from European mills in Luxembourg and Spain. Single-source vulnerability in synthetic gypsum feedstock creates input risk as coal capacity retires. Distribution runs through manufacturer-direct technical sales teams for heavy-duty specifications and construction distributors for standard commercial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium sulphate board raised access floor technology is transitioning from static permanent installations to adaptive modular systems, with factory-configured edge banding replacing legacy full-floor replacement cycles in data center retrofit economics.
For Market Incumbents: Deploy lifecycle service contract bundling to anchor recurring revenue against all-steel panel substitution in electromagnetic shielding applications. Capture specification authority through direct technical sales presence in Northern Virginia and Dallas hyperscale corridors, while backward integration into steel pedestal production defends margin position against galvanized sheet cost volatility. For New Entrants and Emerging Players: Capture underpenetrated Nordic markets in Sweden and Finland where data center construction accelerates without mature local supply chains. Target cleanroom-grade panel specialization for Eindhoven semiconductor and pharmaceutical manufacturing facilities, entering through precision-tolerance engineering partnerships rather than volume manufacturing scale. For Investors and Strategic Acquirers: Re-rating potential sits with precision-engineering specialists given cleanroom certification moats and pharmaceutical facility expansion. Long-term viability favors asset-light designers with installed base leverage for service contract anchoring over capital-heavy producers exposed to steel and gypsum commodity cycles. Watch hyperscale operator load specification creep toward 12 kN-plus ratings as the inflection signal for heavy-duty capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Pedestal Production | Kingspan Group's captive supply of galvanized components insulates against European mill output volatility. |
| Cleanroom-Grade Certification Investment | MERO-TSK International's precision tolerance systems command premium positioning in pharmaceutical manufacturing. |
| Lifecycle Service Contract Bundling | Lindner Group leverages German installed base for recurring maintenance revenue beyond panel sales. |
| Modular Edge Banding System Launch | Netherlands and Ireland data centers specify adaptive panels for phased AI infrastructure rollouts. |
| Recycled-Content Panel Repositioning | EU Green Deal embodied carbon tracking accelerates specification of documented gypsum sourcing panels. |
Research Methodology
Multi-period observation of hyperscale data center procurement cycles, EN 13501-1 certification timelines, and coal plant retirement schedules anchored the trend analysis, supplemented by interviews with facility engineering directors, construction procurement managers, raised access floor installation contractors, and gypsum processing plant operators. Secondary validation drew from EPA energy efficiency guidelines, EU Construction Products Regulation filings, German EnEV standard updates, and hyperscaler capital expenditure disclosures. Bottom-up panel shipment estimates triangulated against top-down commercial construction floor area projections.
Input-output matrices mapped load rating specifications, fire certification grades, and installation type preferences across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, end user budget authority, and installation capital deployment model. CAGRs were derived from elasticity-adjusted demand curves incorporating AI rack density forecasts and building code adoption lag functions. Industry-specific inputs included synthetic gypsum supply forecasts from coal plant FGD output and European steel mill capacity utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to coal plant retirement acceleration, REACH chemical restriction expansion, and hyperscale operator procurement timeline compression. Outputs reflect documented assumptions around certification lag, skilled labor availability, and substitute technology penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Spray Foam Insulation Market