
 Asphalt Shingles Market | 2026-2036
Asphalt Shingles Market Size, Share, and Industry Trends Forecast 2026-2036
Asphalt Shingles Market Analysis
Modular bundle configurations pairing underlayment, starter strips, and ridge caps with shingle pallets is recalibrating contractor procurement economics and reducing jobsite complexity. Owens Corning leverages captive fiberglass mat production to control raw material quality and cost position across its shingle lines. CertainTeed differentiates through specialty color blends and premium designer profiles that command higher contractor loyalty in affluent suburban markets. Atlas Roofing Corporation competes aggressively on wind-warranty terms, extending coverage thresholds that resonate in storm-exposed geographies.
Asphalt shingles are roofing materials manufactured from a base mat of fiberglass or organic felt saturated with asphalt and surfaced with mineral granules, engineered to provide waterproofing, UV resistance, and fire protection for sloped roof assemblies. The product serves as the dominant residential roofing solution in North America due to its balance of installed cost, contractor familiarity, and established distribution infrastructure. Architectural laminated shingles represent the fastest-growing product type as homeowners prioritize dimensional aesthetics and extended warranty terms over basic 3-tab economics. The replacement installation segment anchors volume demand, driven by aging housing stock and recurring storm damage cycles that trigger insurance-funded re-roofing. Fiberglass-based materials dominate material composition due to superior fire ratings, lighter weight, and compatibility with longer warranty programs.
The EPA Energy Star cool roof program and ASTM D7158 wind classification standards shape product development priorities and regional market access requirements for manufacturers serving the US market. Florida's Miami-Dade County Product Control and Texas Department of Insurance building code amendments create localized compliance thresholds that filter which shingle systems qualify for installation in high-velocity wind zones. Stakeholders must monitor evolving insurance industry loss-mitigation incentives and municipal resilience ordinances that increasingly mandate impact-resistant roofing as a condition of coverage renewal in catastrophe-prone counties.
Market Dynamics
Insurance loss-mitigation mandates in hurricane-exposed US counties are compressing re-roofing cycles and forcing specification upgrades toward impact-resistant laminated systems, restructuring contractor bidding patterns and manufacturer warranty economics.
Growth Catalysts
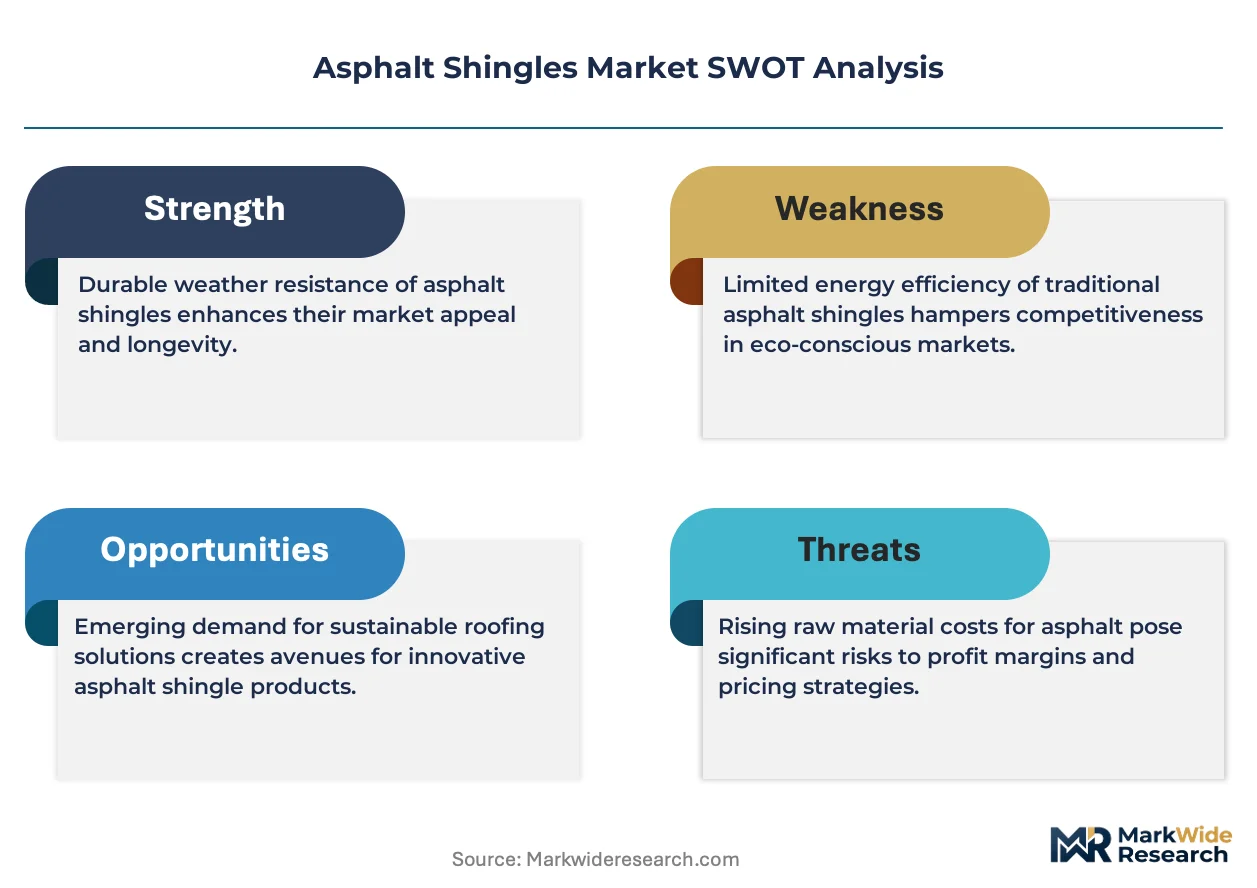
- Florida Building Code T24-22:The state's wind-borne debris provisions now require Miami-Dade Product Control approval for shingles in High-Velocity Hurricane Zones, accelerating replacement demand for certified laminated products.
- Residential re-roofing intensity:Aging housing stock across the southeastern United States, combined with recurring storm damage cycles, generates sustained insurance-funded replacement volume.
- Fiberglass mat technology:Lighter base materials with superior fire ratings enable extended warranty terms that contractors leverage to differentiate bids in competitive suburban markets.
Market Restraints
- Asphalt flux cost volatility:Refinery output fluctuations and competing demand from road construction create input price instability that compresses manufacturing margins.
- Granule supply concentration:Domestic mining operations for ceramic-coated surface granules cluster in specific Appalachian and Great Lakes regions, exposing producers to localized disruption risk.
- Metal roofing substitution:Longer lifecycle and declining installed cost of standing-seam systems erode share in premium residential segments where durability commands price premiums.
Strategic Opportunities
- Texas Department of Insurance incentives:Windstorm certification discounts for impact-rated roofing create pull-through demand in coastal counties where coverage costs dominate homeowner decisions.
- Cool roof pigment chemistry:Solar reflectance formulations meeting EPA Energy Star thresholds open specification access to municipal resilience ordinances in sun-belt metropolitan areas.
- Direct contractor platform procurement:Digital ordering systems bundling underlayment, starter strips, and ridge caps reduce jobsite complexity and capture share from traditional two-step distribution.
Industry Challenges
- Installer certification bottlenecks:Manufacturer extended-warranty programs require trained contractor networks, and capacity constraints in storm-recovery periods delay revenue recognition.
- ASTM D7158 testing backlog:Wind classification laboratory capacity limits speed-to-market for new product introductions in high-velocity zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphalt Shingles Market |
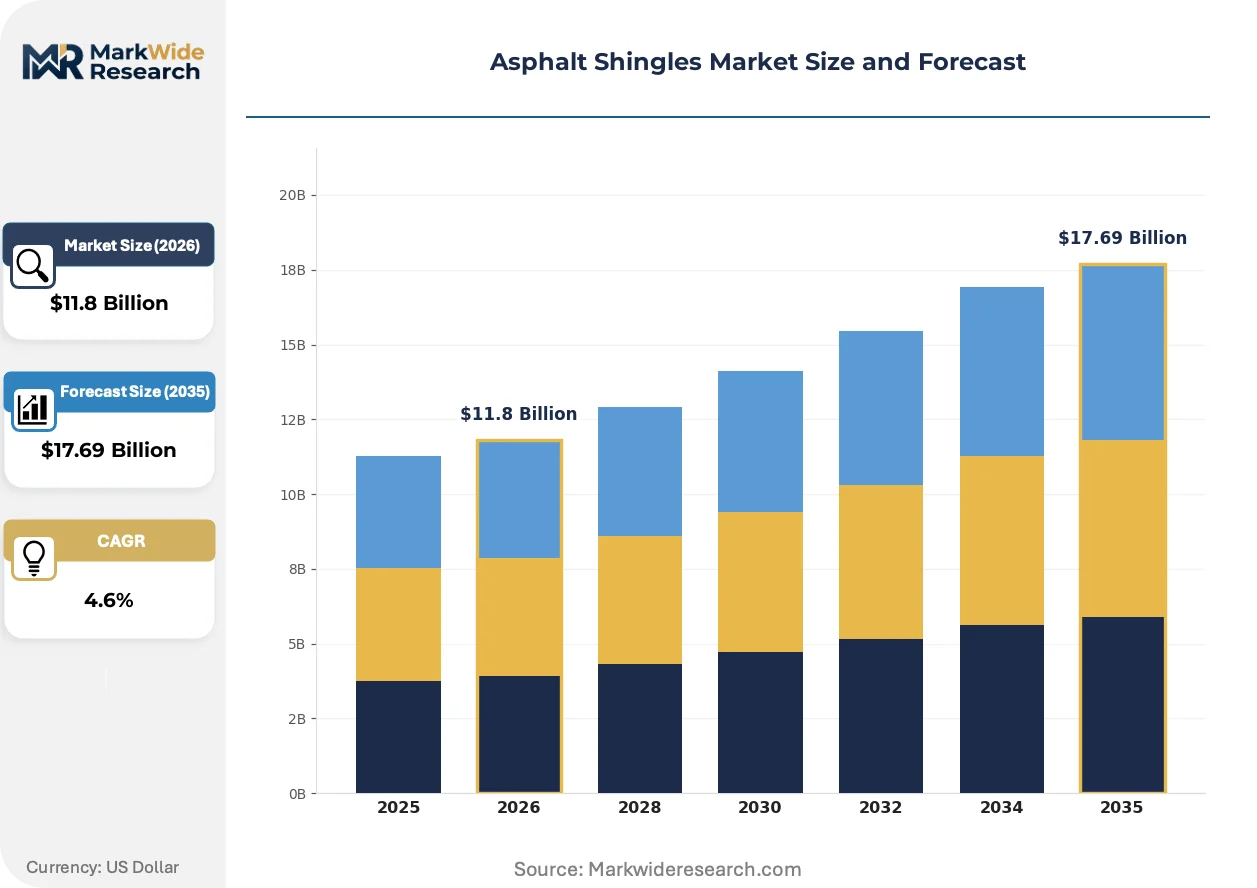
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3-tab, Architectural, Composite, Designer Installation Type: New Construction, Replacement, Retrofit, Repair Material: Fiberglass, Organic, Mineral, Reflective End User: Residential, Commercial, Industrial, DIY |
| Companies Covered | Malarkey, Atlas Roofing Corporation, GAF, PABCO Roofing Products, TAMKO, Owens Corning, IKO Industries, Johns Manville, CertainTeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphalt Shingles Market Emerging Trajectories
Product development priorities are converging on dual-performance systems that simultaneously satisfy wind-resistance and thermal-reflectance standards, compressing the traditional trade-off between durability and energy efficiency.
Polymer-modified asphalt formulations are unifying impact resistance and flexibility in cold-weather applications. Regional distributors in the upper Midwest report accelerated uptake among contractors serving lake-effect snow zones. This chemistry is unifying previously separate product lines for hail-prone and freeze-thaw geographies, reducing SKU complexity for multi-regional manufacturers.
EPA Energy Star cool roof program revisions are tightening solar reflectance index thresholds for steep-slope assemblies. Product managers must reformulate granule coatings or risk exclusion from federal tax credit eligibility. Southern California and Arizona municipal building departments have adopted these standards as code amendments, forcing specification changes in new construction segments.
Homeowner buying patterns now prioritize insurance premium reductions over first-cost minimization. Independent roofing contractors in Florida and Texas report extended-warranty laminated shingles capturing share from three-tab economy grades. This preference shift is most visible in catastrophe-prone counties where annual coverage costs exceed material price differentials within three to five years.
Asphalt Shingles Market Segmentation
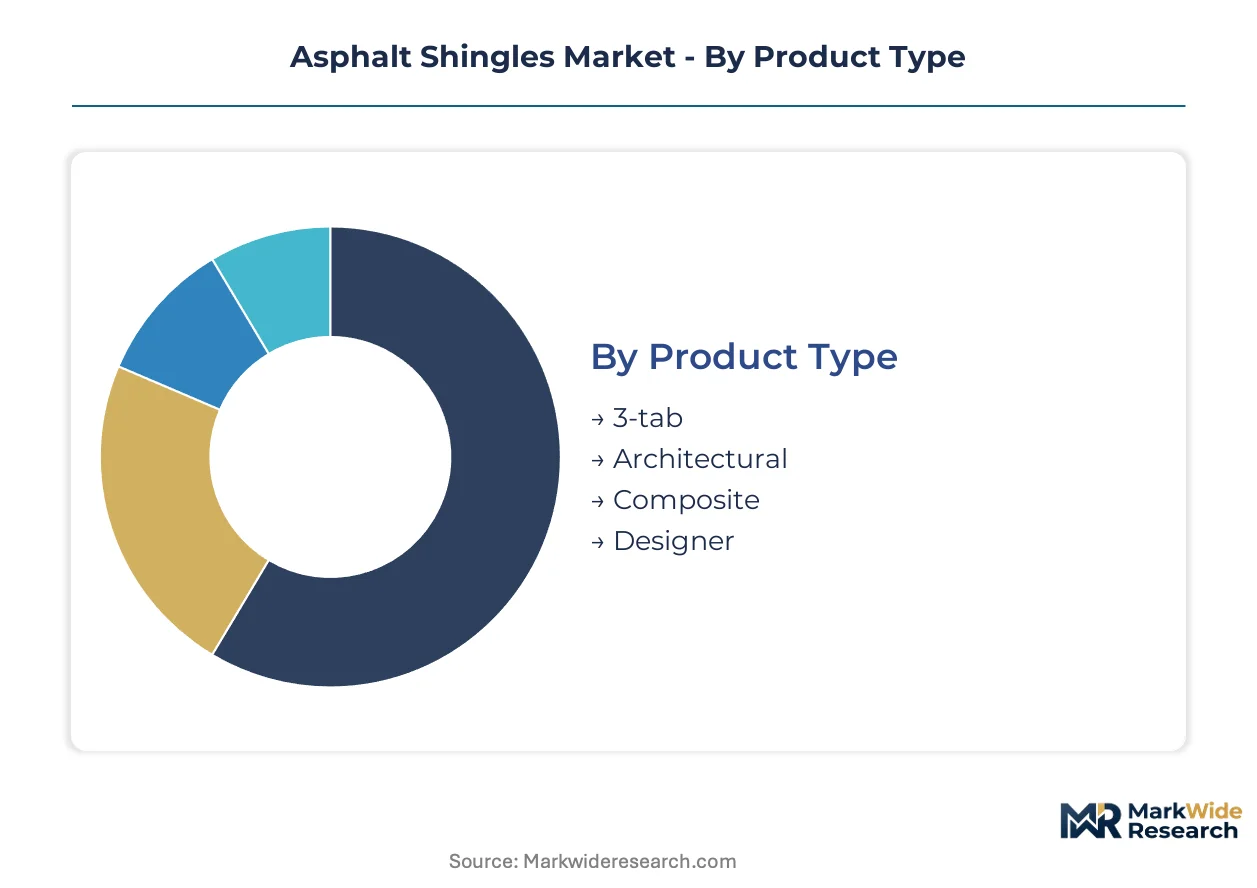
Segmentation in the asphalt shingles market reveals how capital deployment, regulatory compliance, and installation economics concentrate competitive advantage across distinct product tiers and customer channels. Manufacturers calibrate production capacity and distribution investments based on which segments command premium pricing and recurring replacement volume.
Product Type:
Capital intensity escalates sharply with manufacturing complexity, as multi-layer lamination and specialized granule coating require dedicated production lines and extended curing infrastructure.
- Architectural:Multi-layer fiberglass mat construction with dimensional surface profiling delivers enhanced wind resistance and extended warranty terms. Demand concentrates in Florida and Texas coastal counties where insurance mandates drive specification upgrades toward impact-rated laminated systems.
- 3-tab:Single-layer strip configuration with uniform rectangular exposure represents the baseline economy tier. Volume persists in inland southeastern states where building code cycles remain less stringent and contractor bidding prioritizes first-cost minimization.
- Designer:Premium profiles replicate slate or wood shake aesthetics through specialized die-cutting and color-blending processes.
- Composite:Hybrid formulations incorporating recycled rubber or plastic modifiers for enhanced impact absorption in hail-prone geographies.
Architectural shingles absorb the bulk of installed capacity; Designer profiles are expanding most quickly in affluent suburban markets.
Installation Type:
Volume distribution reflects the age structure of US housing stock and the geographic concentration of catastrophe exposure that triggers insurance-funded replacement cycles.
- Replacement:Removal and reinstallation on existing roof decks dominates industry volume, driven by aging housing inventory and recurring storm damage in hurricane-exposed southeastern counties. Florida's High-Velocity Hurricane Zones generate sustained demand for certified systems that satisfy Miami-Dade Product Control approval.
- New Construction:Installation on residential developments and custom builds tracks housing starts and builder preference for warranty-backed products that reduce callback liability.
- Retrofit:Overlay applications on structurally sound existing roofs serve cost-sensitive homeowners in jurisdictions permitting multiple shingle layers.
- Repair:Partial replacement of wind-lifted or impact-damaged sections addresses isolated storm damage without full re-roofing.
Replacement installations command the majority of contractor labor allocation; New Construction exhibits the steepest expansion trajectory in sun-belt metropolitan areas with active residential development.
Material:
Raw material selection determines fire rating eligibility, warranty term extension, and regional market access under municipal building code amendments.
- Fiberglass:Non-combustible base mat with asphalt saturation and ceramic granule surfacing achieves Class A fire ratings and enables 30- to 50-year warranty programs. Dominant specification in jurisdictions adopting stringent fire codes and in insurance markets requiring documented fire resistance.
- Organic:Cellulose felt base with heavier asphalt saturation provides enhanced cold-weather flexibility but reduced fire ratings. Retained share in northern tier states with severe freeze-thaw cycling where pliability during winter installation outweighs fire classification concerns.
- Mineral:Slate or ceramic granule surfacing without asphalt saturation serves specialized restoration applications.
- Reflective:Solar-reflective granule formulations engineered to meet EPA Energy Star cool roof thresholds for steep-slope assemblies.
Fiberglass-based materials anchor manufacturing throughput; Reflective formulations are gaining share fastest in California and Arizona municipalities with adopted cool roof ordinances.
End User:
Customer segmentation structures distribution channel configuration, with professional contractor networks serving distinct procurement patterns from retail DIY and commercial specification channels.
- Residential:Single-family and multi-family sloped roof applications constitute the core demand base, with homeowner decisions increasingly influenced by insurance premium reduction potential rather than first-cost minimization alone. Professional contractor installation dominates this channel.
- Commercial:Low-slope and steep-slope applications on retail, office, and institutional buildings specify enhanced warranty terms and documented installation certification to satisfy asset management requirements.
- Industrial:Warehouse and manufacturing facility roofing prioritizes durability and maintenance access over aesthetic considerations.
- DIY:Retail purchases by homeowners for self-installation concentrate in repair and small-scale replacement projects.
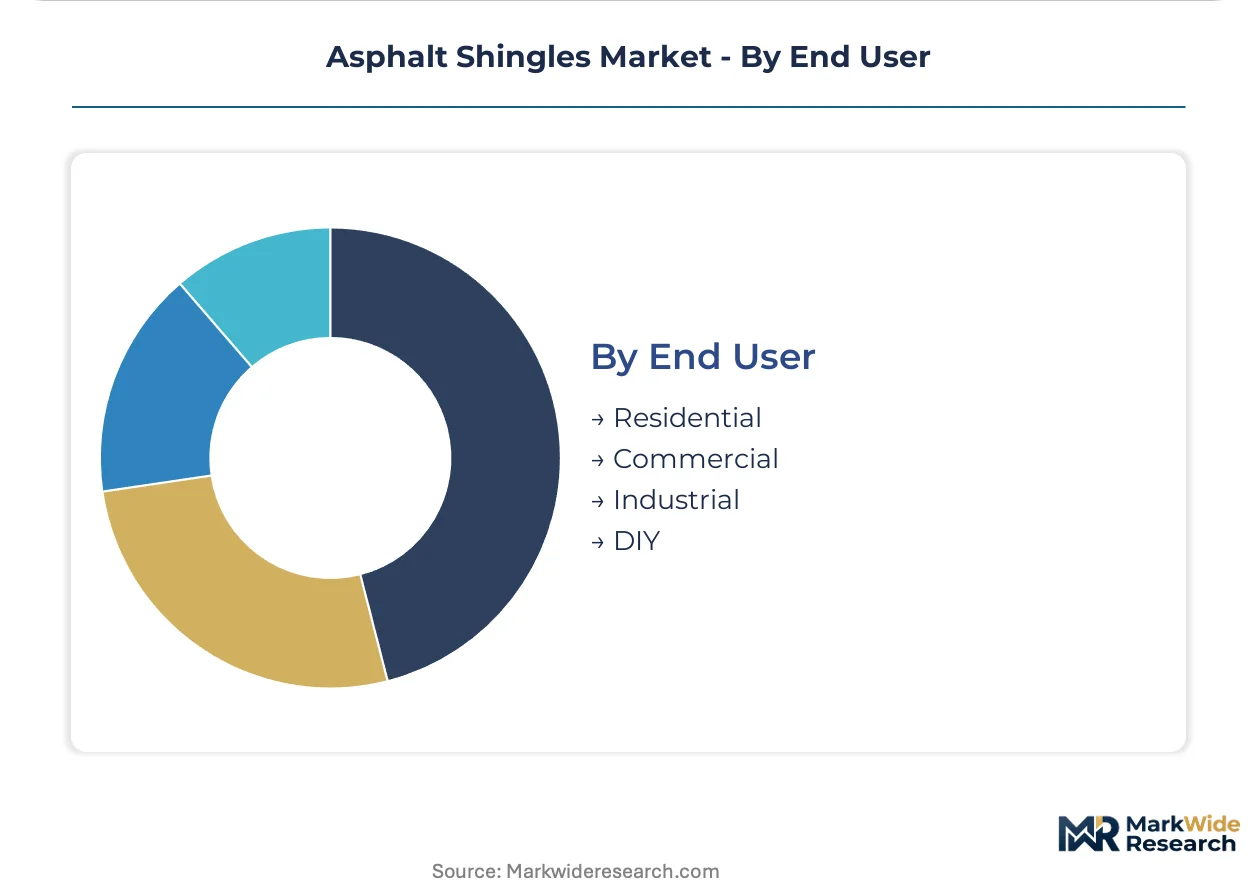
Residential end users generate the preponderance of volume; Commercial specifications are climbing the fastest as institutional investors prioritize lifecycle cost documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the southeastern United States while consumption concentrates in storm-exposed coastal zones. This geographic mismatch drives freight optimization and regional distribution center placement. Canada and Mexico serve secondary demand pools with distinct regulatory frameworks.
United States
Florida and Texas generate the dominant replacement volume as hurricane exposure compresses re-roofing cycles. The EPA's Energy Star cool roof program and ASTM D7158 wind classification standards filter product access in high-velocity zones. Miami-Dade County's Product Control approval process anchors certification requirements for coastal installations.
Canada
Freeze-thaw cycling in Ontario and Quebec sustains demand for cold-weather flexible formulations. Health Canada's building material standards and provincial fire codes shape product specification. The Greater Toronto Area concentrates contractor networks serving aging suburban housing stock.
Mexico
Monterrey and Mexico City metro areas drive new construction volume as residential development expands. The country's national construction regulator sets baseline material standards that parallel ASTM frameworks. Northern border states absorb cross-border distribution from Texas manufacturing clusters.
Asphalt Shingles Market Vendor Landscape
The competitive structure tilts toward integrated building materials conglomerates with captive fiberglass supply. Consolidation around a handful of national brands persists despite regional specialty producers. Two strategic archetypes dominate: vertically integrated mat producers controlling raw material quality, and specification-focused specialists commanding premium positioning. Capacity expansion and warranty term extension represent the dominant competitive moves.
Among North American building materials specialists, Owens Corning, CertainTeed, and Atlas Roofing Corporation occupy distinct positioning vectors. Owens Corning exemplifies the integrated archetype through captive fiberglass mat production. CertainTeed anchors the premium-tier specification channel. Atlas Roofing Corporation represents aggressive warranty-term competition in storm-exposed geographies.
| Leading Market Players |
|---|
| Malarkey |
| Atlas Roofing Corporation |
| GAF |
| PABCO Roofing Products |
| TAMKO |
| Owens Corning |
| IKO Industries |
| Johns Manville |
| CertainTeed |
| Others |
Supply Flow & Price Mechanics
Roofing contractor labor pools in Florida and Texas generate cost differentials that widen pricing spreads between premium laminated systems and economy three-tab products. These regional wage premiums compress margins on certified installations while elevating tiered product positioning.
Pricing Analysis
Margin tightening in economy-grade three-tab shingles reflects asphalt flux cost volatility and competing road construction demand. Three-tier pricing structure across premium laminated, standard architectural, and economy three-tab levels separates products by ASTM wind certification and warranty duration. Price differentiation hinges on Miami-Dade Product Control approval status and contractor certification tier. Cost-down pressure on economy grades accelerates because homeowner price sensitivity concentrates in inland markets outside hurricane zones, while coastal buyers prioritize insurance premium reductions over first-cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for ceramic-coated granules compel manufacturers to qualify Appalachian and Great Lakes mining operations simultaneously. Raw material procurement draws from domestic fiberglass mat production, petroleum-derived asphalt flux, and regionally concentrated mineral surfacing operations. Supply chain risk centers on single-source vulnerability for specialized polymer-modified asphalt formulations. Distribution runs through national building materials distributors serving contractor networks, with direct-to-contractor digital platforms gaining share in storm-recovery periods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asphalt shingles market has become a vertical-integration race, with captive fiberglass mat production emerging as the decisive cost-control lever separating integrated conglomerates from specification-dependent competitors.
For Market Incumbents: Anticipate metal roofing substitution in premium residential segments by extending warranty terms and accelerating polymer-modified asphalt R&D. Defensive moves require deepening backward integration into granule coating operations and expanding Miami-Dade-certified production capacity in the southeastern United States. Channel control through exclusive contractor certification programs protects pricing power against emerging direct-procurement platforms. For New Entrants and Emerging Players: Cool roof pigment chemistry delivering EPA Energy Star thresholds offers a technology-first wedge into California and Arizona municipal specification channels. White-space targets include reflective formulation segments underserved by incumbent portfolios and digital procurement platforms bundling underlayment with shingle pallets. Go-to-market positioning should emphasize insurance premium reduction documentation for catastrophe-prone county homeowners. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists possessing captive fiberglass supply and established Miami-Dade certification, given tightening EPA cool roof standards and ASTM wind classification requirements. Long-term viability favors manufacturers with storm-zone installation density and extended-warranty program scale. The signal to watch is Texas Department of Insurance incentive expansion into additional coastal counties, which would accelerate specification upgrades and compress replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fiberglass Mat Integration | Controls raw material quality and cost position across shingle product lines. |
| Miami-Dade Product Control Certification | Unlocks access to Florida High-Velocity Hurricane Zone replacement volume. |
| Polymer-Modified Asphalt R&D Investment | Unifies impact resistance and cold-weather flexibility in single product platforms. |
| Direct Contractor Platform Development | Reduces jobsite complexity through bundled underlayment and accessory procurement. |
| Cool Roof Pigment Formulation | Qualifies products for EPA Energy Star thresholds and municipal ordinance compliance. |
Methodological Framework
Document review covered SEC 10-K filings from building materials conglomerates, ASTM technical standards, and EPA Energy Star program documentation, complemented by interviews with regional roofing distributors, certified installation contractors, and municipal building code officials. Primary fieldwork included discussions with procurement managers at national distributor networks and technical directors at fiberglass mat suppliers. Secondary validation drew from National Association of Home Builders construction data, insurance industry loss reports, and customs records tracking asphalt and mineral granule trade flows. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Historical shipment data cross-referenced against panel input from industry participants anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, installation category, material composition, and end-user channel, with regional regulatory clusters treated as distinct market access filters. CAGRs were derived from replacement cycle intensity in storm-exposed geographies and new construction tracking in sun-belt metropolitan areas. Industry-specific inputs incorporated Florida Building Code amendment timelines and Texas Department of Insurance incentive program expansion patterns.
Several conditions sit outside the modeled scope, including abrupt petroleum price shocks affecting asphalt flux costs, granule mining operation disruptions, and unanticipated metal roofing cost declines. Deviation in hurricane frequency or insurance industry loss-mitigation mandate intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market