
 Ultra High Performance Concrete (UHPC) Market | 2026-2036
Ultra High Performance Concrete (UHPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Performance Concrete (UHPC) Market Intelligence
Performance-based maintenance contracts is broadening what infrastructure owners purchase alongside raw material supply. Sika AG leverages its global admixture portfolio to anchor specification-driven procurement in European bridge programs. BASF SE competes through R&D intensity in fiber-matrix bonding chemistry. Lafarge sustains manufacturing scale across precast operations in France and Canada.
Ultra High Performance Concrete denotes a cementitious composite exceeding 150 MPa compressive strength through optimized particle packing, silica fume densification, and steel fiber reinforcement, engineered for extreme durability in structural elements exposed to chloride ingress, abrasion, or seismic loading. Precast segments dominate current volume as factory-cured elements reduce field variability and accelerate installation schedules for bridge decks and building facades. Cast-in-place applications represent the fastest-growing category where contractors gain expertise in self-consolidating placement techniques for complex geometries and retrofit overlays.
ACI 239 committee guidelines, EN 206 performance classes, and CSA S6 Canadian highway bridge standards collectively elevate minimum durability thresholds that conventional concrete cannot satisfy. These frameworks directly shape product qualification protocols and limit market access to producers with certified third-party validation. Stakeholders must monitor evolving fiber content specifications and carbon accounting requirements that will redefine competitive positioning in public infrastructure tenders.
Market Dynamics
Bridge rehabilitation mandates across aging infrastructure portfolios are compressing project timelines and forcing specification upgrades that conventional concrete cannot satisfy. Federal highway authorities in Germany, state DOTs in the United States, and Transport Canada are embedding UHPC into standard repair protocols for critical span elements.
Growth Catalysts
- EN 206 Performance Classes:European standards for chloride resistance and freeze-thaw durability now exceed conventional concrete capabilities, mandating UHPC for marine and alpine infrastructure exposure zones.
- Seismic Retrofit Programs:Japan's METI guidelines for building resilience and California's bridge column wrapping specifications accelerate fiber-reinforced UHPC adoption in high-risk seismic corridors.
- Precast Factory Curing:Controlled production environments eliminate field variability in hydration kinetics, enabling just-in-time delivery for overnight deck replacements on active highway corridors.
Market Restraints
- Silica Fume Supply Concentration:Norwegian and Chinese metallurgical silicon producers control over 70% of global microsilica output, exposing UHPC manufacturers to input cost volatility and geopolitical disruption risk.
- Specialized Mixing Equipment:High-shear batching systems for steel fiber dispersion require capital outlays that preclude small regional concrete producers from qualification for public tenders.
- CSA S6 Certification Timeline:Canadian highway bridge standards demand 18-month field performance validation before product approval, delaying market entry for new formulations.
Strategic Opportunities
- Building Façade Cladding:Thin-section UHPC panels offer architects compression strengths exceeding natural stone at one-third the weight, opening speculative commercial construction in dense urban cores.
- EU Green Deal Carbon Accounting:Emerging embodied carbon thresholds for public procurement favor UHPC's extended service life over repeated conventional concrete replacement cycles.
- 3D-Printed Structural Elements:Convergence of robotic extrusion with self-consolidating UHPC rheology enables geometrically complex infrastructure components without formwork labor.
Industry Challenges
- Fiber Alignment Control:Achieving consistent steel fiber orientation in cast-in-place applications requires specialized training that most contractor workforces lack, creating quality assurance gaps in field installations.
- Multi-Jurisdictional Approval:Producers must navigate separate validation protocols under ACI 239, EN 206, and CSA S6 simultaneously, fragmenting R&D resources across incompatible testing regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Performance Concrete (UHPC) Market |
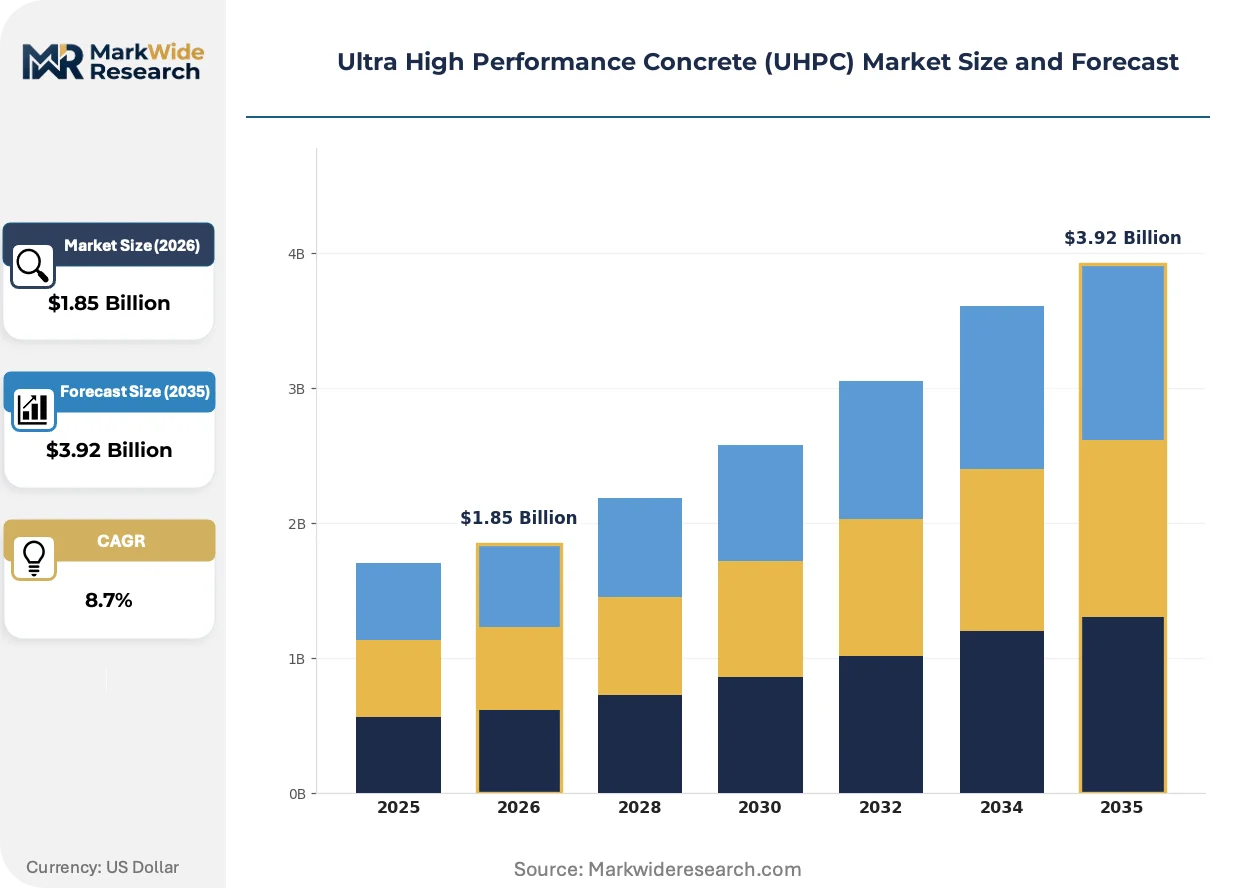
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precast, Cast-in-Place, Ultra-High-Performance Fiber-Reinforced Concrete, Lightweight UHPC Application: Bridge Construction, Building Facades, Overlays, Industrial Flooring End User: Construction Companies, Infrastructure Developers, Government Agencies, Private Developers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Outlets |
| Companies Covered | BASF SE, GCP Applied Technologies Inc., Sika AG, Buzzi Unicem S.p.A., MAPEI S.p.A., Holcim Ltd, Lafarge, VSL International SA, CEMEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Performance Concrete (UHPC) Market Strategic Shifts & Innovations
Digital fabrication methods and predictive material modeling are compressing development cycles for UHPC formulations while expanding addressable geometries beyond traditional precast limitations. Specification frameworks are tightening in parallel, creating dual pressure on producers to innovate faster under stricter compliance regimes.
Hybrid fiber systems combining steel and synthetic polymer filaments are decentralizing application expertise across contractor tiers. Mid-size regional builders in Texas and Bavaria now specify blended-fiber UHPC for culvert linings and sound wall bases without specialist engineering support. This diffusion is eroding the historical monopoly of precast specialists on complex UHPC work.
ACI 239 committee revisions to fiber content minimums and durability testing protocols are reshaping qualification requirements for North American bridge programs. The updated guidelines mandate 28-day chloride diffusion coefficients below established thresholds, disqualifying formulations that passed under earlier editions. State DOTs in Florida and coastal California are accelerating specification updates to incorporate these stricter benchmarks.
Asset owners are bundling material supply with performance warranties spanning 50-year service life, displacing traditional unit-price procurement for major rehabilitation contracts. Engineering firms in Germany and the Netherlands now carry liability for UHPC deck performance, forcing closer collaboration with certified producers during design phases. This shift concentrates contract awards among vertically integrated suppliers with in-house testing capabilities.
Ultra High Performance Concrete (UHPC) Market Segmentation
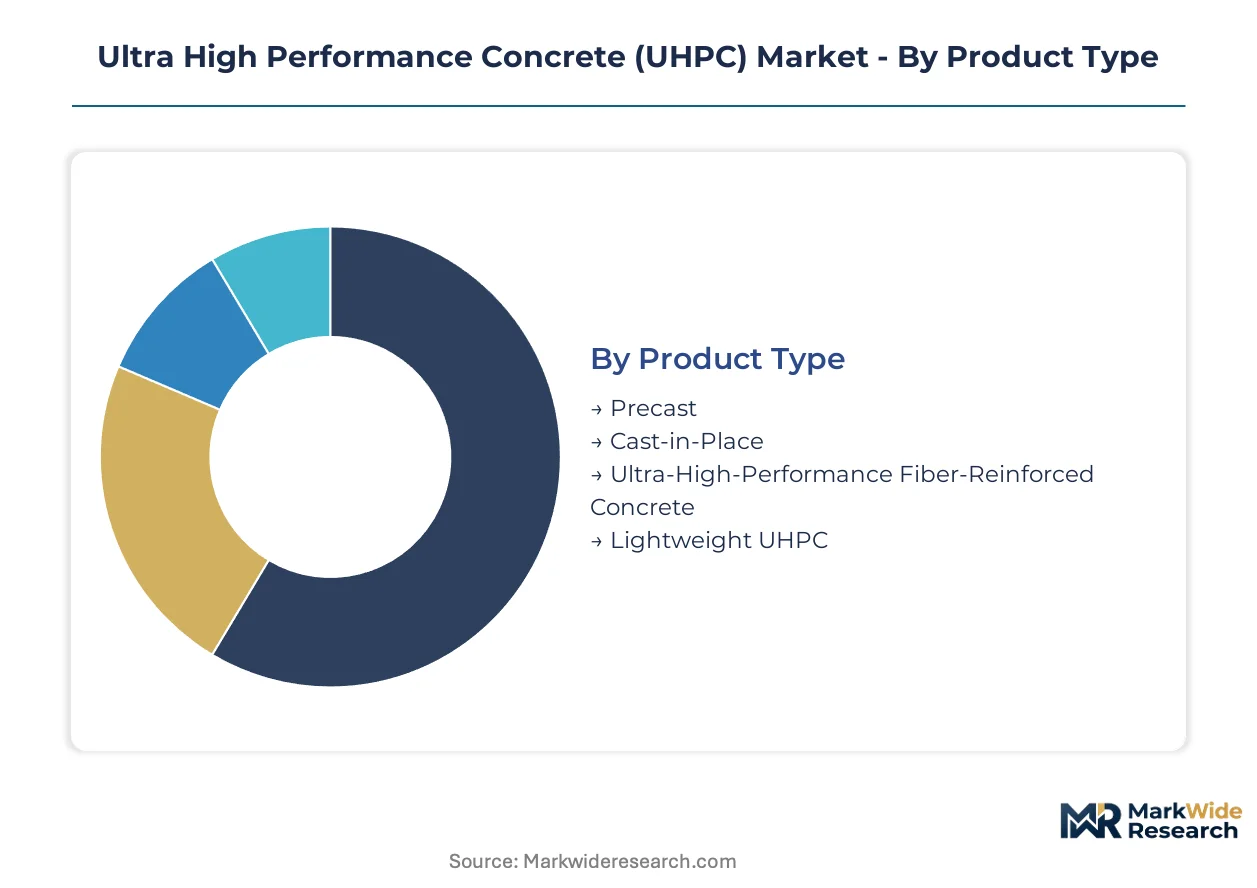
Segmentation in the UHPC market tracks where material science sophistication intersects with procurement complexity. Factory-controlled production dominates current volumes, while field placement techniques are expanding contractor participation. Distribution channels fragment across specification-driven public tenders and architect-led private developments.
Product Type:
Integration depth separates factory-cured systems requiring capital-intensive batching equipment from site-mixed formulations accessible to mid-tier contractors.
- Precast:Factory-cured elements achieve consistent hydration kinetics through controlled temperature and humidity regimes. German federal highway authorities specify precast deck panels for overnight span replacements on Autobahn corridors, compressing installation schedules and eliminating field variability.
- Cast-in-Place:Self-consolidating rheology enables complex geometries and retrofit overlays without formwork labor. California DOT contractors gain expertise in high-shear mixing for seismic column wrapping applications, though fiber alignment control remains a workforce training gap.
- Ultra-High-Performance Fiber-Reinforced Concrete:Steel fiber densities exceeding 2% by volume deliver post-cracking tensile capacity for blast-resistant structures.
- Lightweight UHPC:Expanded glass or shale aggregates reduce dead loads for vertical building envelope applications.
Precast leads volumes today; cast-in-place is gaining share fastest.
Application:
Cost tier stratification separates structural rehabilitation programs with public funding guarantees from speculative commercial construction exposed to development cycle volatility.
- Bridge Construction:Chloride resistance and freeze-thaw durability exceed EN 206 performance class thresholds for marine and alpine exposure zones. Transport Canada embeds UHPC into standard repair protocols for critical span elements across the national highway system.
- Building Facades:Thin-section panels deliver compression strengths exceeding natural stone at one-third the weight. Architects in dense urban cores specify UHPC cladding for speculative commercial towers where envelope performance drives leasing premiums.
- Overlays:Bonded resurfacing extends service life of deteriorated concrete substrates without full-depth replacement.
- Industrial Flooring:Abrasion resistance serves heavy manufacturing environments with concentrated wheel loads.
Bridge construction commands the premium tier; building facades show the steepest expansion trajectory.
End User:
Customer type determines specification authority—public agencies mandate certified compliance while private developers optimize for speed-to-occupancy.
- Construction Companies:Tier-one contractors with in-house batching capabilities capture performance-warranty contracts bundling material supply with 50-year service life guarantees.
- Infrastructure Developers:Public-private partnerships finance bridge rehabilitation through availability payments tied to asset condition metrics.
- Government Agencies:Federal and state DOTs embed UHPC into standard repair protocols, concentrating demand among pre-qualified producers.
- Private Developers:Commercial real estate sponsors specify UHPC for trophy assets where extended service life supports green building certifications.
Government agencies anchor procurement volumes; private developers are expanding most quickly.
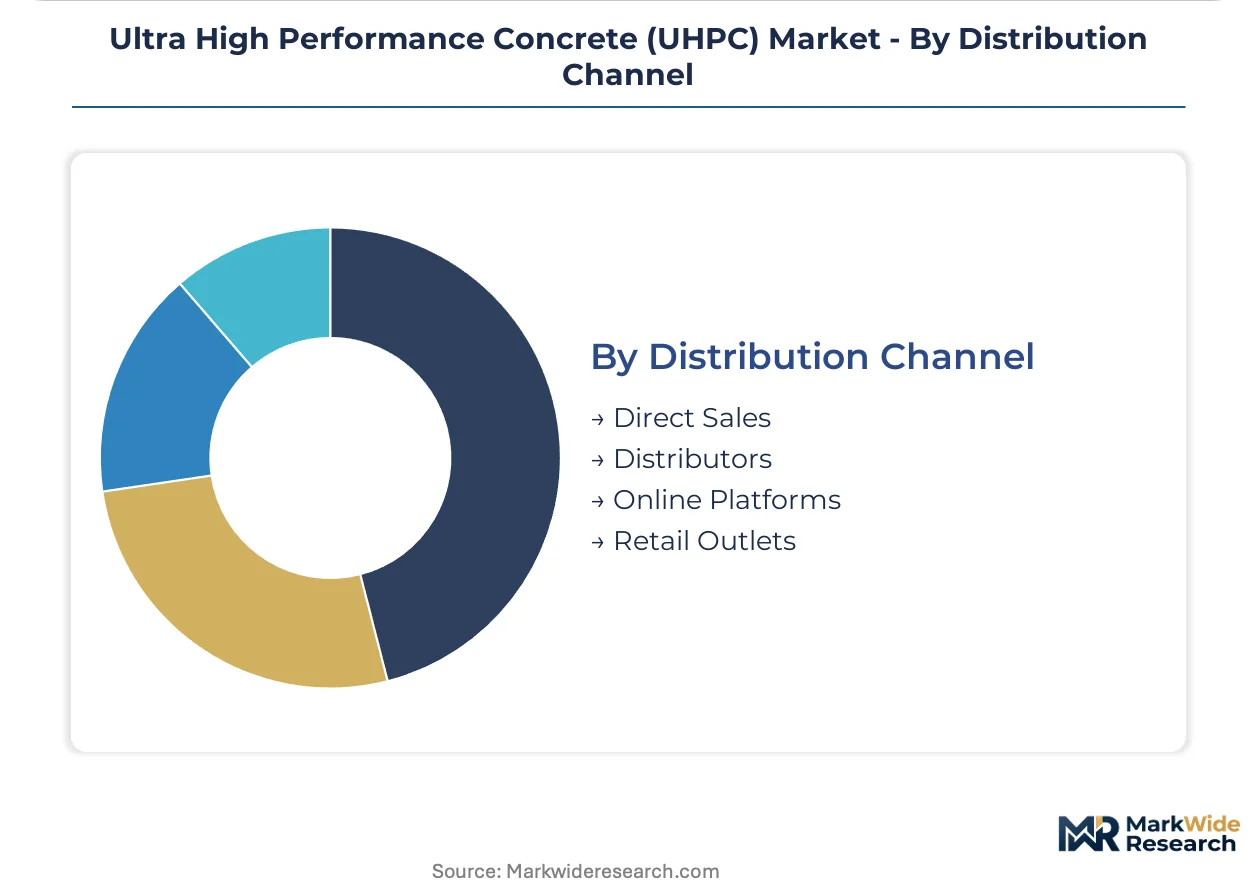
Distribution Channel:
Supply concentration favors direct relationships between producers and specification holders, marginalizing intermediaries in high-complexity applications.
- Direct Sales:Technical service engineers collaborate with design teams during pre-bid phases, locking in formulation approvals before tender submission.
- Distributors:Regional material handlers serve mid-size contractors for standardized precast elements with established engineering details.
- Online Platforms:Digital procurement portals streamline reordering of certified mixes for repeat public infrastructure clients.
- Retail Outlets:Limited to small-volume repair products and specialty admixtures for contractor experimentation.
Direct sales dominate specification-driven segments; distributors retain position in commoditized precast categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands infrastructure rehabilitation volumes while the United States concentrates bridge retrofit demand. Both markets embed UHPC into federal procurement protocols. China and Japan round out the geographic footprint with distinct specification regimes.
Germany
Federal highway authorities specify UHPC for critical Autobahn span replacements and deck overlays. EN 206 performance classes mandate chloride resistance thresholds that conventional concrete cannot satisfy. Industrial clusters in North Rhine-Westphalia and Bavaria host precast fabrication facilities serving overnight corridor replacement schedules.
United States
State DOTs in California, Florida, and coastal corridors accelerate bridge column wrapping specifications for seismic resilience. ACI 239 committee guidelines tighten fiber content minimums and durability testing protocols. Contractors in Texas gain expertise in self-consolidating placement techniques for complex retrofit geometries.
Canada
Transport Canada embeds UHPC into standard repair protocols for critical span elements across the national highway system. CSA S6 certification demands eighteen-month field performance validation before product approval. Quebec and Ontario infrastructure developers finance rehabilitation through availability payments tied to asset condition metrics.
Japan
METI guidelines for building resilience accelerate fiber-reinforced UHPC adoption in high-risk seismic corridors. Prefecture-level bridge authorities specify the material for alpine infrastructure exposure zones. Industrial concentration in the Chubu region around Nagoya supplies factory-cured elements for just-in-time delivery.
China
Metallurgical silicon producers in Henan and Sichuan control microsilica output essential for silica fume densification. GB standards for ultra-high-performance cementitious composites are converging toward EN 206 performance benchmarks. Yangtze River Delta infrastructure programs trial 3D-printed structural elements with self-consolidating UHPC rheology.
Ultra High Performance Concrete (UHPC) Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with specification-driven public tenders favoring established admixture portfolios while private developments prioritize speed-to-occupancy partnerships. The vendor base concentrates among chemical conglomerates with global R&D networks and regional precast operators with certified fabrication capabilities. Three archetypes dominate: integrated chemical suppliers controlling fiber-matrix bonding chemistry, multinational cement producers leveraging manufacturing scale, and specialized admixture formulators anchoring specification-driven procurement. Competitive moves center on backward integration into silica fume supply chains and strategic partnerships bundling material supply with performance warranties.
Within the integrated chemical supplier tier, BASF SE and Sika AG exemplify archetypes that anchor specification-driven procurement through global admixture portfolios. Lafarge occupies a position representing multinational cement producers with manufacturing scale across precast operations. These three companies sit within distinct competitive vectors—R&D intensity, manufacturing footprint, and technical service depth—without overlapping strategic positioning.
| Leading Market Players |
|---|
| BASF SE |
| GCP Applied Technologies Inc. |
| Sika AG |
| Buzzi Unicem S.p.A. |
| MAPEI S.p.A. |
| Holcim Ltd |
| Lafarge |
| VSL International SA |
| CEMEX |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap precast specialists across Bavaria and North Rhine-Westphalia anchor supply discipline through generational capital allocation, resisting price wars even when Norwegian silica fume costs spike. Their patient financing insulates EN 206-certified producers from quarterly margin pressure that erodes quality in commodity concrete markets.
Pricing Analysis
Capacity additions in China's Henan province are reshaping price floors for microsilica-densified formulations, pressuring European producers to differentiate through certified chloride-resistance performance. Project-based long-term contracting dominates, with price differentiation resting on EN 206 performance class certification and fiber content grade. Cost compression in standard-grade precast is intensifying because Chinese metallurgical silicon output feeds global spot markets. Government agencies show least price sensitivity due to 50-year lifecycle accounting; small regional contractors face greatest pressure from high-shear batching equipment capital requirements.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian and Chinese metallurgical silicon producers controlling over 70% of global microsilica output. Raw material dependencies center on silica fume densification agents, high-tensile steel fiber, and polycarboxylate superplasticizers. Tariff exposure runs through Sino-European trade corridors for critical densification inputs. Distribution runs through direct technical service relationships with federal highway authorities and state DOTs, marginalizing intermediaries in specification-driven segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ACI 239 committee revisions to fiber content minimums and durability testing protocols continuously elevate entry barriers and extend incumbent replacement cycles.
For Market Incumbents: Anticipate displacement risk from hybrid fiber systems that democratize cast-in-place expertise across mid-tier contractors. Defensive moves require backward integration into silica fume supply chains and captive certification laboratories to accelerate multi-jurisdictional approvals under ACI 239, EN 206, and CSA S6 simultaneously. For New Entrants and Emerging Players: Regional distributors serving Texas and Bavarian mid-size builders represent the most accessible channel for blended-fiber UHPC formulations requiring less specialist engineering support. White-space targets include 3D-printed structural elements for Yangtze River Delta infrastructure trials and lightweight UHPC panels for speculative commercial facades in dense urban cores. Go-to-market positioning should emphasize just-in-time delivery partnerships for overnight highway corridor replacements. For Investors and Strategic Acquirers: Integrated chemical suppliers with global admixture portfolios are the most active acquirer in this space, consolidating regional precast operators to secure specification-driven procurement relationships. Long-term viability hinges on carbon accounting alignment with EU Green Deal embodied carbon thresholds. Acquisition targets should display certified third-party validation capabilities and in-house testing infrastructure. The signal to watch is Transport Canada's CSA S6 certification timeline compression, which would accelerate market access for new formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Fume Supply | Norwegian metallurgical silicon producers face new competition from captive sourcing arrangements by BASF and Sika. |
| Multi-Jurisdictional Certification Investment | Producers navigating ACI 239, EN 206, and CSA S6 simultaneously fragment less-resourced competitors. |
| Hybrid Fiber System Development | Steel-polymer blends erode precast specialist monopolies by enabling contractor-tier cast-in-place adoption. |
| Performance Warranty Bundling | German engineering firms now carry 50-year liability, concentrating awards among vertically integrated suppliers. |
| 3D-Printed Structural Element Trials | Yangtze River Delta infrastructure programs test robotic extrusion with self-consolidating UHPC rheology. |
Research Approach
Coverage spans Germany, the United States, Canada, Japan, and China, with primary inputs from each market's infrastructure procurement ecosystem. The analysis combines structured interviews with federal highway authority specification engineers, state DOT materials directors, precast plant managers, and technical admixture R&D leads with secondary validation through EN 206 implementation guidelines, ACI 239 committee documentation, CSA S6 bridge standards, customs trade data for silica fume flows, and SEC filings from listed chemical conglomerates. Bottom-up volume estimates from certified producer capacities triangulate against top-down infrastructure spending allocations.
Rate-of-change decomposition separates volume growth into bridge rehabilitation mandate intensity, precast-to-cast-in-place mix shift, and regional specification adoption curves across the projection horizon. Segmentation dimensions modeled include factory-cured versus site-mixed production, chloride resistance performance tier, fiber content grade, and public versus private procurement channel. CAGRs derive from regression-weighted infrastructure spending forecasts and producer capacity expansion announcements. Industry-specific inputs include Transport Canada's 18-month CSA S6 field validation timeline and METI seismic retrofit program acceleration metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silica fume supply disruption, geopolitical trade corridor instability, and contractor workforce training gaps in fiber alignment control. Forecasts reflect documented assumptions about specification adoption rates and certification timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
South Africa Wall Putty Market