
 Drywall and Gypsum Board Market | 2026-2036
Drywall and Gypsum Board Market Size, Share, and Industry Trends Forecast 2026-2036
Drywall and Gypsum Board Market Analysis
The capital-intensity divergence between integrated gypsum miners and board-only fabricators is rotating competitive advantage toward upstream asset owners. Knauf Group leverages captive quarry access across multiple continents to sustain margin stability when raw material costs fluctuate. Georgia-Pacific LLC anchors its North American position through dense manufacturing scale and rail-linked distribution hubs. Saint-Gobain differentiates via specialty formulations that command specification in acoustic and fire-rated commercial assemblies.
Drywall and gypsum board consists of a gypsum plaster core pressed between thick paper facings, manufactured through continuous casting and drying processes that yield standard panels in thicknesses from 1/4 inch to 5/8 inch, serving primarily as interior wall and ceiling substrates in buildings. Fire-resistant board leads specification value in commercial high-rises where code mandates extend dwell-time ratings, while moisture-resistant board captures faster growth in healthcare and hospitality renovation projects where humidity control is critical. The 5/8 inch thickness segment occupies the dominant volume position in multi-family residential and commercial construction due to its superior sound attenuation and fire performance.
EPA regulations on synthetic gypsum sourcing, OSHA silica exposure limits in manufacturing, and ASTM C1396 product standards collectively shape material compliance costs and factory capital requirements for domestic producers. The EU Green Deal and associated embodied-carbon reporting rules are beginning to filter into import specifications for board products entering European construction supply chains. Stakeholders must monitor how evolving EPD requirements and regional quarry permitting delays reshape sourcing strategies and factory location decisions.
Market Dynamics
The EPA's lead-safe renovation rules and evolving green building codes are tightening material certification requirements while concentrating demand in Sun Belt states where housing starts and commercial retrofits accelerate.
Growth Catalysts
- Fire-rated panel mandates:Commercial high-rise codes in the United States extend dwell-time ratings, pulling specification toward Type X and Type C boards. Multi-family residential towers absorb these panels at accelerating rates.
- OSHA silica exposure limits:Manufacturing compliance investments favor scaled producers with capital to retrofit facilities, consolidating supply toward integrated quarry-to-board operators with captive gypsum sourcing.
- Healthcare humidity control:Moisture-resistant board captures renovation demand in hospitals and hospitality properties where ASTM C1396 moisture-resistant grades outperform standard panels in wet-zone applications.
Market Restraints
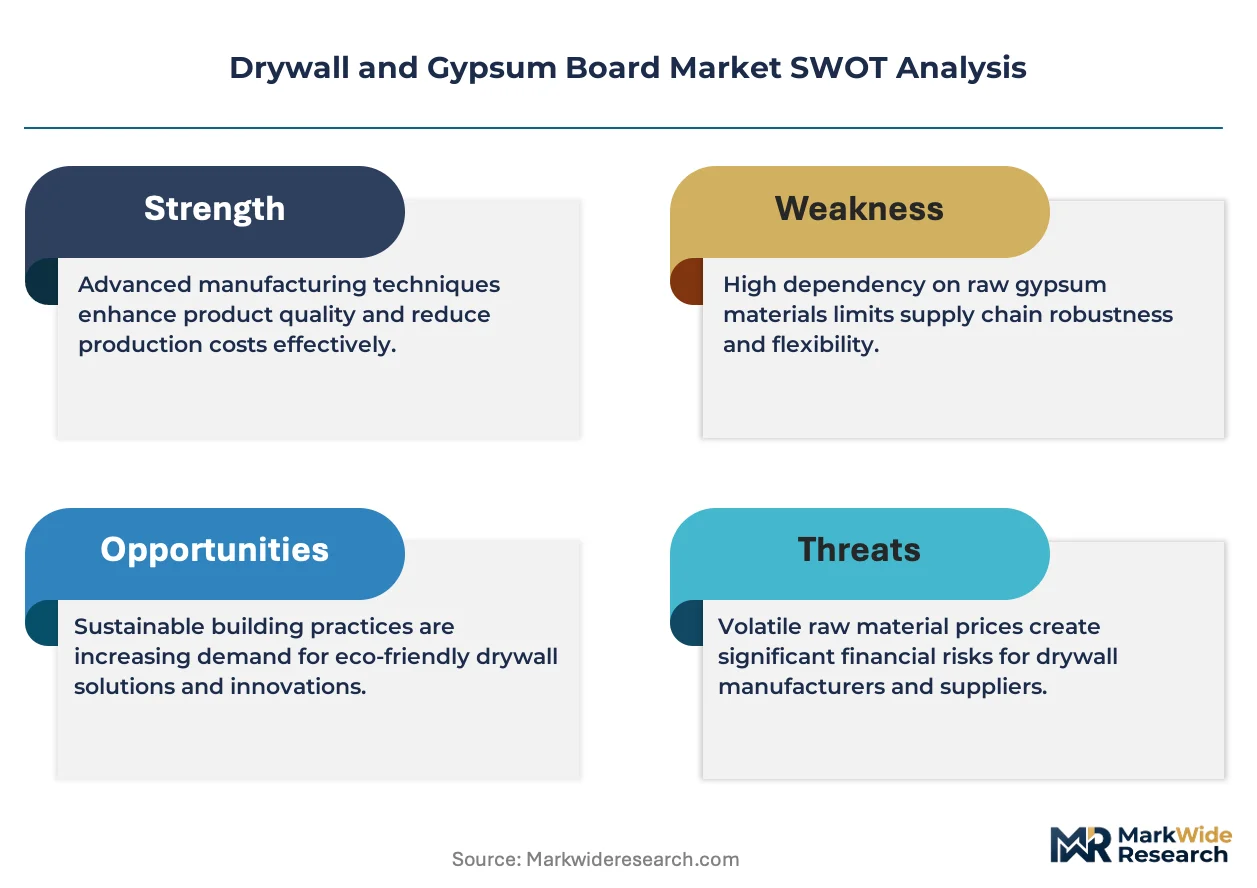
- Natural gas price volatility:Drying kilns consume substantial thermal energy; European producers face particular pressure from F-Gas Regulation compliance叠加 with energy cost spikes.
- Synthetic gypsum sourcing limits:EPA regulations on flue-gas desulfurization byproduct quality constrain alternative feedstock availability for board-only fabricators lacking captive quarries.
- Light-gauge steel framing substitution:Cold-formed steel stud systems in commercial construction reduce drywall surface area per linear foot of partition, compressing volume intensity in some building types.
Strategic Opportunities
- EU Green Deal embodied-carbon reporting:Import specifications for board products entering European construction supply chains reward producers with verified Environmental Product Declarations and low-carbon quarry operations.
- Prefabricated wall panel integration:Offsite construction modules incorporating pre-cut drywall layers create channel partnerships with modular fabricators, bypassing traditional distribution tiers.
- Acoustic specialty formulations:Open-plan commercial retrofits and multi-family sound transmission code upgrades drive specification of enhanced-density cores in Germany, France, and the United Kingdom.
Industry Challenges
- EPD certification timelines:Third-party verified environmental product declarations require 12-18 month validation cycles, delaying market access for reformulated low-carbon boards.
- Rail-linked distribution hub capital:Manufacturing scale economics demand heavy siding access and automated loading systems, locking out greenfield entrants without substantial infrastructure commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drywall and Gypsum Board Market |
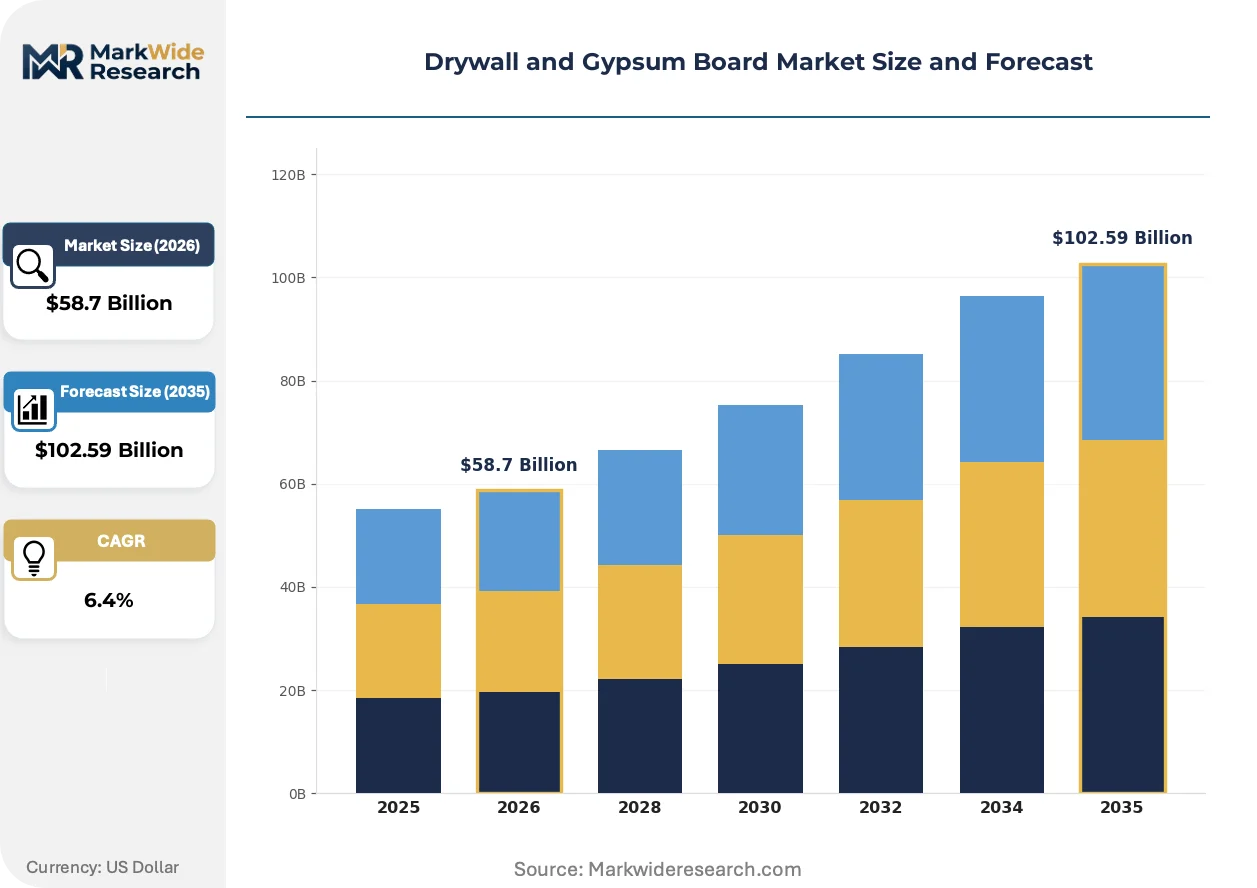
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Board, Moisture-Resistant Board, Fire-Resistant Board, Soundproof Board End User: Residential Construction, Commercial Construction, Industrial Applications, Renovation Projects Thickness: 1/4 inch, 3/8 inch, 1/2 inch, 5/8 inch Application: Interior Walls, Ceilings, Partitions, Exterior Sheathing |
| Companies Covered | Knauf Group, Etex Group, National Gypsum Company, PABCO Gypsum, American Gypsum Company LLC, USG Corporation, Georgia-Pacific LLC, CERTAINTEED, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drywall and Gypsum Board Market Emerging Trajectories
Product chemistry, regulatory disclosure requirements, and procurement centralization are compressing traditional competitive advantages while opening pathways for specialized formulations and direct channel relationships.
Glass-mat faced gypsum sheathing is displacing traditional paper-faced boards in exterior applications where moisture cycling and mold resistance matter. Multi-family developers in coastal United States markets specify these panels for elevator shafts and exterior soffits. The shift is compressing demand for conventional moisture-resistant paper-faced products in high-exposure zones.
REACH and associated ECHA substance restrictions on formaldehyde emissions and flame retardants are forcing reformulation of paper facings and core additives across European supply chains. Manufacturers serving Germany and France have accelerated low-emitting product line investments. The regulatory pressure is most acute in healthcare and school construction where indoor air quality certification schemes operate.
Consolidated national homebuilder procurement desks are compressing supplier rosters and demanding volume-tier pricing with embedded logistics services. Regional distributors in the United States Sun Belt face disintermediation as direct mill-to-site delivery contracts multiply. The procurement concentration is visible most clearly in Phoenix, Dallas-Fort Worth, and Atlanta metropolitan construction corridors.
Drywall and Gypsum Board Market Segmentation
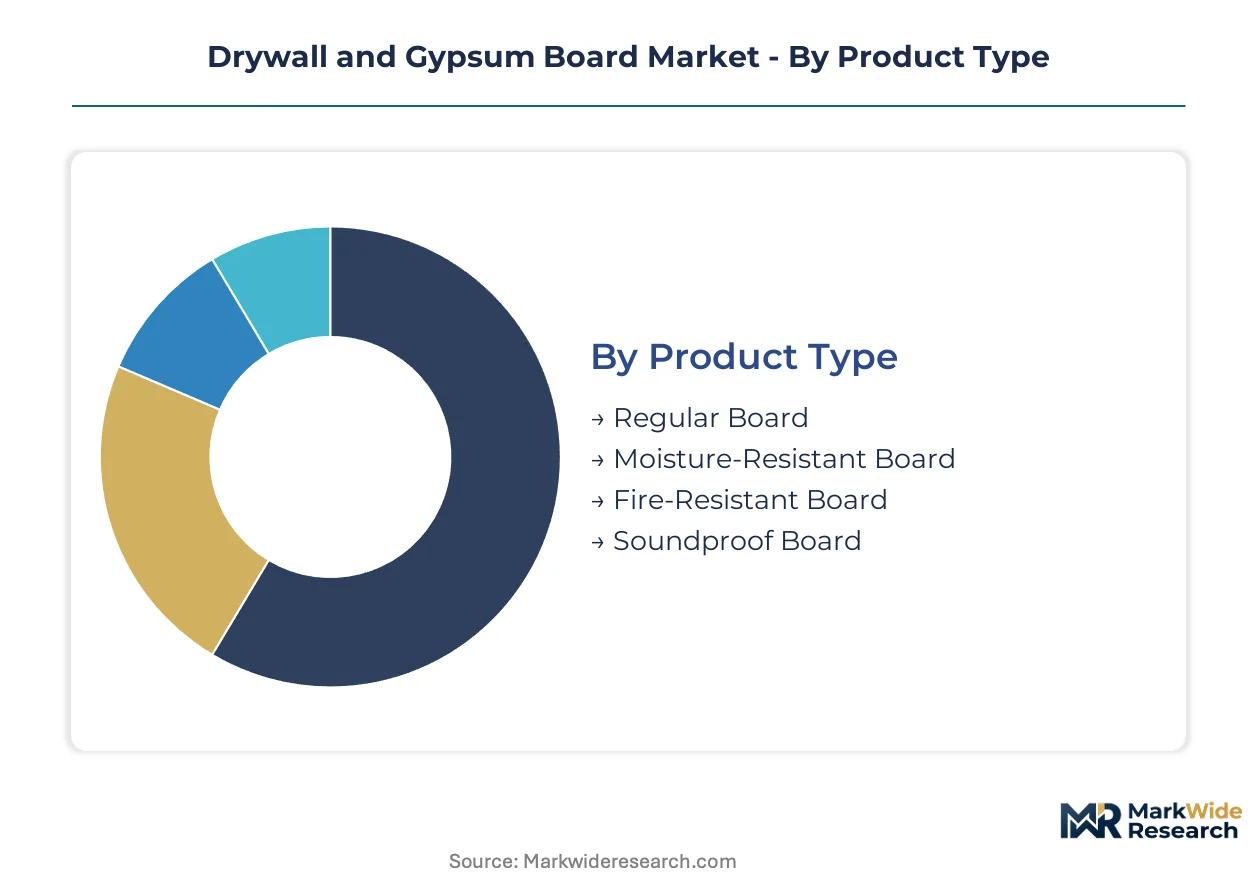
Segmentation in drywall and gypsum board reveals how regulatory codes, construction methods, and performance specifications fragment demand across technically distinct product categories. Each dimension carries implications for factory capital allocation, distribution density, and specification relationships with architect and contractor channels.
Product Type:
ASTM C1396 compliance tiers and EPA synthetic gypsum sourcing rules create divergent certification burdens across product lines, concentrating margin in formulations that satisfy multi-attribute code requirements.
- Fire-Resistant Board:Type X and Type C formulations incorporate glass fiber reinforcement and gypsum crystalline structure modifications to achieve extended dwell-time ratings. Commercial high-rise construction in United States Sun Belt cities absorbs these panels as building codes mandate enhanced fire performance for elevator shafts and occupancy separations.
- Moisture-Resistant Board:Wax emulsion additives and silicone-treated paper facings elevate core moisture tolerance above standard grades. Healthcare renovation corridors in humid climates specify these panels for wet-zone wall assemblies where humidity cycling degrades conventional board integrity.
- Regular Board:Unmodified gypsum plaster core with standard paper facings serves cost-sensitive residential volume construction.
- Soundproof Board:Enhanced-density cores and laminated construction attenuate sound transmission in multi-family residential towers.
Fire-Resistant Board handles the majority of throughput in commercial specification channels; Moisture-Resistant Board is the fastest mover on share as healthcare and hospitality retrofit activity accelerates.
End User:
Procurement scale and specification authority vary sharply across customer types, with national homebuilders consolidating supplier rosters while industrial buyers prioritize technical compliance documentation.
- Residential Construction:Single-family and multi-family housing starts drive volume absorption, particularly in suburban corridors where framing crews demand consistent board handling characteristics and predictable fastener retention.
- Commercial Construction:Office towers, retail shells, and institutional buildings specify fire-rated and acoustic assemblies with documented EPD credentials for LEED and BREEAM submissions.
- Renovation Projects:Healthcare and hospitality property upgrades concentrate demand for moisture-resistant and low-emitting formulations as indoor air quality certification schemes tighten material selection criteria.
- Industrial Applications:Manufacturing facilities and warehouse interiors require impact-resistant and clean-room-compatible board systems with specialized surface treatments.
Residential Construction maintains the deepest volume footprint; Renovation Projects are expanding most quickly as building stock age and energy retrofit mandates multiply project pipelines.
Thickness:
Dimensional selection directly determines fire rating achievement, sound attenuation performance, and structural spanning capability in wall and ceiling assemblies.
- 5/8 inch:Dominant specification in multi-family residential and commercial construction due to superior STC ratings and one-hour fire resistance without additional layering. United States building codes mandate this thickness for occupancy separations and shaft walls in structures exceeding four stories.
- 1/2 inch:Standard residential interior wall substrate balancing material cost against adequate nail-pull resistance and basic fire performance for single-family detached construction.
- 3/8 inch:Applied in curved surface applications and renovation overlays where minimal thickness addition preserves existing spatial dimensions.
- 1/4 inch:Specialized use for repair patches, curved archways, and laminate substrates requiring extreme flexibility.
5/8 inch thickness commands the specification premium in code-governed assemblies; 1/2 inch thickness delivers the highest unit volume in absolute terms across all construction categories.
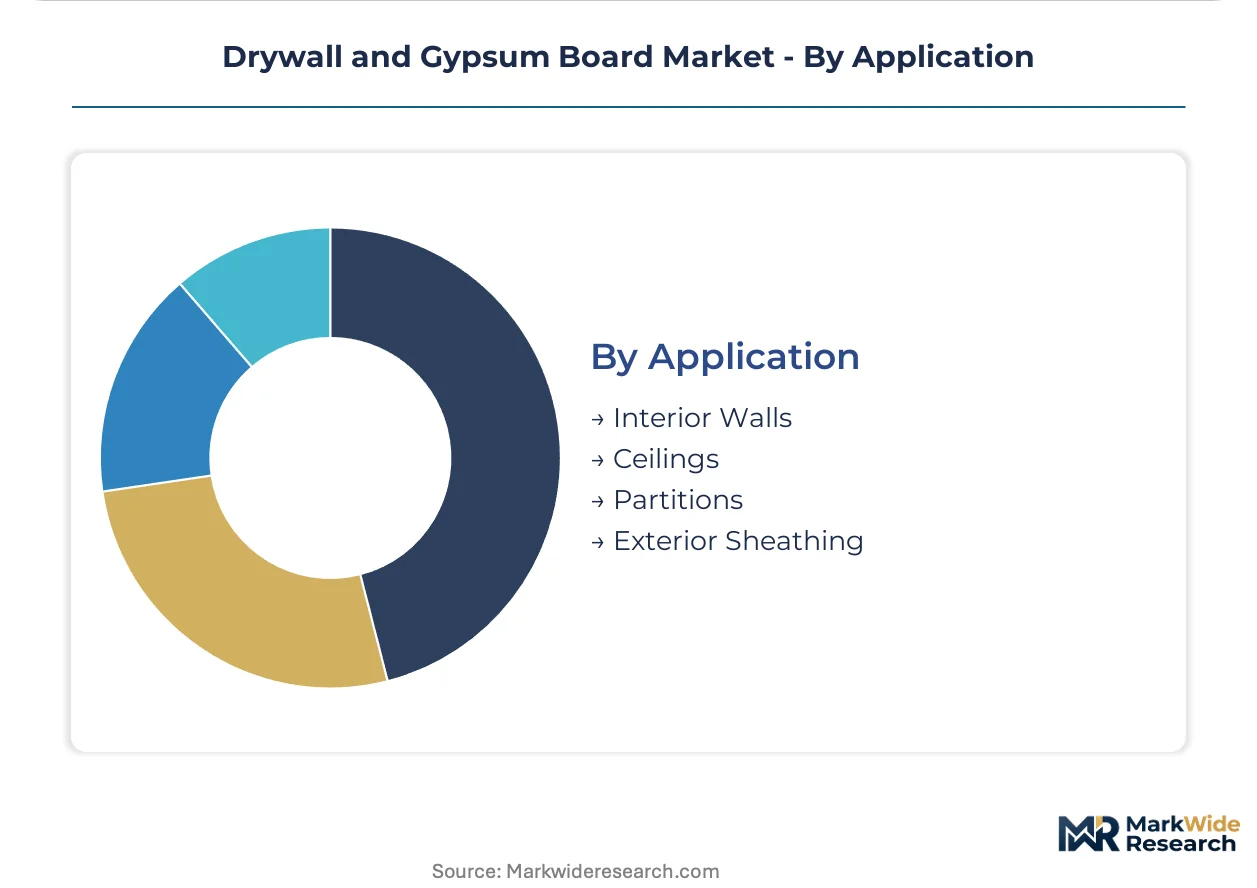
Application:
Exposure conditions and performance expectations fragment demand across interior and exterior use cases, with material substitution threats varying by assembly location.
- Interior Walls:Primary substrate for vertical surface finishing in residential and commercial buildings, absorbing the majority of gypsum board volume through standard and fire-rated specifications.
- Ceilings:Sag-resistant formulations address gravity loading and humidity exposure in horizontal applications, particularly in hospitality and healthcare corridors with stringent deflection limits.
- Exterior Sheathing:Glass-mat faced panels displace traditional paper-faced products in coastal United States markets where moisture cycling and mold resistance determine material survival.
- Partitions:Demountable and relocatable wall systems incorporate pre-cut board layers for flexible space planning in commercial tenant improvement cycles.
Interior Walls anchor absolute volume consumption; Exterior Sheathing is gaining share fastest as glass-mat technology penetrates high-exposure construction zones previously served by cement board and plywood.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive residential builders in suburban United States corridors absorb volume through distributor networks, while specification-driven commercial projects in Western Europe tolerate premium pricing for certified low-carbon formulations.
United States
Sun Belt housing starts in Phoenix, Dallas-Fort Worth, and Atlanta absorb fire-rated 5/8 inch panels at accelerating rates. EPA lead-safe renovation rules tighten material certification for retrofit contractors. Southeast manufacturing clusters near gypsum quarries in Oklahoma and Texas expand kiln capacity to serve coastal demand.
Germany
Multi-family acoustic code upgrades in Berlin and Munich pull enhanced-density core specifications. REACH formaldehyde emission limits force reformulation of paper facings and core additives. Industrial concentration in North Rhine-Westphalia anchors production of low-emitting grades for healthcare construction.
China
Urban renewal projects in tier-one cities specify moisture-resistant boards for high-humidity climates. GB standards on building energy efficiency tighten thermal performance requirements for interior assemblies. Yangtze River Delta manufacturing bases scale glass-mat faced sheathing for coastal high-rise applications.
United Arab Emirates
NEOM and Red Sea Project developments specify imported fire-rated assemblies for hospitality and commercial towers. Dubai building codes mandate enhanced fire performance for occupancy separations above twelve stories. Jebel Ali logistics corridors concentrate distribution hubs serving Gulf Cooperation Council retrofit cycles.
India
Affordable housing missions in Maharashtra and Gujarat absorb standard-grade boards through volume construction programs. BIS certification requirements for gypsum products tighten quality enforcement at state levels. Delhi-NCR commercial retrofit activity accelerates specification of moisture-resistant formulations for climate-controlled interiors.
Drywall and Gypsum Board Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialty formulators commanding specification premiums while integrated miners defend margin through captive quarry access. The market structures around three tiers: multinational integrated producers with continental quarry networks, regional scale fabricators dependent on purchased gypsum, and niche specialists in acoustic or low-emitting formulations. Dominant competitive moves include backward integration into quarry assets and direct mill-to-site delivery contracts that bypass traditional distribution.
Within the integrated multinational tier, Knauf Group and Saint-Gobain exemplify archetypes that combine captive gypsum sourcing with formulation specialization. Georgia-Pacific LLC occupies a position representing North American scale concentration through dense manufacturing footprints and rail-linked distribution infrastructure. These three anchors illustrate how upstream asset control separates margin-stable operators from board-only fabricators exposed to raw material volatility.
| Leading Market Players |
|---|
| Knauf Group |
| Etex Group |
| National Gypsum Company |
| PABCO Gypsum |
| American Gypsum Company LLC |
| USG Corporation |
| Georgia-Pacific LLC |
| CERTAINTEED |
| Saint-Gobain |
| Others |
Supply Flow & Price Mechanics
Kiln capacity utilization above eighty percent in Oklahoma and Texas manufacturing clusters compresses marginal cost curves for integrated producers while elevating price floors for board-only fabricators purchasing synthetic gypsum feedstock. Scale economics in rail-linked distribution anchor competitive position across Sun Belt residential corridors where national homebuilders consolidate procurement rosters.
Pricing Analysis
After-sales logistics and jobsite delivery bundling drives lifetime value retention among national homebuilder accounts. Three-tier pricing structure across premium fire-rated, standard moisture-resistant, and economy regular grades reflects ASTM certification burden and gypsum sourcing security. Pricing pressure stems from synthetic gypsum supply constraints under EPA flue-gas desulfurization rules. Residential volume builders exhibit highest price sensitivity; commercial specification channels tolerate premium positioning for documented EPD credentials.
Supply Chain Analysis
Just-in-time inventory preferences dominate among Sun Belt framing contractors while strategic stockpiling of fire-rated panels occurs ahead of code enforcement windows in multi-family towers. Manufacturing concentrates in the United States, Germany, and China with captive quarry access differentiating margin stability. Raw material flows draw from natural gypsum deposits, synthetic gypsum byproduct, and glass fiber reinforcement. Single-source vulnerability in rail-car availability elevates logistics risk. Distribution runs through mill-direct contracts and regional distributor networks serving contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quarry permitting expertise and kiln retrofit capital represent scarce capabilities that separate margin-stable integrated operators from exposed board-only fabricators. The market rewards upstream asset control and specification-grade formulation chemistry.
For Market Incumbents: Secure captive gypsum reserves in Oklahoma and Texas corridors to defend feedstock cost position against synthetic gypsum sourcing limits. Reinforce mill-direct delivery contracts with national homebuilders in Phoenix and Atlanta to lock out distributor-tier competition. Glass-mat sheathing technology threatens traditional moisture-resistant paper-faced products; accelerate R&D in exterior-grade formulations. For New Entrants and Emerging Players: Differentiate on low-carbon quarry operations with verified Environmental Product Declarations targeting EU Green Deal import specifications. Prefabricated wall panel partnerships with modular fabricators in Dallas-Fort Worth represent the most penetrable white-space channel. Lead with acoustic specialty formulations for Berlin and Munich multi-family retrofits where code upgrades drive enhanced-density core demand. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with rail-linked distribution hubs serving consolidated national builder accounts. Long-term viability hinges on backward integration into quarry assets and formulation specialization in fire-rated or low-emitting grades. Watch for EPD certification timeline compression as inflection signal; accelerated validation cycles would advantage reformulated low-carbon board producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive gypsum sourcing insulates margin from EPA synthetic gypsum quality constraints. |
| Fire-Rated Formulation Expansion | Type X and Type C boards command specification premium in Sun Belt high-rise codes. |
| Mill-Direct Delivery Contracts | Bypassing distributor tiers captures procurement consolidation among national homebuilders. |
| EPD Certification Investment | Verified environmental declarations unlock EU Green Deal import channel access. |
| Glass-Mat Sheathing Scale-Up | Exterior-grade panels displace cement board in coastal United States moisture-exposure zones. |
Methodological Framework
Cross-validation between plant manager interviews and SEC 10-K filings anchors the qualitative findings on manufacturing scale economics. Primary fieldwork encompassed gypsum quarry operators, board plant technical directors, national homebuilder procurement leads, and regional distributor sales heads. Secondary sources integrated EPA enforcement data, ASTM standards documentation, customs trade records, and building permit databases. Bottom-up capacity utilization estimates and top-down construction spending trajectories were reconciled across the analysis.
Sensitivity analysis tested forecast robustness against natural gas price volatility and synthetic gypsum supply disruption scenarios. Segmentation dimensions modeled include product type, thickness specification, end-use construction category, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and new construction absorption rates. Industry-specific inputs incorporated housing start permits, commercial square footage pipelines, and code adoption timelines for fire-rated assemblies.
Decision-makers should treat outputs as directional under stable regulatory enforcement and quarry permitting assumptions; material deviation would warrant model refresh. Forecasts reflect construction activity trajectories and energy cost baselines without contingency for tariff restructuring or accelerated green building code adoption. Revision becomes warranted when EPA synthetic gypsum quality thresholds tighten beyond current compliance windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market