
 Concrete Conditioner Market | 2026-2036
Concrete Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Conditioner Market Outlook
The gap between silane-siloxane penetrating sealers and traditional film-forming acrylic coatings is narrowing as nano-modified formulations achieve comparable water repellency with vapor permeability advantages. Sika AG leverages its European formulation heritage to dominate specification-driven infrastructure tenders across Central Europe. BASF SE anchors its position through backward integration into specialty silane intermediates, securing supply continuity for high-purity concrete conditioners. Fosroc International Limited competes on technical service intensity, embedding field engineers directly within contractor workflows in the Middle East and Southeast Asia.
Concrete conditioners comprise chemical treatments—typically silanes, siloxanes, lithium silicates, or fluoropolymers applied at 50–400 g/m²—that penetrate cementitious substrates to reduce permeability, inhibit chloride ingress, or harden surfaces through densification. Liquid formulations lead volume consumption due to spray-applied efficiency on horizontal infrastructure decks, though gel variants command premium positioning for vertical and overhead repair environments where runoff control matters. The organic formulation segment sustains the largest revenue pool given mature acrylic and polyurethane chemistries, while bio-based alternatives occupy an emerging niche as public procurement rules in France and the Netherlands begin rewarding renewable content thresholds.
EPA VOC regulations for architectural coatings constrain solventborne product distribution in the United States, while REACH registration requirements in Europe elevate compliance costs for imported silane precursors. ISO 9001 quality management and CE marking under the Construction Products Regulation shape market access trajectories for suppliers targeting cross-border public works contracts. Stakeholders must monitor how evolving green public procurement criteria redefine specification eligibility across OECD infrastructure programs.
Market Dynamics
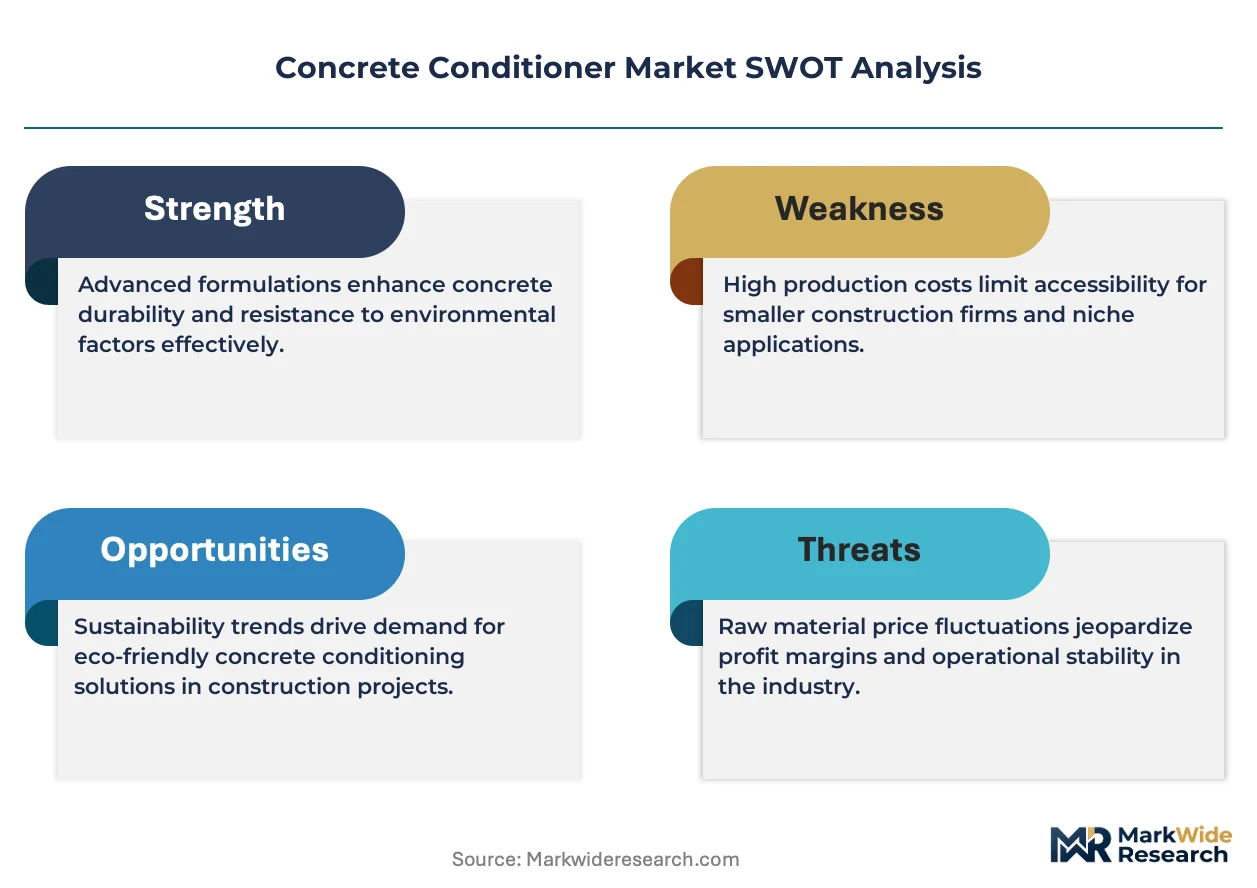
Infrastructure rehabilitation across aging highway networks is pulling specification-grade silane sealers into public procurement pipelines faster than film-forming alternatives can adapt. Federal maintenance budgets in Germany and the United States now prioritize surface life-extension over full concrete replacement, compressing contractor decision cycles toward penetrating chemistries.
Growth Catalysts
- EPA VOC limits:The EPA's tightening volatile organic compound ceilings for architectural coatings are forcing formulators toward waterborne and silane-based penetrating sealers in the United States.
- Bridge deck rehabilitation:State departments of transportation across the United States are accelerating procurement of chloride-resistant treatments as inspection cycles reveal accelerating rebar corrosion.
- Nano-modified siloxanes:These advanced formulations achieve vapor-permeable water repellency previously requiring solventborne acrylics, opening specification access in environmentally restricted jurisdictions.
Market Restraints
- Specialty silane supply concentration:High-purity silane intermediate production clusters in Germany and China, exposing formulators to freight cost volatility and REACH registration compliance burdens for European imports.
- Film-forming acrylic substitution threat:Lower-cost acrylic coatings retain share in private commercial construction where vapor permeability carries less specification weight.
- REACH registration costs:ECHA requirements elevate compliance expenditures for silane precursors, compressing margins for mid-scale formulators lacking backward integration into specialty intermediates.
Strategic Opportunities
- Bio-based procurement incentives:Green public procurement rules in France and the Netherlands are beginning to reward renewable content thresholds, creating specification advantages for bio-based conditioner developers.
- Gel formulation vertical applications:Gel variants command premium positioning for overhead repair environments where runoff control matters, an underdeveloped segment relative to liquid spray applications.
- CE marking under CPR:Construction Products Regulation compliance opens cross-border public works access across EU member states, rewarding early certification investment with specification pipeline visibility.
Industry Challenges
- Field application certification gaps:Contractor workflows require embedded technical support for proper surface preparation and cure monitoring, straining manufacturer service capacity during peak infrastructure seasons.
- ISO 9001 quality system maintenance:Public tender eligibility increasingly demands documented quality management systems, imposing documentation burdens on smaller regional applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Conditioner Market |
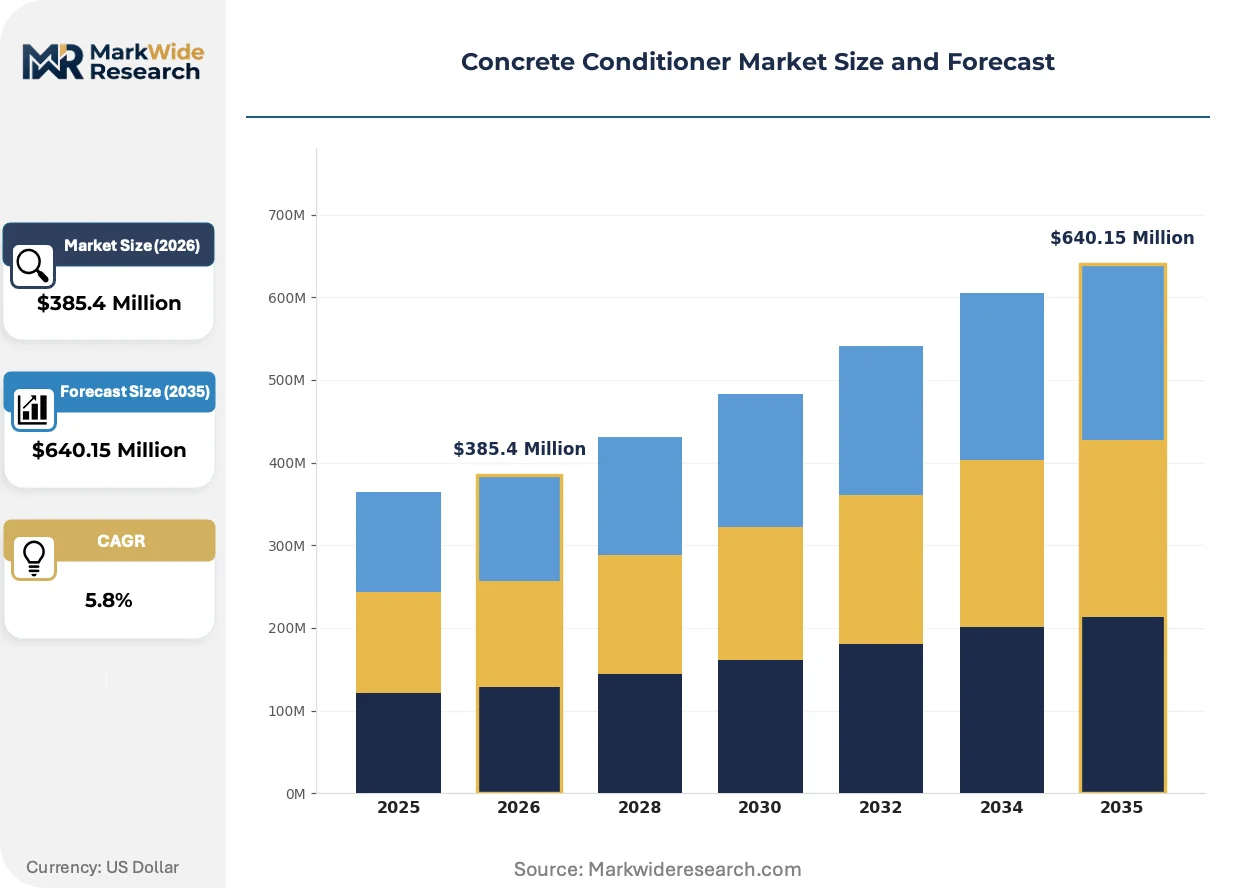
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Emulsion Application: Residential, Commercial, Industrial, Infrastructure Formulation: Organic, Inorganic, Bio-based, Synthetic Delivery Mode: Direct Application, Spray, Brush, Roller |
| Companies Covered | BASF SE, Sika AG, PPG Industries, 3M, The Sherwin-Williams Company, RPM International Inc., Fosroc International Limited, Mapei S.p.A., The Euclid Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Conditioner Market Strategic Shifts
Formulation chemistry is pivoting toward nano-scale modification while regulatory pressure on volatile content accelerates waterborne platform development. Specification authority is migrating from general contractors to asset owners demanding performance warranties.
Nano-silica modified siloxane technology is migrating from laboratory validation to highway department approval lists. State DOT engineers in the United States are specifying these treatments for bridge decks where chloride ingress resistance must coexist with vapor permeability. The technology is migrating from premium commercial applications to standard infrastructure procurement, compressing the price premium traditionally commanded by fluoropolymer alternatives.
REACH registration requirements for silane precursors are tightening supply chain documentation obligations across European formulators. ECHA compliance timelines are extending raw material qualification cycles, forcing smaller blenders toward distributor relationships with registered importers. Silane-based penetrating sealers face the steepest compliance cost escalation, advantaging formulators with captive silane production or long-term supplier contracts predating 2018 registration deadlines.
Asset owner procurement departments are consolidating specification authority previously dispersed among general contractors and construction managers. State infrastructure agencies in Germany and the United States now mandate direct-approved product lists with performance warranty requirements, bypassing traditional contractor material substitution flexibility. This concentration is most visible in federal highway maintenance contracts where life-cycle cost modeling overrides first-cost considerations.
Concrete Conditioner Market Segmentation
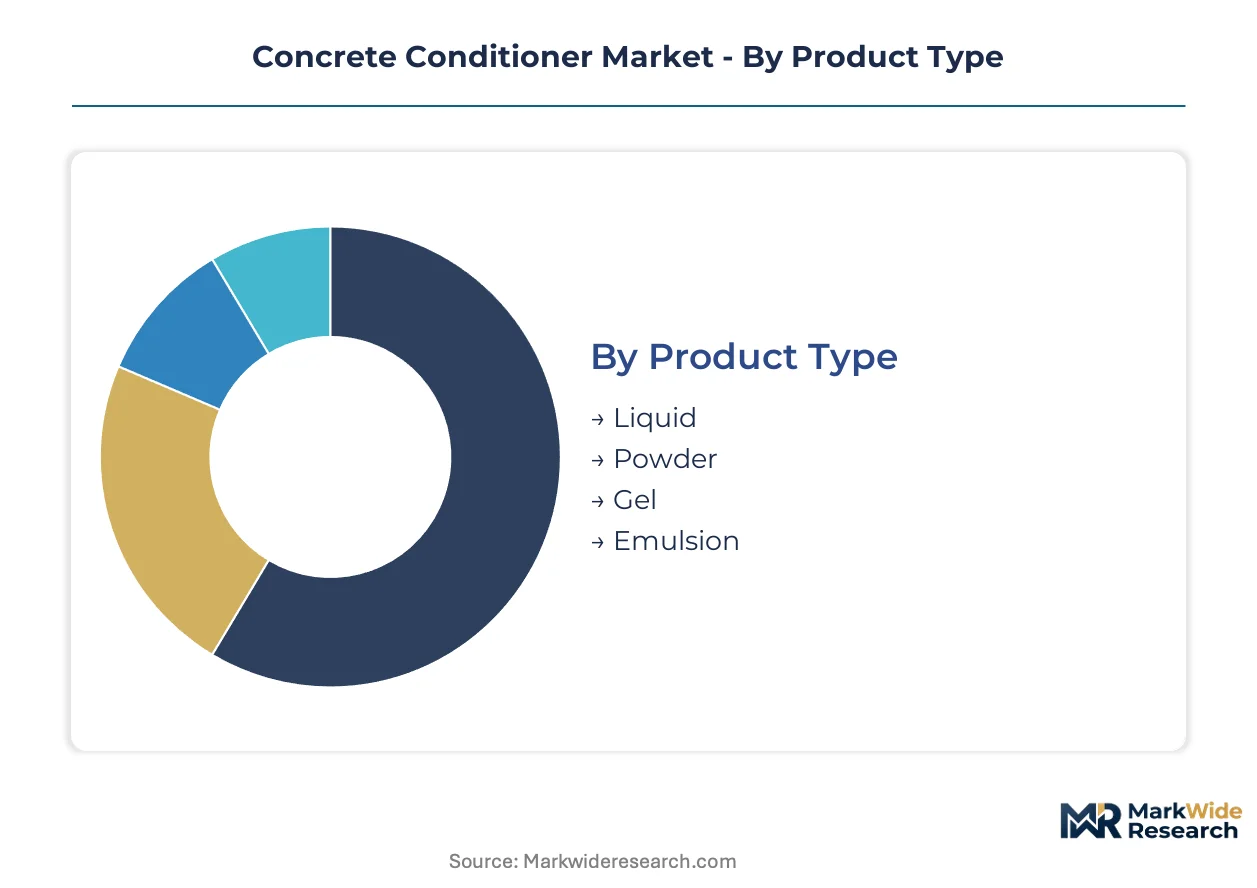
Concrete conditioner segmentation reflects divergent technical requirements across surface preparation methods, substrate conditions, and environmental compliance pressures. Specification-grade infrastructure projects demand penetrating chemistries incompatible with decorative residential applications, fragmenting procurement channels and margin structures.
Product Type:
Surface geometry and accessibility dictate product viscosity selection across horizontal decks, vertical facades, and overhead repairs.
- Liquid:Low-viscosity silane and siloxane solutions penetrate dense concrete substrates through spray application at 50–200 g/m² coverage rates. State transportation departments in the United States specify liquid penetrating sealers for bridge deck rehabilitation where chloride ingress resistance must coexist with vapor permeability.
- Gel:Thixotropic formulations cling to vertical and overhead surfaces without runoff, commanding premium positioning in structural repair environments. German federal transport maintenance budgets prioritize gel applications for tunnel lining refurbishment where access constraints eliminate spray alternatives.
- Powder:Dry-blend lithium silicates require on-site water activation, suiting remote infrastructure sites with limited liquid storage capacity.
- Emulsion:Waterborne acrylic dispersions balance VOC compliance with film-forming protection in commercial building envelope applications.
The dominant share belongs to Liquid formulations, while Gel variants are closing the gap fastest as infrastructure rehabilitation intensifies.
Application:
Asset ownership structures and performance warranty requirements reshape procurement authority across construction verticals.
- Infrastructure:Highway agencies and bridge authorities mandate silane-based penetrating treatments with documented chloride ingress resistance. Federal maintenance budgets in Germany and the United States compress contractor substitution flexibility through approved product lists.
- Commercial:Property developers balance first-cost constraints with insurance-driven durability requirements in parking structures and building envelopes.
- Industrial:Chemical processing facilities specify fluoropolymer sealers for extreme pH exposure and thermal cycling resistance.
- Residential:Decorative concrete contractors favor film-forming acrylics for aesthetic enhancement over vapor-permeable protection.
Infrastructure commands specification authority, though Commercial applications are expanding most quickly as building envelope codes tighten.
Formulation:
Regulatory pressure on volatile organic content accelerates chemistry migration while REACH compliance elevates raw material qualification burdens.
- Organic:Acrylic and polyurethane chemistries dominate film-forming applications with mature supply chains and established contractor familiarity. EPA VOC limits for architectural coatings constrain solventborne organic distribution in the United States, forcing formulators toward waterborne platform development.
- Inorganic:Silane, siloxane, and lithium silicate penetrating treatments reduce permeability through chemical reaction with cementitious substrates rather than surface film formation.
- Bio-based:Plant-derived resin systems occupy an emerging niche as French and Dutch green public procurement rules begin rewarding renewable content thresholds.
- Synthetic:Fluoropolymer formulations deliver premium water and oil repellency for specialized industrial exposure conditions.
Organic formulations retain volume leadership, while Bio-based alternatives are gaining share fastest on procurement incentive tailwinds.
Delivery Mode:
Application equipment requirements and labor skill availability segment contractor capability and project scalability.
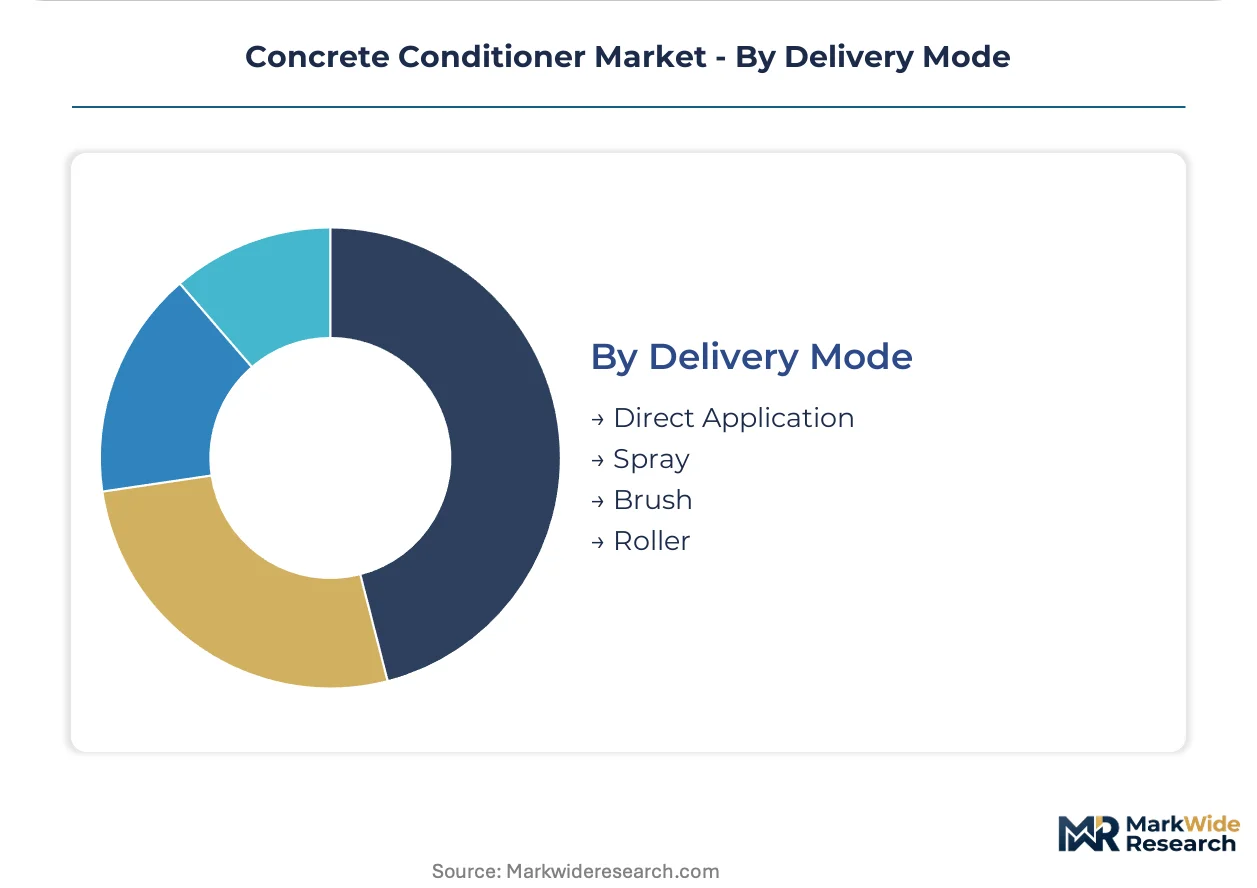
- Spray:Airless and low-pressure spray systems dominate horizontal infrastructure decks with coverage efficiency exceeding 1,000 m² per crew day. State DOT specifications in the United States increasingly require spray-applied penetrating sealers for bridge maintenance contracts.
- Direct Application:Flood-coat and saturation techniques ensure complete substrate penetration in critical structural elements.
- Brush:Hand-applied precision suits detail work and small-area repairs where equipment mobilization is uneconomical.
- Roller:Medium-nap roller application balances coverage speed with material control in commercial flooring environments.
Spray application holds the dominant position, though Direct Application methods are climbing fastest as performance warranty requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-purity silane intermediates tilts trade balances toward Germany and China, while infrastructure rehabilitation budgets in the United States and federal transport maintenance allocations in Germany concentrate demand for penetrating sealers.
United States
State transportation departments accelerate bridge deck rehabilitation contracts specifying chloride-resistant penetrating treatments. EPA VOC limits for architectural coatings constrain solventborne product distribution, pushing formulators toward waterborne silane platforms. Gulf Coast petrochemical corridors near Houston supply specialty silane feedstocks for domestic conditioner manufacturing.
Germany
Federal transport maintenance budgets prioritize concrete life-extension treatments over full replacement, compressing contractor procurement cycles. REACH registration requirements for silane precursors elevate compliance costs for imported intermediates, advantaging domestic producers with captive supply chains. Industrial clusters in North Rhine-Westphalia concentrate formulation expertise for infrastructure-grade penetrating sealers.
China
High-purity silane intermediate production clusters in eastern coastal provinces expose global formulators to freight cost volatility and dual carbon policy compliance pressures. MEE environmental inspections tighten manufacturing emissions standards for silane production facilities. Yangtze River Delta chemical parks anchor siloxane conditioner export capacity serving Southeast Asian infrastructure markets.
France
Green public procurement rules reward renewable content thresholds in concrete conditioner specifications for public works contracts. ANSM and environmental agencies coordinate enforcement of construction product sustainability criteria. Paris-region infrastructure agencies mandate performance warranty requirements for bridge maintenance treatments, bypassing contractor substitution flexibility.
United Arab Emirates
MOHAP and federal construction codes drive specification of fluoropolymer sealers for extreme thermal cycling exposure in coastal infrastructure. Mega-project procurement in Dubai and Abu Dhabi concentrates demand for premium-grade penetrating treatments with documented durability warranties. Local formulation capacity remains limited, sustaining import dependence for specification-grade silane products.
Concrete Conditioner Market Competitive Environment
On the supply side, the industry is moderately consolidated around integrated chemical conglomerates and specialized construction chemical subsidiaries. Three strategic archetypes dominate: backward-integrated silane producers securing feedstock autonomy, technical-service-intensive regional specialists embedding field engineers with contractors, and diversified coatings manufacturers leveraging distribution scale. Competitive moves concentrate on M&A for specialty silane capacity and geographic expansion through distributor partnerships in Middle Eastern and Southeast Asian infrastructure markets.
Among European-integrated chemical groups, BASF SE and Sika AG exemplify divergent positioning strategies—BASF anchors supply security through in-house production of specialty silane intermediates, while Sika leverages technical specification heritage to dominate infrastructure tender pipelines. Fosroc International Limited occupies a service-intensive archetype, embedding application engineering directly within contractor workflows across emerging market geographies. These three represent the dominant competitive vectors: feedstock control, specification authority, and field-service intensity.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| PPG Industries |
| 3M |
| The Sherwin-Williams Company |
| RPM International Inc. |
| Fosroc International Limited |
| Mapei S.p.A. |
| The Euclid Chemical Company |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's specialty silane production clusters concentrate feedstock supply for European formulators, translating upstream capacity tightness into pricing leverage for backward-integrated producers during infrastructure procurement cycles. REACH registration costs for imported intermediates compound this dynamic, compressing margin flexibility for blenders lacking captive silane supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium specification-grade, standard commercial-grade, and economy film-forming tiers. Price differentiation hinges on certification level—CE marking under CPR and ISO 9001 quality systems command measurable premiums—and volume scale commitments from state transportation departments. Cost compression in the standard tier is intensifying as nano-modified siloxanes displace fluoropolymer alternatives. State DOT procurement officers exhibit lowest price sensitivity due to life-cycle cost modeling mandates, while residential decorative contractors face acute budget constraints.
Supply Chain Analysis
Export-control scrutiny on fluorochemical precursors and dual-use silane technologies constrains cross-border flows of high-purity intermediates. Geographic supply concentration centers on Germany, China, and the United States, with specialty silane production drawing from chlorosilane feedstocks and lithium carbonate for densifier applications. Single-source vulnerability persists for REACH-registered silane precursors where ECHA compliance timelines extend qualification cycles. Distribution runs through construction chemical distributors and direct specification sales to infrastructure agencies, with technical service bundling increasingly standard.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as asset owner procurement departments consolidate specification authority, bypassing traditional contractor substitution flexibility and creating niche openings for certified specialists.
For Market Incumbents: Pre-empt margin erosion from nano-siloxane substitution by accelerating backward integration into specialty silane intermediates or securing decade-long supplier contracts predating registration deadlines. Embed field engineers within contractor workflows to defend against technical-service-intensive competitors like Fosroc. CE marking investment opens cross-border EU tender pipelines before smaller rivals qualify. For New Entrants and Emerging Players: Southeast Asian infrastructure markets, particularly Vietnam and Indonesia, exhibit underpenetration for specification-grade penetrating sealers relative to rehabilitation budget growth. Target gel formulation vertical applications where runoff control requirements and premium positioning reduce price competition from liquid spray incumbents. Partner with established distributors holding existing state DOT relationships rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH compliance burdens and raw material qualification cycles favor scaled formulators with captive supply chains or registered importer relationships. Acquisition target archetype: mid-scale European blenders with CE-marked product portfolios and dormant infrastructure agency approvals. Monitor ECHA registration renewal timelines as inflection indicators for supply chain restructuring pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Intermediates | Secures supply continuity for high-purity conditioners as REACH registration costs escalate. |
| CE Marking Certification Investment | Unlocks cross-border public works access across EU member states under Construction Products Regulation. |
| Gel Formulation Capacity Addition | Captures premium positioning in tunnel and overhead repair environments where spray application fails. |
| Technical Service Team Expansion | Embeds application engineers within contractor workflows to differentiate beyond commodity chemistry. |
| Bio-Based Platform Development | Aligns with French and Dutch green procurement rules rewarding renewable content thresholds. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with construction chemical plant managers, state DOT procurement officers, infrastructure contractor project directors, and specialty silane distribution channel partners; and secondary validation through customs trade data, ECHA REACH registration databases, SEC construction chemical segment filings, and federal transportation maintenance budget appropriations. Bottom-up volume triangulation across product type, application, and formulation segments was cross-checked against top-down market sizing from raw material consumption patterns.
Forecast inputs considered infrastructure rehabilitation pipeline visibility, EPA VOC regulatory trajectory, and REACH registration renewal schedules across the projection horizon. Segmentation dimensions modeled include product viscosity tier, asset ownership structure, chemistry platform, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections tied to documented federal maintenance budget growth rates and bridge deck inspection cycle data.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese silane producers or accelerated bio-based procurement mandates would shift outcomes. Material shifts in ECHA enforcement intensity or state DOT warranty requirement adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market