
 Cable Wrapping Tapes Market | 2026-2036
Cable Wrapping Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Wrapping Tapes Market Analysis
REACH is hardening material compliance thresholds across European cable tape supply chains. 3M Company leverages its fluoropolymer expertise to sustain premium positioning in aerospace-grade insulation. Nitto Denko Corporation anchors its competitive stance through deep automotive OEM relationships in Japan and Southeast Asia.
Cable wrapping tapes are pressure-sensitive or heat-bonded laminates, typically 0.1–0.5 mm thick, composed of woven fabrics, polymer films, or rubberized backings coated with acrylic, silicone, or rubber adhesives; they provide electrical insulation, mechanical abrasion resistance, and environmental sealing for wire bundles operating between -40°C and 130°C. PVC formulations still dominate volume in general electrical applications due to cost efficiency, though polyethylene tapes capture expanding share in telecommunications where low-smoke zero-halogen specifications command margin premiums. Wire harness applications for electric vehicles represent the fastest-growing structural segment, pulling specialized cloth and rubber tapes into thermal-management-intensive architectures.
FDA scrutiny of polymer additives in consumer-facing electronics, EPA guidelines on volatile organic compound emissions from adhesive coatings, and EU RoHS substance restrictions collectively reshape formulation roadmaps and qualification timelines for tape suppliers. China's GB standards on flame-retardant cable materials add a fourth compliance layer for manufacturers serving export and domestic markets simultaneously. Stakeholders must monitor how evolving halogen-free mandates across multiple jurisdictions will redistribute qualification costs and sourcing advantages among integrated versus non-integrated suppliers.
Market Dynamics
Electric vehicle wiring harness architectures are pulling specialized thermal-management tapes into high-voltage battery zones, forcing suppliers to requalify adhesive chemistries for sustained 150°C operation.
Growth Catalysts
- REACH compliance deadlines:European ECHA enforcement is accelerating halogen-free tape adoption across automotive wire harness supply chains, compressing qualification timelines for incumbent PVC formulations.
- China's cable production scaling:Domestic manufacturers in Jiangsu and Zhejiang provinces are consuming industrial-grade cloth tapes at volumes that justify dedicated regional coating lines.
- Solid-state battery thermal interfaces:Next-generation EV platforms require ceramic-filled silicone tapes for cell-to-pack insulation, creating specification pull from tier-one harness suppliers.
Market Restraints
- Fluoropolymer feedstock concentration:PTFE resin supply concentrates among three global chemical conglomerates, exposing aerospace-grade tape pricing to volatile fluorinated gas quotas under EU F-Gas Regulation.
- Acrylic monomer cost volatility:Crude-linked propylene derivatives drive 40-60% of pressure-sensitive adhesive input costs, compressing margins for non-integrated converters.
- Technical ceiling in thin-film dielectrics:Sub-0.1 mm polyethylene tapes face puncture resistance limits that constrain miniaturization in high-density telecommunications bundles.
Strategic Opportunities
- India's automotive wire harness export push:PLI scheme incentives for EV component manufacturing are drawing tape qualification programs from Maruti Suzuki and Tata Motors supplier parks near Chennai.
- Recyclable thermoplastic elastomer formulations:TPE backings compatible with existing cable shredding infrastructure address OEM circularity mandates without requiring adhesive separation.
- Digital twin integration in harness design:Siemens and Dassault platforms now embed tape thermal performance data, enabling specification lock-in during early-stage vehicle architecture decisions.
Industry Challenges
- Multi-jurisdiction certification stacking:Simultaneous UL, VDE, and GB standard qualification for a single SKU extends development cycles by 8-14 months.
- Adhesive formulation talent scarcity:Silicone polymer chemistry expertise concentrates among retiring specialists at Japanese and German tape manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Wrapping Tapes Market |
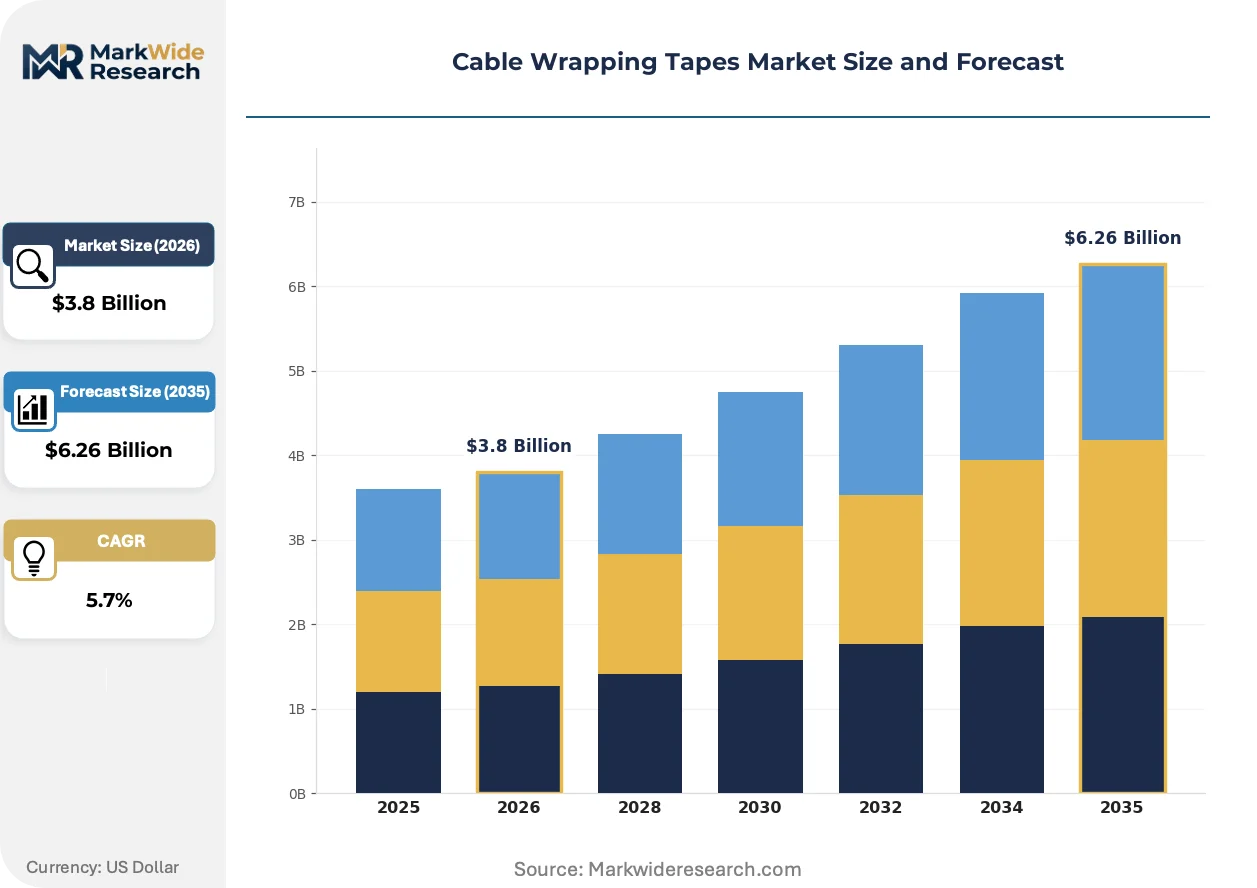
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Cloth, Rubber, Polyethylene Application: Electrical Insulation, Wire Harness, Automotive, Industrial Equipment End User: Telecommunications, Automotive Manufacturers, Home Appliances, Consumer Electronics Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | 3M Company, Parker Hannifin Corp, Nitto Denko Corporation, Scapa Group plc, HellermannTyton, Avery Dennison Corporation, Intertape Polymer Group, tesa SE, Jinyang Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Wrapping Tapes Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to redefine performance benchmarks across automotive, aerospace, and telecommunications applications.
Polyimide film tapes with vapor-deposited aluminum layers are expanding into satellite wiring harnesses where atomic oxygen exposure degrades conventional polymer backings. SpaceX and OneWeb constellation suppliers specify these laminates for low-Earth-orbit cable protection. The technology is expanding into terrestrial high-altitude drone applications as UAV flight ceilings rise.
EU REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing reformulation of rubber-based adhesive tackifiers used in heavy-duty industrial harnessing. German automotive OEMs now require full substance disclosure to SCIP database thresholds. Tape converters serving Volkswagen and BMW supply chains are accelerating silicone adhesive migration programs.
Consolidated procurement through tier-one harness manufacturers is displacing fragmented distributor purchasing in European EV supply chains. Leoni and Aptiv now specify tape performance bundles rather than discrete SKU orders. This concentration is most visible in Hungary and Slovakia, where harness assembly plants cluster near battery gigafactories.
Cable Wrapping Tapes Market Segmentation
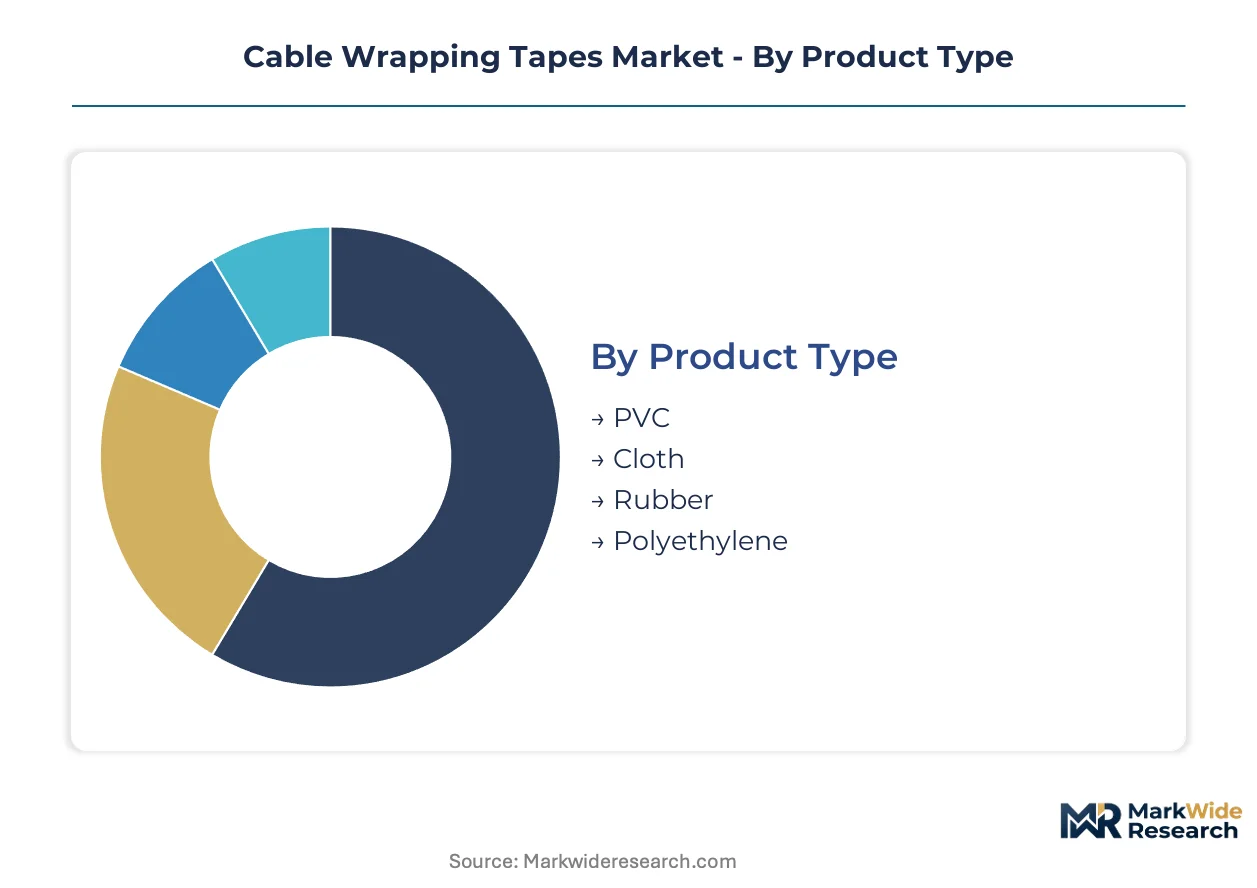
Cable wrapping tape specifications diverge sharply between cost-driven commodity electrical work and mission-critical automotive harnessing. Understanding where volume concentrates versus where margins expand enables suppliers to align coating capacity with qualification investments.
Product Type:
PVC dominates tonnage while polyethylene captures expanding specification premiums in halogen-sensitive applications.
- PVC:Plasticized polyvinyl chloride backings with rubber or acrylic adhesives deliver dielectric strength at the lowest cost per meter. General electrical contractors in India and Southeast Asia specify these formulations for building wire harnessing where smoke toxicity regulations remain permissive.
- Cloth:Woven cotton or synthetic fabric substrates saturated with rubber adhesives withstand abrasion in heavy-duty industrial environments. German automotive OEMs specify cloth tapes for engine-bay wire looms where 130°C sustained operation and mechanical durability override material cost.
- Rubber:Self-amalgamating ethylene-propylene or silicone rubber tapes fuse into seamless moisture barriers for outdoor and underground cable joints. Utility infrastructure maintenance programs in Brazil specify these for medium-voltage distribution splices.
- Polyethylene:Low-density and linear low-density film tapes with cross-linked adhesive layers serve telecommunications bundles requiring low-smoke zero-halogen compliance. Data center construction in Singapore and Sydney specifies these for structured cabling fire safety.
Today's leader: PVC. Tomorrow's challenger: Polyethylene.
Application:
Wire harness assembly commands the steepest expansion trajectory as electric vehicle architectures multiply cable counts per vehicle.
- Electrical Insulation:Single-layer and laminated tapes provide dielectric separation between conductors in power distribution panels and switchgear. Indian state electricity boards specify BIS-certified PVC tapes for rural electrification infrastructure.
- Wire Harness:Multi-tape bundling systems organize and protect cable assemblies in transportation and industrial platforms. EV battery pack suppliers in Hungary and Slovakia qualify specialized thermal-management tapes for 800-volt architectures.
- Automotive:OEM-directed specifications cover interior, underhood, and chassis harness zones with distinct temperature and fluid-resistance requirements. Toyota and Honda supplier parks in Thailand consume premium cloth and felt tapes for noise-dampening harness wrapping.
- Industrial Equipment:Heavy-gauge rubber and armored tapes protect trailing cables on mining machinery and port cranes. Australian iron ore operations specify these for dragline and shovel electrical systems.
Volume concentrates in electrical insulation. Value migrates toward wire harness.
End User:
Automotive manufacturers drive qualification intensity while telecommunications operators standardize procurement around performance bundles.
- Telecommunications:Carrier network buildouts and data center expansions specify flame-retardant polyethylene tapes for fiber and copper cable management. NBN Co in Australia and Openreach in the UK mandate LSZH compliance for indoor infrastructure.
- Automotive Manufacturers:Tier-one harness suppliers Leoni and Aptiv consolidate tape procurement into multi-year performance agreements. Volkswagen's Zwickau EV factory qualifies tape suppliers against 15-year thermal aging protocols.
- Home Appliances:Washing machine and refrigerator assemblers specify cost-optimized PVC tapes for internal power cord organization. Chinese white-goods exporters in Guangdong province drive high-volume, low-margin consumption.
- Consumer Electronics:Laptop and smartphone manufacturers require ultra-thin polyimide or polyester tapes for internal flex cable protection. Foxconn and Pegatron facilities specify sub-0.05 mm thicknesses for miniaturized device architectures.
Automotive manufacturers set the specification ceiling. Telecommunications scales the procurement volume.
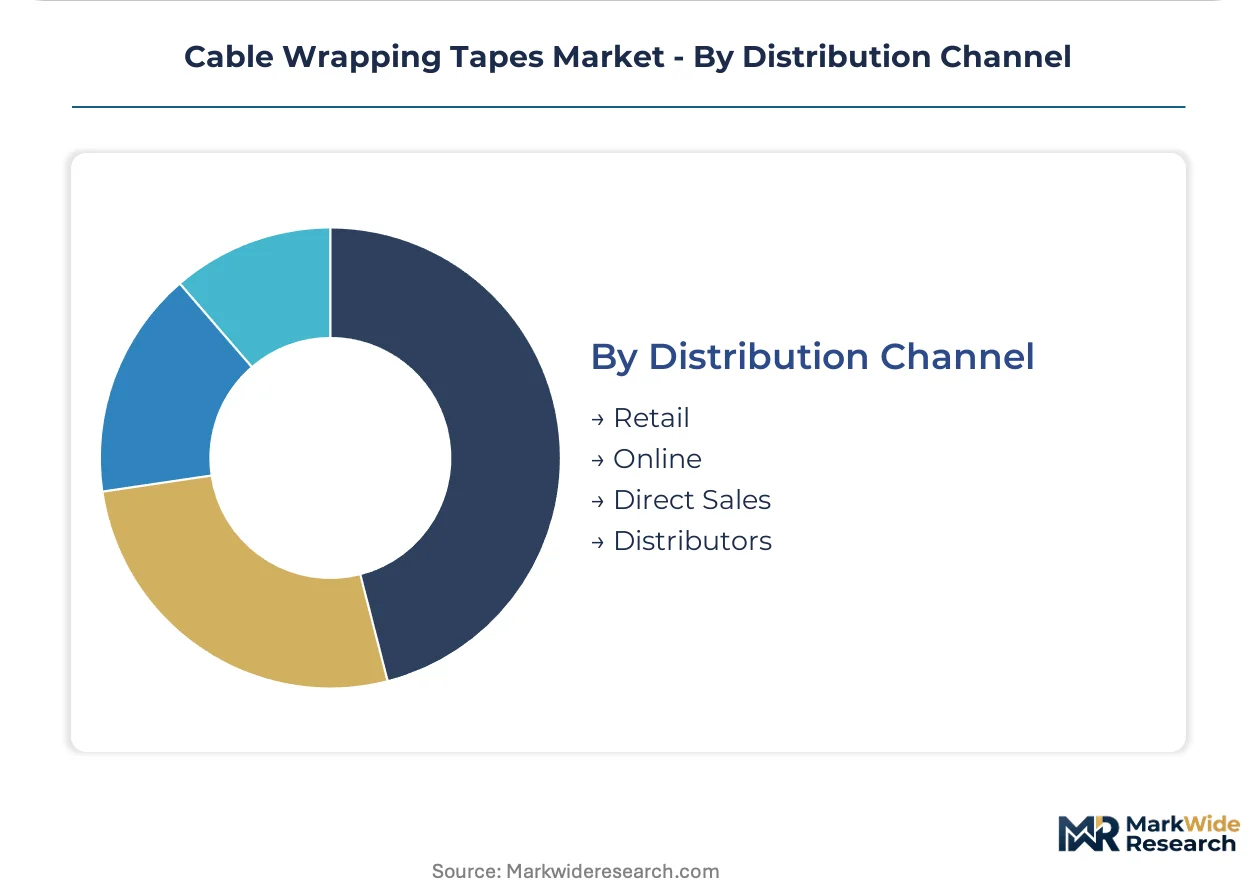
Distribution Channel:
Direct sales capture strategic accounts while distributors serve fragmented maintenance and repair demand.
- Retail:Hardware stores and electrical supply counters stock consumer-grade PVC tapes for residential and small commercial projects. Bunnings Warehouse in Australia and Leroy Merlin in France dominate this channel.
- Online:E-commerce platforms aggregate long-tail demand from repair technicians and small contractors. Alibaba and Amazon Business list industrial-grade SKUs with technical datasheets for specification-conscious buyers.
- Direct Sales:Tape manufacturers deploy technical service engineers to qualify products at tier-one harness and cable factories. 3M and Nitto Denko maintain direct relationships with automotive OEM material engineering departments.
- Distributors:Specialized electrical and electronics distributors hold inventory for MRO procurement and emergency replacement. Rexel and Wesco International consolidate fragmented industrial demand across North American and European markets.
Distributors own the replacement cycle. Direct sales lock in platform design wins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive formulation chemists cluster in Germany and Japan, anchoring high-performance tape development for automotive and aerospace applications.
China
Domestic cable manufacturers in Jiangsu and Zhejiang provinces are scaling industrial-grade cloth tape consumption to match expanding wire harness output. MIIT's GB standards on flame-retardant cable materials impose dual compliance burdens on exporters serving both domestic and international markets. The Yangtze River Delta hosts concentrated coating line investments serving battery gigafactory demand.
Germany
Volkswagen, BMW, and Mercedes-Benz supplier parks drive qualification intensity for thermal-management tapes in 800-volt EV architectures. ECHA's REACH Annex XVII enforcement accelerates halogen-free adhesive migration across automotive wire harness supply chains. Bavaria's harness assembly corridors near Ingolstadt and Munich concentrate tape technical service engineering.
United States
Data center construction in Northern Virginia and Texas pulls low-smoke zero-halogen polyethylene tape specifications from telecommunications operators. EPA guidelines on volatile organic compound emissions from adhesive coatings reshape formulation roadmaps for domestic converters. The Southeast automotive belt spanning Tennessee and South Carolina qualifies specialized tapes for EV battery zone insulation.
Japan
Toyota and Honda supplier parks in Aichi and Saitama prefectures sustain premium cloth and felt tape consumption for noise-dampening harness wrapping. METI's industrial standards for high-temperature electrical insulation maintain technical barriers for imported substitutes. The Kanto region anchors silicone polymer chemistry expertise concentrated among specialized tape manufacturers.
India
Maruti Suzuki and Tata Motors supplier parks near Chennai are accelerating tape qualification programs under PLI scheme incentives for EV component manufacturing. BIS certification requirements for rural electrification infrastructure sustain cost-optimized PVC tape volume. Gujarat's cable manufacturing clusters scale domestic coating capacity to serve export-oriented wire harness producers.
Cable Wrapping Tapes Market Vendor Landscape
The competitive structure tilts toward integrated chemical-to-tape converters with captive adhesive supply. Market concentration remains moderate, with tier-one automotive harness manufacturers consolidating procurement around performance bundles rather than discrete SKUs. Two strategic archetypes dominate: diversified materials conglomerates leveraging fluoropolymer and silicone expertise, and regional specialists anchoring automotive OEM relationships through embedded technical service. Capacity expansion and qualification-driven partnership formation represent the dominant competitive moves.
Among diversified materials conglomerates, 3M Company and Nitto Denko Corporation exemplify integrated players with deep formulation heritage. Parker Hannifin Corp occupies a position among industrial diversification specialists with cross-sector adhesive applications. These three anchors represent distinct competitive vectors: North American fluoropolymer expertise, Japanese automotive OEM integration, and diversified industrial motion-control adjacencies.
| Leading Market Players |
|---|
| 3M Company |
| Parker Hannifin Corp |
| Nitto Denko Corporation |
| Scapa Group plc |
| HellermannTyton |
| Avery Dennison Corporation |
| Intertape Polymer Group |
| tesa SE |
| Jinyang Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
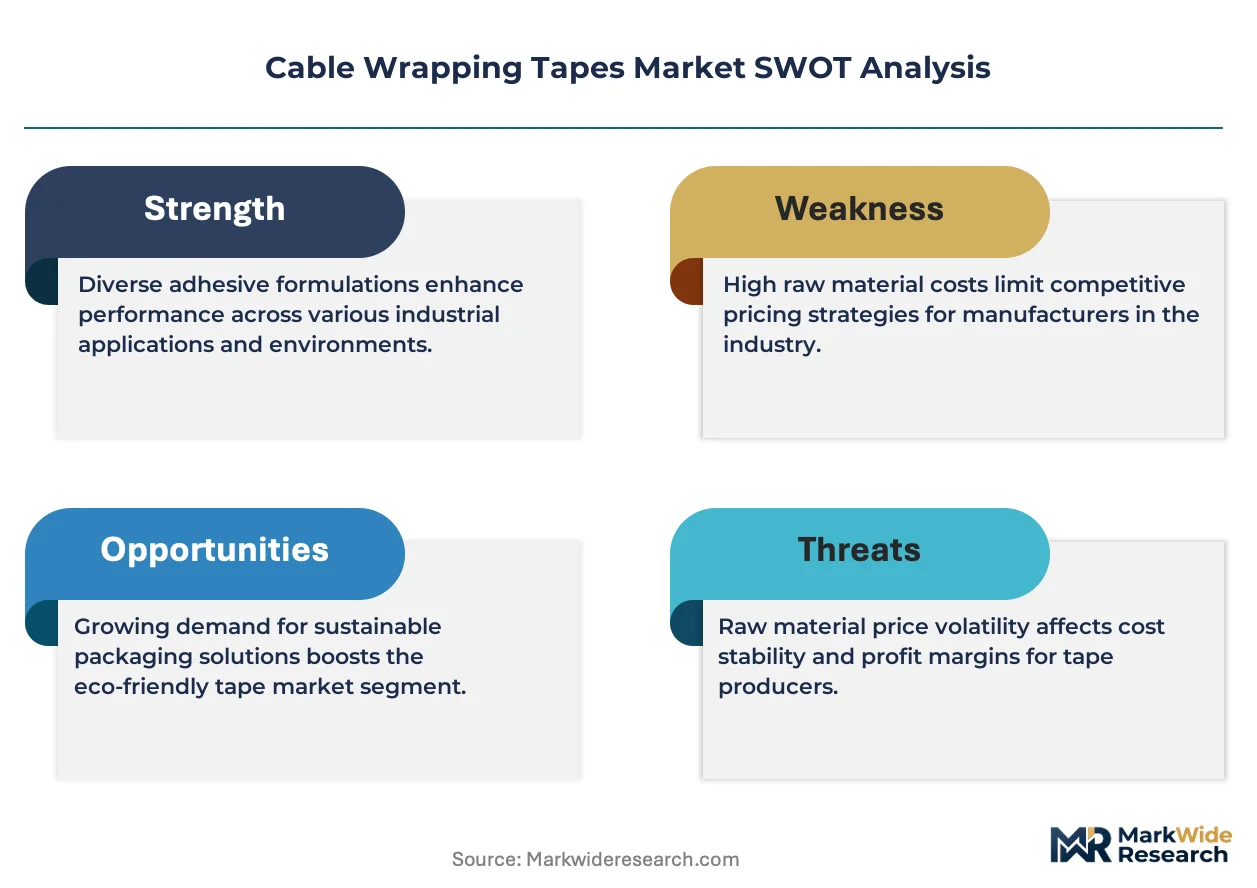
REACH Annex XVII halogen-free mandates gate qualified supply access and premium-tier pricing power, compressing development timelines for converters while rewarding integrated manufacturers with captive adhesive chemistry and established automotive OEM certifications.
Pricing Analysis
Bundled performance agreements versus unbundled SKU procurement splits the market into two pricing regimes. Tier-one harness manufacturers like Leoni and Aptiv negotiate multi-year thermal-performance bundles that lock in volume commitments, while fragmented MRO demand flows through distributors at spot-equivalent rates. Price differentiation rests on UL/VDE certification tiers and automotive platform qualification depth. Cost compression in standard PVC formulations is intensifying because acrylic monomer volatility feeds directly into pressure-sensitive adhesive input costs. Electrical contractors in India and Southeast Asia exhibit highest price sensitivity, whereas German automotive OEMs prioritize 15-year thermal aging protocols over unit cost.
Supply Chain Analysis
Reverse-logistics flows for cable shredding infrastructure are reshaping backing material specifications, with TPE formulations gaining traction for circularity compatibility without adhesive separation. Raw material supply concentrates in China, Germany, and Japan, where fluoropolymer resin production, silicone polymer chemistry expertise, and automotive OEM technical service engineering cluster respectively. Feedstock dependencies include PTFE resin from three global chemical conglomerates, propylene-derived acrylic monomers, and ceramic fillers for solid-state battery thermal interface tapes. Single-source vulnerability in fluorinated gas quotas under EU F-Gas Regulation exposes aerospace-grade tape pricing to volatile supply interruptions. Distribution runs through direct technical service teams for platform design wins and specialized electrical distributors for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier shifts toward halogen-free polyethylene and ceramic-filled silicone formulations, while REACH compliance deadlines compress qualification timelines for non-integrated competitors.
For Market Incumbents: Lock in platform design wins by embedding thermal performance data into Siemens and Dassault digital twin platforms before architecture decisions harden. Deepen backward integration into silicone polymer chemistry to offset adhesive formulation talent scarcity concentrated among retiring Japanese and German specialists. Defend against regional coating line investments in Jiangsu and Zhejiang provinces by accelerating multi-jurisdiction certification stacking capabilities that extend rival development cycles. For New Entrants and Emerging Players: Tier-one harness supplier technical service partnerships offer the most penetrable entry vector for qualification-constrained automotive applications. Target India's PLI scheme incentives near Chennai supplier parks where Maruti Suzuki and Tata Motors are accelerating tape qualification programs with compressed incumbent relationships. Pursue white-space in recyclable thermoplastic elastomer formulations compatible with existing cable shredding infrastructure, addressing OEM circularity mandates without requiring adhesive separation chemistry. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap regional specialists with embedded automotive OEM relationships because tier-one harness manufacturer procurement consolidation favors technical service density over fragmented distributor coverage. Long-term viability centers on qualification asset durability rather than commodity coating capacity. Watch ECHA enforcement intensity and solid-state battery thermal interface specification pull as inflection indicators for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Polymer Chemistry | Captive adhesive supply secures margin protection against propylene derivative volatility and talent scarcity. |
| Multi-Jurisdiction Certification Stacking Investment | UL, VDE, and GB standard simultaneous qualification extends rival development cycles by 8-14 months. |
| Digital Twin Platform Data Embedding | Siemens and Dassault harness design software integration locks in specification decisions before sourcing finalizes. |
| Regional Coating Line Expansion | Dedicated Jiangsu and Zhejiang capacity captures China's scaling domestic cable production and battery gigafactory demand. |
| Recyclable TPE Formulation Development | Circularity-compatible backings address Volkswagen and BMW SCIP database disclosure requirements without adhesive separation. |
Methodological Framework
Multiple input streams — primary interviews with tape manufacturer R&D directors, tier-one harness supplier procurement leads, and automotive OEM material engineers; secondary validation through ECHA regulatory filings, MIIT GB standard publications, and customs trade data; plus SEC 10-K disclosures from diversified materials conglomerates — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against panel input from silicone polymer chemists and coating line operators to anchor growth assumptions across the projection horizon. The analytical framework modeled product type, application, end user, and distribution channel dimensions alongside regional production hub clusters and certification tier penetration. CAGRs were derived from fitted trend extrapolation moderated by qualification timeline constraints and regulatory enforcement schedules. Forecast inputs included electric vehicle wiring harness architecture evolution, solid-state battery thermal interface specification development, and REACH Annex XVII substance restriction implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluoropolymer feedstock quota allocations, acrylic monomer cost volatility, and adhesive formulation expertise succession. Practitioners should monitor ECHA enforcement case volumes, tier-one harness supplier procurement consolidation announcements, and solid-state battery platform qualification timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Gummed Tapes Market
Tapes
Global Adhesive Tapes Market
Tapes
Industrial Tapes Market
Tapes
Global Printed Tape Market
Tapes
Seam Tapes Market
Tapes
Gaffers Tape Market
Tapes
Galley Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Freezer Tape Market
Tapes
Double Coated Film Tapes Market
Tapes
Utility Grade Duct Tapes Market
Tapes
Nano Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Acetate Cloth Tape Market
Tapes
Cloth Self-Adhesive Tapes Market