
 Electronic Pressure Sensitive Tape Dispenser Market | 2026-2036
Electronic Pressure Sensitive Tape Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Pressure Sensitive Tape Dispenser Market Foresight
Preventive maintenance contracts is pivoting how original equipment manufacturers monetize tape dispenser deployments. 3M Company leverages its adhesive science heritage to bundle dispenser hardware with proprietary tape formulations and service agreements. Tesa SE anchors European automotive supply chains through calibrated dispensing systems that reduce material waste in just-in-time production environments.
An electronic pressure sensitive tape dispenser is a motorized or sensor-actuated device that feeds, measures, and cuts pressure sensitive adhesive tape to programmed lengths, typically operating at feed speeds between 0.1 and 3 meters per second with cutting precision of plus or minus 1 millimeter. These systems eliminate manual handling variation in high-volume packaging, assembly, and surface protection workflows. Automatic dispensers command the dominant share of replacement revenue as labor costs rise across manufacturing end users, while sensor technology integration represents the fastest-expanding feature category as programmable logic controllers enable length-memory and batch-counting functions. Electric dispensers occupy the premium tier where multi-width compatibility and programmable cutting angles justify higher capital outlay.
OSHA ergonomic guidelines and EPA material waste regulations in the United States shape product design requirements, compelling manufacturers to certify reduced repetitive strain injury risk and quantify tape savings from precision dispensing. CE marking under EU machinery directives governs European market access, particularly for automatic dispensers with integrated blade safety interlocks. Buyers should evaluate total cost-of-ownership models that incorporate maintenance contract structures against standalone equipment procurement, since service bundling is becoming the primary vendor lock-in mechanism.
Market Dynamics
Sensor-enabled dispensing architectures are compressing equipment replacement cycles as programmable logic controllers enable length-memory and batch-counting functions that legacy manual systems cannot replicate. E-commerce fulfillment centers and automotive packaging lines are driving this hardware refresh.
Growth Catalysts
- OSHA ergonomic mandates:Workplace safety standards in the United States compel manufacturers to certify reduced repetitive strain injury risk, accelerating procurement of motorized dispensing systems.
- Automotive just-in-time production:German automotive component packaging lines are retrofitting with calibrated dispensing systems that reduce material waste in precision assembly workflows.
- Feed speed optimization:Sensor-actuated devices operating between 0.1 and 3 meters per second with plus or minus 1 millimeter cutting precision eliminate manual handling variation in high-volume packaging environments.
Market Restraints
- Capital intensity for multi-width compatibility:Electric dispensers with programmable cutting angles require premium-tier capital outlay that mid-volume manufacturers defer.
- CE marking compliance friction:EU machinery directives governing automatic dispensers with integrated blade safety interlocks extend European market access timelines.
- Adhesive formulation lock-in:Bundled hardware-tape-service agreements from incumbent suppliers create switching costs that constrain procurement flexibility.
Strategic Opportunities
- EPA material waste quantification:Regulatory pressure to document tape savings from precision dispensing creates demand for dispensers with integrated usage analytics.
- Maintenance contract bundling:Original equipment manufacturers are pivoting toward service-based monetization models that lock in recurring revenue streams.
- Surface protection workflows:Assembly lines in electronics manufacturing are adopting sensor-enabled dispensers for temporary masking applications.
Industry Challenges
- PLC programming expertise gap:Facilities lack technicians trained to configure programmable logic controllers for length-memory and batch-counting functions.
- Legacy system integration complexity:Retrofitting sensor-enabled dispensers into existing packaging lines requires custom mounting and control interface adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Pressure Sensitive Tape Dispenser Market |
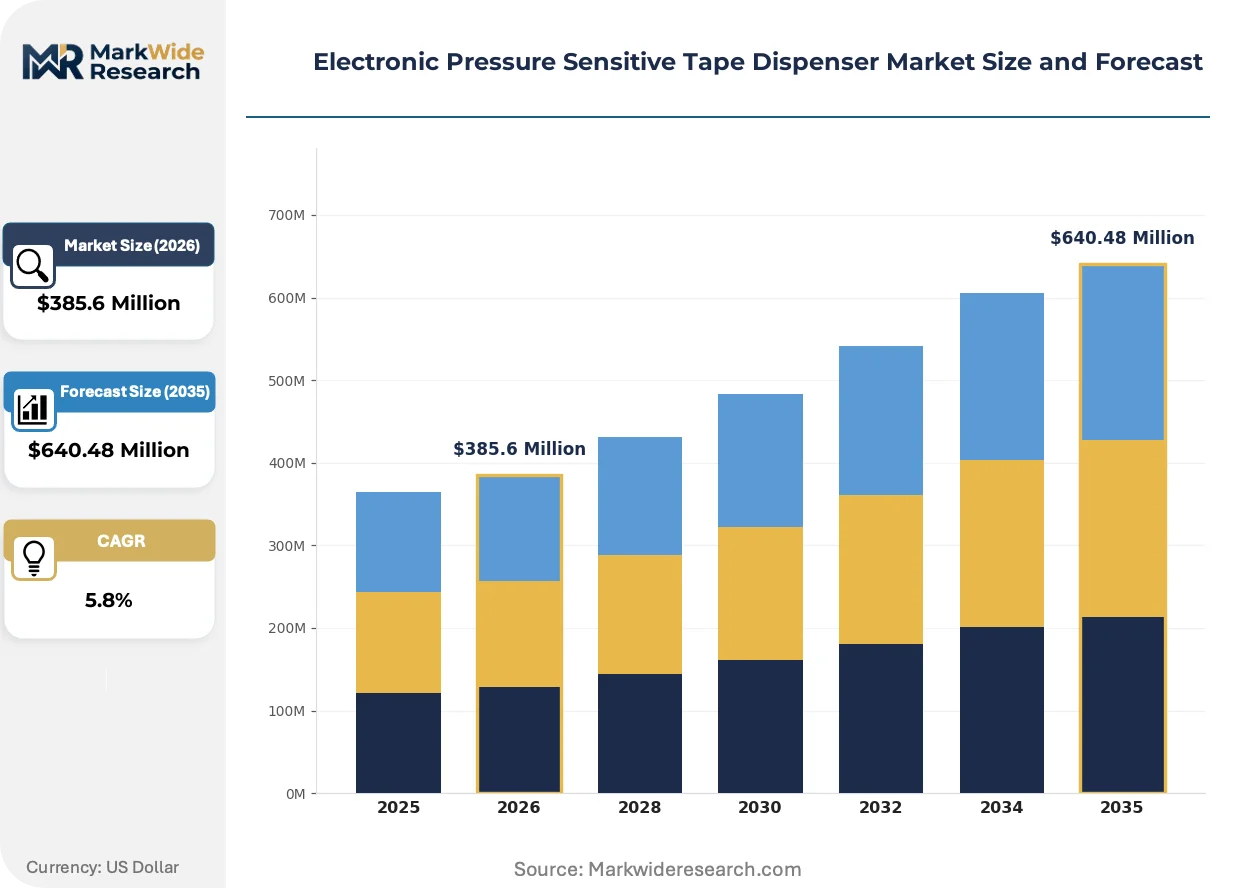
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Automatic Dispensers, Semi-Automatic Dispensers, Electric Dispensers End User: Manufacturing, Construction, Packaging, Retail Feature: Cutting Mechanism, Adhesive Type, Tape Width Compatibility, Sensor Technology Application: Labeling, Sealing, Bundling, Surface Protection |
| Companies Covered | 3M Company, Tesa SE, START International, Uline, Shurtape Technologies, Intertape Polymer Group, Avery Dennison Corporation, Nitto Denko Corporation, LINTEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Pressure Sensitive Tape Dispenser Market Shifts & Advancements
Programmable automation is displacing fixed-mechanism dispensers as buyers prioritize length-memory functions and batch-counting capabilities. This shift favors vendors with software-configurable hardware platforms over mechanical specialists.
Programmable logic controllers with integrated length-memory functions are consolidating control architectures across packaging and assembly workflows. E-commerce fulfillment centers are adopting these systems at accelerated replacement cycles. The technology is consolidating vendor positions by compressing differentiation around software configurability rather than mechanical precision alone.
EPA workplace safety standards and OSHA ergonomic guidelines in the United States are tightening documentation requirements for repetitive strain injury prevention. Manufacturers must certify equipment designs against these standards to maintain market access. Automatic dispensers with ergonomic actuation mechanisms are capturing preference in facilities subject to federal compliance audits.
Buyer procurement patterns are gravitating toward total cost-of-ownership models that weight maintenance contract structures against standalone equipment acquisition. Automotive packaging lines in Germany are leading this evaluation shift. Service bundling is emerging as the primary vendor selection criterion in high-volume manufacturing verticals.
Electronic Pressure Sensitive Tape Dispenser Market Segmentation
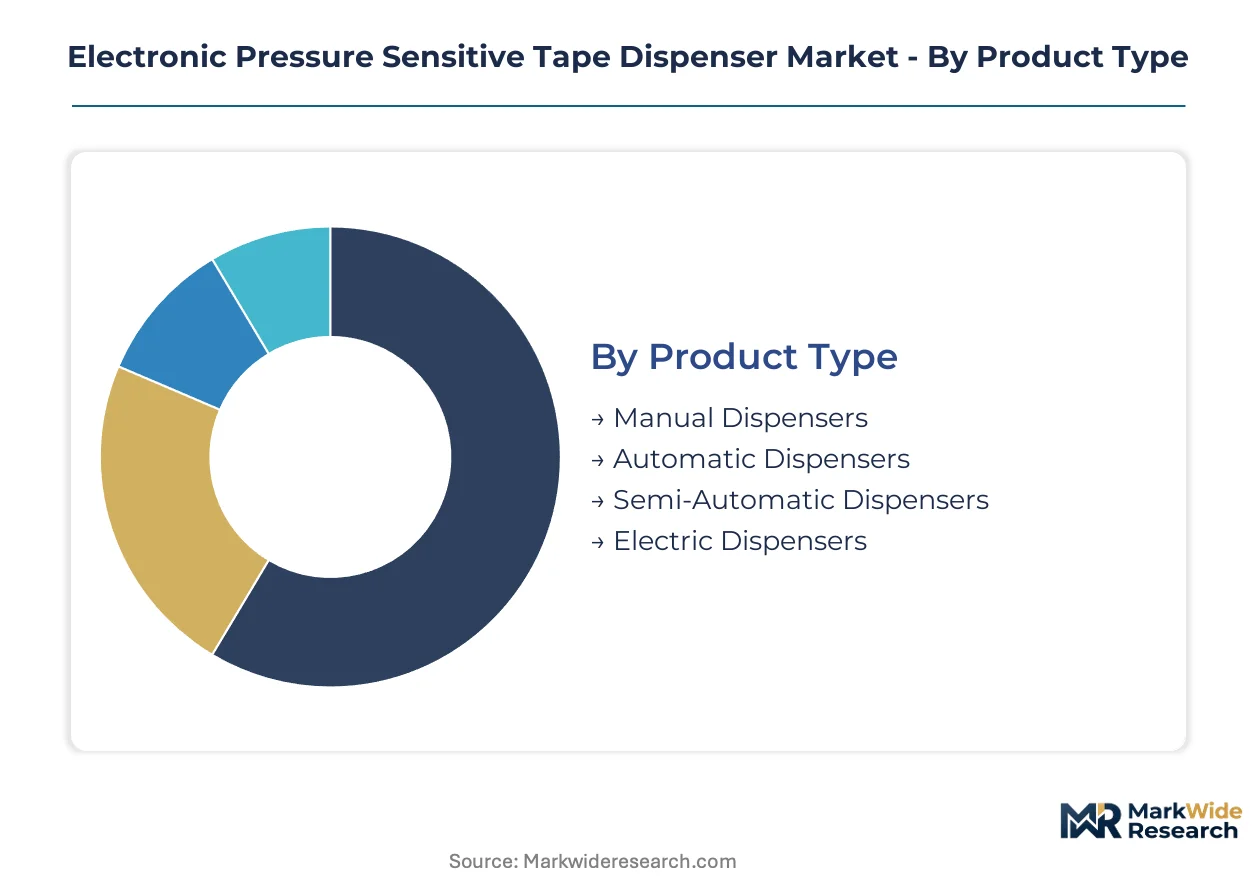
Electronic pressure sensitive tape dispenser procurement patterns diverge sharply across operational environments. Manufacturers prioritize programmable automation and precision cutting, while retail buyers emphasize portability and capital efficiency. Understanding these segment-specific demand drivers enables equipment vendors to align product development with buyer willingness-to-pay.
Product Type:
Capital outlay tolerance and throughput requirements separate buyers across motorized versus mechanical dispensing platforms.
- Automatic Dispensers:Sensor-actuated feed systems with programmable length memory dominate high-volume packaging lines. E-commerce fulfillment centers in Germany are retrofitting legacy stations with these units to meet OSHA ergonomic mandates while reducing material waste in just-in-time workflows.
- Electric Dispensers:Multi-width compatibility and programmable cutting angles define this premium tier. Automotive component suppliers justify higher capital expenditure through quantified tape savings and reduced repetitive strain injury claims under EPA workplace documentation requirements.
- Semi-Automatic Dispensers:Hybrid actuation appeals to mid-volume manufacturers seeking precision without full automation investment.
- Manual Dispensers:Fixed-mechanism units retain share in low-throughput retail and small construction sites where capital constraints dominate procurement decisions.
Automatic dispensers lead volumes today; electric dispensers are gaining share fastest in automotive and electronics manufacturing verticals.
End User:
Regulatory exposure and labor cost structures determine automation adoption intensity across buyer categories.
- Manufacturing:Assembly lines require calibrated dispensing systems with batch-counting functions and blade safety interlocks. CE marking compliance under EU machinery directives shapes European procurement specifications for integrated control architectures.
- Packaging:Sensor-enabled dispensers operating at 0.1 to 3 meters per second feed speed compress replacement cycles in high-throughput environments. Fulfillment centers prioritize equipment with programmable logic controllers for length-memory standardization across shifts.
- Construction:Surface protection and temporary masking applications drive demand for portable units with weather-resistant housings.
- Retail:Point-of-sale bundling and gift-wrapping stations favor compact footprint dispensers with simplified cutting mechanisms.
Manufacturing commands the largest installed base; packaging end users are expanding procurement most aggressively.
Feature:
Software configurability is displacing mechanical differentiation as the primary vendor selection criterion.
- Sensor Technology:Programmable logic controllers enable length-memory, batch-counting, and usage analytics that legacy systems cannot replicate. Facilities lacking PLC programming expertise face implementation delays despite hardware availability.
- Cutting Mechanism:Precision blades with plus or minus 1 millimeter tolerance eliminate manual handling variation. Integrated safety interlocks satisfy CE marking requirements for European market access.
- Tape Width Compatibility:Multi-width platforms reduce changeover downtime in mixed-product packaging environments.
- Adhesive Type:Formulation-specific feed paths prevent residue buildup and maintain cutting precision across tape chemistries.
Sensor technology anchors premium pricing; cutting mechanism specifications dominate replacement part revenue.
Application:
Workflow precision requirements dictate equipment specification complexity and service contract bundling preferences.
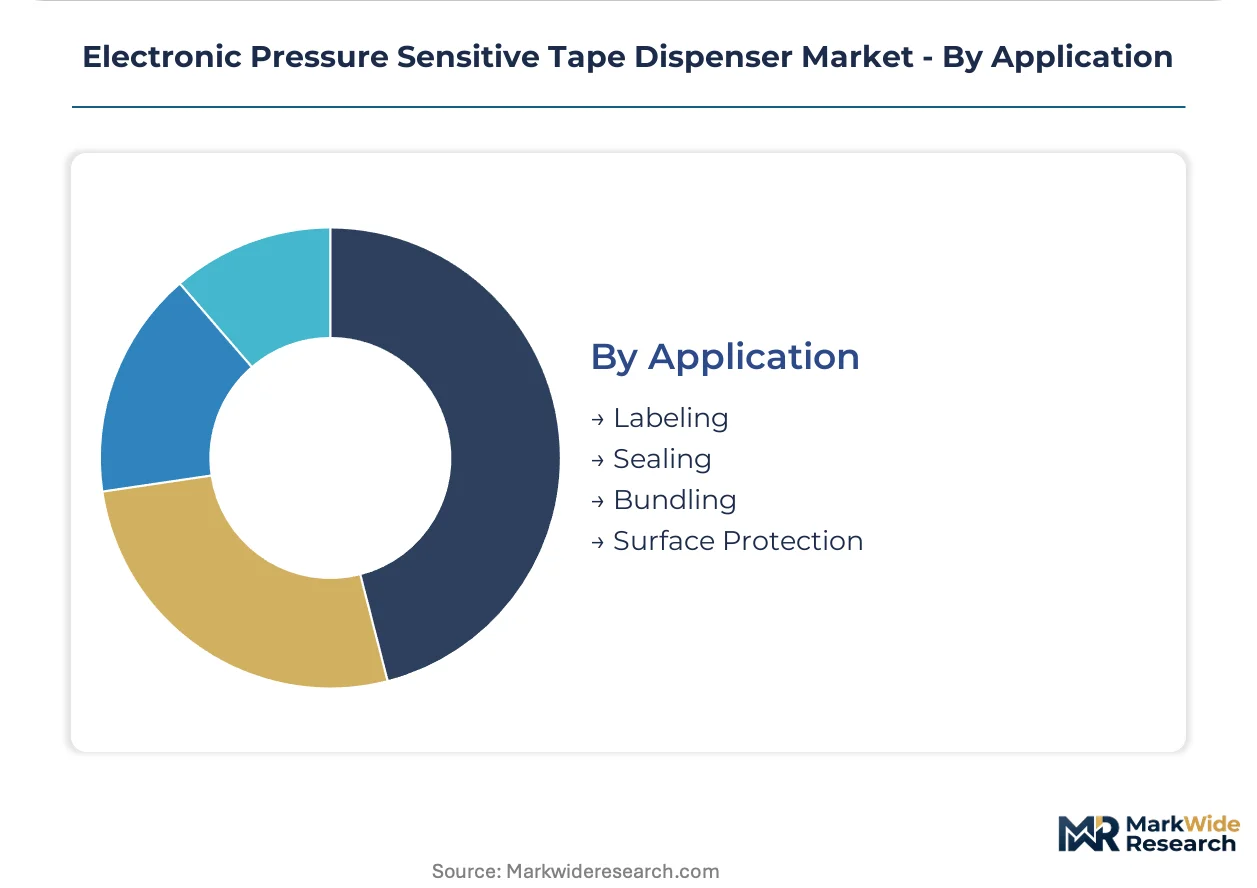
- Sealing:Carton closure operations demand consistent tape length application to minimize material waste. EPA documentation requirements for tape savings quantification favor dispensers with integrated usage tracking.
- Surface Protection:Temporary masking in electronics and automotive assembly requires clean removal without adhesive residue. Sensor-enabled dispensers with programmable feed speeds reduce application variation in cleanroom environments.
- Labeling:Print-and-apply integration drives demand for dispensers with synchronized control interfaces.
- Bundling:Strapping and unitization applications prioritize throughput over length precision in warehouse operations.
Sealing applications generate the highest equipment throughput; surface protection workflows are adopting sensor-enabled systems most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting procurement patterns as manufacturers relocate assembly operations to jurisdictions with streamlined machinery certification pathways. Compliance cost gaps between OSHA-mandated US facilities and CE-marking European plants are accelerating cross-border equipment sourcing decisions.
United States
E-commerce fulfillment centers in Ohio and Texas are retrofitting packaging lines with sensor-enabled dispensers to satisfy OSHA ergonomic mandates. EPA documentation requirements for material waste quantification favor equipment with integrated usage analytics. The Detroit automotive corridor is deploying calibrated dispensing systems for just-in-time component protection workflows.
Germany
Automotive suppliers in Baden-Württemberg are leading European adoption of programmable logic controller dispensers with batch-counting functions. CE marking under EU machinery directives governs procurement specifications for blade safety interlocks. The Stuttgart industrial cluster is retrofitting precision assembly lines to reduce tape waste in surface protection applications.
China
Electronics manufacturing in the Yangtze River Delta is absorbing electric dispensers with multi-width compatibility for temporary masking operations. GB standards and MIIT industrial automation directives shape domestic equipment specifications. Shenzhen-based assembly plants are prioritizing feed speed optimization in cleanroom environments.
Japan
Automotive packaging lines in the Nagoya industrial corridor require calibrated dispensing systems with plus-or-minus 1 millimeter cutting precision. METI productivity initiatives and JIS standards govern equipment procurement in precision manufacturing sectors. Osaka-area electronics assemblers are adopting sensor-actuated devices for surface protection workflows.
South Korea
Seoul Capital Area fulfillment centers are expanding automatic dispenser procurement to meet rising labor cost pressures. MFDS workplace safety guidelines and METI-aligned industrial standards influence equipment selection criteria. Busan-Ulsan manufacturing complexes are integrating programmable dispensers into mixed-product packaging environments.
Electronic Pressure Sensitive Tape Dispenser Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with adhesive science heritage conferring bundling advantages in premium tiers. The vendor base concentrates around three strategic archetypes: diversified materials conglomerates with captive dispenser divisions, precision equipment specialists with programmable automation expertise, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include preventive maintenance contract bundling and sensor technology licensing arrangements that lock in recurring revenue streams.
Within the diversified materials tier, 3M Company and Tesa SE exemplify bundling strategies that combine dispenser hardware with proprietary tape formulations and service agreements. START International occupies a position among precision equipment specialists focused on programmable automation platforms. These three anchors represent distinct competitive vectors: adhesive science integration, European automotive supply chain anchoring, and software-configurable hardware specialization respectively.
| Leading Market Players |
|---|
| 3M Company |
| Tesa SE |
| START International |
| Uline |
| Shurtape Technologies |
| Intertape Polymer Group |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| LINTEC Corporation |
| Others |
Supply & Pricing Matrix
EPA workplace safety documentation mandates governing material waste quantification gate both qualified supply and premium-tier pricing access for tape dispenser manufacturers seeking automotive and electronics manufacturing contracts. Compliance-certified vendors command pricing power while uncertified competitors face exclusion from procurement shortlists at OSHA-audited facilities.
Pricing Analysis
Capacity additions in China are reshaping price floors for electric dispensers with multi-width compatibility. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by CE marking certification and programmable logic controller sophistication. Pricing pressure stems from mid-volume manufacturers deferring capital expenditure on premium-tier equipment. Retail and small construction buyers exhibit highest price sensitivity; automotive component suppliers show lowest sensitivity due to quantified tape savings documentation.
Supply Chain Analysis
Domestic-content mandates in Germany and South Korea are reshaping sourcing patterns for sensor-actuated dispensing architectures. Component manufacturing concentrates in China, Germany, and Japan. Supply chains draw from precision motors, programmable logic controllers, and calibrated cutting blades. Single-source vulnerability in PLC chipset supply poses structural risk. Distribution runs through industrial equipment distributors and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
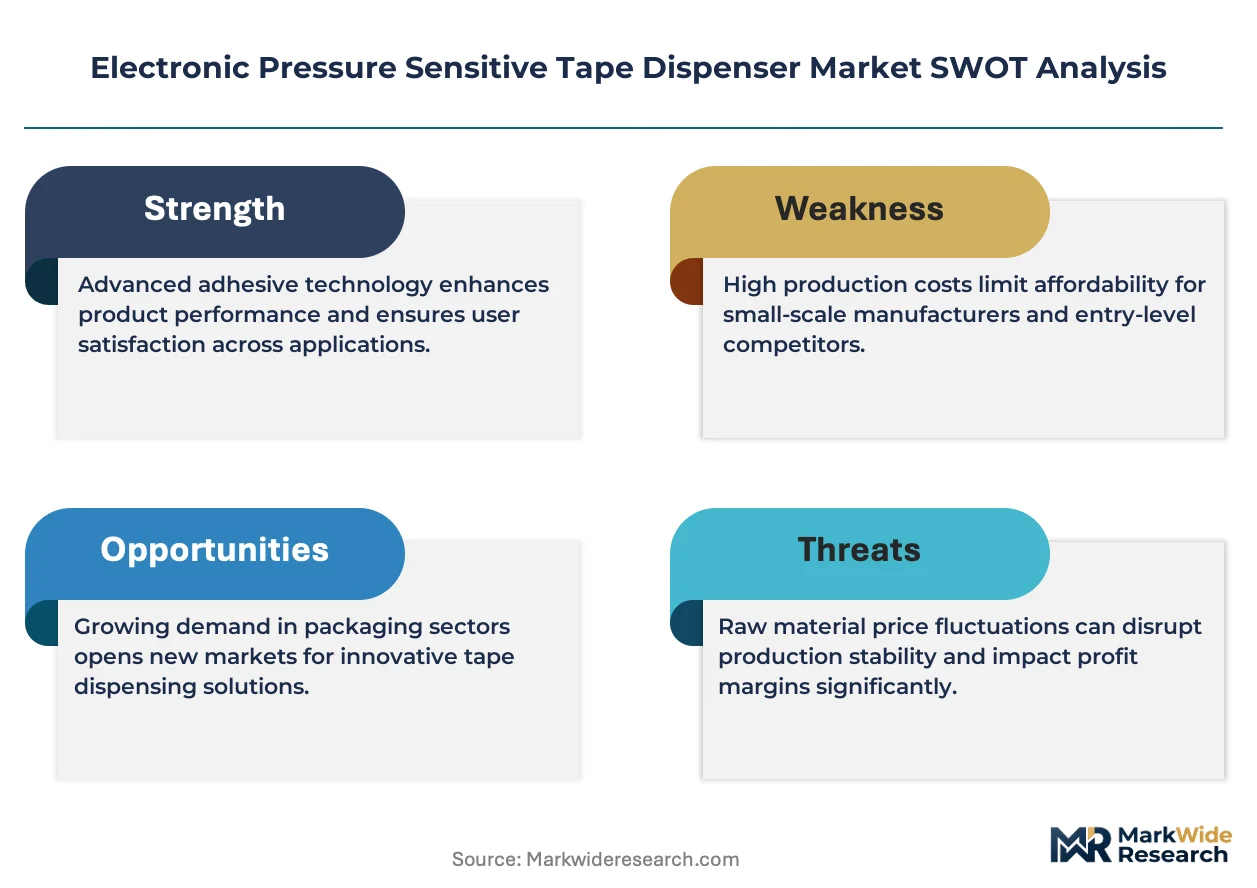
This market represents a late-cycle quality story as procurement patterns shift toward sensor-enabled dispensers with integrated usage analytics and preventive maintenance bundling.
For Market Incumbents: Deepen preventive maintenance contract penetration to lock in recurring revenue streams against emerging programmable automation specialists. Invest in PLC programming training infrastructure to address the technician expertise gap threatening implementation timelines. Prioritize CE marking certification investments to defend European automotive supply chain positions.
For New Entrants and Emerging Players: Capture surface protection workflow opportunities in electronics manufacturing cleanrooms where sensor-enabled dispenser adoption is accelerating fastest. Target mid-volume packaging facilities in South Korea seeking semi-automatic hybrid solutions. Lead with software-configurable platforms that compress differentiation around length-memory functions rather than mechanical precision.
For Investors and Strategic Acquirers: Roll-up economics work for precision equipment specialists with programmable automation expertise because vendor consolidation is compressing differentiation around software configurability. Five-to-ten year viability favors vendors with captive adhesive formulation partnerships or service-based monetization models. Watch EPA enforcement intensity around material waste documentation as inflection indicator for premium-tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Contract Bundling | Locks in recurring revenue streams at German automotive packaging lines facing OSHA ergonomic mandates. |
| Sensor Technology Licensing Arrangements | Enables programmable length-memory functions that legacy manual systems cannot replicate. |
| CE Marking Certification Investment | Secures European market access for automatic dispensers with blade safety interlocks. |
| PLC Programming Training Infrastructure | Addresses technician expertise gaps delaying implementation in e-commerce fulfillment centers. |
| Adhesive Formulation Partnership | Creates hardware-tape-service bundling advantages against standalone equipment competitors. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads alongside secondary validation. Sources include customs and trade data, SEC 10-K filings, industrial automation equipment databases, and machinery directive compliance registries. Bottom-up equipment shipment data triangulates against top-down manufacturing capital expenditure estimates.
Granularity-level modeling extends across product type, end user vertical, feature configuration, and application workflow with regional production cluster differentiation. CAGRs derive from segment-level growth trajectory analysis across the projection horizon. Forecast inputs incorporate e-commerce fulfillment center expansion rates, automotive just-in-time production intensity, and regulatory enforcement patterns for ergonomic equipment mandates.
Supply chain disruption, regulatory enforcement variance, and capital expenditure cycle timing are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding sensor technology adoption curves and maintenance contract penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Mastic Tapes Market
Tapes
Global Surface Protection Tapes Market
Tapes
India Reflective Tapes Market
Tapes
PVC Tapes Market
Tapes
Thread Seal Tape Market
Tapes
Tabbing Tapes Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Twist Tube Market
Tapes
Foam Tape Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Pre-Printed Tape Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
High Bond Tape Market
Tapes
Filament Tapes Market
Tapes
Utility Grade Duct Tapes Market