
 Global Adhesive Tapes Market | 2026-2036
Global Adhesive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adhesive Tapes Market Analysis
Pressure-sensitive adhesive specifications for electric vehicle battery modules is unwinding commodity-grade dominance in the Global Adhesive Tapes Market. 3M Company leverages its fluoropolymer backing patents to command thermal-interface tape supply chains. Nitto Denko Corporation anchors Asian electronics assembly demand through polyimide film specialization. Avery Dennison Corporation competes on sustainable acrylic chemistry certified under emerging bio-based standards.
Global Adhesive Tapes are laminar structures combining a backing substrate—polypropylene, PVC, paper, or foam—with a coated adhesive layer activated by light pressure, engineered for bonding, sealing, insulating, or surface protection in industrial and commercial environments. Double-sided tapes capture expanding share in automotive lightweighting applications where mechanical fasteners add mass, while electrical tapes face margin compression from silicone thermal-gap filler displacement in power electronics. Medical-grade skin-contact tapes represent the fastest-growing material segment as wearable device proliferation drives hypoallergenic acrylic demand.
FDA biocompatibility requirements govern medical tape market access in the United States, while REACH substance restrictions and RoHS hazardous material limits reshape European adhesive formulation portfolios. China's GB standards and SAMR product safety enforcement tighten import tape certification protocols. Stakeholders must monitor evolving chemical disclosure mandates under the EU Green Deal and assess captive supply chain exposure to propylene feedstock volatility.
Market Dynamics
Automotive electrification is forcing a structural recalibration of adhesive tape specifications as thermal management requirements displace commodity-grade products from battery module assembly lines.
Growth Catalysts
- EU Green Deal chemical mandates:REACH substance restrictions are accelerating solvent-free adhesive reformulation across European industrial corridors, opening premium-grade procurement windows for compliant suppliers.
- Electric vehicle battery thermal interfaces:OEMs specify pressure-sensitive adhesives with polyimide and fluoropolymer backings for cell-to-cell bonding in high-temperature operating environments.
- Germany's precision manufacturing clusters:Stuttgart and Munich industrial zones concentrate demand for medical-grade and electronics-assembly tapes with sub-micron thickness tolerances.
Market Restraints
- Propylene feedstock volatility:Acrylic adhesive production costs fluctuate with petrochemical supply chain disruptions, compressing margins for non-integrated manufacturers.
- Silicone thermal-gap filler substitution:Power electronics manufacturers in Japan and South Korea are displacing electrical tapes with liquid-dispensed gap fillers in high-wattage inverter applications.
- China GB certification timelines:SAMR product safety enforcement extends import tape approval cycles, creating inventory risk for non-domestic suppliers.
Strategic Opportunities
- India PLI scheme for electronics:Domestic mobile and wearable device assembly is expanding addressable demand for hypoallergenic skin-contact tapes certified under BIS standards.
- Wearable medical device proliferation:Continuous glucose monitors and cardiac patches require FDA biocompatibility-compliant acrylic adhesives with seven-day wear duration.
- Bio-based chemistry certification:Emerging sustainability standards in the European Union create first-mover positioning for suppliers with mass-balance-certified feedstocks.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-VOC hot-melt and UV-curable adhesive development commands premium compensation, constraining R&D throughput.
- Dual certification requirements:Medical tape suppliers must simultaneously satisfy FDA 21 CFR Part 175 and EU MDR biocompatibility testing, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adhesive Tapes Market |
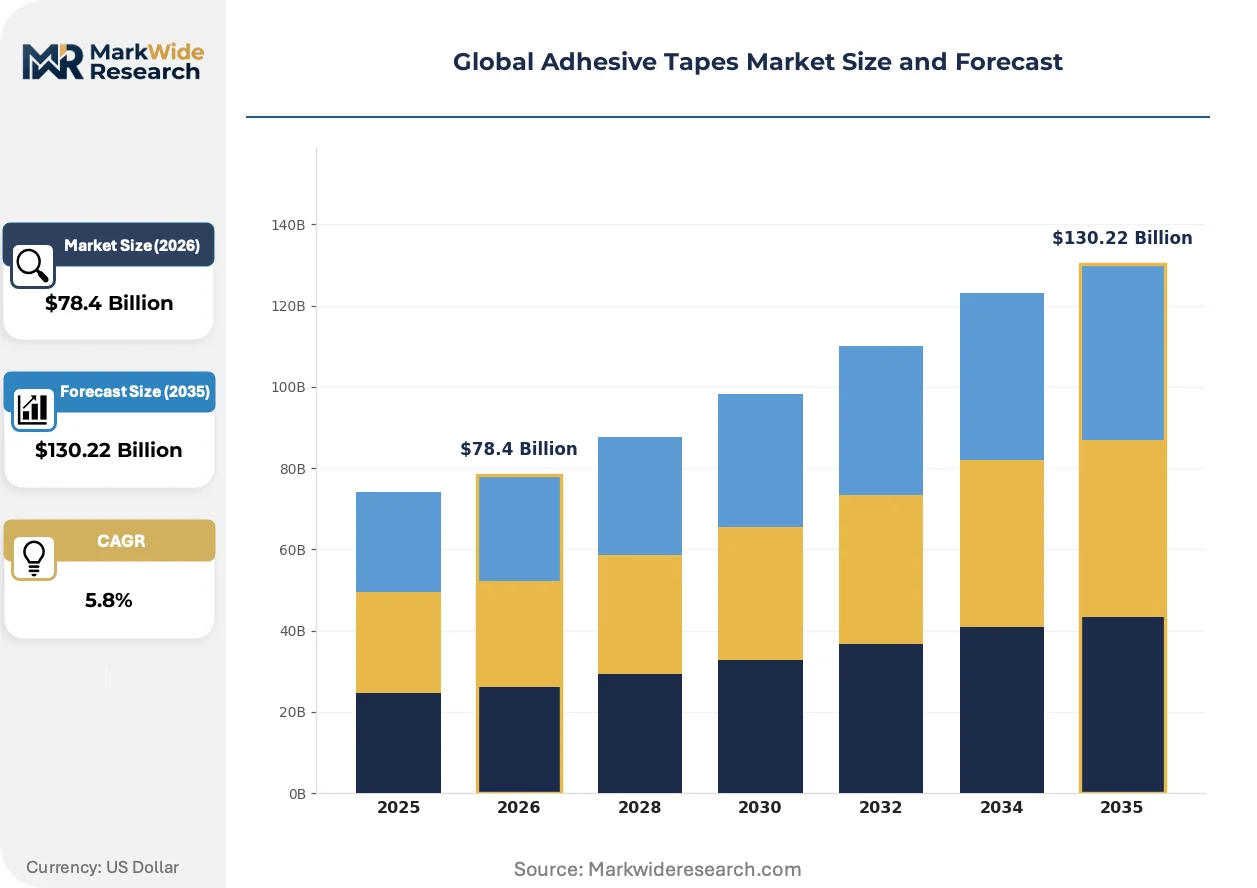
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Electrical, Masking, Duct Material: PVC, Polypropylene, Paper, Foam Application: Automotive, Medical, Packaging, Construction End User: Manufacturers, Retailers, Hospitals, DIY Enthusiasts |
| Companies Covered | 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, tesa SE, Lintec Corporation, Intertape Polymer Group, Berry Global Inc., Lohmann GmbH & Co. KG, Scapa Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adhesive Tapes Market Emerging Trajectories
Material science advances and regulatory chemistry mandates are converging to redefine competitive positioning across specialty tape segments, with thermal performance and sustainability credentials emerging as primary differentiation vectors.
Water-based acrylic emulsion technology is decomposing solvent-borne adhesive dominance in industrial masking and packaging applications. Automotive OEMs in Germany and Japan specify these formulations for assembly-line bonding where volatile organic compound emissions face strict factory-level caps. The shift is compressing capital equipment requirements for coating lines while elevating drying energy costs.
REACH substance restriction amendments are forcing systematic reformulation of halogenated flame retardants and phthalate plasticizers in European electrical tape portfolios. ECHA regulatory updates published through 2024 designate several legacy chemistries as Substances of Very High Concern, triggering substitution mandates with 18-24 month compliance windows. German cable harness manufacturers are accelerating qualification of phosphorus-nitrogen intumescent alternatives.
Direct procurement relationships between automotive Tier-1 suppliers and specialty tape converters are consolidating volume away from distribution intermediaries. Battery pack assemblers in South Korea and the United States negotiate multi-year supply agreements specifying thermal-interface performance guarantees and locked resin pricing. Channel restructuring is most pronounced in power electronics and EV battery verticals where technical service integration determines supplier selection.
Global Adhesive Tapes Market Segmentation
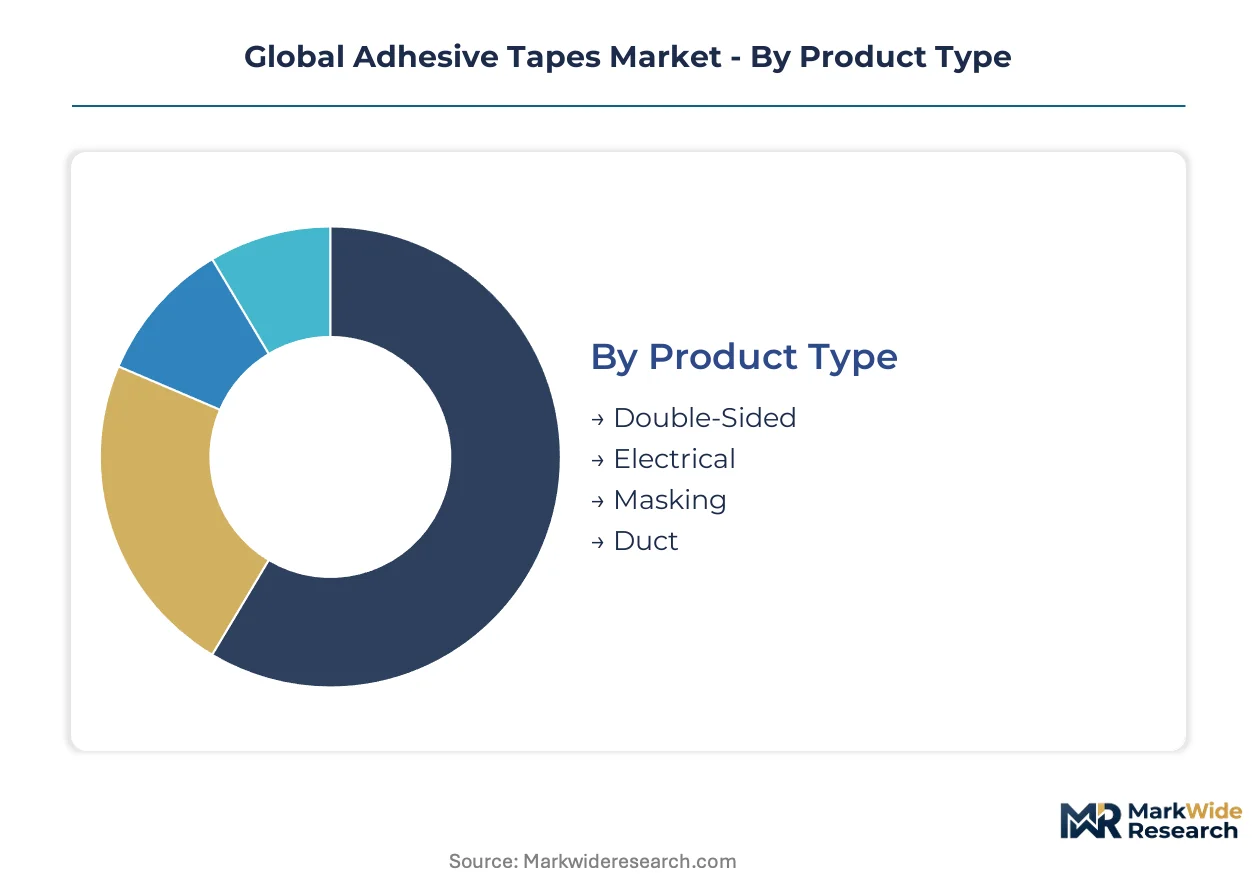
Segmentation in adhesive tapes determines pricing power, channel access, and technical service intensity. Product construction and material chemistry dictate whether converters sell through distribution or direct to OEM engineering teams.
Product Type:
Double-sided tapes flow through direct procurement channels to automotive Tier-1s, while single-sided commodity formats dominate distributor inventories serving maintenance-repair-operations demand.
- Double-Sided:Pressure-sensitive adhesive coatings on both faces of polyimide or foam substrates enable structural bonding without mechanical fasteners. Stuttgart automotive clusters specify these for battery module assembly where mass reduction outweighs material cost premiums.
- Electrical:Vinyl or rubber-based insulating layers with flame-retardant chemistry protect wire harnesses in power electronics. Japanese inverter manufacturers are displacing these with liquid silicone gap fillers in high-wattage applications, compressing segment margins.
- Masking:Crepe paper backings with controlled adhesion support paint bake cycles and surface protection in industrial finishing.
- Duct:Reinforced polyethylene or cloth substrates serve HVAC sealing and general repair applications through retail and contractor channels.
By volume, duct tape leads through mass retail distribution. By growth pace, double-sided formats are climbing the fastest on electrification demand.
Material:
Substrate selection determines thermal ceiling, conformability, and coating compatibility, with cost tiers separating specification-grade from commodity procurement.
- PVC:Plasticized vinyl films offer electrical insulation and chemical resistance at moderate cost. German cable harness manufacturers qualify these under REACH-substituted flame-retardant formulations to maintain EU market access.
- Polypropylene:Oriented PP films provide moisture barrier and tensile strength for packaging and industrial applications. South Korean battery pack assemblers specify biaxially oriented grades for cell-to-cell bonding where dimensional stability matters.
- Paper:Saturated crepe and flatback stocks enable clean removal in masking and splicing applications with lower unit economics.
- Foam:Acrylic or rubber-based cellular structures absorb vibration and fill gaps in automotive trim attachment and electronics gasketing.
Polypropylene commands the largest production volumes. Foam substrates are expanding most quickly on automotive lightweighting and electronics sealing demand.
Application:
End-use verticals segment by regulatory burden, with medical and automotive requiring certified supply chains that packaging and construction bypass.
- Automotive:Thermal-interface bonding, wire harness wrapping, and interior trim attachment dominate tape consumption. OEMs in the United States and Germany negotiate multi-year supply agreements specifying performance guarantees and locked resin pricing.
- Medical:Hypoallergenic acrylic adhesives on breathable nonwovens or films enable wearable device attachment and wound care. FDA biocompatibility requirements and EU MDR testing extend product launch timelines for suppliers serving this vertical.
- Packaging:Water-based acrylic emulsions on biaxially oriented polypropylene support case sealing and carton closing at high line speeds.
- Construction:Weather-resistant foil and butyl tapes seal building envelopes and HVAC ducts against moisture intrusion.
Packaging generates the highest unit volumes. Medical applications are gaining share fastest on continuous glucose monitor and cardiac patch proliferation.
End User:
Customer type determines order pattern, technical service requirement, and pricing structure across the value chain.
- Manufacturers:OEMs and Tier-1 suppliers procure through direct relationships with tape converters, specifying custom slit widths and adhesive formulations. Battery pack assemblers in South Korea and the United States drive consolidation toward technical service-integrated supply agreements.
- Retailers:Mass merchants and specialty distributors stock standardized SKUs for consumer and light commercial demand, with inventory turns prioritizing breadth over technical depth.
- Hospitals:Central supply departments and surgical suites demand sterile packaging and lot traceability for skin-contact and device-attachment tapes.
- DIY Enthusiasts:Home improvement retailers serve repair, crafting, and small-project demand through impulse and planned purchases.
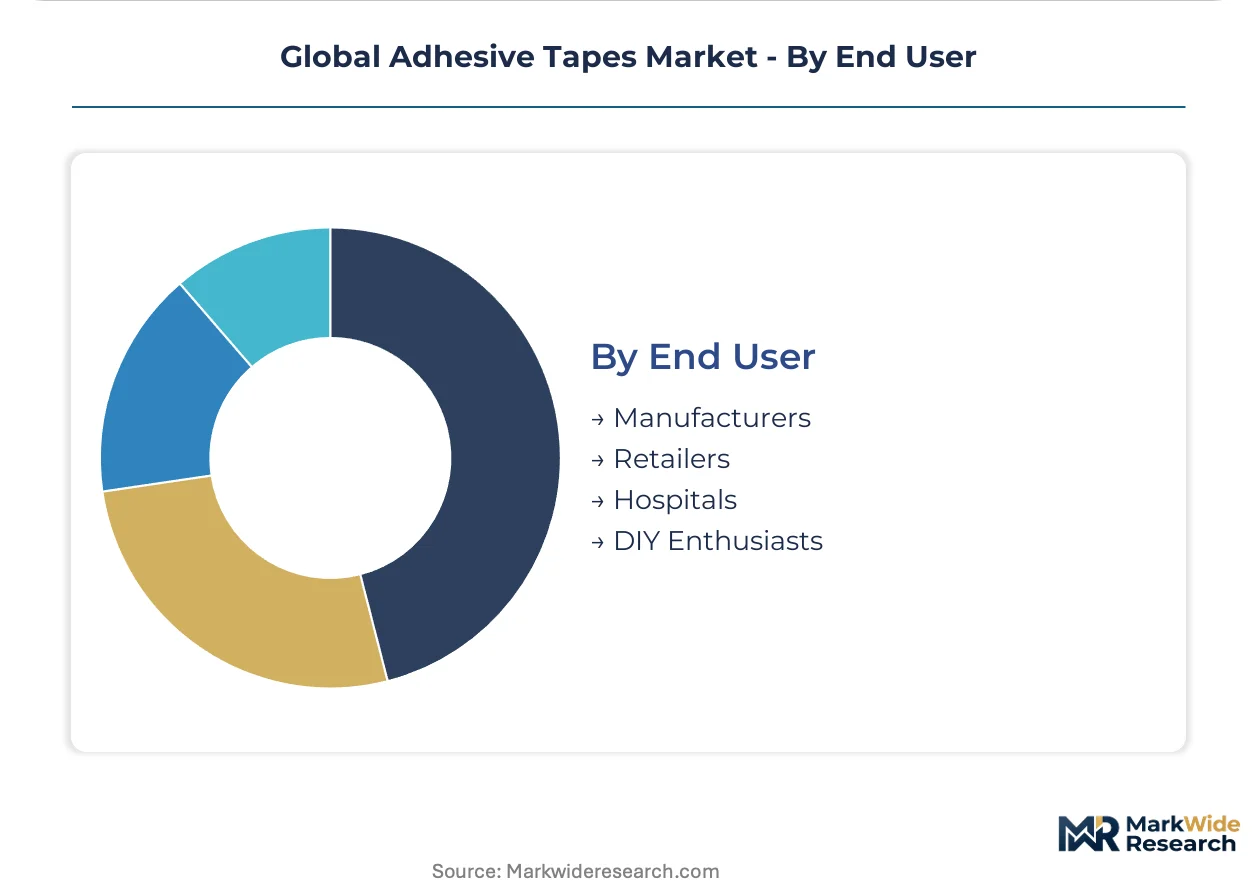
Manufacturers represent the largest revenue concentration. Hospitals are expanding most quickly on wearable medical device adoption and chronic disease management protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reshape regional tape procurement patterns. Germany and South Korea run structural surpluses in specialty thermal-interface grades. The United States and China balance volumes through cross-border automotive supply chains.
United States
Electric vehicle battery assembly and aerospace wire harnessing consume specification-grade polyimide tapes. FDA 21 CFR Part 175 governs medical-grade acrylic imports for wearable device attachment. Detroit automotive clusters negotiate multi-year thermal-interface supply agreements with locked resin pricing.
Germany
Precision manufacturing and automotive electrification drive premium-grade procurement in Stuttgart and Munich industrial zones. REACH substance restrictions and EU Green Deal mandates force solvent-free adhesive reformulation across supply chains. Bavarian cable harness manufacturers qualify phosphorus-nitrogen flame-retardant alternatives to maintain EU market access.
China
Electronics assembly and battery pack manufacturing concentrate demand in the Yangtze River Delta and Pearl River Delta. SAMR product safety enforcement and GB standards tighten import tape certification protocols, extending approval cycles. Shanghai-based converters serve domestic EV OEMs with localized polypropylene substrate supply.
Japan
Power electronics and semiconductor packaging anchor specialty tape consumption. METI industrial standards and JIS certification requirements shape domestic procurement specifications. Nagoya automotive suppliers displace electrical tapes with liquid silicone gap fillers in high-wattage inverter applications.
South Korea
Battery cell manufacturing and electronics assembly dominate tape demand in the Seoul Capital Area and Busan-Ulsan corridor. MFDS biocompatibility requirements govern medical-grade imports for wearable device proliferation. Domestic battery pack assemblers negotiate direct procurement agreements specifying thermal-interface performance guarantees.
Global Adhesive Tapes Market Vendor Landscape
Concentration sits with diversified materials conglomerates holding patent-protected backing technologies. Mid-scale regional converters occupy fragmented niches in industrial masking and packaging grades. Two strategic archetypes dominate: integrated resin-to-tape manufacturers with captive feedstock security, and specialized converters serving single-vertical OEMs with technical service integration. Competitive moves center on backward integration into acrylic emulsion production and geographic expansion through distributor acquisition in emerging electronics assembly corridors.
Among diversified materials conglomerates, 3M Company and Avery Dennison Corporation occupy positions exemplifying patent-backed thermal-interface specialization and sustainable chemistry certification respectively. Nitto Denko Corporation anchors the Asian electronics assembly vector through polyimide film concentration. These three represent the integrated-to-specialist spectrum, with each sitting within distinct competitive tiers defined by R&D intensity and vertical scope rather than scale alone.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| tesa SE |
| Lintec Corporation |
| Intertape Polymer Group |
| Berry Global Inc. |
| Lohmann GmbH & Co. KG |
| Scapa Group plc |
| Others |
Supply Flow & Price Mechanics
Liquid silicone gap filler substitution for electrical tapes is redrawing supply geography toward Japan and South Korea while compressing pricing power in legacy vinyl-backed segments. This displacement dynamic simultaneously elevates thermal-interface tape premiums and erodes commodity-grade margins across converter portfolios.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Global Adhesive Tapes Market. Price differentiation rests on REACH compliance certification and volume-scale procurement, with German automotive clusters least sensitive due to locked multi-year agreements. Cost compression in commodity-grade masking and packaging tapes is intensifying because of propylene feedstock volatility. Retail distributors serving DIY enthusiasts exhibit highest price sensitivity, while battery pack assemblers prioritize thermal-performance guarantees over unit economics.
Supply Chain Analysis
Acrylic emulsion feedstock concentration in Germany, South Korea, and the United States shapes converter input costs across specialty grades. Backing substrate production draws from biaxially oriented polypropylene lines in China, polyimide film extrusion in Japan, and fluoropolymer coating in the United States. Single-source vulnerability sits with European halogenated flame-retardant suppliers facing ECHA substitution mandates. Distribution runs through direct technical-service relationships for automotive and medical OEMs, while mass retail channels handle standardized industrial and consumer SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Adhesive Tapes Market is entering a cyclical recovery phase as automotive electrification capital expenditure rebounds from pandemic-era deferrals and battery pack assembly capacity expands across multiple continents.
For Market Incumbents: Fortify captive acrylic emulsion supply through backward integration into propylene derivative production or locked resin offtake agreements with German and South Korean petrochemical suppliers. Accelerate ECHA-compliant phosphorus-nitrogen flame-retardant qualification to defend European electrical tape positioning against regulatory displacement. Prioritize FDA 21 CFR Part 175 certification investment for medical-grade skin-contact portfolios as wearable device OEMs consolidate supplier bases.
For New Entrants and Emerging Players: Technical service integration gaps in Indian electronics assembly corridors offer white-space entry points for BIS-certified hypoallergenic tape specialists. Target continuous glucose monitor and cardiac patch converters with seven-day wear-duration acrylic formulations as FDA-compliant supply concentrates among incumbent oligopolists. Pursue direct procurement relationships with Bengaluru and Chennai wearable device assemblers bypassing distribution intermediaries.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional converters holding REACH-certified solvent-free coating capacity and established automotive Tier-1 relationships. Long-term viability over a five-to-ten-year horizon favors suppliers with mass-balance bio-based feedstock certification positioning for EU Green Deal procurement preferences. Monitor SAMR GB certification timeline compression as the inflection signal for China market access premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion | Captive propylene supply locks margin stability against petrochemical volatility for converters. |
| REACH-Compliant Flame-Retardant Reformulation | Phosphorus-nitrogen chemistry substitution preserves EU electrical tape market access for German harness manufacturers. |
| FDA Biocompatibility Certification Investment | 21 CFR Part 175 compliance opens wearable medical device procurement to tape specialists. |
| Direct Procurement Relationship Development | Battery pack assemblers in South Korea prioritize technical service integration over distributor breadth. |
| Bio-Based Feedstock Mass-Balance Certification | EU Green Deal procurement windows favor suppliers with sustainability credential differentiation. |
Methodological Framework
Cross-validation between converter production data and automotive OEM procurement disclosures anchors the qualitative findings in this study. Primary interviews with adhesive formulation chemists, Tier-1 supplier procurement directors, medical device regulatory affairs leads, and distribution channel partners were synthesized with secondary validation from ECHA regulatory filings, SAMR certification databases, customs trade records, and SEC 10-K supply chain disclosures. Bottom-up tape consumption modeling by end-use vertical and top-down petrochemical feedstock demand analysis were triangulated to establish volume estimates.
Sensitivity analysis around propylene price elasticity and electric vehicle battery production ramp rates tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product construction type, substrate material chemistry, end-use application vertical, and regional regulatory cluster. CAGRs were derived from slope-log regression of annualized consumption estimates. Industry-specific forecast inputs incorporate automotive thermal-interface content-per-vehicle trajectories and medical wearable device attachment surface-area requirements.
Forecasts assume regulatory continuity in REACH, FDA 21 CFR Part 175, and SAMR GB standards regimes; material policy shifts would require re-modeling of compliance cost pass-through and certification timeline impacts. Practitioners should keep alternative scenarios live as ECHA substance restriction amendments and EU Green Deal chemical disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Aerospace Tapes Market
Tapes
Sterilization Tape Market
Tapes
Thread Seal Tape Market
Tapes
Masking Tape Market
Tapes
Strapping Supplies Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Foil Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Mastic Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Building and Construction Tapes Market