
 Acetate Cloth Tape Market | 2026-2036
Acetate Cloth Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Acetate Cloth Tape Market Outlook
Automotive electrification specialists are redrawing procurement patterns for acetate cloth tape as EV motor and battery pack assembly expands. Nitto Denko Corporation leverages its polymer chemistry heritage to dominate high-temperature adhesive grades for traction motor insulation. 3M Company sustains broad channel control across wholesale distributors and direct OEM contracts in North America. Tesa SE anchors European supply through REACH-compliant formulations that serve German automotive tier-1s.
Acetate cloth tape consists of woven cellulose acetate fabric coated with pressure-sensitive adhesive, typically rated for continuous operating temperatures between 105°C and 130°C, serving primarily as electrical insulation and coil winding fixation in motors and transformers. Single-sided tape occupies the largest volume share due to its ubiquity in transformer manufacturing and general maintenance workflows, while specialty tape commands the strongest margin pool where UL-certified flame-retardant grades address aerospace and rail applications. Double-sided tape represents the fastest-growing structural category as automakers adopt laminated insulation systems for compact power-dense motor designs.
FDA and OSHA frameworks govern workplace exposure limits during tape manufacturing and application in US facilities, while REACH and RoHS directives in Europe restrict phthalate plasticizers and heavy metal stabilizers in adhesive backings. The EU F-Gas Regulation indirectly shapes demand by accelerating transitions to electrical systems requiring more robust insulation materials. Stakeholders must monitor evolving flammability certifications and regional chemical restrictions to maintain product registration and avoid supply disqualification in regulated end markets.
Market Dynamics
Automotive electrification is compressing insulation material specifications as EV traction motors demand thinner, thermally stable coil winding fixation that withstands higher operating temperatures than legacy internal combustion systems.
Growth Catalysts
- EV Powertrain Expansion:Traction motor production volumes in China, Germany, and the United States are pulling acetate cloth tape procurement into long-term supply agreements with tier-1 automotive suppliers.
- REACH Compliance Mandates:European halogen-free adhesive requirements are accelerating formulation upgrades that command premium positioning in transformer and rail applications.
- Transformer Replacement Cycles:Aging grid infrastructure across Japan and South Korea is generating maintenance demand for UL-certified insulation tapes in utility-scale equipment.
Market Restraints
- Cellulose Acetate Supply Concentration:Woven fabric substrate production clusters in East Asia create single-source vulnerability for tape manufacturers outside the region.
- Silicone Adhesive Substitution:High-temperature silicone tapes rated above 180°C are displacing acetate grades in aerospace engine compartment applications where thermal margins have widened.
- RoHS Compliance Costs:European heavy metal restrictions in adhesive stabilizers are forcing reformulation investments that compress margins on standard-grade products.
Strategic Opportunities
- Indian Manufacturing Localization:BIS certification requirements and domestic content incentives under the PLI scheme are opening captive supply opportunities for acetate cloth tape production serving motor and transformer OEMs.
- Battery Pack Thermal Management:Laminated insulation systems in pouch cell assembly are creating double-sided tape applications that did not exist in conventional cylindrical cell designs.
- EU F-Gas Regulation:Accelerated phase-down of fluorinated greenhouse gases is driving HVAC system electrification that requires more robust electrical insulation in compressor motors and fan drives.
Industry Challenges
- Adhesive Chemist Talent Scarcity:Formulation expertise for halogen-free, high-shear pressure-sensitive adhesives is concentrated among retiring specialists in Japanese and German chemical firms.
- UL Certification Timelines:Extended flame-retardant testing protocols for rail and aerospace grades are delaying product launches by 18-24 months.
- Legacy Equipment Integration:Tape slitting and winding machinery in Southeast Asian contract manufacturers requires retrofitting to handle thinner, higher-tensile acetate substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetate Cloth Tape Market |
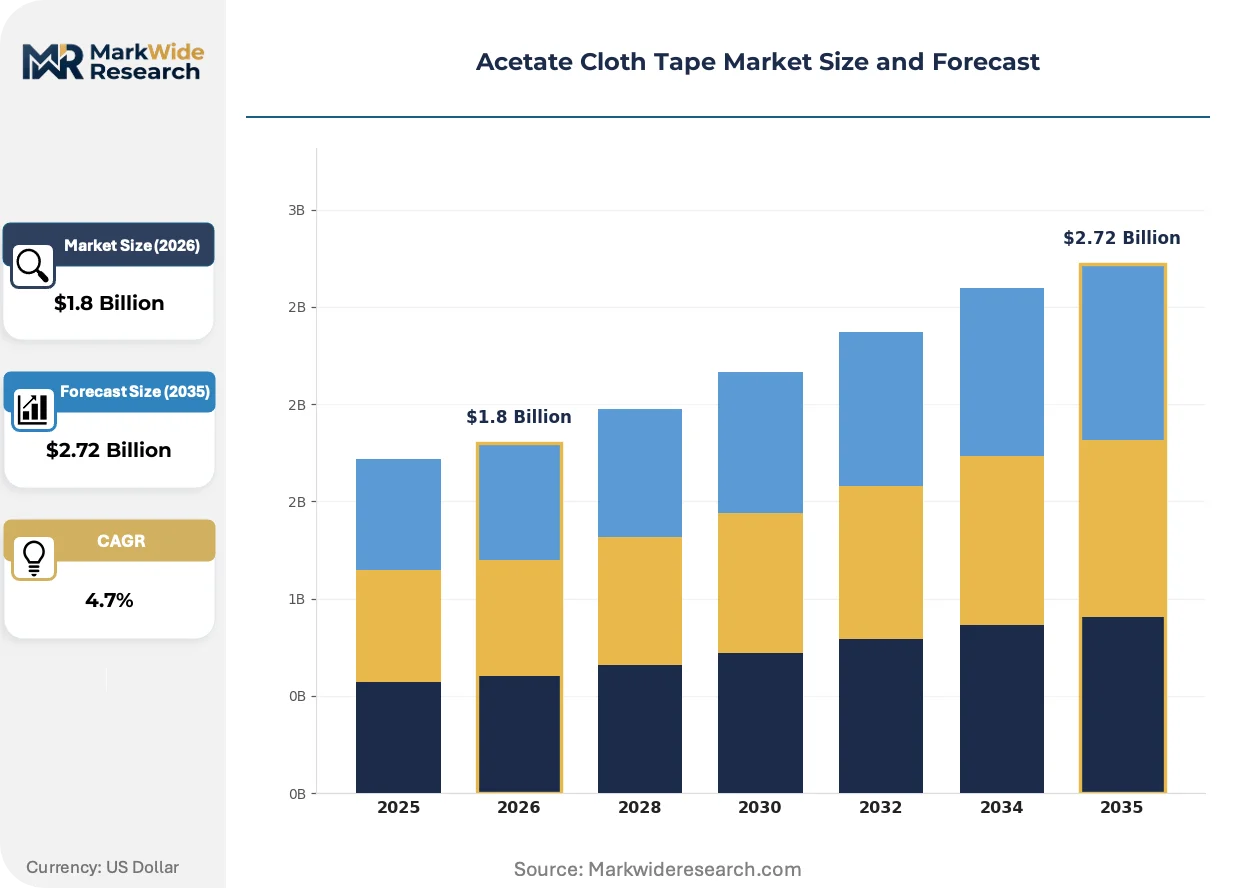
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tape, Double-Sided Tape, Transparent Tape, Specialty Tape End User: Packaging, Automotive, Construction, Electronics Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales Application: General Maintenance, Repair, Surface Protection, Crafting |
| Companies Covered | 3M Company, Nitto Denko Corporation, Teraoka Seisakusho Co., Ltd., Parafix Tapes & Conversions Ltd, PPI Adhesive Products, Kruse Adhesive Tape, Symbio, Inc., Kingzom Co., Limited, Tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetate Cloth Tape Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine acetate cloth tape performance benchmarks across automotive, energy, and industrial verticals.
Ultra-thin acetate substrates below 0.08mm thickness are enabling higher slot fill factors in hairpin-wound EV motors. German and Japanese automakers are qualifying these grades for 800V architectures. The technology is miniaturizing motor footprints while maintaining dielectric integrity.
REACH Annex XVII restrictions on phthalate plasticizers are forcing adhesive suppliers to migrate toward bio-based tackifier systems. ECHA enforcement actions against non-compliant imports are tightening border controls. European transformer manufacturers are now demanding full material disclosure documentation from Asian tape suppliers.
Consolidated procurement through automotive tier-1s is displacing fragmented distributor purchasing in the EV supply chain. Direct OEM contracts with adhesive coaters are replacing spot-market buying for high-volume motor programs. This concentration is most visible in China's Yangtze River Delta manufacturing cluster where CATL and BYD supplier parks dominate tape specification authority.
Acetate Cloth Tape Market Segmentation
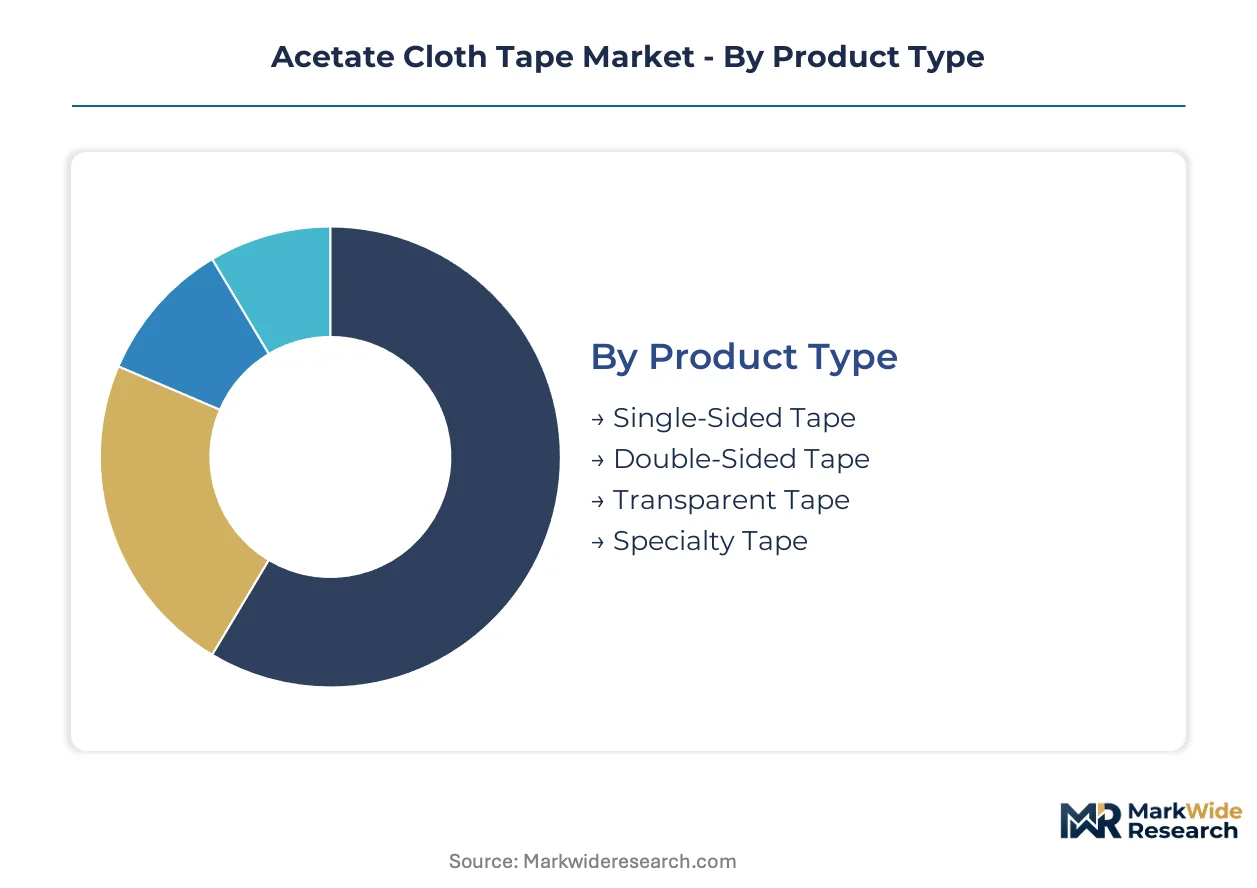
Acetate cloth tape segmentation reveals divergent margin profiles across product architectures and channel structures. Specialty formulations and direct OEM supply relationships concentrate value capture, while commodity single-sided grades compete on throughput efficiency in fragmented distributor networks.
Product Type:
Specialty and double-sided configurations command the widest margin spreads, driven by certification requirements and automotive qualification timelines that limit supplier entry.
- Single-Sided Tape:Woven cellulose acetate fabric with pressure-sensitive adhesive on one face, rated for 105°C to 130°C continuous operation. Transformer manufacturers in China and Japan consume the largest volumes for coil winding fixation, though price competition from regional coaters compresses margins on standard grades.
- Double-Sided Tape:Adhesive coatings on both substrate faces enable laminated insulation systems for compact EV motor designs. German and Japanese automakers are qualifying these grades for 800V traction motor architectures, creating the steepest expansion trajectory among all product types as power density requirements intensify.
- Transparent Tape:Low-pigmentation acetate substrate maintains optical clarity for aesthetic-sensitive applications. Electronics assembly in South Korea utilizes these grades where visual inspection of underlying components remains necessary.
- Specialty Tape:UL-certified flame-retardant and halogen-free formulations serve aerospace and rail applications. REACH compliance mandates in Europe and FAA flammability protocols in the United States create regulatory moats that sustain premium positioning.
Single-sided tape holds installed capacity. Double-sided tape is rotating up the share rankings.
End User:
Electronics and automotive verticals drive specification intensity, with EV powertrain electrification rewriting procurement standards for thermal and dielectric performance.
- Electronics:Coil winding and transformer insulation dominate consumption, particularly for EV powertrain components and grid infrastructure replacement cycles in Japan and South Korea. UL certification requirements and RoHS compliance costs shape supplier selection.
- Automotive:Traction motor and battery pack assembly are pulling acetate cloth tape into long-term supply agreements with tier-1 suppliers. Hairpin-wound motor designs utilizing ultra-thin substrates below 0.08mm thickness are gaining share fastest as 800V architectures proliferate.
- Packaging:General-purpose sealing and bundling applications utilize economy-grade single-sided tapes. Price sensitivity limits formulation innovation in this segment.
- Construction:Surface protection and temporary fastening represent opportunistic demand with minimal specification barriers. Regional construction cycles in Germany and the United States influence volume fluctuations.
Electronics maintains the deepest specification moats. Automotive is climbing the fastest as electrification accelerates.
Distribution Channel:
Channel economics bifurcate between high-touch direct OEM contracts and transactional wholesale throughput, with automotive consolidation favoring the former.
- Direct Sales:Long-term supply agreements with automotive tier-1s and transformer OEMs concentrate volume and specification authority. CATL and BYD supplier parks in China's Yangtze River Delta exemplify this channel's dominance in EV supply chains.
- Wholesale Distributors:Broad inventory availability serves maintenance, repair, and operations demand across fragmented industrial accounts. 3M Company sustains channel control through this structure in the United States.
- Specialty Stores:Technical product expertise supports specification-sensitive applications in aerospace and rail. ECHA enforcement actions against non-compliant imports are tightening European border controls, elevating the value of traceable supply.
- Online Retail:Low-friction procurement serves small-volume crafting and general maintenance segments. Price transparency limits margin expansion in this channel.
Direct sales commands specification authority. Wholesale distributors retain volume throughput leadership.
Application:
Functional differentiation separates high-reliability industrial uses from discretionary consumer applications, with thermal management emerging as a new specification vector.
- General Maintenance:Transformer and motor repair operations in aging Japanese and South Korean grid infrastructure generate recurring demand for UL-certified insulation tapes. Replacement cycles provide defensive volume stability.
- Repair:Electrical equipment refurbishment in industrial settings requires dielectric integrity verification. REACH Annex XVII restrictions on phthalate plasticizers are forcing adhesive migration toward bio-based tackifier systems in European-serving applications.
- Surface Protection:Temporary masking and finishing aid in manufacturing workflows. Construction and electronics assembly in Germany utilize these grades for process control.
- Crafting:Hobby and educational applications represent price-elastic demand with minimal technical requirements. Online retail penetration is highest in this segment.
General maintenance anchors replacement-driven volume. Repair applications are expanding most quickly as regulatory chemistry constraints create upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors East Asian acetate cloth tape flows, handling substrate imports and finished tape exports for transformer and motor manufacturers across the Yangtze River Delta manufacturing belt.
China
CATL and BYD supplier parks in the Yangtze River Delta drive procurement concentration for EV traction motor insulation. MIIT dual carbon goals accelerate halogen-free adhesive adoption in domestic transformer production. Shenzhen-based coaters are expanding slitting capacity to serve battery pack assembly lines for export markets.
Japan
Aging grid infrastructure across the Kanto and Kansai regions sustains maintenance demand for UL-certified coil winding tapes. METI energy efficiency mandates push transformer OEMs toward higher thermal grade specifications. Nagoya-area manufacturers dominate ultra-thin substrate development for 800V motor architectures.
Germany
BMW and Volkswagen tier-1 suppliers in Bavaria and Baden-Württemberg specify REACH-compliant halogen-free grades for traction motor programs. ECHA enforcement actions against phthalate-containing imports tighten border controls at Rotterdam and Hamburg. The Stuttgart industrial cluster hosts adhesive formulation R&D for next-generation EV insulation systems.
United States
EPA and OSHA frameworks govern workplace exposure limits at tape slitting facilities in Ohio and Illinois. FERC grid modernization initiatives stimulate transformer replacement cycles across the Midwest and Texas. Detroit-area automotive tier-1s are consolidating procurement through direct OEM contracts rather than distributor channels.
India
BIS certification requirements and PLI scheme domestic content incentives open captive supply opportunities for motor and transformer OEMs. CEA grid expansion targets in Maharashtra and Gujarat pull insulation material demand from regional distributors. Tamil Nadu-based contract manufacturers are retrofitting slitting equipment to handle thinner acetate substrates.
Acetate Cloth Tape Market Competitive Environment
Listed leaders compete with private specialists across formulation chemistry and channel control dimensions. The vendor base stratifies into three tiers: multinational adhesive conglomerates with polymer heritage, regional coaters with substrate slitting scale, and niche specialists with UL certification depth. Competitive moves center on REACH-compliant formulation upgrades and direct OEM contract consolidation in automotive supply chains.
Among Japanese chemical conglomerates, Nitto Denko Corporation and Teraoka Seisakusho Co., Ltd. exemplify the polymer heritage archetype with deep formulation expertise. Tesa SE anchors European supply through REACH-compliant positioning. 3M Company represents the channel control archetype with wholesale distributor relationships across North American industrial accounts.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| Teraoka Seisakusho Co., Ltd. |
| Parafix Tapes & Conversions Ltd |
| PPI Adhesive Products |
| Kruse Adhesive Tape |
| Symbio, Inc. |
| Kingzom Co., Limited |
| Tesa SE |
| Others |
Value Chain & Pricing Dynamics
Halogen-free adhesive migration is simultaneously redrawing raw material sourcing maps and compressing margin structures for standard-grade acetate cloth tape producers. European REACH mandates are forcing coaters to abandon legacy phthalate-based tackifier systems sourced from East Asian petrochemical clusters, triggering reformulation costs that propagate through distributor pricing tiers while premium-certified grades capture widening spreads.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs acetate cloth tape transactions. UL-certified flame-retardant grades for aerospace and rail command the widest premiums due to certification moats and testing timelines, while standard single-sided transformer grades face cost compression from regional Chinese coaters. Price differentiation hinges on certification tier and volume scale, with automotive tier-1 direct contracts locking in annual volume commitments that shield qualified suppliers from spot-market volatility. Margins are tightening in the standard-grade tier due to cellulose acetate substrate concentration in East Asian weaving mills. Packaging and crafting segments exhibit the highest price sensitivity, sourcing through wholesale distributors and online retail channels with minimal specification barriers.
Supply Chain Analysis
Inbound logistics costs through the Port of Shanghai fluctuate with container availability on Asia-Europe trade lanes, directly impacting landed costs for European transformer manufacturers dependent on Chinese substrate supply. Woven cellulose acetate fabric production concentrates in China and Japan, with adhesive coating and slitting operations distributed across Germany, the United States, and India. The supply chain draws from cellulose acetate flake, pressure-sensitive adhesive resins, and release liner films as core inputs. Single-source vulnerability in East Asian substrate weaving creates structural risk for tape manufacturers outside the region. Distribution runs through direct OEM contracts for automotive electrification programs and wholesale distributor networks for maintenance and repair demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for halogen-free, high-shear pressure-sensitive adhesives has become the critical scarcity in this market, with retiring specialists at Japanese and German chemical firms leaving capability gaps that resist rapid replication. This talent compression shapes competitive durability across all strategic positions.
For Market Incumbents: Shield market position by deepening captive supply relationships with cellulose acetate substrate weavers in the Yangtze River Delta and Nagoya industrial clusters. Accelerate UL certification pipelines for 800V motor grades before qualification windows close at German and Japanese automakers. Silicone adhesive substitution in aerospace applications and emerging Indian coaters with PLI scheme backing represent the most acute threats to margin maintenance. For New Entrants and Emerging Players: Aftermarket technical service for aging Japanese and South Korean grid infrastructure presents the most penetrable white-space opportunity, as incumbent distributors lack dielectric integrity verification capabilities. Target BIS certification pathways for Maharashtra and Gujarat transformer OEMs before domestic content incentives mature. A specification-support go-to-market angle—providing material disclosure documentation for REACH compliance—differentiates against commodity coaters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European adhesive coaters holding REACH-compliant formulation libraries but lacking automotive qualification depth. Long-term viability across the analysis window favors targets with direct OEM contracts in EV powertrain supply chains rather than distributor-dependent revenue. The signal to watch is UL certification timeline compression for rail and aerospace grades, which would indicate regulatory moat erosion and trigger portfolio rebalancing toward automotive-exposed assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Acetate Substrate | Captive weaving capacity in East Asia insulates against single-source supply disruption for tape coaters. |
| REACH-Compliant Formulation Upgrade | Halogen-free adhesive migration unlocks premium positioning in German automotive tier-1 supply chains. |
| Long-term Supply Agreement with EV Motor OEM | Direct contracts with CATL and BYD supplier parks secure volume visibility across 800V architecture ramp. |
| Joint Venture with Indian Contract Manufacturer | PLI scheme alignment and BIS certification accelerate localization for Maharashtra transformer OEM demand. |
| Specialty Store Channel Expansion | Technical specification expertise captures aerospace and rail procurement requiring traceable REACH documentation. |
Study Parameters
The analysis maps single-sided, double-sided, transparent, and specialty acetate cloth tape configurations, each validated through procurement managers at automotive tier-1 suppliers, transformer OEM technical directors, adhesive coater operations heads, and wholesale distributor category managers. Primary fieldwork combined with secondary validation from customs trade databases, MIIT production statistics, ECHA substance registration filings, and SEC 10-K disclosures from listed adhesive conglomerates. Bottom-up volume builds from slitting capacity and substrate consumption patterns triangulated against top-down macroeconomic drivers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end-user vertical, distribution channel, and application dimensions alongside regional production cluster dynamics. CAGRs derived from segment-level growth rate reconciliation with macroeconomic indicators. Industry-specific forecast inputs included EV powertrain production schedules, transformer replacement cycle data from Japanese utilities, and REACH Annex XVII enforcement trajectory.
Underlying assumptions cover sustained automotive electrification investment, continued East Asian substrate supply dominance, and stable regulatory chemistry constraints, with deviation risk concentrated in cellulose acetate feedstock price volatility and UL certification timeline extensions. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
India Masking Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Heat Release Tape Market
Tapes
ESD Tapes and Labels Market
Tapes
Filmic Tapes Market
Tapes
Removal Strips Market
Tapes
Dicing Tapes Market
Tapes
Glue Tape Market
Tapes
High Bond Tape Market
Tapes
Europe Packaging Tapes Market
Tapes
Foil Tapes Market
Tapes
Mastic Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Strapping Tapes Market