
 Utility Grade Duct Tapes Market | 2026-2036
Utility Grade Duct Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Grade Duct Tapes Market Analysis
Multi-source procurement among industrial distributors is hardening as buyers seek supply resilience against resin volatility. 3M Company anchors its position through captive polyethylene compounding operations that buffer raw material swings. Intertape Polymer Group competes via specialized waterproof tape formulations engineered for outdoor electrical sealing. Berry Global Group leverages its North American manufacturing scale to sustain contractor channel dominance.
Utility grade duct tape denotes a pressure-sensitive adhesive tape constructed from polyethylene-laminated cloth scrim with a synthetic rubber adhesive, typically rated for tensile strength between 20 and 35 pounds per inch and service temperatures from 40°F to 200°F, designed for general bundling, sealing, and temporary repair across commercial and industrial environments. Heavy Duty and Flame Retardant variants command premium positioning as building code enforcement intensifies, while General Purpose volumes remain the baseline revenue pool across retail and contractor channels. Polyethylene and Fabric materials occupy the structural core of the market, with Aluminum Foil tapes carving a defensible niche in HVAC duct sealing where thermal reflectivity specifications matter.
OSHA workplace safety standards and EPA VOC emission regulations for adhesive products constrain formulation choices and elevate compliance costs for domestic manufacturers. The EU REACH framework and RoHS directives shape export qualification requirements for tape producers serving European industrial distributors. Stakeholders must monitor evolving flammability testing protocols and resin substitution pathways as regulatory thresholds tighten without grandfathering legacy formulations.
Market Dynamics
Federal infrastructure spending in the United States is compressing procurement cycles and forcing distributors to hold larger polyethylene resin inventories to meet contractor demand spikes.
Growth Catalysts
- OSHA flame-retardant mandates:Commercial building retrofits in the United States now require certified tapes, pulling premium-grade volumes through mechanical contractor channels.
- HVAC duct sealing specifications:Thermal reflectivity requirements in federal building codes are accelerating aluminum foil tape adoption across facility maintenance programs.
- Polyethylene compounding advances:Captive resin processing capabilities are insulating major suppliers from petrochemical price swings and securing contractor loyalty.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings compress margins for non-integrated tape converters dependent on spot resin markets.
- Adhesive formulation constraints:EPA VOC emission limits restrict solvent-based rubber adhesives, forcing costly waterborne system conversions without performance parity.
- Mechanical fastening substitution:Cable tie and clamp systems in industrial bundling applications displace general-purpose duct tape in permanent installations.
Strategic Opportunities
- Data center construction surge:Hyperscale facility builds in Northern Virginia and Dallas-Fort Worth are creating specialized demand for low-outgassing, cleanroom-compatible tape formulations.
- Electric vehicle battery plant retrofits:Thermal management sealing requirements in Michigan and Tennessee assembly facilities favor high-temperature aluminum foil variants.
- Buy American procurement preference:Federal infrastructure awards now prioritize domestic tape sourcing, advantaging North American manufacturing footprints.
Industry Challenges
- Flammability certification timelines:UL 723 and ASTM E84 testing backlogs delay new product launches by four to six months, freezing inventory investment.
- Adhesive chemist talent scarcity:Formulation expertise in synthetic rubber compounding is concentrating at legacy manufacturers, constraining new entrant R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Grade Duct Tapes Market |
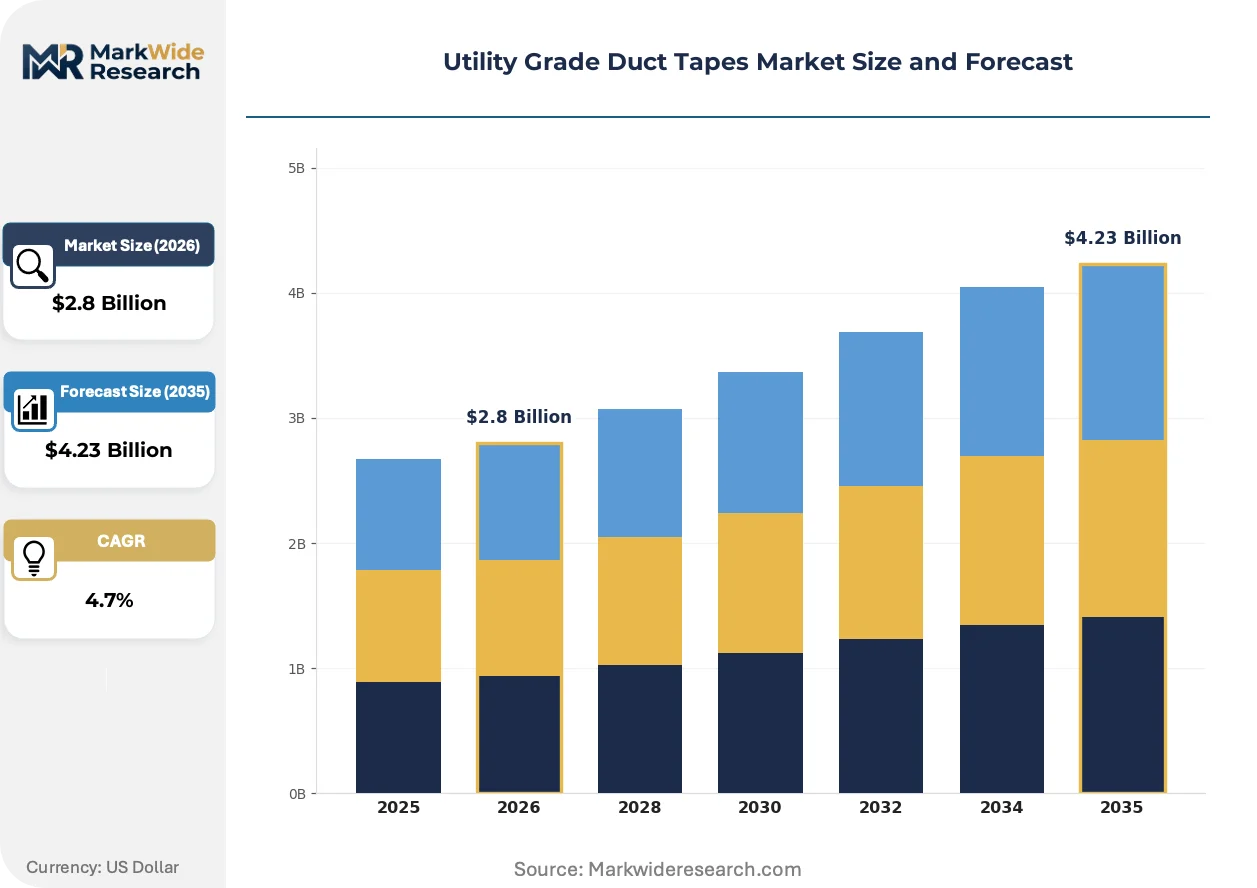
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, Waterproof, Heavy Duty, Flame Retardant Material: Polyethylene, Fabric, PVC, Aluminum Foil Application: Construction, Automotive, Electrical, HVAC End User: Contractors, DIY Consumers, Industrial Users, Retailers |
| Companies Covered | 3M Company, Intertape Polymer Group, Shurtape Technologies, Berry Global Group, tesa SE, Pro Tapes & Specialties, Nadco Tapes & Labels, MBK Tape Solutions, Scapa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Grade Duct Tapes Market Emerging Trajectories
Formulation chemistry and procurement logistics are absorbing the bulk of competitive investment as manufacturers defend margin structures against resin volatility and regulatory compliance costs.
Hot-melt synthetic rubber adhesives are absorbing market share from solvent-based systems in general-purpose construction applications. Regional distributors serving residential contractors are adopting these formulations to avoid EPA VOC storage and handling liabilities. The shift is compressing solvent-based product lines into specialty industrial niches where performance specifications override compliance costs.
EPA enforcement of Clean Air Act standards for adhesive manufacturing is tightening volatile organic compound thresholds in tape production facilities. Domestic converters are absorbing capital costs for thermal oxidizer installations and aqueous adhesive line conversions. Smaller regional manufacturers without captive compounding operations are exiting the contractor channel rather than absorbing compliance infrastructure investments.
Multi-source resin procurement is hardening among industrial distributors as buyers seek supply resilience against polyethylene price spikes. Large mechanical contractors in Texas and Florida are qualifying secondary adhesive tape suppliers to prevent jobsite delays from single-source dependency. This behavior is fragmenting volume concentration among top-tier manufacturers and elevating regional converters with flexible compounding capabilities.
Utility Grade Duct Tapes Market Segmentation
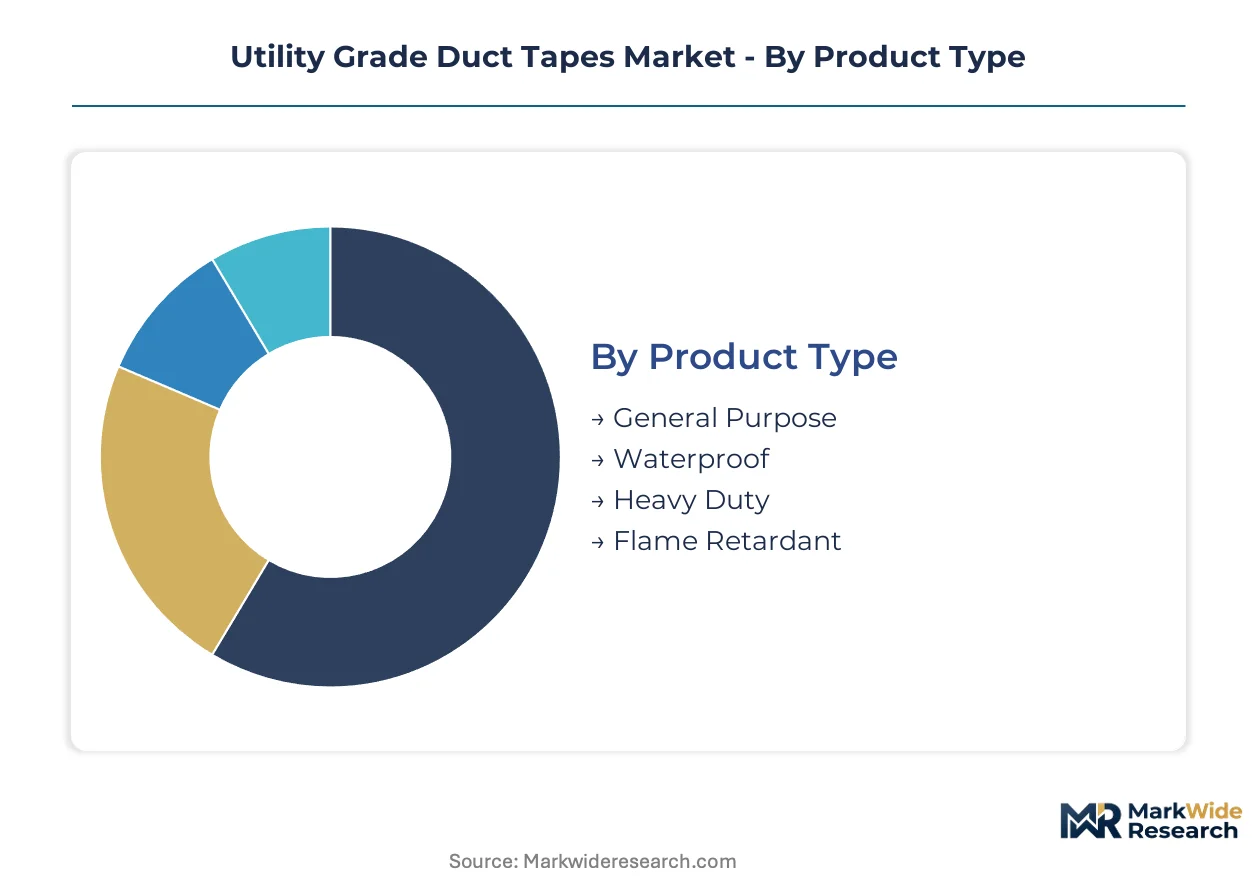
Segmentation in utility grade duct tapes reveals how formulation chemistry and procurement specifications diverge across use environments. Contractors specify heavy-duty and flame-retardant grades for code-compliant installations, while retail channels move general-purpose volumes for temporary repairs. Understanding these splits exposes where margin concentrates versus where volume scales.
Product Type:
General Purpose tapes function as standalone consumables for quick fixes, while Heavy Duty and Flame Retardant variants embed into certified building systems requiring documented compliance.
- General Purpose:Polyethylene-laminated cloth scrim with synthetic rubber adhesive rated for 20-25 pounds per inch tensile strength. Retail hardware chains and residential contractors in the United States sustain baseline volumes despite compression from cable tie substitution in permanent bundling.
- Heavy Duty:Reinforced scrim construction delivering 30-35 pounds per inch tensile strength with thicker polyethylene backing. Infrastructure maintenance crews across Texas and Florida specify these grades for outdoor temporary repairs where UV exposure and mechanical stress exceed standard tape capabilities.
- Waterproof:Specialized adhesive systems engineered for moisture-barrier sealing in outdoor electrical applications. Intertape Polymer Group competes through formulations targeting marine and utility infrastructure exposure.
- Flame Retardant:UL 723 and ASTM E84 certified constructions meeting OSHA workplace safety mandates for commercial building retrofits. EPA compliance costs and four-to-six-month certification timelines constrain supplier participation.
General Purpose leads volumes today; Flame Retardant is gaining share fastest.
Material:
Cost tier differentiation separates commodity polyethylene and fabric laminates from performance aluminum foil systems commanding specification-driven premiums.
- Polyethylene:Structural backbone of general-purpose and heavy-duty tapes, with captive compounding operations at major suppliers insulating against ethylene price volatility. 3M's integrated resin processing secures contractor channel loyalty through supply stability.
- Fabric:Woven cloth scrim providing tear resistance and hand-tearability across construction sites. The material dominates contractor procurement for temporary holding and surface protection where clean removal matters.
- PVC:Alternative backing for specialized electrical insulation tapes where dielectric strength requirements exceed polyethylene capabilities. Niche positioning in industrial maintenance programs.
- Aluminum Foil:Thermal reflectivity specifications in federal HVAC codes drive adoption across facility maintenance. Berry Global leverages North American manufacturing scale to sustain dominance in mechanical contractor channels specifying these grades.
Polyethylene and Fabric together anchor volume; Aluminum Foil is expanding most quickly.
Application:
Customer type concentration varies sharply: Construction absorbs contractor-specified premium grades, while Electrical and HVAC applications embed tapes into regulated building systems.
- Construction:General bundling, temporary weather sealing, and surface protection across commercial and residential builds. Federal infrastructure spending compresses procurement cycles and forces distributors to hold larger resin inventories.
- HVAC:Duct sealing specifications requiring thermal reflectivity and air-barrier performance. Aluminum foil tapes dominate this segment where building code enforcement intensifies.
- Electrical:Insulation and moisture sealing for outdoor utility infrastructure. Waterproof tape formulations from specialized suppliers address this specification-driven niche.
- Automotive:Temporary repair and wire harness bundling in assembly and aftermarket channels. Cable tie systems displace duct tape in permanent OEM installations.
Construction commands the largest volume position; HVAC shows the steepest expansion trajectory.
End User:
Procurement scale and specification authority separate institutional buyers from fragmented retail demand.
- Contractors:Mechanical and electrical contractors specifying certified grades for code-compliant installations. Multi-source qualification behavior is hardening among Texas and Florida contractors seeking supply resilience.
- Industrial Users:Manufacturing facilities and utility operators with formalized procurement programs. Data center construction in Northern Virginia and Dallas-Fort Worth creates specialized demand for cleanroom-compatible formulations.
- DIY Consumers:Retail hardware and home improvement channel purchasers driving general-purpose volume. Price sensitivity dominates with minimal specification requirements.
- Retailers:Distribution intermediaries consolidating fragmented demand and influencing private-label sourcing decisions. Regional distributors are adopting hot-melt adhesive formulations to avoid EPA VOC handling liabilities.
Contractors represent the fastest-expanding buyer segment; Retailers mediate the largest volume flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American demand concentration for utility grade duct tapes, driven by hyperscale data center construction and commercial HVAC retrofit intensity. Federal infrastructure awards and state-level building code enforcement create divergent procurement patterns across major economies.
United States
Federal infrastructure spending compresses contractor procurement cycles across Texas and Florida mechanical trades. OSHA flame-retardant mandates for commercial building retrofits pull premium-grade volumes through certified distribution channels. Northern Virginia data center clusters generate specialized demand for low-outgassing tape formulations compatible with cleanroom environments.
Germany
Industrial maintenance programs across the Ruhr and Bavaria sustain heavy-duty tape consumption for machinery bundling and temporary sealing applications. EU REACH framework and RoHS directives constrain adhesive formulation choices for exporters serving European distributors. Stuttgart automotive assembly facilities favor high-temperature aluminum foil variants for thermal management sealing in EV battery production lines.
China
Construction sector expansion in the Yangtze River Delta and Pearl River Delta drives general-purpose tape volumes for residential and commercial builds. MIIT industrial standards and GB certification requirements shape domestic product specifications for pressure-sensitive adhesives. Shenzhen electronics manufacturing clusters create demand for specialized electrical insulation tapes in wire harness assembly.
Japan
Precision manufacturing facilities in the Chubu region around Nagoya specify certified grades for automotive and aerospace component protection. METI energy efficiency regulations accelerate HVAC duct sealing tape adoption in commercial building retrofits. Osaka-Kobe industrial corridor distributors maintain multi-source qualification practices to mitigate supply disruption risks from petrochemical feedstock volatility.
India
Infrastructure development across Maharashtra and Gujarat construction markets sustains contractor channel growth for general-purpose and heavy-duty grades. BIS certification requirements for building materials tighten product compliance thresholds for domestic and imported tape suppliers. Bangalore-Telangana electronics manufacturing clusters generate emerging demand for cleanroom-compatible formulations in semiconductor assembly operations.
Utility Grade Duct Tapes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized waterproof and flame-retardant formulations to escape commodity pricing pressure. The market structure concentrates volume among integrated manufacturers with captive resin processing capabilities, while regional converters serve fragmented contractor demand through flexible compounding operations. Two strategic archetypes dominate: vertically integrated multinationals defending channel relationships through supply stability, and specialized regional fabricators capturing niche specification-driven segments. Competitive moves center on multi-source qualification partnerships with large mechanical contractors and thermal oxidizer investments to meet EPA VOC emission thresholds.
Among North American-integrated manufacturers, 3M Company and Berry Global Group exemplify the supply-resilience archetype through captive polyethylene compounding operations that buffer raw material price swings. Intertape Polymer Group occupies a specialization position with waterproof tape formulations targeting marine and outdoor electrical sealing applications. These three anchors demonstrate how formulation chemistry expertise and resin integration separate sustainable competitors from margin-compressed converters dependent on spot market procurement.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group |
| Shurtape Technologies |
| Berry Global Group |
| tesa SE |
| Pro Tapes & Specialties |
| Nadco Tapes & Labels |
| MBK Tape Solutions |
| Scapa Group |
| Others |
Supply Flow & Price Mechanics
Hot-melt adhesive conversion in North American tape manufacturing is compressing solvent-based product margins while concentrating production among converters with thermal oxidizer infrastructure. This shift simultaneously elevates compliance costs for smaller regional players and hardens price discipline among integrated suppliers with captive polyethylene compounding.
Pricing Analysis
Ethylene and propylene price pass-through dominates contract negotiations between tape converters and mechanical contractors. Three-tier pricing structure across flame-retardant certified, heavy-duty reinforced, and general-purpose economy levels separates specification-driven premiums from commodity baseline. Cost compression in general-purpose grades is intensifying because cable tie substitution erodes permanent bundling demand. DIY consumers exhibit highest price sensitivity; data center contractors specifying cleanroom-compatible formulations show lowest.
Supply Chain Analysis
Reverse-logistics flows for tape products remain minimal given the consumable nature of utility-grade applications, though distributor inventory returns spike during resin price volatility windows. Manufacturing concentrates in the United States, China, and Germany, with polyethylene resin supply drawing from Gulf Coast petrochemical complexes. Single-source vulnerability runs through ethylene pipeline dependencies. Distribution runs through industrial distributors and mechanical contractor supply houses with multi-source qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States-Germany regulatory arbitrage on flame-retardant certification timelines creates margin capture opportunities for suppliers with dual UL 723 and CE marking capabilities.
For Market Incumbents: Deploy captive resin compounding to buffer petrochemical price swings and secure contractor loyalty against emerging waterproof tape specialists. Invest in thermal oxidizer infrastructure to meet EPA VOC thresholds before smaller competitors exit. Defend channel position by qualifying as secondary suppliers for Texas and Florida mechanical contractors pursuing multi-source resilience. For New Entrants and Emerging Players: Capture the cleanroom-compatible formulation niche serving Northern Virginia and Dallas-Fort Worth data center construction, where incumbent capacity concentrates on commodity grades. Target electric vehicle battery plant retrofits in Michigan and Tennessee with high-temperature aluminum foil variants. Enter through direct specification partnerships with mechanical engineering firms rather than distributor channel contests. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with flexible compounding capabilities but lacking EPA compliance infrastructure. Long-term viability over the next decade hinges on resin integration and certification asset ownership. Monitor UL 723 testing backlog durations as an inflection signal for product launch velocity and inventory investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Compounding | Captive resin processing insulates margins from ethylene price volatility and secures contractor supply agreements. |
| Thermal Oxidizer Installation for VOC Compliance | EPA Clean Air Act enforcement elevates capital barriers and accelerates competitor exit from contractor channels. |
| Dual Certification Investment (UL 723 and CE Marking) | Regulatory arbitrage between United States and German markets opens specification-driven premium capture. |
| Cleanroom-Compatible Formulation Development | Data center construction in Northern Virginia creates specialized demand underserved by commodity producers. |
| Multi-Source Qualification Partnerships | Texas and Florida mechanical contractors prioritize supply resilience over single-brand loyalty. |
Methodological Framework
Direct dialogue with adhesive tape plant managers, mechanical contractor procurement leads, industrial distribution channel partners, and EPA compliance officers grounded qualitative findings. Secondary validation drew from OSHA workplace safety filings, EPA Clean Air Act enforcement records, customs trade data on polyethylene resin imports, and SEC 10-K disclosures from integrated manufacturers. Bottom-up volume estimates from end-use application sizing triangulated against top-down petrochemical feedstock demand models.
Bottom-up segmentation modeling across product type, material composition, application environment, and end-user procurement scale generated volume and value outputs across the projection horizon. CAGRs derived from trend extrapolation of contractor channel expansion, regulatory mandate adoption curves, and resin price elasticity assumptions. Industry-specific forecast inputs included federal infrastructure spending allocation patterns and HVAC retrofit code enforcement intensity by state.
Ethylene price volatility, UL certification timeline extensions, and mechanical fastening substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions on regulatory grandfathering provisions and resin supply continuity. Practitioners should monitor OSHA enforcement intensity, petrochemical crack spread movements, and cable tie penetration rates in industrial bundling for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tape and Label Adhesives Market
Tapes
Packaging Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Sterilization Tape Market
Tapes
Global Non Woven Tape Market
Tapes
Duct Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Thermoplastic Tape Market
Tapes
Global Adhesive Tapes Market
Tapes
Global Surface Protection Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Mastic Tapes Market
Tapes
Tape Banding Machine Market
Tapes
Cable Wrapping Tapes Market
Tapes
Tapes Market
Tapes
Dicing Tapes Market