
 Industrial Tapes Market | 2026-2036
Industrial Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Tapes Market Intelligence
Automotive assembly is pivoting toward structural bonding tapes as OEMs replace mechanical fasteners to cut vehicle weight. 3M Company leverages its acrylic adhesive portfolio to dominate crash-durable bonding applications. Avery Dennison Corporation anchors North American supply through pressure-sensitive tape capacity near Detroit and Spartanburg. Nitto Denko Corporation specializes in thin-film electronic bonding tapes for EV battery module assembly.
Industrial tapes are flexible laminates coated with pressure-sensitive or heat-activated adhesives, typically 25–200 micrometers thick, designed for surface joining, sealing, masking, or electrical insulation without curing time. Adhesive tapes and specialty tapes lead volume, with specialty tapes capturing widening margin pools in electronics and medical-grade applications. Polyethylene and foam substrates are displacing legacy PVC in automotive and construction segments as thermal performance requirements tighten.
EPA regulates volatile organic compound emissions from adhesive tape manufacturing under 40 CFR Part 59, while REACH restricts phthalate plasticizers and heavy-metal pigments in European tape imports. OSHA workplace exposure limits for solvent-based adhesive handling shape plant-level procurement toward water-acrylic systems. Stakeholders must monitor evolving battery-grade tape certification standards as solid-state cell architectures redefine thermal runaway protection requirements.
Market Dynamics
Automotive OEMs are systematically replacing mechanical fasteners with structural bonding tapes to meet fleet-weight reduction mandates, compressing assembly timelines while forcing adhesive suppliers to certify crash-durable formulations under NHTSA and ECE R94 protocols.
Growth Catalysts
- EV Battery Thermal Management:Solid-state cell architectures require flame-retardant polyimide tapes for module-to-pack bonding, with OEMs specifying UL 94 V-0 certification as a procurement gate.
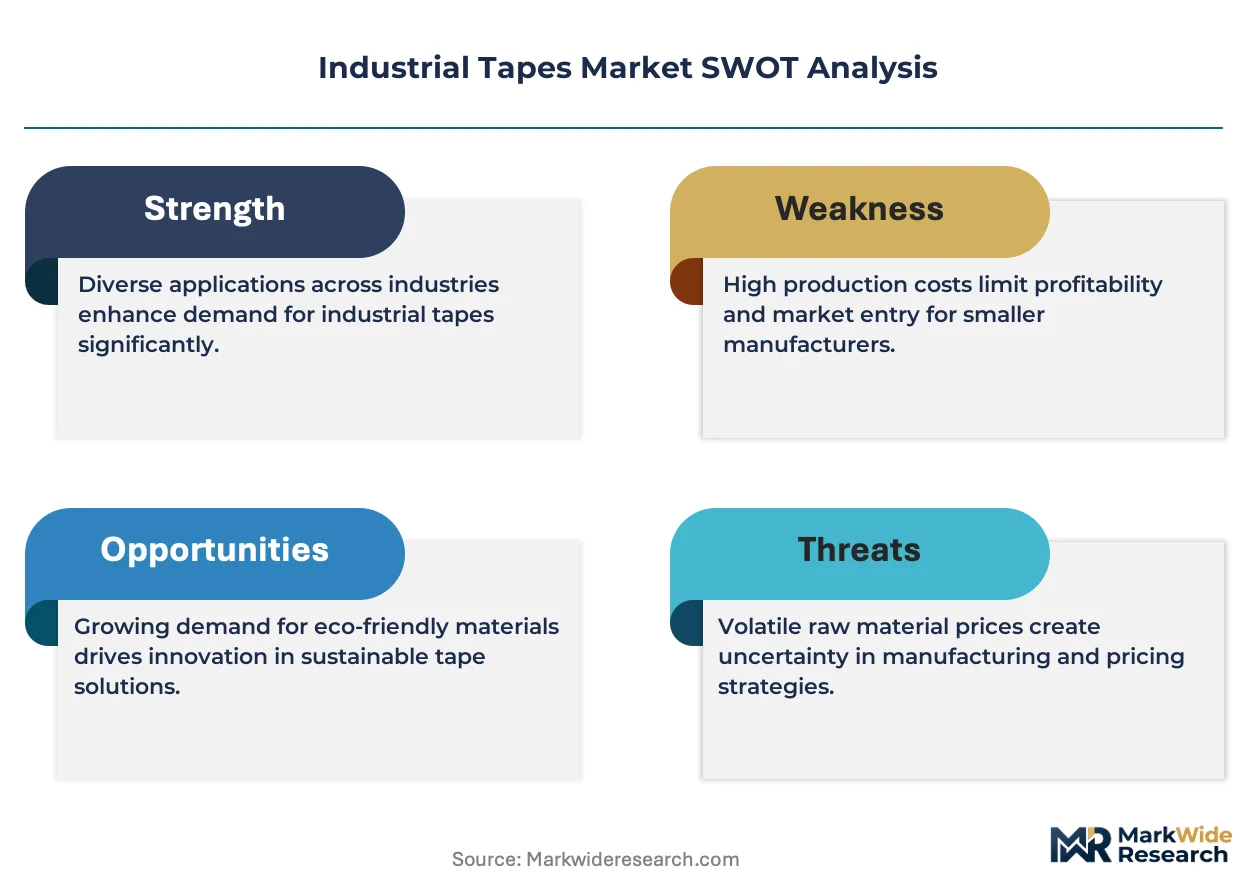
- REACH Phthalate Restrictions:ECHA's 2025 plasticizer ban is accelerating water-acrylic adhesive conversions among European converters, opening margin pools for compliant formulation specialists.
- China's Dual Carbon Goals:MIIT energy-efficiency mandates for manufacturing plants are driving solvent-to-hot-melt process conversions in Jiangsu and Guangdong tape production clusters.
Market Restraints
- Petrochemical Feedstock Volatility:Propylene and acrylic acid price swings compress converter margins, particularly for small-batch specialty tape producers lacking long-term supply contracts.
- Asian Substrate Concentration:BOPP film supply concentrates among Korean and Chinese petrochemical integrateds, creating single-source vulnerability for European and North American tape laminators.
- Mechanical Fastener Substitution Limits:Structural tapes face load-bearing constraints in heavy-truck chassis assembly, where bolted joints retain dominance for cyclic-stress applications.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for mobile and component manufacturing are attracting tape converters to set up bonded-warehouse operations near Chennai and Noida export zones.
- Medical-Grade Wearable Integration:Skin-contact silicone tape demand from continuous glucose monitor manufacturers offers 40-60 point gross margin premiums over industrial grades.
- EU CSRD Supply Chain Disclosure:Mandatory Scope 3 emissions reporting is creating first-mover advantage for tape suppliers with ISO 14064-certified carbon accounting and recycled-content substrates.
Industry Challenges
- Formulation Chemist Shortage:Water-acrylic polymer synthesis expertise is scarce as veteran solvent-based adhesive engineers retire, forcing converters to partner with university polymer science programs.
- Battery-Grade Certification Timelines:OEM qualification cycles for EV thermal-runaway protection tapes extend 18-24 months, locking out new entrants from platform awards.
- Legacy ERP Integration:Smaller tape converters struggle to integrate lot-traceability systems required by automotive Tier-1 suppliers, delaying IATF 16949 certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Tapes Market |
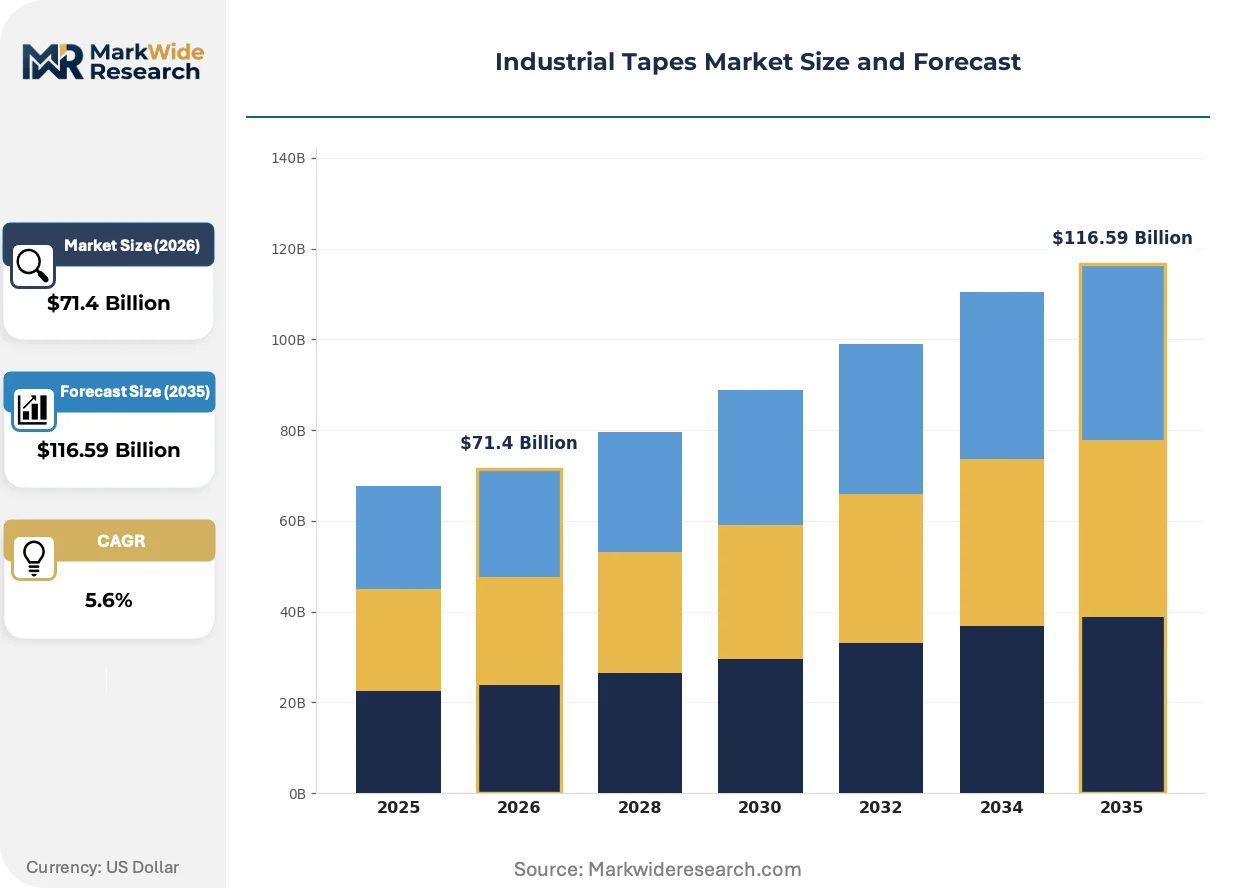
| Market Size in 2026 | $71.4 Billion |
| Market Size in 2035 | $116.59 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Tapes, Specialty Tapes, Duct Tapes, Masking Tapes Material: Polyethylene, Vinyl, Paper, Foam Application: Automotive Assembly, Electronics Manufacturing, Construction, Packaging End User: Manufacturers, Contractors, Retail, Maintenance Services |
| Companies Covered | 3M Company, Avery Dennison Corporation, Nitto Denko Corporation, Tesa SE, Intertape Polymer Group, Henkel AG & Company KGaA, Saint-Gobain, Lintec Corporation, Shurtape Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Tapes Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to redefine tape performance specifications across mobility, energy, and healthcare verticals. Formulation priorities now center on thermal stability, biocompatibility, and circular material flows.
Hot-melt pressure-sensitive adhesive technology is modularizing around metallocene-catalyzed olefin elastomers that deliver shear resistance without solvent-based processing. Automotive interior trim suppliers in Germany and Mexico are adopting these systems to eliminate VOC emissions from cockpit assembly operations. The shift is compressing capital requirements for new coating lines while disqualifying legacy solvent-based equipment from greenfield plant investments.
EPA's 40 CFR Part 59 Subpart F is tightening VOC content limits for adhesive tape manufacturing, forcing domestic converters to validate water-borne or UV-curable alternatives. The rule's 2025 compliance deadline has triggered capital allocation toward electron-beam curing systems among major industrial tape producers. Pressure-sensitive tape categories serving construction and DIY channels face the steepest reformulation costs due to volume scale and price sensitivity.
Automotive Tier-1 procurement teams are consolidating supplier panels and demanding IMDS-compliant material declarations for every substrate-adhesive combination. Tape converters must now maintain digital twin documentation of chemical composition across multi-layer laminates. This behavioral shift is most visible in Detroit and Spartanburg supply basins, where OEM platform teams have reduced qualified adhesive tape vendors by 30-40 percent over two program cycles.
Industrial Tapes Market Segmentation
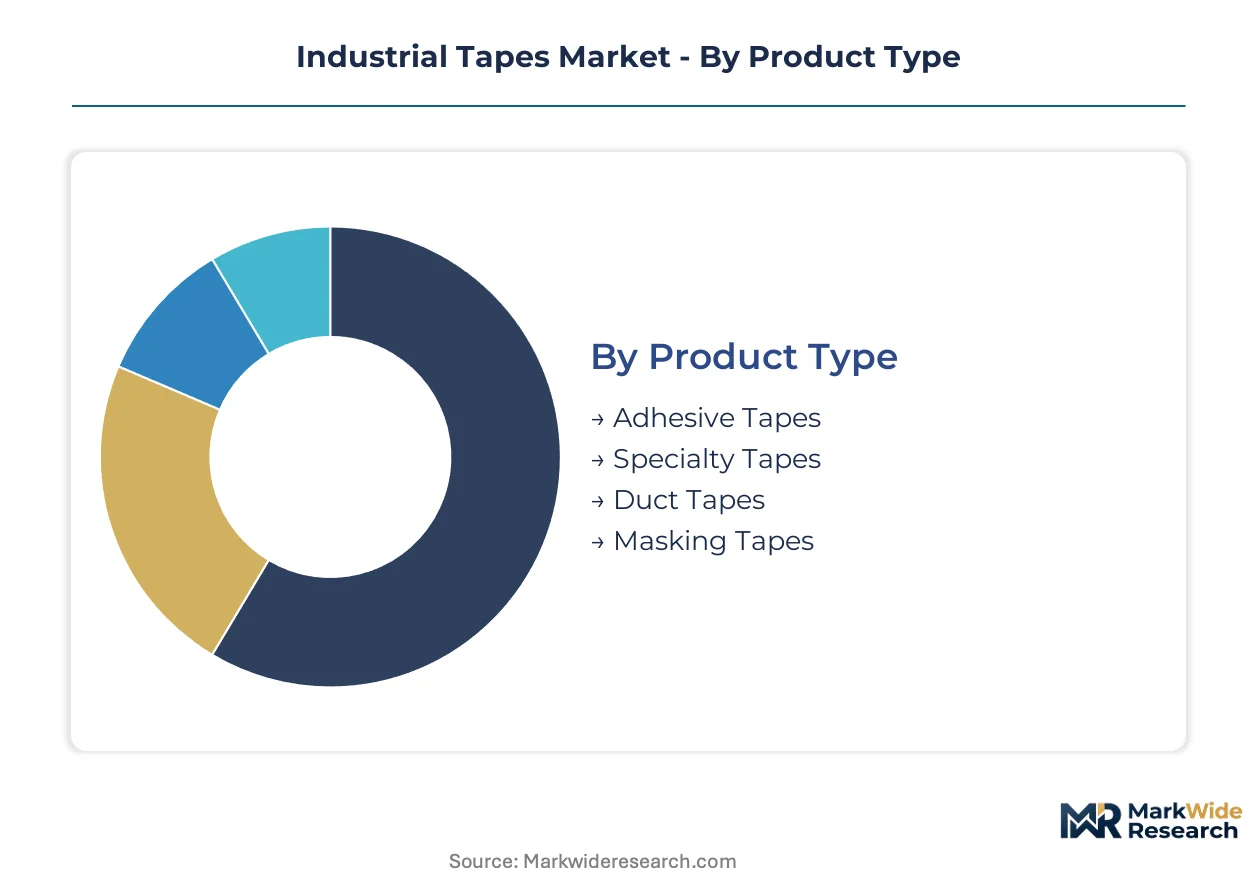
Industrial tape procurement diverges sharply across end-use verticals, with automotive and electronics buyers demanding certified thermal performance while construction and retail channels prioritize cost efficiency and availability. Material selection and adhesive chemistry must align with specific regulatory exposure and assembly process constraints.
Product Type:
Coating capacity concentrates among integrated petrochemical players in East Asia and Germany, with specialty tape lines commanding premium tolling fees due to cleanroom requirements and lot-traceability systems.
- Adhesive Tapes:Pressure-sensitive laminates using acrylic, rubber, or silicone adhesives on flexible backings serve general industrial bonding and sealing. Automotive assembly plants in Germany and Mexico specify these for interior trim fixation where VOC emissions must meet EPA limits.
- Specialty Tapes:Engineered for extreme thermal, electrical, or chemical resistance—polyimide films for EV battery module bonding dominate current capacity expansion. OEM qualification cycles extend 18-24 months, locking in supplier relationships.
- Duct Tapes:Polyethylene-coated cloth with natural rubber adhesive serves HVAC sealing and construction weatherproofing. Water-acrylic formulations are displacing solvent-based grades under REACH phthalate restrictions.
- Masking Tapes:Crepe paper backings with controlled adhesion enable clean removal after paint bake cycles. Automotive refinishing shops in the US specify temperature ratings up to 150°C for OEM color-matching operations.
Adhesive tapes absorb the bulk of installed capacity; specialty tapes are expanding most quickly.
Material:
Substrate selection determines thermal ceiling, chemical resistance, and recyclability profile—automotive electrification is forcing rapid displacement of legacy materials.
- Polyethylene:Linear low-density films dominate packaging and surface protection tapes. China's petrochemical integrateds control BOPP supply, creating single-source vulnerability for European laminators.
- Vinyl:PVC backings retain share in electrical insulation and floor marking despite REACH plasticizer scrutiny. Phthalate-free formulations command 15-20 point price premiums.
- Paper:Saturated kraft and crepe papers serve masking and splicing applications where conformability matters. Japanese suppliers lead thin-gauge specialty paper substrate production.
- Foam:Acrylic and polyurethane foam tapes enable gap-filling and vibration damping in automotive panel bonding. Double-coated foam constructions are displacing mechanical clips in EV battery pack assembly.
Polyethylene substrates anchor volume production; foam materials are climbing the fastest as vehicle lightweighting accelerates.
Application:
End-use process requirements dictate adhesive chemistry, backing thickness, and certification burden—electronics and automotive buyers impose the most stringent qualification protocols.
- Automotive Assembly:Structural bonding tapes replace spot welds and rivets in body-in-white and battery module construction. Crash-durable acrylic formulations must certify under NHTSA and ECE R94 protocols.
- Electronics Manufacturing:Thin-film polyimide and polyester tapes enable flexible circuit lamination and thermal management. Solid-state battery architectures are redefining flame-retardant specifications.
- Construction:Weather sealing, vapor barrier joining, and temporary surface protection drive volume. OSHA workplace exposure limits favor water-acrylic systems in commercial building projects.
- Packaging:Carton sealing and pallet unitization consume commodity-grade BOPP tapes. E-commerce fulfillment growth in India is attracting bonded-warehouse operations near Chennai export zones.
Automotive assembly commands the highest technical margins; electronics manufacturing is gaining share fastest on semiconductor reshoring.
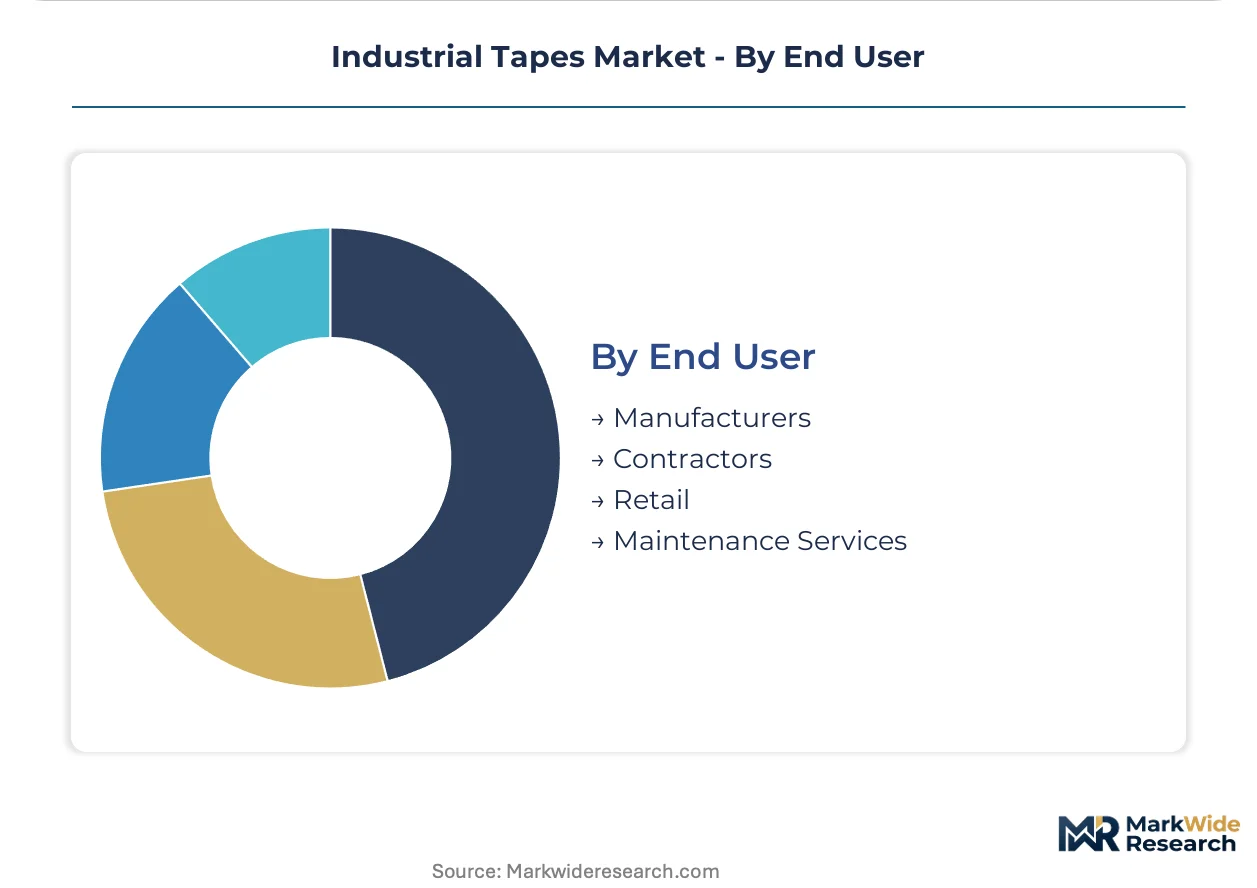
End User:
Procurement behavior fragments across direct OEM supply, distributor-led contractor channels, and retail DIY—each with distinct price sensitivity and technical support requirements.
- Manufacturers:Tier-1 automotive and electronics OEMs demand IATF 16949 certification, IMDS material declarations, and digital twin documentation. Supplier panels have consolidated 30-40 percent over recent program cycles.
- Contractors:Commercial construction and MRO buyers purchase through distributor networks with stock-and-serve logistics. Regional availability often overrides specification compliance.
- Retail:Home improvement and office supply channels move commodity SKUs with minimal technical differentiation. Price competition intensified as private-label sourcing shifted to Chinese integrateds.
- Maintenance Services:Industrial MRO and facility management prioritize SKU consolidation and same-day availability. Predictive maintenance programs are expanding consumption of condition-monitoring adhesive sensors.
Manufacturers concentrate specification power and margin capture; maintenance services are expanding most quickly on predictive asset management adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Jiangsu Province and export processing clusters near Chennai are concentrating tape manufacturing capacity as governments deploy tax incentives to capture automotive and electronics supply chains.
China
MIIT energy-efficiency mandates are accelerating solvent-to-hot-melt conversions in Jiangsu and Guangdong production clusters. The dual carbon goals framework tightens emissions standards for petrochemical-integrated tape substrate plants. Suzhou and Dongguan host the densest concentrations of BOPP film lamination capacity serving battery module and automotive interior applications.
Germany
ECHA's 2025 phthalate plasticizer ban is forcing water-acrylic adhesive conversions among Stuttgart-area automotive suppliers. REACH compliance costs are consolidating converter panels as Tier-1 OEMs demand IMDS material declarations. Bavaria's chemical corridor near Ludwigshafen anchors specialty polyimide tape development for EV thermal management systems.
United States
EPA's 40 CFR Part 59 Subpart F VOC limits are triggering capital allocation toward electron-beam curing systems among domestic producers. NHTSA crash-durable certification requirements shape procurement from Detroit and Spartanburg assembly basins. Michigan and South Carolina host the primary automotive tape qualification laboratories serving North American OEM platform teams.
Mexico
Nearshoring incentives under the IMMEX program are attracting tape converters to bonded-warehouse operations near Querétaro and Nuevo León automotive hubs. USMCA rules of origin compliance shapes substrate sourcing decisions for export-oriented laminators. The Bajío Region concentrates new coating line investments serving US-based EV battery and interior trim suppliers.
India
PLI scheme production-linked incentives for electronics manufacturing are drawing tape converters to Chennai and Noida export zones. BIS certification requirements for adhesive formulations create entry barriers for unqualified imports. Maharashtra and Tamil Nadu industrial corridors host emerging cleanroom tape capacity serving mobile device and component assembly operations.
Industrial Tapes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with adhesive formulation expertise concentrating among integrated petrochemical players while regional converters compete on logistics proximity. The market structure tiers between multinational chemical conglomerates with captive polymer supply and independent laminators dependent on toll coating arrangements. Three archetypes dominate: substrate-integrated multinationals, automotive-certified specialists, and regional construction-grade suppliers. Competitive moves center on IATF 16949 certification acquisition and water-acrylic formulation patent filings as regulatory deadlines approach.
Within the multinational tier, 3M Company and Avery Dennison Corporation exemplify the substrate-integrated archetype with polymer science capabilities spanning adhesive synthesis to finished tape lamination. Nitto Denko Corporation occupies a position bridging automotive and electronics verticals through thin-film bonding expertise. These three anchors represent distinct competitive vectors: broad portfolio coverage, regional supply chain density, and precision specialty focus respectively.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Tesa SE |
| Intertape Polymer Group |
| Henkel AG & Company KGaA |
| Saint-Gobain |
| Lintec Corporation |
| Shurtape Technologies |
| Others |
Cost & Logistics Intelligence
Tier-1 automotive procurement consolidation around IATF 16949-certified suppliers is compressing qualified vendor pools and forcing supply-side investments in lot-traceability systems that translate into tiered cost structures across the value chain.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to automotive-qualified specialty tapes against standard industrial grades. Three-tier pricing structure across premium, standard, and economy levels separates crash-durable acrylic formulations certified under NHTSA protocols from general-purpose pressure-sensitive laminates and commodity carton-sealing tapes. Cost compression in construction-grade BOPP tapes is intensifying because Chinese petrochemical integrateds are flooding export markets with excess substrate capacity. Retail DIY channels exhibit highest price sensitivity, while EV battery module suppliers accept premium positioning for UL 94 V-0 certified polyimide constructions.
Supply Chain Analysis
Acrylic acid and propylene feedstock supply rests on integrated petrochemical producers in China, South Korea, and Germany. BOPP film substrate draws from Korean and Chinese petrochemical complexes, while specialty polyimide films feed from Japanese and German chemical corridors. Single-source vulnerability concentrates in BOPP supply where three producers control 70 percent of export-grade capacity. Distribution runs through automotive Tier-1 supplier hubs near Detroit, Stuttgart, and Querétaro, with construction channels served by regional distributor networks carrying stock-and-serve inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom-grade coating capacity for battery and medical applications operates at effective utilization ceilings, propping pricing power for qualified converters and creating durable margin pools for first movers with certified assets.
For Market Incumbents: Deploy electron-beam curing capacity additions in Michigan and South Carolina to capture EPA 40 CFR Part 59 compliance-driven substitution demand from solvent-based competitors. Deepen captive polymer synthesis capabilities to offset propylene price volatility exposure. Consolidate supplier panels around IMDS-compliant digital twin documentation to lock out unqualified regional converters from automotive platform awards. For New Entrants and Emerging Players: Distributor partnerships with construction-focused regional networks offer lowest barrier entry into weather-sealing and HVAC applications where specification compliance is less stringent than automotive. Medical-grade silicone tape for continuous glucose monitor manufacturers represents the most penetrable white-space segment, with 40-60 point gross margin premiums over industrial grades. Target bonded-warehouse operations near Chennai and Noida to capture India PLI scheme electronics manufacturing demand without full BIS certification burden. For Investors and Strategic Acquirers: Re-rating potential sits with water-acrylic formulation specialists given ECHA 2025 phthalate ban acceleration and stranded solvent-based capacity risk. Five-to-ten year viability favors converters with ISO 14064-certified carbon accounting and recycled-content substrate pipelines aligned to EU CSRD Scope 3 disclosure mandates. Watch OEM qualification cycle completion rates for EV thermal-runaway protection tapes as inflection signal for platform award timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymer Synthesis | Captive adhesive supply insulates converters from propylene price volatility and secures formulation IP control. |
| Electron-Beam Curing Capacity Expansion | EPA 40 CFR Part 59 compliance positions converters for automotive interior trim procurement from Detroit OEMs. |
| Joint Venture with Chinese BOPP Producers | Long-term substrate offtake agreements reduce single-source vulnerability for European and North American laminators. |
| Green Manufacturing Transition | ISO 14064-certified carbon accounting creates first-mover advantage under EU CSRD Scope 3 supply chain disclosure rules. |
| Long-term Supply Agreement with EV Battery OEMs | Platform-level thermal management tape contracts lock in 18-24 month qualification cycles and exclude new entrants. |
Research Approach
Independent corroboration across converter plant managers, automotive Tier-1 procurement leads, and distribution channel partners underwrites the qualitative findings. Primary interviews with adhesive formulation R&D directors and regulatory affairs specialists at tape manufacturers were validated against secondary sources including EPA 40 CFR filings, ECHA REACH substance restrictions, and SEC 10-K disclosures from listed petrochemical suppliers. Bottom-up capacity assessments across Jiangsu, Guangdong, and Bavaria production clusters were triangulated with top-down demand modeling from automotive and electronics end-use verticals.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, material substrate, application vertical, and end-user procurement channel. Automotive electrification content-per-vehicle metrics and solid-state battery architecture adoption curves feed the specialty tape growth assumptions. CAGRs derive from weighted average of historical capacity expansion patterns and forward-looking OEM platform award schedules, with cross-validation against customs trade data for BOPP film and acrylic acid import flows.
Caveats apply where feedstock price volatility, regulatory deadline delays, or battery technology substitution could materially shift the outlook. Forecasts reflect assumptions about OEM qualification cycle timing and phthalate ban enforcement intensity. A small set of named triggers—ECHA plasticizer restriction implementation pace, MIIT energy-efficiency mandate stringency, and NHTSA crash-durable certification protocol updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Breathable Tape Market
Tapes
Smart Card Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
High Bond Tape Market
Tapes
Pucker Free Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Edge Band Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Global Surface Protection Tapes Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Thread Seal Tape Market
Tapes
Flatback Tapes Market
Tapes
Glue Tape Market
Tapes
Twist Tube Market
Tapes
Carbon Tapes Market
Tapes
Raffia Tapes Market