
 Vacuum Fillers Market | 2026-2036
Vacuum Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Fillers Market Analytics
German equipment manufacturing is hardening as the dominant supply base for precision vacuum filling systems. Vemag Maschinenbau GmbH leverages its Bavarian production footprint to dominate high-throughput meat processing lines. Albert Handtmann Maschinenfabrik GmbH & Co. KG anchors its position through deep specialization in portioning accuracy and integrated clipping technology. RISCO S.p.A. competes from Italy with strong export positioning across European protein processing facilities.
Vacuum fillers are enclosed pumping systems that evacuate air from product chambers before depositing precise volumes of liquids, pastes, powders, or granules into containers or casings, typically operating at vacuum levels between 85 and 95 percent to prevent oxidation and ensure density consistency. Automatic fillers command the largest installed base due to throughput requirements in high-volume food processing, while semi-automatic units retain relevance in mid-tier pharmaceutical batch operations where changeover flexibility matters more than line speed. Pneumatic technology leads the technology split for its reliability in washdown environments, though electric drive systems are gaining share in cleanroom pharmaceutical applications where energy precision and reduced contamination risk justify higher capital outlay.
FDA food safety regulations and EU hygiene standards for food contact machinery shape equipment design requirements, mandating stainless steel construction, CIP compatibility, and full traceability documentation that elevates compliance costs for market entrants. ISO 14159 hygiene design standards and 3-A Sanitary Standards in the United States further constrain product architecture, favoring incumbents with established certification portfolios. Stakeholders must weigh automation intensity against regulatory compliance breadth when evaluating capacity expansion or geographic diversification strategies.
Market Dynamics
Meat processors in Germany and the United States are consolidating production lines around enclosed vacuum filling architectures to satisfy escalating hygiene documentation requirements under EU MDR and FDA frameworks. This regulatory compression is forcing equipment replacement cycles and reshaping vendor qualification criteria.
Growth Catalysts
- EU MDR hygiene mandates:Food contact machinery must now demonstrate full material traceability and clean-in-place compatibility, accelerating stainless steel vacuum filler deployments across German and Italian meat processing facilities.
- Electric drive precision:Servo-controlled filling systems are penetrating pharmaceutical cleanrooms where dosage accuracy and energy efficiency outweigh pneumatic reliability advantages.
- Portioning automation:High-throughput sausage and prepared meat lines in the United States are integrating vacuum fillers with clipping and casing systems to reduce labor exposure and contamination risk.
Market Restraints
- Stainless steel input volatility:Grade 316L stainless steel price swings compress margins for equipment fabricators and extend quoting timelines for large-capacity systems.
- Precision component supply concentration:High-vacuum pumps and servo motors concentrate among German and Japanese suppliers, exposing lead time risk for non-integrated equipment builders.
- Technical limitation in powder handling:Vacuum filler architectures struggle with cohesive powder flow compared to auger or gravity systems, constraining penetration in nutritional supplement manufacturing.
Strategic Opportunities
- Cleanroom pharmaceutical expansion:Biologic drug manufacturers in Switzerland and Ireland are specifying vacuum fillers for aseptic filling of viscous parenteral formulations.
- Plant-based protein processing:Textured vegetable protein and mycoprotein processors require modified vacuum filler geometries to handle non-animal paste rheologies without structural degradation.
- ISO 14159 certification acceleration:Equipment vendors with pre-validated hygiene design documentation capture preference among multinational food manufacturers seeking faster facility commissioning.
Industry Challenges
- Electromechanical technician scarcity:Maintenance of hybrid pneumatic-electric filler systems requires cross-trained personnel rarely available in regional meat processing clusters.
- 3-A Sanitary Standards certification timelines:United States dairy and meat processors face six-to-nine-month validation periods for imported European equipment, delaying line activation.
- Legacy control system integration:Brownfield facilities running proprietary PLC architectures encounter protocol mismatches when retrofitting modern vacuum fillers with Ethernet-based diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Fillers Market |
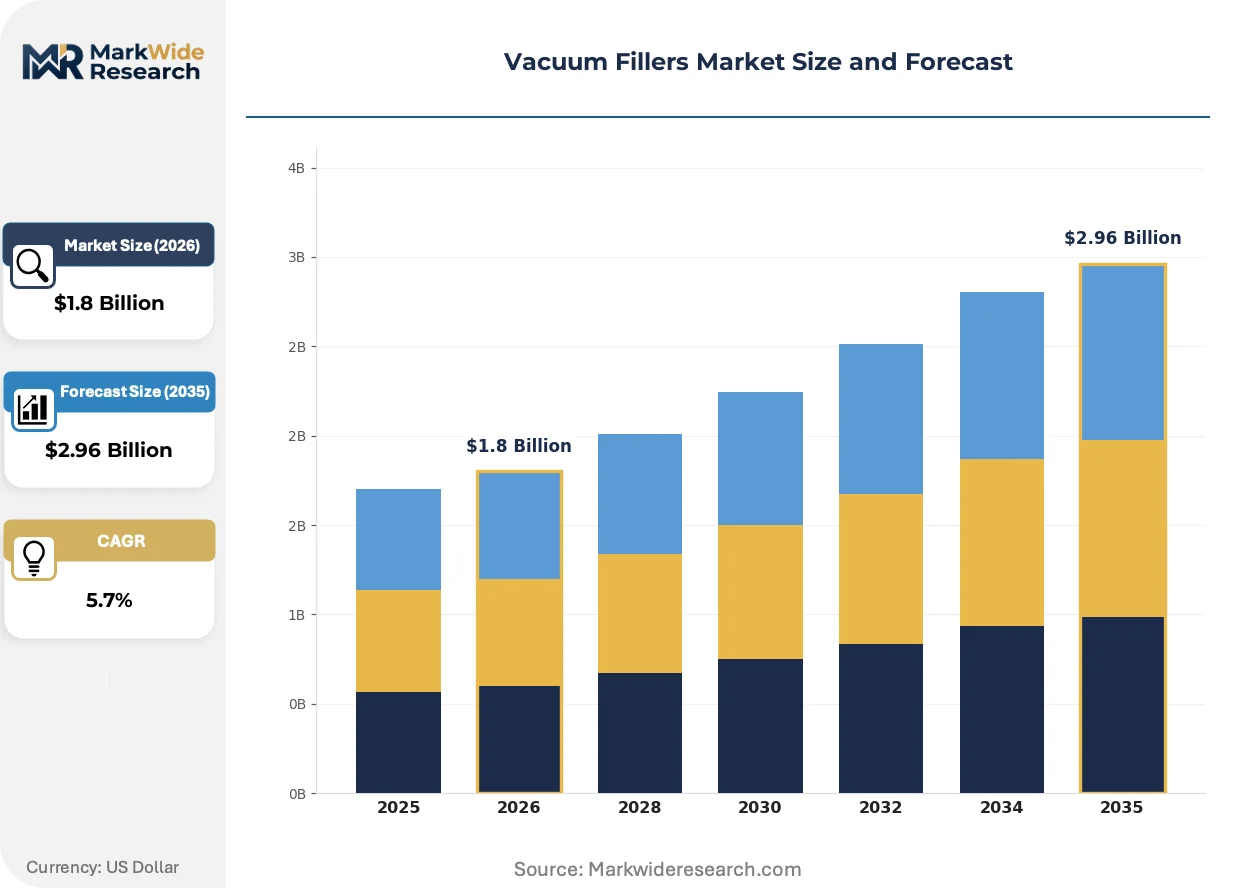
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Fillers, Semi-Automatic Fillers, Manual Fillers, Multi-Head Fillers End User: Food Processing, Pharmaceuticals, Cosmetics, Chemical Application: Liquid Filling, Paste Filling, Powder Filling, Granular Filling Technology: Pneumatic, Electric, Hydraulic, Mechanical |
| Companies Covered | Vemag Maschinenbau GmbH, Albert Handtmann Maschinenfabrik GmbH & Co. KG, RISCO S.p.A., Heinrich Frey Maschinenbau GmbH, Multivac Group, ULMA Packaging S. Coop., Henkelman B.V., Tenco S.r.l., GEA Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Fillers Market Evolving Landscape
Equipment architecture is bifurcating between washdown-optimized pneumatic systems for protein processing and precision electric platforms for pharmaceutical aseptic filling. This divergence is fragmenting vendor R&D priorities and reshaping aftermarket service models.
Servo-electric vacuum filling technology is expanding into pharmaceutical parenteral manufacturing where dosing precision of ±0.5% and elimination of compressed air contamination risk justify capital premiums. Biologic drug fill-finish contractors in Switzerland and Ireland are specifying these systems for high-value monoclonal antibody formulations. The technology is expanding into adjacent therapeutic categories previously served by peristaltic or piston pumps.
EU MDR and FDA food safety frameworks are mandating full digital traceability for food contact machinery materials and maintenance histories. Equipment vendors must now embed RFID tagging and cloud-connected sensor arrays to document stainless steel grade provenance and seal integrity. German meat processing lines are retrofitting legacy vacuum fillers with compliance modules to avoid production suspension during authority inspections.
Pharmaceutical procurement departments are unbundling vacuum filler acquisitions from long-term service contracts, compressing vendor revenue recognition and forcing equipment manufacturers to price maintenance separately. This pattern concentrates among biologic drug contractors in the United States and contract manufacturing organizations in Ireland. Aftermarket parts pricing transparency is becoming a competitive differentiator as buyers benchmark multi-year total cost of ownership.
Vacuum Fillers Market Segmentation
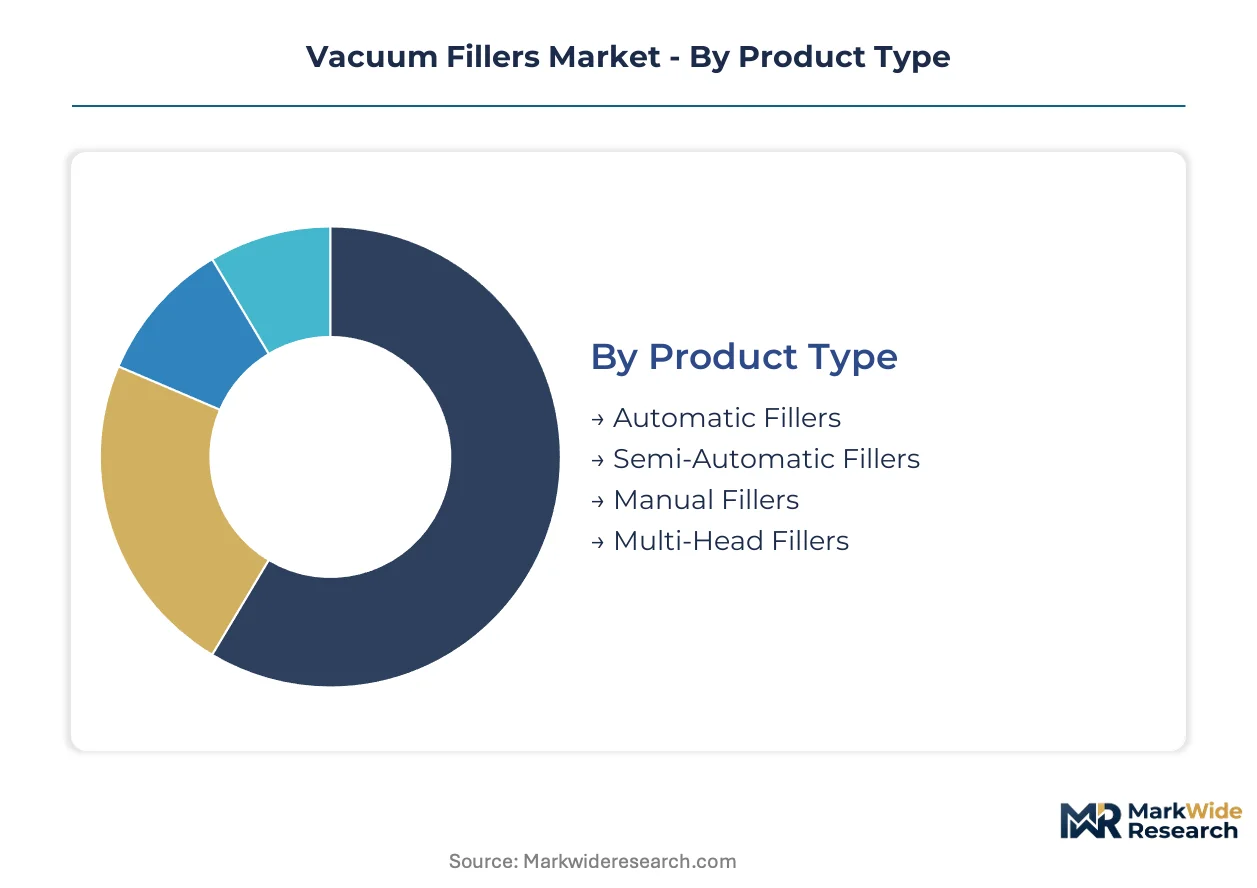
Vacuum filler segmentation reveals how certification burdens, throughput requirements, and material compatibility shape procurement decisions across protein processing, pharmaceutical manufacturing, and adjacent industries. Equipment specifications diverge sharply between washdown food environments and cleanroom drug production, with regulatory frameworks dictating viable technology choices in each vertical.
Product Type:
EU MDR hygiene mandates and FDA food safety frameworks impose distinct certification requirements across automation tiers, with automatic systems demanding full material traceability documentation and manual units facing lighter validation burdens.
- Automatic Fillers:Enclosed pumping architectures with integrated CIP systems evacuate chambers to 85-95 percent vacuum before depositing precise volumes at throughputs exceeding 10,000 units hourly. German meat processing plants and U.S. prepared meat facilities are consolidating procurement around these systems to satisfy escalating hygiene documentation requirements under EU MDR and FDA frameworks.
- Semi-Automatic Fillers:Hybrid configurations balance throughput with batch flexibility, typically employing pneumatic vacuum pumps with manual container positioning. Mid-tier pharmaceutical operations in Switzerland and Ireland specify these units for parenteral formulation filling where changeover speed outweighs line velocity.
- Manual Fillers:Operator-dependent systems with simple vacuum chambers suit small-batch cosmetic and specialty chemical production where capital constraints limit automation investment.
- Multi-Head Fillers:Parallel filling heads synchronized through central vacuum manifolds enable simultaneous container processing for high-volume liquid and paste applications.
Automatic Fillers sit at the top of the volume ranking, with Multi-Head Fillers climbing the fastest as protein processors seek labor reduction through parallel processing architectures.
End User:
Customer procurement patterns stratify across cost tiers, with pharmaceutical buyers absorbing premium pricing for aseptic certification and food processors prioritizing stainless steel durability under aggressive washdown protocols.
- Food Processing:Protein processors, dairy cooperatives, and prepared meal manufacturers deploy vacuum fillers for sausage stuffing, sauce depositing, and portion-controlled packaging. German and Italian meat facilities are retrofitting legacy lines with EU MDR-compliant automatic systems to avoid production suspension during authority inspections.
- Pharmaceuticals:Biologic drug fill-finish contractors in Switzerland and Ireland specify servo-electric vacuum fillers for monoclonal antibody and parenteral formulation filling where dosing precision of ±0.5 percent and elimination of compressed air contamination risk justify capital premiums.
- Cosmetics:Cream, lotion, and serum manufacturers employ vacuum filling to prevent oxidation of active ingredients and ensure consistent product density across batch runs.
- Chemical:Specialty chemical and agrochemical formulators utilize corrosion-resistant vacuum architectures for viscous and solvent-based product handling.
Food Processing commands the largest installed base, with Pharmaceuticals expanding most quickly as biologic manufacturing scales across European contract manufacturing organizations.
Application:
Material rheology determines vacuum filler geometry selection, with liquid and paste applications dominating current deployments while powder handling remains technically constrained.
- Liquid Filling:Thin to moderately viscous fluids including sauces, marinades, pharmaceutical solutions, and cosmetic serums flow readily through vacuum filler nozzles with minimal shear degradation. U.S. prepared meat lines integrate liquid filling with clipping systems to reduce labor exposure and contamination risk.
- Paste Filling:Thixotropic and shear-sensitive materials including ground meat emulsions, pharmaceutical ointments, and textured vegetable protein formulations require gentle handling to maintain structural integrity. Plant-based protein processors are driving specification changes to accommodate non-animal paste rheologies.
- Powder Filling:Cohesive and aerated powders present flow challenges that vacuum architectures struggle to address compared to auger or gravity systems, constraining penetration in nutritional supplement manufacturing.
- Granular Filling:Free-flowing particulates including spice blends, chemical granules, and agricultural inputs suit vacuum transfer when combined with vibratory feed assistance.
Liquid Filling maintains the highest deployment volume, with Paste Filling gaining share fastest as plant-based protein processing scales.
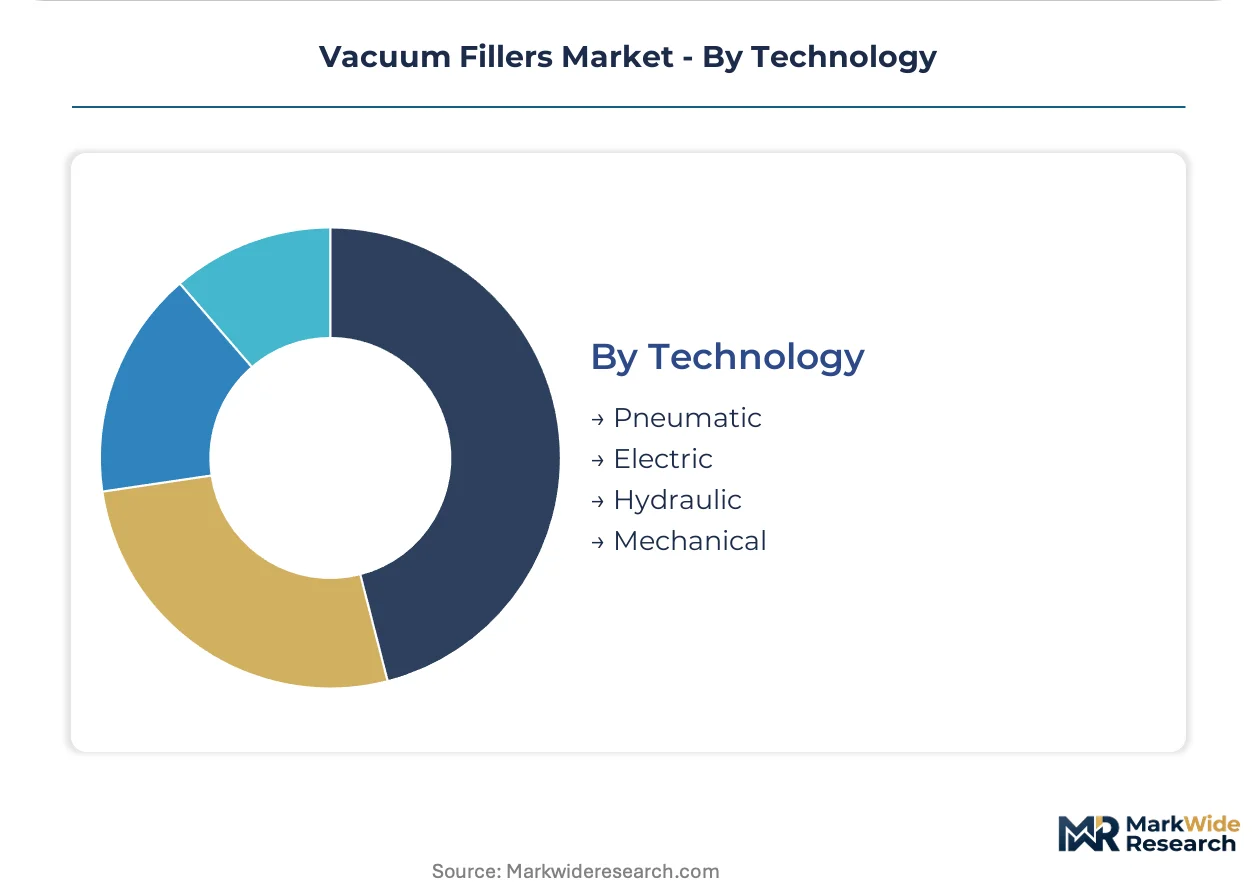
Technology:
Supply concentration among German and Japanese component suppliers shapes technology availability, with pneumatic systems benefiting from established maintenance networks and electric platforms requiring scarcer electromechanical expertise.
- Pneumatic:Compressed air-driven vacuum pumps and actuators dominate protein processing installations for reliability in aggressive washdown environments. German meat processing clusters maintain deep technician familiarity with pneumatic maintenance protocols.
- Electric:Servo-controlled drive systems deliver precise dosing control and energy efficiency for pharmaceutical cleanrooms where contamination risk reduction outweighs higher capital outlay. Swiss and Irish biologic manufacturers are specifying these platforms for aseptic filling operations.
- Hydraulic:High-force actuation systems suit heavy-viscosity materials and large-capacity filling applications where pneumatic force proves insufficient.
- Mechanical:Cam-driven and linkage-based architectures persist in cost-sensitive markets with limited automation infrastructure and maintenance capabilities.
Pneumatic technology retains the largest installed base, with Electric platforms climbing the fastest as pharmaceutical procurement prioritizes precision and energy efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vacuum filler procurement as manufacturers migrate capacity toward jurisdictions with clearer compliance cost structures. EU MDR documentation burdens and FDA validation timelines create divergent total-cost-of-ownership profiles across major processing economies.
Germany
Bavarian meat processing clusters are consolidating automatic vacuum filler deployments to satisfy EU MDR hygiene mandates requiring full stainless steel traceability. The Federal Institute for Risk Assessment enforces material certification protocols that elevate equipment replacement cycles. Munich-based protein processors are retrofitting legacy lines with CIP-compatible architectures to avoid production suspension during authority inspections.
United States
Prepared meat facilities in Wisconsin and Nebraska are integrating vacuum fillers with clipping systems to reduce labor exposure under FDA food safety modernization frameworks. USDA FSIS inspection protocols mandate enclosed filling architectures for high-volume sausage operations. Chicago-area equipment distributors report six-to-nine-month validation periods for imported European systems, delaying line activation.
Italy
Emilia-Romagna protein processors specify vacuum fillers with integrated portioning accuracy for traditional cured meat production under EFSA hygiene guidelines. The Ministry of Health enforces food contact machinery standards that favor domestic equipment fabricators. Parma-based processing cooperatives are expanding automatic filler capacity to serve export markets demanding full material documentation.
Switzerland
Basel-region biologic drug fill-finish contractors specify servo-electric vacuum fillers for monoclonal antibody production under Swissmedic aseptic manufacturing guidelines. The Therapeutic Products Act mandates contamination risk mitigation that justifies capital premiums for electric drive precision. Lucerne-area contract manufacturers are scaling parenteral formulation capacity to serve European pharmaceutical outsourcing demand.
China
Shandong meat processing clusters are adopting vacuum filler architectures to meet SAMR food safety supervision requirements for packaged protein products. GB standards for food machinery hygiene design constrain imported equipment qualification timelines. Qingdao-based processors are retrofitting lines with stainless steel filling systems to satisfy export market documentation requirements.
Vacuum Fillers Market Competitive Landscape
German producers anchor the premium tier with Bavarian and Baden-Württemberg fabrication clusters holding dominant positions in high-throughput protein processing equipment. Italian specialists occupy a distinct export-oriented niche serving European cured meat traditions. Market structure bifurcates between integrated packaging system vendors and standalone filling equipment fabricators. Competitive moves concentrate on hygiene design certification acceleration and pharmaceutical cleanroom qualification to capture biologic manufacturing expansion.
Within the German precision-engineering tier, Vemag Maschinenbau GmbH and Albert Handtmann Maschinenfabrik GmbH & Co. KG represent established fabrication archetypes with deep specialization in meat processing automation. RISCO S.p.A. exemplifies the Italian export-focused model serving protein facilities across Mediterranean and Central European markets. These three entities occupy positions that reflect geographic production concentration and end-use vertical alignment rather than scale-based hierarchy.
| Leading Market Players |
|---|
| Vemag Maschinenbau GmbH |
| Albert Handtmann Maschinenfabrik GmbH & Co. KG |
| RISCO S.p.A. |
| Heinrich Frey Maschinenbau GmbH |
| Multivac Group |
| ULMA Packaging S. Coop. |
| Henkelman B.V. |
| Tenco S.r.l. |
| GEA Group AG |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between EU MDR-validated stainless steel systems and non-certified alternatives manifests in both pricing premiums and supply chain sourcing patterns. Pharmaceutical buyers absorb 40-60 percent capital premiums for servo-electric platforms with Swissmedic documentation, while protein processors in Germany and Italy prioritize Grade 316L traceability over absolute cost minimization.
Pricing Analysis
Distributor margins compress pricing transparency across European and North American channels, with Bavarian fabricators commanding 15-25 point premiums through direct OEM relationships. Three-tier pricing structure across premium servo-electric, standard pneumatic, and economy mechanical tiers reflects certification burden and automation intensity. Pricing pressure stems from stainless steel input volatility and extended quoting timelines for large-capacity systems. Mid-tier pharmaceutical operations in Switzerland exhibit lowest price sensitivity due to monoclonal antibody formulation value, while Chinese meat processors in Shandong prioritize capital efficiency.
Supply Chain Analysis
Workforce scarcity for electromechanical technicians in Bavarian and Baden-Württemberg fabrication clusters constrains capacity expansion for hybrid pneumatic-electric systems. German and Japanese suppliers concentrate high-vacuum pump and servo motor production, exposing non-integrated builders to lead time risk. Component dependencies center on Grade 316L stainless steel, precision vacuum seals, and servo drive controllers. Single-source vulnerability in Japanese servo motor supply creates bottleneck exposure. Distribution runs through regional equipment distributors in Chicago and Munich, with direct OEM contracting gaining share among multinational food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vacuum fillers market functions as a regulatory compounder where EU MDR documentation burdens and FDA validation timelines accelerate equipment replacement cycles. These compliance milestones create structural demand for certified stainless steel architectures with full material traceability.
For Market Incumbents: Deepen backward integration into Grade 316L stainless steel sourcing to defend margin position against raw material volatility. Prioritize pre-validated ISO 14159 hygiene design documentation to capture preference among multinational food manufacturers seeking faster facility commissioning. Invest in electromechanical technician training programs to address workforce scarcity constraining hybrid system maintenance capacity. For New Entrants and Emerging Players: Capture plant-based protein processing white space where modified vacuum filler geometries for textured vegetable protein and mycoprotein remain underspecified by incumbent vendors. Target Swiss and Irish biologic drug fill-finish contractors with servo-electric platforms priced below German premium tiers. Lead with aftermarket parts pricing transparency as competitive differentiator against bundled service contract incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where electromechanical technician scarcity and certification documentation burdens favor scaled vendors with established compliance portfolios. Long-term viability centers on hybrid technology capabilities spanning washdown protein processing and cleanroom pharmaceutical applications. Acquisition target archetype: mid-cap Italian or German specialists with EU MDR pre-validation and export positioning across European protein facilities. Signal to watch: biologic manufacturing capacity announcements in Switzerland and Ireland indicating servo-electric demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Pre-Validation Investment | Accelerates facility commissioning for German meat processors facing authority inspection risk. |
| Servo-Electric Platform Development | Captures Swiss biologic manufacturers requiring ±0.5% dosing precision for monoclonal antibodies. |
| Backward Integration into Stainless Steel | Insulates Bavarian fabricators from Grade 316L price volatility extending quoting timelines. |
| Electromechanical Technician Training Programs | Addresses workforce scarcity constraining hybrid pneumatic-electric system maintenance capacity. |
| Plant-Based Protein Geometry Modification | Enables textured vegetable protein handling without structural degradation for emerging processors. |
Research Methodology
Multiple input streams — equipment procurement directors at protein processing facilities, pharmaceutical fill-finish contractors, regulatory affairs specialists, and aftermarket service heads — were reconciled with customs data, SEC filings from packaging system vendors, EU MDR documentation databases, and food machinery trade association reports. Bottom-up installation base estimates were triangulated against top-down market sizing derived from stainless steel consumption patterns and capital expenditure disclosures.
Cross-referencing historical replacement cycle data with expert panel input on regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include automation tier, end-use vertical, material application, and drive technology architecture. CAGRs were derived from weighted capacity expansion announcements and documented equipment lifecycles. Industry-specific inputs encompassed EU MDR implementation pace and FDA food safety modernization enforcement intensity.
Stainless steel price volatility, regulatory inspection frequency escalation, and electromechanical technician availability are the dominant revision risks to installed base and replacement cycle assumptions. Forecasts reflect documented compliance burden trajectories and capital allocation patterns across protein processing and pharmaceutical manufacturing. Material deviation in named triggers warrants pause and re-evaluation of equipment demand velocity and vendor margin sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Skin Packaging Equipment Market