
 Nano Tapes Market | 2026-2036
Nano Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Tapes Market Outlook
Acrylic copolymer chemistry is narrowing the performance gap between solvent-based and waterborne nano tape formulations, enabling thinner bond lines without sacrificing peel strength. 3M leverages its polymer science archive to sustain formulation leadership across high-temperature automotive applications. Nitto Denko Corporation anchors East Asian supply through captive resin synthesis and roll-to-roll coating scale. Tesa SE competes in European industrial channels with certified cleanroom-compatible product lines.
Nano tapes are pressure-sensitive adhesive constructions with thickness below 50 micrometers, engineered from acrylic, silicone, or rubber-based polymers coated onto release liners for precision bonding in constrained geometries. They serve primarily to replace mechanical fasteners, liquid adhesives, and welding in assemblies where thermal cycling, vibration resistance, or electrical conductivity is required. Double-sided configurations command the deepest margin pools in electronics lamination, while conductive grades are capturing the fastest expansion as foldable displays and 5G antenna modules proliferate. Polymer substrates dominate volume, though adhesive formulation differentiation—not base film selection—determines supplier profitability in medical and semiconductor end uses.
The EPA governs volatile organic compound emissions from adhesive manufacturing in the United States, pushing converters toward waterborne and UV-curable process technologies. REACH and RoHS frameworks in the European Union restrict phthalate plasticizers and heavy metal stabilizers in tape chemistries, reshaping raw material qualification protocols for exporters. Stakeholders must monitor how China's GB standards evolution and dual carbon goals affect domestic acrylic monomer availability and coating energy intensity.
Market Dynamics
East Asian electronics manufacturers are compressing bond-line tolerances below 20 micrometers for foldable display lamination, forcing adhesive suppliers to reformulate acrylic copolymers without sacrificing thermal cycling resistance.
Growth Catalysts
- 5G antenna module proliferation:Telecommunications equipment manufacturers in South Korea are specifying conductive nano tapes for electromagnetic interference shielding in compact base station assemblies.
- REACH compliance deadlines:ECHA restrictions on phthalate plasticizers are accelerating qualification of bio-based acrylic monomers across European medical device supply chains.
- Dual carbon goals:China's MEE enforcement of coating energy intensity limits is driving waterborne process adoption in domestic tape converting facilities.
Market Restraints
- Captive resin synthesis concentration:Polymer feedstock supply concentrates among Japanese and South Korean chemical conglomerates, creating qualification bottlenecks for secondary converters.
- UV-curable equipment capex:Transitioning from solvent-based coating lines requires vacuum deposition chambers and electron beam curing systems beyond mid-tier processor balance sheets.
- Silicone adhesive substitution:High-temperature automotive gasketing applications are migrating toward liquid silicone injection molding for assemblies exceeding 150°C continuous exposure.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme subsidies for semiconductor packaging and display fabrication are creating first-mover qualification windows for cleanroom-compatible tape suppliers.
- Biocompatible wearable adhesion:Skin-contact glucose monitoring patches require hypoallergenic silicone nano tapes with 7-day wear certification not yet commoditized by incumbent players.
- Automotive battery thermal interface materials:Cell-to-pack architectures are specifying double-sided conductive tapes for heat dissipation in electric vehicle module assembly.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 Class 7 validation for medical-grade tape slitting operations extends 18-24 months, delaying revenue recognition for new production lines.
- Acrylic monomer IP thickets:Cross-linked copolymer patents held by diversified chemical majors create licensing complexity for independent formulation houses entering semiconductor packaging.
- Roll-to-roll coating talent scarcity:Thin-film precision coating engineers with sub-micron thickness control experience command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Tapes Market |
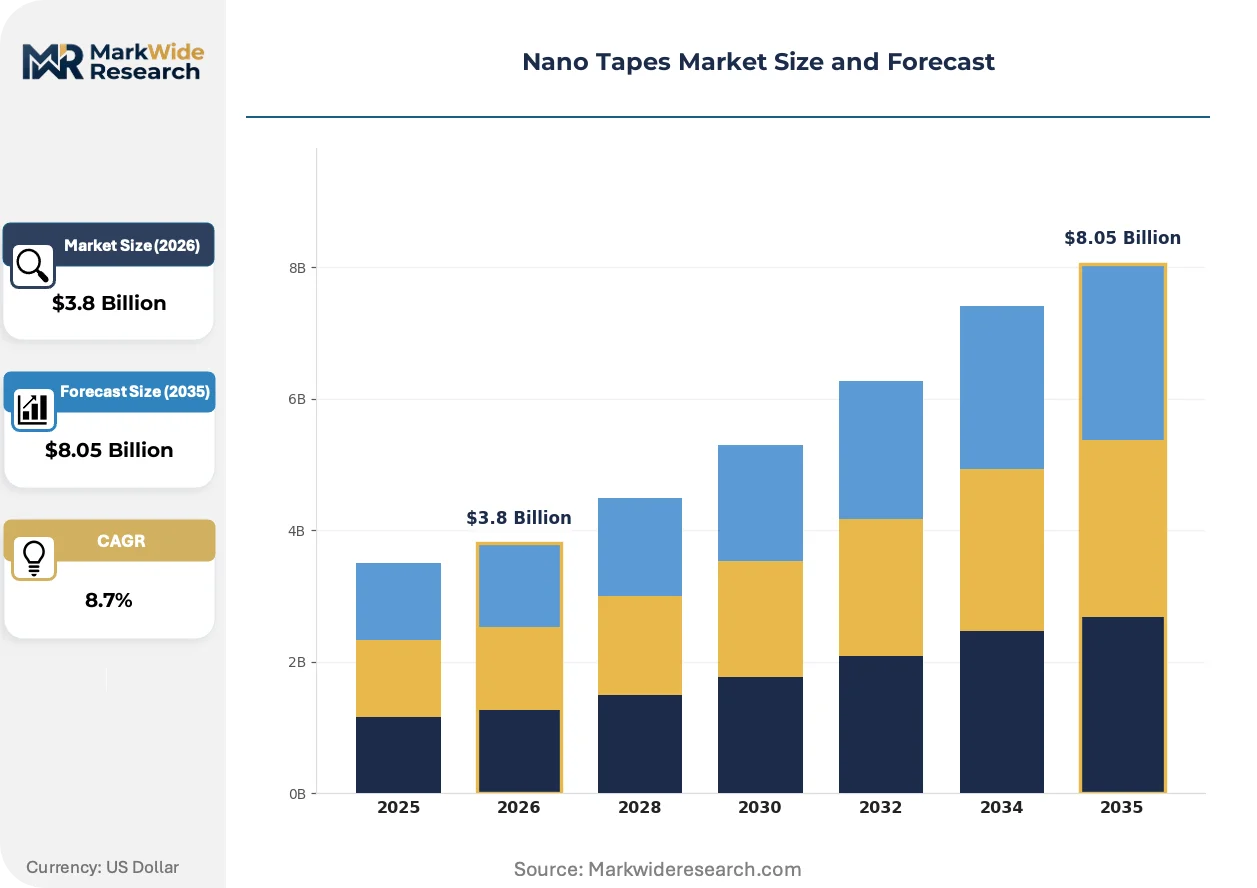
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Single-Sided, Conductive, Non-Conductive Application: Automotive, Electronics, Construction, Healthcare Material: Polymer, Adhesive, Fabric, Foam End User: Manufacturers, DIY Consumers, Retailers, Industrial Users |
| Companies Covered | 3M, Nitto Denko Corporation, Tesa SE, Lohmann GmbH & Co. KG, Scapa Group plc, Avery Dennison Corporation, Sekisui Chemical Co., Ltd., LINTEC Corporation, Guangzhou New Vision New Material Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Tapes Market Strategic Shifts
Active chemistry development and manufacturing process intensification are compressing development cycles for next-generation adhesive architectures. Three convergent developments are restructuring supplier capabilities and buyer procurement criteria.
Self-assembling monolayer surface treatments are rendering obsolete plasma activation pre-treatments for low-surface-energy substrates. Automotive interior tier suppliers in Germany are adopting these chemistries for direct bonding to recycled polypropylene panels. The elimination of pretreatment equipment is compressing line footprints and reducing volatile organic compound exposure in assembly plants.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening volatile organic compound limits for adhesive coating operations. Converters in the United States are retrofitting solvent recovery systems or migrating to UV-curable acrylic platforms. Medical device laminators face the steepest compliance costs due to cleanroom air handling requirements that compound emission control investments.
Consolidated specification-setting by South Korean display panel manufacturers is narrowing qualified supplier lists to three or fewer tape converters per substrate category. Procurement teams at Samsung Display and LG Display are requiring captive resin traceability and quarterly reliability testing. This concentration is visible in Gyeonggi Province, where packaging engineers now specify supplier facilities by individual coating line certification rather than corporate quality systems.
Nano Tapes Market Segmentation
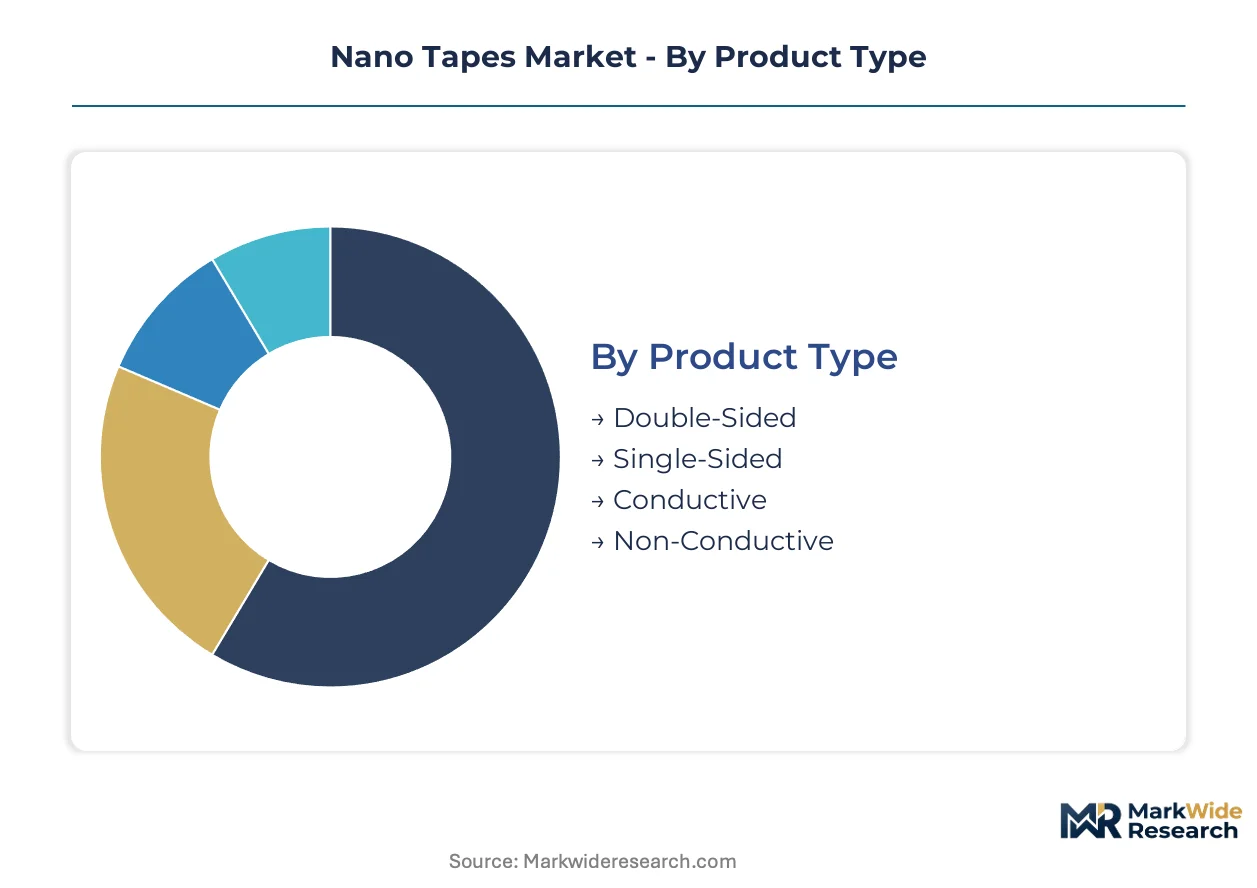
Segmentation in nano tapes reveals how formulation chemistry and bonding architecture determine margin capture. Suppliers align R&D portfolios against specific stress regimes—thermal cycling, electrical conductivity, or biocompatibility—that dominate each end-use environment.
Product Type:
After-sales service intensity varies sharply across product architectures, with conductive grades requiring technical field support for impedance matching and failure analysis that commodity tapes never trigger.
- Double-Sided:Pressure-sensitive adhesive layers on both faces of a carrier film enable substrate-to-substrate lamination without mechanical fasteners. Samsung Display and LG Display procurement teams in Gyeonggi Province specify these for foldable OLED panel bonding where 20-micron bond lines must survive 200,000 fold cycles.
- Conductive:Silver-filled or carbon-nanotube-doped acrylic matrices provide electromagnetic interference shielding and electrical grounding paths. South Korean telecommunications equipment manufacturers specify these for 5G base station antenna modules where compact geometries prohibit separate grounding hardware.
- Single-Sided:One active adhesive face suits surface protection and temporary masking applications with minimal technical support requirements.
- Non-Conductive:Dielectric formulations isolate electrical potentials in battery pack assemblies and display driver boards.
Double-sided configurations hold the largest share; momentum sits with conductive grades as foldable display and 5G antenna volumes climb.
Application:
Application-driven cost tiers separate specification-grade automotive and electronics demand from price-sensitive construction and healthcare segments.
- Electronics:Miniaturized device assembly demands sub-50-micron thickness with thermal cycling resistance across -40°C to 150°C. East Asian semiconductor packaging clusters in South Korea and China's display manufacturing corridor concentrate procurement of acrylic copolymer formulations certified for cleanroom handling.
- Automotive:Battery thermal interface materials and interior panel bonding require flame-retardant additives meeting OEM material data sheet specifications. German automotive interior tier suppliers adopt self-assembling monolayer surface treatments for direct bonding to recycled polypropylene panels.
- Construction:Weather sealing and vapor barrier applications prioritize UV stability and moisture resistance over precision thickness control.
- Healthcare:Skin-contact wearable adhesion for glucose monitoring patches requires hypoallergenic silicone chemistries with multi-day wear certification.
Electronics commands premium pricing; automotive represents the steepest expansion trajectory as electric vehicle production scales.
Material:
Volume concentration in polymer substrates masks where supplier profitability actually resides—adhesive formulation differentiation, not base film selection, determines margins in medical and semiconductor end uses.
- Adhesive:Acrylic, silicone, and rubber-based polymer chemistries constitute the functional layer determining peel strength, temperature resistance, and electrical properties. REACH compliance deadlines for phthalate plasticizers are accelerating bio-based acrylic monomer qualification across European medical device supply chains.
- Polymer:Polyester, polyimide, and polyethylene terephthalate films provide dimensional stability as carrier substrates. China's MEE enforcement of coating energy intensity limits is driving waterborne process adoption in domestic tape converting facilities using these substrates.
- Fabric:Woven or non-woven textile backings reinforce mechanical strength in heavy-duty industrial bonding.
- Foam:Cellular polymer structures provide conformability and gap-filling in uneven substrate assemblies.
Adhesive formulations generate the highest margins; polymer substrates move the greatest tonnage.
End User:
Customer type dictates sales channel configuration and technical support depth, with industrial users requiring application engineering that DIY consumers never access.
- Manufacturers:Electronics and automotive OEMs specify certified tape constructions with captive resin traceability and quarterly reliability testing. South Korean display panel manufacturers now qualify supplier facilities by individual coating line certification rather than corporate quality systems.
- Industrial Users:Maintenance, repair, and operations procurement in manufacturing plants demands consistent availability and technical documentation for audit compliance.
- Retailers:Distributors and big-box channels stock standardized SKUs with minimal technical differentiation.
- DIY Consumers:Home improvement and craft applications drive volume through hardware and e-commerce channels with no application support.
Manufacturers dominate value capture; industrial users show the fastest volume growth as maintenance operations standardize on pressure-sensitive alternatives to mechanical fasteners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturers concentrate procurement in three distinct buyer archetypes: South Korean display panel producers, Chinese semiconductor packagers, and German automotive interior tiers. Each cluster demands different certification protocols and bond-line specifications.
South Korea
Samsung Display and LG Display procurement teams specify 20-micron bond lines for foldable OLED lamination requiring 200,000-fold cycle survival. MFDS oversees biocompatibility standards for medical-grade adhesive applications. Gyeonggi Province hosts the deepest concentration, where engineers now qualify supplier facilities by individual coating line certification rather than corporate quality systems.
China
Display manufacturing corridors in the Yangtze River Delta and Pearl River Delta compress procurement timelines for miniaturized device assembly. MEE enforces coating energy intensity limits that push domestic converters toward waterborne process adoption. Shenzhen and Suzhou clusters concentrate the highest volume of captive resin synthesis operations serving regional electronics supply chains.
Germany
Automotive interior tier suppliers adopt self-assembling monolayer surface treatments for direct bonding to recycled polypropylene panels. REACH restrictions on phthalate plasticizers accelerate bio-based acrylic monomer qualification across medical device supply chains. Baden-Württemberg hosts the densest concentration of cleanroom-compatible tape slitting operations serving European industrial channels.
United States
Telecommunications equipment manufacturers specify conductive nano tapes for 5G base station antenna modules where compact geometries prohibit separate grounding hardware. EPA National Emission Standards for Hazardous Air Pollutants tighten volatile organic compound limits for adhesive coating operations. Michigan and Ohio automotive clusters drive qualification of flame-retardant formulations for battery thermal interface materials in electric vehicle module assembly.
Japan
Semiconductor packaging facilities procure acrylic copolymer formulations certified for cleanroom handling in advanced node device assembly. METI coordinates standards alignment for adhesive chemistry specifications across electronics supply chains. Kyushu and Chubu regions concentrate the highest density of roll-to-roll coating operations with sub-micron thickness control capabilities.
Nano Tapes Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct margin tiers. The market structure consolidates around diversified chemical conglomerates with captive resin synthesis capabilities, while independent formulation houses occupy narrower technical niches. Three archetypes dominate: vertically integrated polymer science leaders, precision coating specialists with roll-to-roll scale, and regional converters serving price-sensitive industrial channels. Competitive moves concentrate on strategic partnerships for resin supply security and geographic expansion into Indian electronics manufacturing zones.
Within the diversified chemical conglomerate tier, 3M and Nitto Denko Corporation exemplify players with backward integration into polymer feedstock production. Tesa SE occupies a position among European precision coating specialists with certified cleanroom-compatible product lines. These three anchors demonstrate how formulation differentiation—not base film selection—determines supplier profitability in medical and semiconductor end uses.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| Tesa SE |
| Lohmann GmbH & Co. KG |
| Scapa Group plc |
| Avery Dennison Corporation |
| Sekisui Chemical Co., Ltd. |
| LINTEC Corporation |
| Guangzhou New Vision New Material Technology |
| Others |
Value Chain & Pricing Dynamics
Captive resin synthesis operations in Japan and South Korea concentrate polymer feedstock supply among a handful of chemical conglomerates, positioning downstream tape converters in a cost-pass-through dynamic where formulation differentiation—not base film selection—determines margin capture in medical and semiconductor end uses.
Pricing Analysis
Cost-plus contracts with acrylic monomer indexation dominate procurement between Japanese chemical conglomerates and East Asian tape converters. Three-tier pricing structure across premium, standard, and economy levels separates cleanroom-certified semiconductor grades from industrial maintenance SKUs. Cost compression in standard-grade electronics lamination is intensifying as Chinese display manufacturers consolidate qualified supplier lists. DIY consumers and construction distributors exhibit the highest price sensitivity, while South Korean display panel procurement teams prioritize coating line certification over unit cost.
Supply Chain Analysis
Acrylic monomer and silicone polymer feedstock draws from petrochemical complexes concentrated in Japan, South Korea, and eastern China. Specialty release liners and precision-coated polymer films hinge on roll-to-roll coating equipment with sub-micron thickness control capabilities concentrated in Kyushu and Chubu regions. Single-source vulnerability persists for silver-filled conductive formulations used in 5G antenna modules. Distribution runs through direct OEM specification channels for electronics and automotive tiers, with industrial distributors serving maintenance and repair operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as foldable display penetration and 5G infrastructure buildout create qualification windows before incumbent supply contracts solidify.
For Market Incumbents: Entrench formulation leadership by securing captive resin supply agreements with South Korean and Japanese chemical conglomerates before secondary converters achieve qualification. Invest in ISO 14644 Class 7 cleanroom certification for individual coating lines to meet Samsung Display and LG Display procurement protocols. Defend against silicone adhesive substitution in high-temperature automotive gasketing by advancing acrylic copolymer thermal cycling performance above 150°C continuous exposure. For New Entrants and Emerging Players: Establish a beachhead in Indian electronics manufacturing zones where PLI scheme subsidies for semiconductor packaging and display fabrication create first-mover qualification windows absent entrenched supplier relationships. Target biocompatible wearable adhesion for glucose monitoring patches requiring hypoallergenic silicone chemistries with 7-day wear certification not yet commoditized by incumbent players. Lead with technical field support capabilities for impedance matching in conductive grades to differentiate from commodity tape distributors. For Investors and Strategic Acquirers: Capital is best deployed toward precision coating specialists with roll-to-roll scale and existing cleanroom infrastructure rather than independent formulation houses lacking captive resin supply. Long-term viability centers on backward integration into polymer feedstock production or exclusive supply agreements with Japanese and South Korean chemical conglomerates. Watch for consolidation signals when South Korean display manufacturers reduce qualified supplier lists below three per substrate category.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Secures feedstock access against Japanese and South Korean chemical conglomerate concentration. |
| Cleanroom Certification Investment | Enables qualification for Samsung Display and LG Display procurement in Gyeonggi Province. |
| Waterborne Process Migration | Aligns with China's MEE enforcement of coating energy intensity limits and REACH compliance deadlines. |
| Biocompatible Formulation Development | Captures glucose monitoring patch demand requiring hypoallergenic silicone 7-day wear certification. |
| Indian Manufacturing Footprint Expansion | Positions for PLI scheme subsidies in semiconductor packaging and display fabrication corridors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating line engineers, procurement leads at South Korean display panel manufacturers, regulatory affairs specialists navigating REACH and RoHS frameworks, and technical directors at acrylic monomer suppliers. Secondary validation drew from EPA National Emission Standards for Hazardous Air Pollutants filings, ECHA restriction proposals on phthalate plasticizers, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data on adhesive-coated film imports. Bottom-up volume modeling and top-down value triangulation were cross-referenced against reported segment revenues.
Calibration against historical capacity utilization rates and announced coating line expansions anchored the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, adhesive chemistry, end-use stress regime, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating foldable display volume forecasts and 5G base station deployment trajectories. Conductive grade penetration rates and waterborne process adoption curves served as industry-specific forecast inputs.
Sensitivities concentrate around Chinese dual carbon goal enforcement affecting coating energy intensity limits, South Korean display manufacturer supplier consolidation timelines, and acrylic monomer price volatility tied to petrochemical feedstock markets. Cross-checking against ECHA regulatory proposal timelines and announced cleanroom certification completions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Plastic Adhesive Tapes Market
Tapes
Breathable Tape Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
ESD Tapes and Labels Market
Tapes
Tape Dispenser Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Acoustic Tape Market
Tapes
Application Tapes Market
Tapes
Tape and Label Adhesives Market
Tapes
Strapping Supplies Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Edge Band Tapes Market
Tapes
Dicing Tapes Market
Tapes
Aluminum Foil Tape Market