
 Freezer Tape Market | 2026-2036
Freezer Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Freezer Tape Market Foresight
Low-temperature acrylic adhesion grade is unwinding legacy rubber-based formulations across cold-chain logistics. 3M leverages proprietary acrylic polymer chemistry to sustain premium positioning in pharmaceutical track-and-trace applications. Jiangyin Danuo Adhesive Products Co., Ltd. anchors cost-competitive supply for Asia-Pacific food exporters. MBK Tape Solutions specializes in custom die-cut configurations for clinical trial specimen management.
Freezer tape is a pressure-sensitive adhesive tape engineered with sub-zero tack retention, typically formulated with acrylic or silicone polymers on polyethylene or aluminum foil backings, designed to maintain label integrity and seal strength at temperatures reaching minus eighty degrees Celsius. The product serves critical identification, sealing, and traceability functions in temperature-controlled supply chains where standard adhesives embrittle and fail. Acrylic tape leads material selection for pharmaceutical logistics due to its balanced cold-flow resistance and repositionability, while aluminum foil laminates command margin pools in cryogenic chemical processing where thermal conductivity management matters. Silicone adhesive variants represent the fastest-growing product category as ultra-cold biologics distribution, including cell and gene therapies, proliferates beyond traditional cold-chain parameters.
FDA cold-chain documentation requirements shape adhesive performance benchmarks and validation protocols for domestic pharmaceutical distribution. EPA regulations on volatile organic compound emissions influence solvent-based adhesive manufacturing processes and facility compliance investments. ISO 9001 quality management and IEC temperature-testing standards govern international market access and customer qualification procedures. Stakeholders must monitor evolving biologics temperature profiles and adhesive qualification timelines to align R&D roadmaps with next-generation cold-chain specifications.
Market Dynamics
Ultra-cold biologics distribution is compressing adhesive qualification timelines and forcing tape manufacturers to accelerate silicone polymer R&D cycles ahead of traditional pharmaceutical validation schedules.
Growth Catalysts
- Cell and gene therapy expansion:Cryogenic storage requirements for CAR-T treatments and mRNA vaccines are multiplying freezer tape touchpoints across clinical and commercial supply chains.
- FDA cold-chain documentation rules:Updated traceability mandates are tightening adhesive performance benchmarks and expanding validation testing volumes for domestic pharmaceutical distributors.
- Aluminum foil laminate demand:Cryogenic chemical processing applications requiring thermal conductivity management are pulling premium-backed tape configurations into industrial freezer operations.
Market Restraints
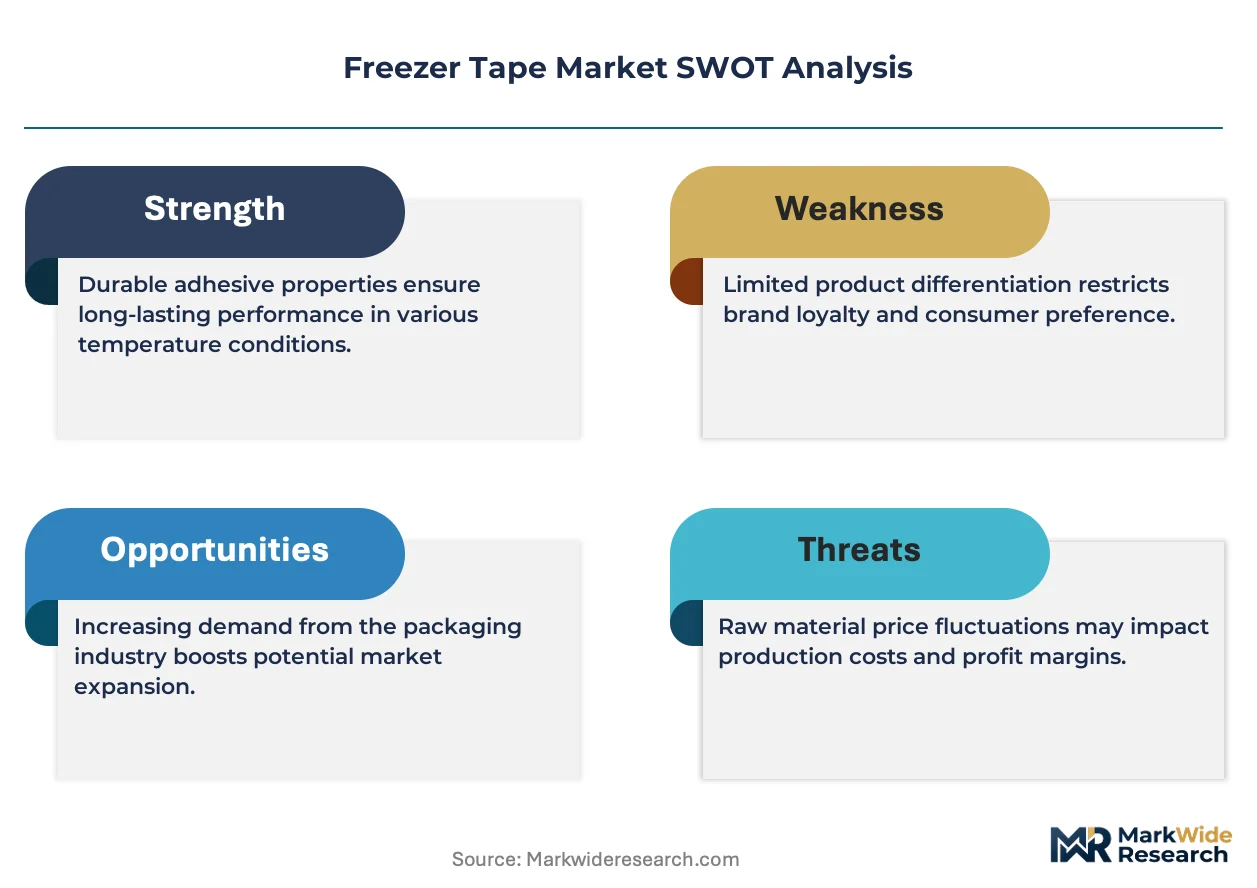
- Acrylic monomer cost volatility:Petrochemical feedstock fluctuations are compressing margins for mid-tier tape converters dependent on spot-market resin purchasing.
- Asia-Pacific supply concentration:Cost-competitive substrate manufacturing clusters in eastern China create geographic vulnerability for North American and European tape assemblers.
- Silicone adhesive cure limitations:Extended production cycle times for ultra-cold grades constrain output scalability relative to commodity acrylic formulations.
Strategic Opportunities
- India biologics manufacturing:CDSCO cold-chain infrastructure investments and export-oriented pharmaceutical parks are opening specification-setting opportunities for validated tape suppliers.
- Radio-frequency identification integration:Converging pressure-sensitive adhesive and NFC inlay technologies enables temperature-logging smart labels for high-value specimen tracking.
- Direct-to-clinic distribution:Hospital and research laboratory procurement platforms are shortening channel structures and creating technical sales relationships bypassing traditional industrial distributors.
Industry Challenges
- Adhesive formulator talent scarcity:Deep expertise in sub-zero polymer rheology resides with a narrow cohort of specialized chemists, constraining product development bandwidth across mid-sized manufacturers.
- Multi-jurisdiction certification timelines:Sequential FDA, EMA, and PMDA validation protocols extend market entry cycles for novel silicone adhesive platforms targeting global biologics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezer Tape Market |
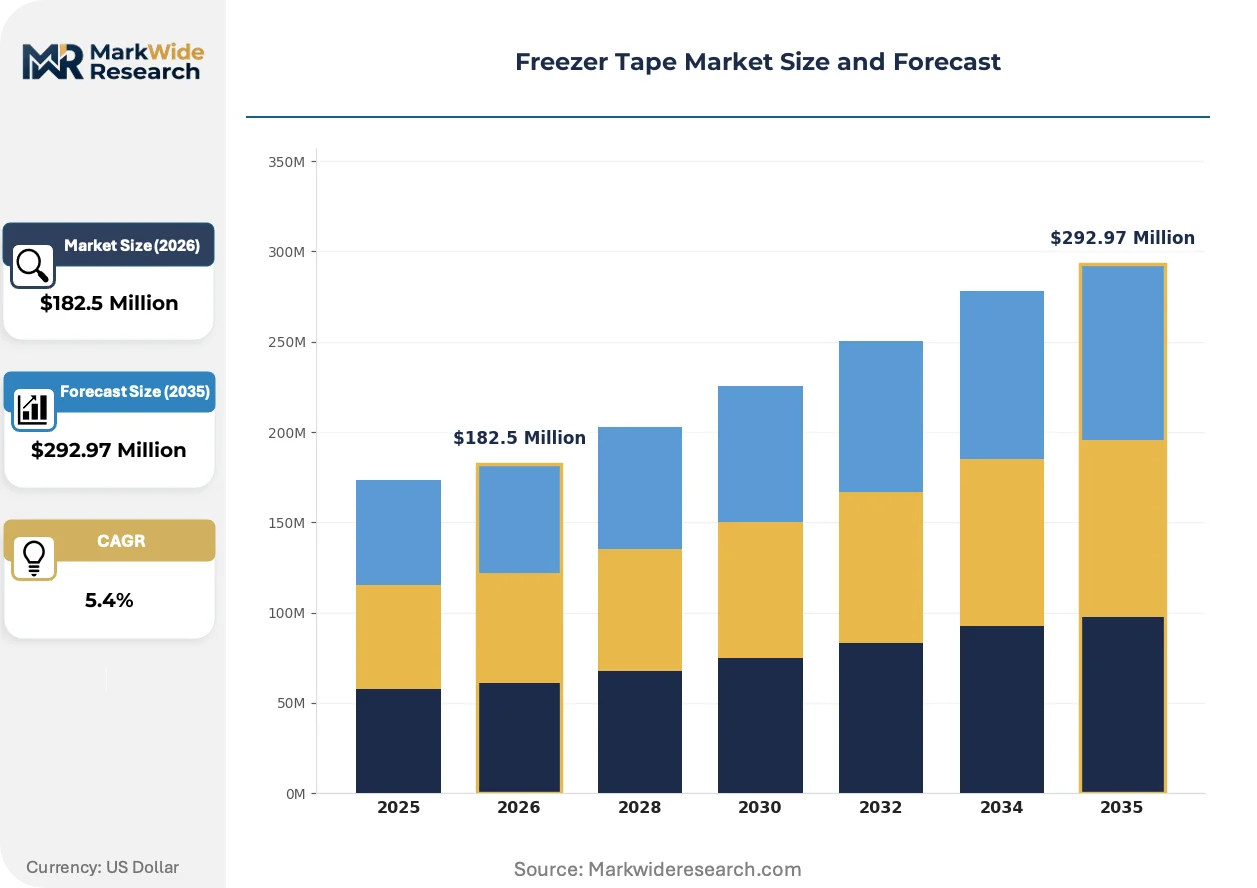
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $292.97 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Tape, Rubber Adhesive Tape, Silicone Tape, Hot Melt Tape Material: Polyethylene, Polypropylene, PVC, Aluminum Foil, Paper Application: Cold Storage, Food Packaging, Pharmaceutical Logistics, Chemical Processing End User Industry: Logistics Providers, Food Suppliers, Pharma Companies, Chemical Manufacturers |
| Companies Covered | 3M, Jiangyin Danuo Adhesive Products Co., Ltd., Jiangyin Haoxuan Aluminum Foil Adhesive Products Co., Ltd., Jiangsu Shixin Adhesive Tape Products Co. Ltd., JIANGYIN MEIYUAN INDUSTRIES, Jiangxi Ming Yang Glass Fiber Co., Ltd., Zhejiang Maxwel Insulation Technology Co., Ltd., MBK Tape Solutions, Can-Do National Tape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezer Tape Market Shifts & Advancements
Material science advances and regulatory documentation digitization are converging to redefine performance benchmarks across temperature-controlled supply chains, with adhesive functionality extending beyond passive sealing into active traceability.
Silicone pressure-sensitive adhesive formulations engineered for minus eighty degrees Celsius tack retention are displacing legacy rubber-based tapes in cell therapy logistics. Gene therapy developers and specialized couriers are adopting these grades for cryogenic liquid nitrogen shipment validation. The displacement is compressing market share for commodity rubber adhesives previously dominant in minus twenty degrees Celsius pharmaceutical distribution.
EMA's updated Good Distribution Practice guidelines for medicinal products are mandating tamper-evident sealing documentation across European Union member states. Pharmaceutical logistics operators must now maintain adhesive performance records spanning temperature excursion events. Cold-chain service providers in Germany, France, and the Netherlands are retrofitting quality management systems to capture tape batch-level traceability data.
Consolidated buying by integrated biologics manufacturers is compressing supplier rosters and elevating technical service expectations over transactional purchasing. Large pharmaceutical distributors are unbundling tape procurement from general packaging supply agreements and establishing direct relationships with adhesive specialists. This concentration is most visible in United States distribution networks where specialty pharmacy and third-party logistics integration has advanced furthest.
Freezer Tape Market Segmentation
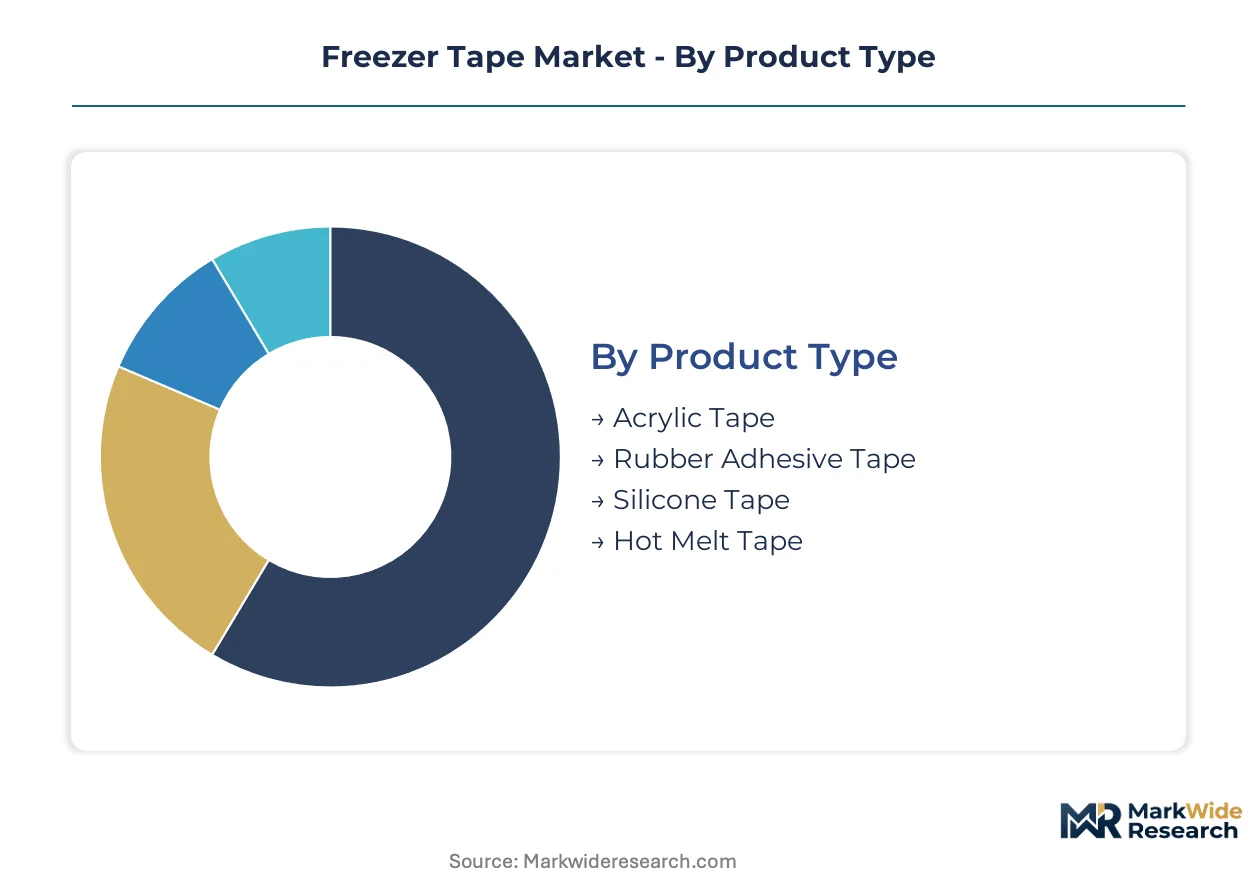
Freezer tape segmentation reflects divergent performance requirements across temperature thresholds and regulatory exposure. Material chemistry and backing substrate choices determine qualification timelines and margin capture in pharmaceutical versus industrial applications.
Product Type:
Silicone formulations face the most acute substitution pressure as acrylic polymers close the performance gap at minus forty degrees Celsius while undercutting cure-cycle economics.
- Acrylic Tape:Formulated with low-temperature acrylic polymers on polyethylene backings, this grade balances cold-flow resistance with repositionability during label application. Pharmaceutical logistics operators in the United States specify acrylic tapes for minus twenty to minus forty degrees Celsius distribution where FDA validation documentation is required.
- Silicone Tape:Pressure-sensitive silicone adhesives engineered for minus eighty degrees Celsius tack retention serve cryogenic liquid nitrogen shipments for cell and gene therapies. Ultra-cold biologics distributors accept extended lead times and premium pricing to secure validated silicone grades for CAR-T treatment logistics.
- Rubber Adhesive Tape:Legacy natural and synthetic rubber formulations dominate commodity cold storage at higher temperature bands.
- Hot Melt Tape:EVA and polyolefin-based hot melt adhesives offer cost positioning for short-duration freezer applications with minimal thermal cycling.
Acrylic tape retains volume leadership; silicone tape holds the steepest expansion curve.
Material:
Backing material selection tracks end-use thermal conductivity requirements and chemical resistance profiles across food, pharmaceutical, and industrial chemical segments.
- Polyethylene:Low-density and linear low-density polyethylene films provide moisture barrier properties and flexibility at cryogenic temperatures. Cold-chain logistics providers specify PE-backed tapes for pharmaceutical secondary packaging where puncture resistance and seal integrity are prioritized over thermal management.
- Aluminum Foil:Laminated foil constructions with polyethylene interlayers command premium positioning in cryogenic chemical processing applications. Chemical manufacturers specify foil-backed tapes for thermal conductivity management and electromagnetic shielding in ultra-low temperature reactor maintenance and sample preservation protocols.
- Polypropylene:Oriented polypropylene films offer stiffness and printability for barcode labeling applications in automated warehouse environments.
- PVC:Polyvinyl chloride backings provide conformability to irregular surfaces in legacy industrial freezer installations.
- Paper:Saturated kraft paper backings serve temporary holding and masking functions in food processing equipment maintenance.
Polyethylene dominates shipment volumes; aluminum foil laminates capture the widest margin spreads.
Application:
Regulatory documentation intensity varies sharply across application segments, with pharmaceutical logistics imposing the most demanding adhesive qualification protocols.
- Pharmaceutical Logistics:Track-and-trace labeling, tamper-evident sealing, and temperature excursion documentation for biologics distribution. FDA cold-chain rules and EMA Good Distribution Practice guidelines mandate batch-level traceability and performance record retention across United States and European Union distribution networks.
- Cold Storage:Pallet labeling, rack identification, and inventory management in automated warehouse environments. Third-party logistics operators in Germany and the Netherlands specify freezer-grade adhesives for minus twenty-five degrees Celsius ambient storage of packaged consumer goods.
- Food Packaging:Case sealing, date coding, and allergen labeling for frozen food manufacturing and distribution.
- Chemical Processing:Cryogenic sample labeling, equipment tagging, and safety documentation in industrial gas and specialty chemical facilities.
Pharmaceutical logistics commands the highest specification tier; cold storage moves the largest physical volume.
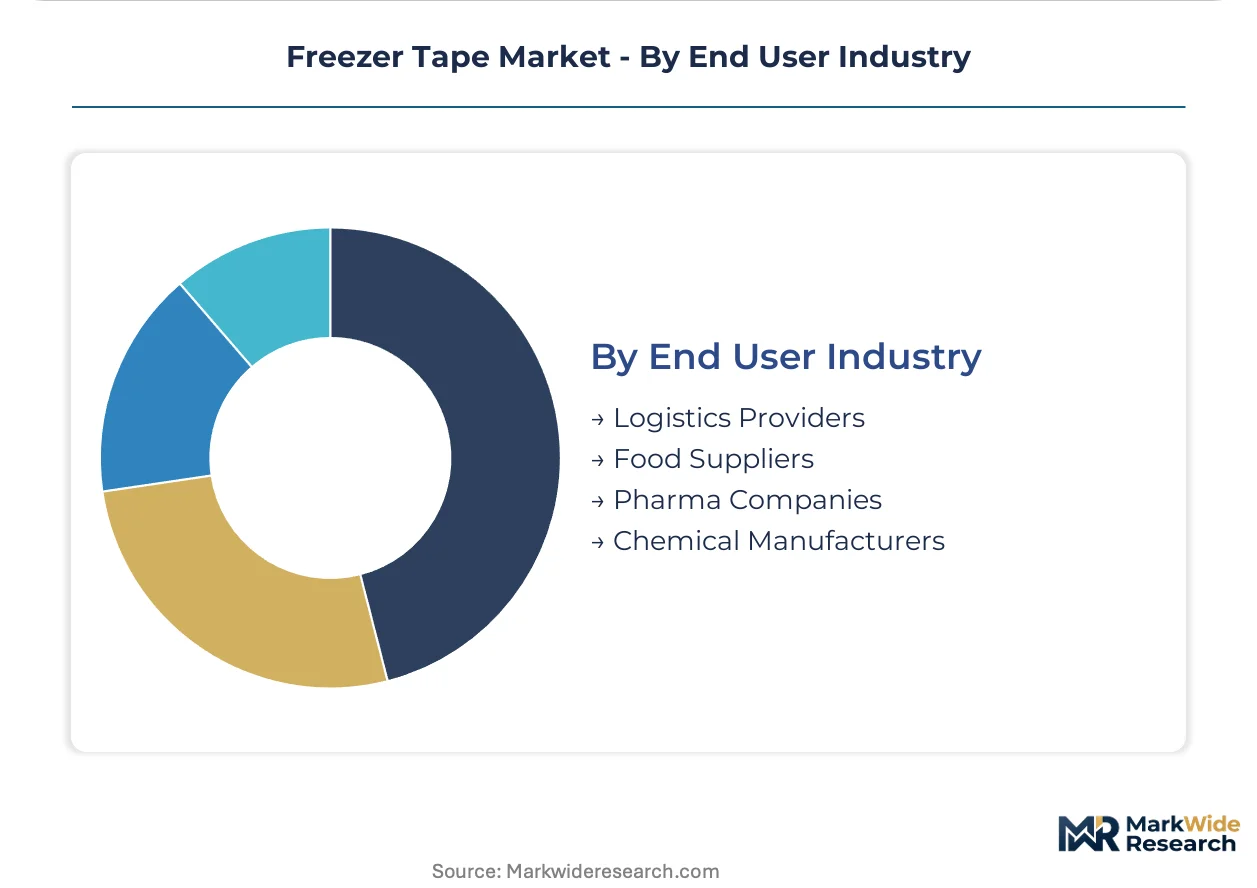
End User Industry:
Procurement centralization patterns differ markedly across end user categories, with pharma companies unbundling tape from general packaging agreements.
- Pharma Companies:Integrated biologics manufacturers and specialty pharmacy networks source validated freezer tapes through direct technical relationships with adhesive specialists. Large pharmaceutical distributors in the United States bypass industrial packaging distributors to secure batch documentation and quality management system alignment.
- Logistics Providers:Cold-chain third-party logistics operators manage multi-client inventory with standardized tape specifications across temperature zones. Consolidated buying by integrated logistics platforms in North America and Europe is compressing supplier rosters and elevating technical service requirements.
- Food Suppliers:Frozen food manufacturers and retail distribution centers prioritize cost efficiency and supply security in high-volume procurement.
- Chemical Manufacturers:Industrial gas producers and specialty chemical companies specify tapes for cryogenic handling and safety compliance in plant operations.
Logistics providers aggregate the broadest demand base; pharma companies drive the most rapid specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adhesive substrate manufacturing clusters in eastern China supply the majority of freezer tape backings, while pharmaceutical validation protocols concentrate specification-setting authority in the United States and Germany.
United States
FDA cold-chain documentation rules are tightening adhesive performance benchmarks for biologics distributors. The agency's updated traceability mandates expand validation testing volumes across domestic pharmaceutical networks. Boston and San Francisco biotech corridors drive silicone tape demand for cell therapy logistics.
Germany
EMA Good Distribution Practice guidelines mandate tamper-evident sealing documentation across EU member states. German cold-chain service providers retrofit quality management systems to capture batch-level tape traceability data. The Rhine-Ruhr logistics cluster anchors European specification-setting for pharmaceutical-grade freezer tapes.
China
Jiangsu and Zhejiang provinces host concentrated polyethylene film and aluminum foil substrate manufacturing for global tape assemblers. NMPA cold-chain infrastructure investments support domestic biologics distribution expansion. Shanghai pharmaceutical parks are qualifying validated tape suppliers for export-oriented production.
India
CDSCO cold-chain infrastructure investments and export-oriented pharmaceutical parks open specification-setting opportunities for validated tape suppliers. The country's national pharmaceutical regulator aligns with international qualification timelines for silicone adhesive platforms. Hyderabad and Mumbai biologics manufacturing clusters are expanding freezer tape procurement for clinical trial specimen management.
Japan
PMDA validation protocols extend market entry cycles for novel silicone adhesive platforms targeting global biologics networks. METI standards govern temperature-testing requirements for domestic pharmaceutical distribution. Osaka-Kobe industrial corridors maintain specialized adhesive formulator expertise for sub-zero polymer rheology.
Freezer Tape Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the freezer tape market. Proprietary acrylic polymer chemistry sustains premium positioning for pharmaceutical track-and-trace applications, while substrate manufacturing scale anchors cost-competitive supply for Asia-Pacific food exporters. Three archetypes dominate: integrated materials specialists with captive polymer production, regional converters serving pharmaceutical validation requirements, and commodity assemblers leveraging substrate manufacturing clusters. Competitive dynamics center on M&A activity to secure adhesive formulator talent and strategic partnerships to accelerate silicone polymer R&D cycles ahead of traditional validation schedules.
Among Chinese substrate and adhesive manufacturers, Jiangyin Danuo Adhesive Products Co., Ltd., Jiangsu Shixin Adhesive Tape Products Co. Ltd., and Zhejiang Maxwel Insulation Technology Co., Ltd. occupy positions within the cost-competitive supply tier serving Asia-Pacific food exporters and industrial cold storage applications. MBK Tape Solutions represents the specialized converter archetype focused on custom die-cut configurations for clinical trial specimen management. 3M anchors the technology leadership tier through proprietary acrylic polymer chemistry for pharmaceutical track-and-trace applications.
| Leading Market Players |
|---|
| 3M |
| Jiangyin Danuo Adhesive Products Co., Ltd. |
| Jiangyin Haoxuan Aluminum Foil Adhesive Products Co., Ltd. |
| Jiangsu Shixin Adhesive Tape Products Co. Ltd. |
| JIANGYIN MEIYUAN INDUSTRIES |
| Jiangxi Ming Yang Glass Fiber Co., Ltd. |
| Zhejiang Maxwel Insulation Technology Co., Ltd. |
| MBK Tape Solutions |
| Can-Do National Tape |
| Others |
Supply & Pricing Matrix
FDA cold-chain documentation rules gate both supply qualification and price differentiation simultaneously, creating a bifurcated market where validated silicone adhesive platforms command substantial premiums over commodity acrylic formulations while mid-tier converters struggle to recover certification costs.
Pricing Analysis
FDA cold-chain documentation rules dictate the pricing tier structure across pharmaceutical logistics applications. Three-tier pricing structure across premium, standard, and economy levels separates validated silicone grades for ultra-cold biologics from FDA-compliant acrylic tapes and unvalidated rubber formulations. Price differentiation centers on certification grade and volume scale, with large pharmaceutical distributors extracting favorable terms through consolidated procurement. Cost compression in the mid-tier acrylic segment is intensifying because petrochemical feedstock volatility squeezes converters dependent on spot-market resin purchasing. Food suppliers and industrial cold storage operators exhibit the highest price sensitivity, while cell therapy developers accept premium positioning to secure validated supply.
Supply Chain Analysis
China and South Korea anchor substrate manufacturing for global freezer tape assemblers, with Jiangsu and Zhejiang provinces hosting concentrated polyethylene film and aluminum foil production. Raw material dependencies draw from acrylic monomer feedstocks, silicone polymer resins, and metallized film laminates. Single-source vulnerability concentrates in eastern Chinese substrate clusters, creating geographic exposure for North American and European tape converters. Distribution runs through direct technical relationships between adhesive specialists and integrated biologics manufacturers, bypassing traditional industrial packaging distributors for pharmaceutical-grade supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freezer tape functionality is shifting from passive sealing toward active traceability as RFID-NFC convergence creates platform economics around temperature-logging smart labels, with interoperability standards determining which adhesive suppliers capture data-layer value.
For Market Incumbents: Compound proprietary polymer chemistry advantages by accelerating silicone R&D cycles ahead of compressed biologics validation timelines. Deepen backward integration into acrylic monomer supply to buffer petrochemical volatility exposure. Secure adhesive formulator talent through targeted acquisition of specialized rheology teams in Japan and Germany, where sub-zero polymer expertise concentrates. For New Entrants and Emerging Players: Anchor in India's CDSCO-qualifying pharmaceutical parks, where export-oriented biologics manufacturing is expanding faster than validated tape supplier presence. Target clinical trial specimen management as the most penetrable application, where custom die-cut configurations and rapid technical service outweigh scale advantages. Pursue direct-to-clinic distribution relationships with hospital procurement platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicone adhesive platforms as extended cure cycles constrain output scalability relative to commodity formulations. Long-term viability favors integrated materials specialists with captive polymer production over pure-play converters. Acquire regional converters possessing FDA or EMA validation credentials but lacking scale. Watch silicone polymer R&D cycle compression relative to traditional pharmaceutical validation schedules as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Polymer R&D Acceleration | Compressed qualification timelines for ultra-cold biologics distribution force faster development cycles than traditional pharma validation permits. |
| Backward Integration into Acrylic Monomer Supply | Captive resin production buffers margin compression from petrochemical feedstock volatility affecting spot-market dependent converters. |
| RFID-NFC Smart Label Integration | Converging adhesive and inlay technologies enables temperature-logging traceability for high-value cell therapy shipments. |
| India Pharmaceutical Park Qualification | CDSCO cold-chain infrastructure investments open specification-setting opportunities ahead of validated supplier saturation. |
| Adhesive Formulator Talent Acquisition | Deep expertise in sub-zero polymer rheology resides with narrow specialized cohorts in Osaka-Kobe and Rhine-Ruhr clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold-chain logistics directors, pharmaceutical packaging engineers, adhesive R&D chemists, and regulatory affairs specialists at biologics distributors. Secondary validation drew from FDA cold-chain guidance documents, EMA Good Distribution Practice updates, ISO 9001 certification registries, and IEC temperature-testing standards. Customs trade data and pharmaceutical logistics operator procurement disclosures provided shipment volume cross-checks. Bottom-up tape consumption estimates triangulated against top-down cold-chain infrastructure investment flows.
Across the analysis window, volume and value outputs reflect segmented modeling across adhesive chemistry, backing substrate, temperature threshold, application intensity, and regional regulatory cluster dimensions. CAGRs were derived from adhesive consumption elasticity to biologics distribution network expansion and pharmaceutical cold-chain infrastructure deployment curves. Forecast inputs incorporated silicone polymer cure-cycle constraints, acrylic monomer price volatility bands, and multi-jurisdiction certification timeline differentials.
Material uncertainties — regulatory timeline compression, feedstock price shocks, and single-source substrate concentration — sit outside the modeled envelope. Forecasts reflect assumptions about continued biologics distribution network expansion and stable qualification protocol sequencing. Recalibration cycles align with material shifts in FDA documentation rule updates and EMA guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Differential Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Global Printed Tape Market
Tapes
Pre-Printed Tape Market
Tapes
Automotive Tapes Market
Tapes
Carbon Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Umbilical Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Tape Unwinder Market
Tapes
Dry Wall Tapes Market
Tapes
Double Sided Tape Market
Tapes
Paper Packaging Tapes Market
Tapes
Flocking Tape Market
Tapes
Acetate Cloth Tape Market
Tapes
Carton Sealing Tape Market