
 Galley Tapes Market | 2026-2036
Galley Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Galley Tapes Market Analytics
Capital-intensity divergence between integrated film producers and downstream converters is reorganizing competitive tiers in the galley tapes sector. 3M Company leverages captive resin synthesis and global certification infrastructure to sustain premium positioning across aerospace-qualified product lines. Scapa Group PLC competes through specialized coating capabilities and narrow-batch flexibility for marine and regional aviation customers.
Galley tapes are pressure-sensitive adhesive products engineered for bonding, sealing, and surface protection in confined food-service and equipment-mounting environments aboard aircraft, vessels, and railcars; they typically incorporate flame-retardant acrylic or silicone chemistries meeting smoke-toxicity specifications under FAR 25.853 and equivalent marine standards. Double-sided tape holds the largest volume share among product types due to its ubiquity in panel-to-frame assembly, while specialty tape commands the strongest margin pool as OEMs specify custom die-cut configurations for galley module integrators. Polyester dominates material selection for structural applications where dimensional stability under thermal cycling is critical, though polyethylene variants are gaining traction in quick-assembly retrofit programs where conformability to irregular substrates matters more than ultimate tensile strength.
FAA certification requirements under 14 CFR Part 25, EASA CS-25 flammability protocols, and REACH substance restrictions collectively determine which adhesive platforms qualify for galley installations in regulated transport sectors. These frameworks create a dual barrier: new entrants must secure multi-year qualification timelines with airframe OEMs while incumbent suppliers face reformulation costs when ECHA adds candidate substances to the authorization list. Stakeholders should monitor the convergence of sustainability mandates with existing flammability regimes, as bio-based adhesive research advances and regulators weigh lower-carbon alternatives against proven fire-performance track records.
Market Dynamics
REACH substance restrictions and FAA flammability recertification cycles are compressing adhesive qualification timelines while fragmenting supplier tiers between integrated resin producers and downstream converters.
Growth Catalysts
- Aerospace Interior Retrofit Cycles:Fleet modernization programs across narrow-body and wide-body platforms are expanding tape consumption for galley module sealing and panel bonding applications.
- EASA CS-25 Harmonization:European aviation safety protocols are aligning test methodologies with FAA standards, reducing dual-certification burdens for adhesive platforms serving transatlantic supply chains.
- Silicone Chemistry Advances:Low-VOC, high-temperature adhesive formulations are penetrating marine galley applications where smoke-toxicity specifications under SOLAS conventions apply.
Market Restraints
- Specialty Monomer Supply Concentration:Flame-retardant acrylic precursors depend on concentrated petrochemical feedstock sources in the US Gulf Coast and Rotterdam-Antwerp corridor.
- ECHA Authorization List Expansion:REACH candidate substance additions trigger mandatory reformulation costs for incumbent suppliers maintaining aerospace-qualified product lines.
- Structural Bonding Adhesives:Two-part epoxy and polyurethane systems compete for load-bearing galley installations where peel strength requirements exceed pressure-sensitive tape capabilities.
Strategic Opportunities
- India Defense Aviation:Indigenous transport aircraft programs under the country's defense procurement corridors create qualified supplier openings for cabin interior bonding materials.
- Bio-Based Adhesive Research:Lignin-derived tackifier platforms advancing through EU Green Deal-funded consortia offer pathways to lower-carbon certification maintenance.
- Direct OEM Engagement:Tier-one galley module integrators are consolidating vendor bases, creating channel consolidation opportunities for certified converters with die-cutting capabilities.
Industry Challenges
- Multi-Year Qualification Timelines:Airframe OEM certification protocols under 14 CFR Part 25 require extensive burn-test documentation and production part approval processes.
- Flammability Testing Capacity:Limited FAA-designated testing laboratories create bottlenecks for new adhesive platform validation, extending time-to-revenue for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galley Tapes Market |
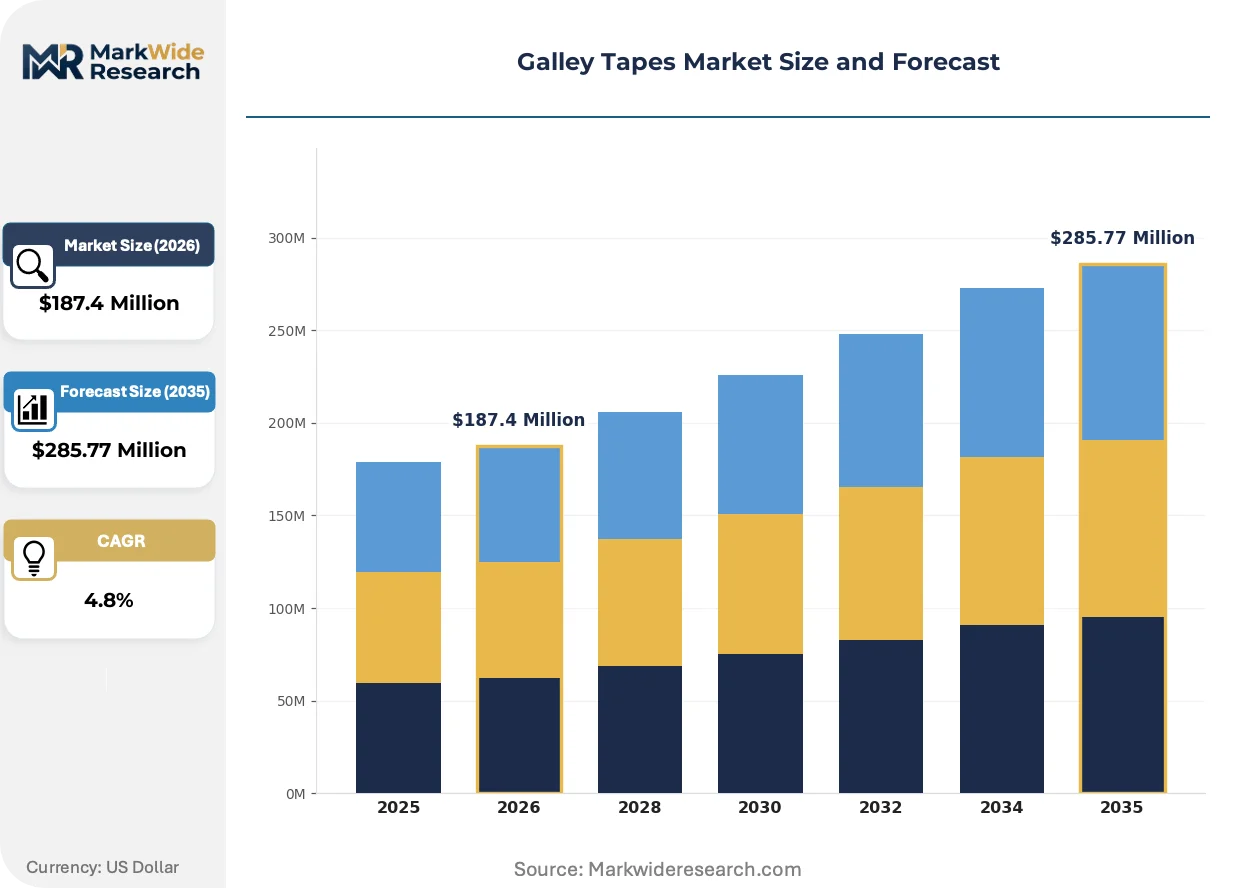
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tape, Foam Tape, Adhesive Transfer Tape, Specialty Tape Application: Aerospace, Automotive Manufacturing, Electronics Assembly, Marine Construction Material: Polyester, Polyethylene, Vinyl, Paper End User: Manufacturers, Contractors, DIY Enthusiasts, Commercial Operators |
| Companies Covered | 3M Company, Nitto Denko Corporation, tesa SE, Lintec Corporation, Avery Dennison Corporation, Intertape Polymer Group, Berry Global Inc., Scapa Group PLC, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galley Tapes Market Evolving Landscape
Adhesive platform evolution is accelerating around sustainability mandates and performance certification convergence, reshaping how converters align R&D roadmaps with regulatory timelines.
Flame-retardant polyester film carriers are fragmenting traditional nylon-reinforced tape architectures in structural galley applications. Tier-one aerospace suppliers are specifying dimensionally stable substrates for thermal cycling environments. This material shift is fragmenting legacy supply relationships as converters requalify coating lines for thinner, higher-modulus films.
REACH candidate substance restrictions are tightening specifications for halogenated flame retardants in European-registered aircraft. ECHA authorization procedures are forcing adhesive formulators toward phosphorus-nitrogen synergist systems. Marine galley segments serving EU-flagged vessels face parallel compliance pressures under the EU Green Deal's sustainable chemistry targets.
Consolidated procurement functions at major airline MRO providers are compressing supplier qualification cycles. Traditional distributor networks serving regional aviation operators face disintermediation as direct sourcing agreements with certified converters expand. Germany's aerospace manufacturing corridor around Hamburg exhibits the most pronounced channel consolidation, with tier-one galley module producers centralizing bonding material specifications.
Galley Tapes Market Segmentation
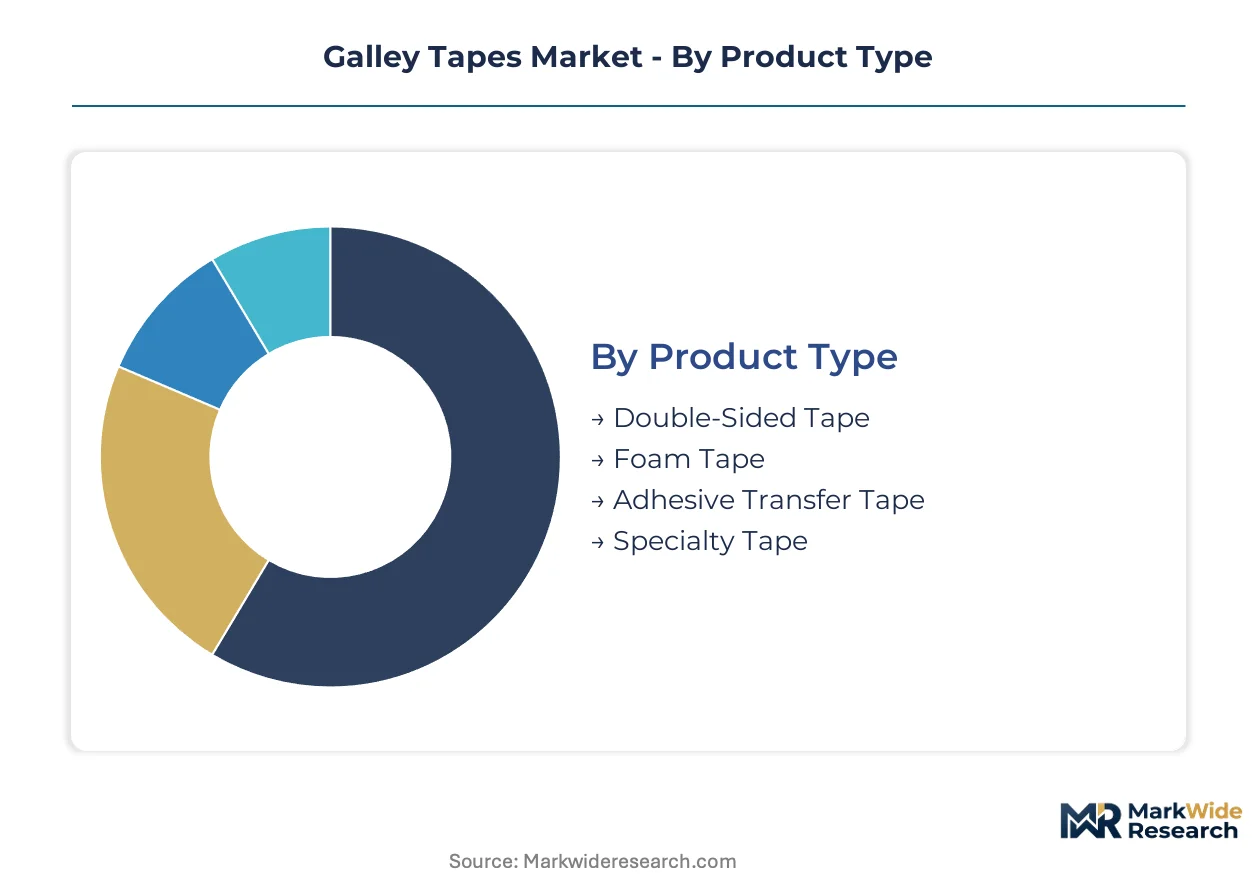
Galley tape specifications diverge sharply across transport sectors, with FAA 14 CFR Part 25, EASA CS-25, and SOLAS flammability protocols dictating which adhesive chemistries and carrier materials qualify for cabin installations. Segmentation reveals how regulatory scope, thermal performance requirements, and assembly methodologies fragment demand across aerospace, marine, and adjacent industrial applications.
Product Type:
FAA and EASA flammability certifications create tiered qualification barriers that concentrate volume in legacy formats while specialty configurations capture margin premiums through custom die-cutting and narrow-batch flexibility.
- Double-Sided Tape:Pressure-sensitive adhesive layers on both faces of polyester or polyethylene carriers enable rapid panel-to-frame bonding without mechanical fasteners. Aerospace retrofit programs in Germany's Hamburg-Munich manufacturing corridor consume substantial volumes for galley module assembly where FAR 25.853 smoke-toxicity compliance is mandatory.
- Specialty Tape:Custom die-cut configurations with flame-retardant acrylic or silicone chemistries serve OEM-specified geometries for tier-one galley integrators. REACH candidate substance restrictions on halogenated flame retardants are forcing reformulation toward phosphorus-nitrogen synergist systems in European-registered aircraft applications.
- Foam Tape:Conformable acrylic foam carriers absorb thermal expansion stresses in marine galley installations subject to SOLAS smoke-toxicity protocols.
- Adhesive Transfer Tape:Unsupported adhesive films provide ultra-thin bonding layers for electronics-adjacent galley equipment mounting where space constraints dominate.
Established volume favors double-sided tape; emerging adoption favors specialty tape.
Application:
End-use concentration reflects the divergence between regulated transport sectors with multi-year qualification timelines and industrial segments with compressed procurement cycles.
- Aerospace:Narrow-body and wide-body fleet modernization programs drive consumption for cabin sealing, panel bonding, and surface protection in confined food-service environments. EASA CS-25 harmonization with FAA test methodologies is reducing dual-certification burdens for adhesive platforms serving transatlantic supply chains.
- Marine Construction:EU-flagged vessels face parallel compliance pressures under REACH substance restrictions and EU Green Deal sustainable chemistry targets for galley installations. Low-VOC silicone formulations are penetrating this segment where SOLAS conventions apply.
- Automotive Manufacturing:Quick-assembly bonding for specialty vehicle galley conversions leverages polyethylene tape variants where conformability matters more than ultimate tensile strength.
- Electronics Assembly:Precision mounting applications for galley-adjacent control interfaces specify thin-gauge adhesive transfer tapes with dielectric properties.
Aerospace commands the dominant share; marine construction is climbing the fastest on regulatory harmonization and fleet renewal.
Material:
Carrier selection trades dimensional stability against conformability, with thermal cycling performance separating aerospace-qualified specifications from general industrial grades.
- Polyester:High-modulus film carriers provide dimensional stability under repeated thermal cycling in structural galley applications. Tier-one aerospace suppliers are specifying thinner, higher-modulus polyester substrates that fragment legacy nylon-reinforced tape architectures.
- Polyethylene:Lower modulus and superior conformability to irregular substrates support quick-assembly retrofit programs where speed of installation outweighs ultimate load-bearing requirements.
- Vinyl:Cost-effective carrier for general industrial bonding with limited temperature resistance.
- Paper:Temporary holding and masking applications in pre-assembly surface preparation workflows.
Polyester dominates certified aerospace demand; polyethylene is gaining share fastest in retrofit-focused procurement.
End User:
Procurement authority concentration is compressing supplier qualification cycles as consolidated MRO functions disintermediate traditional distributor networks.
- Manufacturers:Tier-one galley module integrators in Germany's aerospace corridor centralize bonding material specifications through direct sourcing agreements with certified converters. These stakeholders demand die-cutting capabilities and batch-traceable certification documentation.
- Commercial Operators:Airline MRO providers with consolidated procurement functions are narrowing approved vendor lists to converters with established FAA and EASA qualification portfolios.
- Contractors:Regional aviation and marine refit specialists source through remaining distributor channels with compressed lead time requirements.
- DIY Enthusiasts:Minimal penetration due to flammability certification barriers; limited to non-regulated recreational vessel applications.
Manufacturer direct procurement dominates value capture; commercial operator consolidation is reshaping channel structure most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's aerospace corridor consumes galley tapes through tier-one module integrators demanding die-cut precision, while the United States prioritizes fleet retrofit volumes and India's defense aviation programs source certified bonding materials for indigenous transport aircraft.
Germany
Tier-one galley module producers around Hamburg and Munich centralize bonding material specifications through direct sourcing agreements with certified converters. REACH substance restrictions on halogenated flame retardants force adhesive formulators toward phosphorus-nitrogen synergist systems for European-registered aircraft. The Hamburg-Munich manufacturing corridor exhibits pronounced channel consolidation as procurement functions narrow approved vendor lists.
United States
Narrow-body and wide-body fleet modernization programs drive substantial tape consumption for cabin sealing and panel bonding applications. FAA certification requirements under 14 CFR Part 25 mandate extensive burn-test documentation and production part approval processes for adhesive platforms. Concentrated petrochemical feedstock sources along the US Gulf Coast supply flame-retardant acrylic precursors to domestic converter operations.
India
Indigenous transport aircraft programs under defense procurement corridors create qualified supplier openings for cabin interior bonding materials. BIS standards and DGFT import regulations shape adhesive qualification pathways for foreign converters seeking market entry. Aerospace manufacturing clusters in Karnataka and Telangana are developing tier-two supplier ecosystems for galley module assembly.
France
EASA CS-25 harmonization with FAA test methodologies reduces dual-certification burdens for adhesive platforms serving transatlantic supply chains. ANSM oversight of industrial chemical applications intersects with aviation safety protocols for cabin interior materials. The Toulouse aerospace cluster anchors demand from airframe OEMs specifying custom die-cut configurations for galley installations.
Japan
PMDA and METI frameworks govern chemical substance registration for adhesive formulations used in transport applications. JIS standards provide baseline specifications for pressure-sensitive tapes serving industrial and aviation-adjacent segments. The Nagoya aerospace manufacturing region sources bonding materials for regional jet programs and marine galley retrofits under SOLAS conventions.
Galley Tapes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive resin synthesis capabilities separating premium-positioned suppliers from downstream converters dependent on merchant feedstocks. The market structure rewards multi-year certification portfolios with airframe OEMs while compressing margins for undifferentiated commodity formats. Two strategic archetypes dominate: integrated film producers controlling upstream polymer synthesis and specialized coating houses offering narrow-batch flexibility. Competitive moves center on direct OEM engagement strategies and die-cutting capability investments that bypass traditional distribution channels.
Among integrated multinational suppliers, 3M Company and Nitto Denko Corporation exemplify the premium-tier archetype through established aerospace qualification infrastructure. Tesa SE anchors the European specialist position with coating capabilities concentrated in certified adhesive platforms. These three names represent the competitive core around which tier-two converters and regional coating houses organize their market participation.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| tesa SE |
| Lintec Corporation |
| Avery Dennison Corporation |
| Intertape Polymer Group |
| Berry Global Inc. |
| Scapa Group PLC |
| Lohmann GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
FAA 14 CFR Part 25 and EASA CS-25 certification protocols gate both supplier qualification and price differentiation simultaneously, concentrating pricing power among converters with established aerospace portfolios while compressing margins for undifferentiated commodity formats.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier-one galley module integrators and certified converters, with spot purchasing limited to emergency retrofit scenarios. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and batch traceability documentation. Cost compression in standard-grade polyethylene tapes is intensifying because REACH reformulation cycles erode incumbent margin buffers. Regional aviation contractors exhibit highest price sensitivity; OEM direct accounts prioritize qualification reliability over unit cost.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp petrochemical corridors to German aerospace manufacturing clusters have tightened converter margin structures. Flame-retardant acrylic precursors draw from concentrated US Gulf Coast and North Sea feedstock sources. Polyester film carriers rest on Asian and European polymer synthesis capacity. Single-source vulnerability concentrates in specialty monomer supply for phosphorus-nitrogen synergist formulations. Distribution runs through direct OEM agreements with die-cutting capability requirements, bypassing traditional industrial tape distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Galley tape procurement is consolidating around platform-certified adhesive ecosystems, with interoperability between EASA and FAA test methodologies reducing dual-qualification friction for converters serving transatlantic supply chains.
For Market Incumbents: Shield aerospace-qualified product lines by accelerating backward integration into captive resin synthesis for flame-retardant acrylic precursors. Deepen die-cutting capabilities at Hamburg and Munich service centers to capture tier-one galley module integrator consolidation. Counter REACH authorization list expansion by pre-qualifying phosphorus-nitrogen synergist platforms before mandatory reformulation deadlines. For New Entrants and Emerging Players: Aftermarket technical service gaps in regional aviation MRO networks offer white-space entry points where incumbent converters prioritize OEM direct accounts. Marine galley retrofit demand under SOLAS conventions represents the most penetrable segment for unqualified suppliers building certification track records. Pursue joint development agreements with EU-flagged vessel operators to establish burn-test documentation under lower regulatory barriers than aerospace applications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialty tape coating lines as REACH compliance forces dedicated production segregation. Long-term viability favors converters with established FAA and EASA qualification portfolios rather than merchant feedstock-dependent coating houses. Acquisition targets should demonstrate die-cutting automation and batch-traceable certification documentation. Monitor ECHA candidate substance list additions as the critical inflection signal for reformulation cost waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive supply of flame-retardant acrylic precursors insulates margin structures from petrochemical feedstock volatility. |
| Die-Cutting Capability Expansion | Precision cutting automation captures tier-one galley module integrator procurement consolidation in Germany's aerospace corridor. |
| REACH-Compliant Formulation Pre-Qualification | Phosphorus-nitrogen synergist platforms reduce mandatory reformulation costs when ECHA expands authorization lists. |
| Direct OEM Engagement Programs | Bypassing traditional distributor networks captures value from consolidated procurement functions at airline MRO providers. |
| Marine Certification Track-Building | SOLAS burn-test documentation establishes regulatory credibility for eventual aerospace qualification pursuit. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with adhesive formulators, tier-one galley module procurement directors, FAA-designated testing laboratory managers, and marine classification society surveyors; alongside secondary validation through EASA certification databases, REACH candidate substance registers, customs trade flows for pressure-sensitive tape classifications, and SEC filings from integrated tape manufacturers. Bottom-up segment sizing triangulated against top-down aerospace retrofit program announcements.
Across the analysis window, the forecast framework modeled demand by product type, application sector, carrier material grade, and end-user procurement authority concentration. CAGRs derived from segment-level volume trajectories indexed to fleet modernization cycle timing and regulatory harmonization milestones. Industry-specific inputs incorporated flame-retardant chemistry substitution elasticities and qualification timeline distributions for new adhesive platforms.
Underlying assumptions cover continued EASA-FAA test methodology convergence, with deviation risk concentrated in unilateral REACH substance restrictions or extended FAA certification backlogs at designated testing laboratories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Industrial Tapes Market
Tapes
Packaging Tapes Market
Tapes
Glue Tape Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Wing Walk Tapes Market
Tapes
Lacing Tape Market
Tapes
Paper Packaging Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Shipping Tapes Market
Tapes
Utility Grade Duct Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
Paper Masking Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Europe Packaging Tapes Market
Tapes
Freezer Tape Market
Tapes
Sealing and Strapping Packaging Tapes Market