
 Gummed Tapes Market | 2026-2036
Gummed Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Gummed Tapes Market Outlook
European kraft paper mills is broadening substrate availability for adhesive tape converters. 3M Company leverages its polymer science infrastructure to sustain high-performance tape formulations across industrial grades. Intertape Polymer Group anchors North American supply through integrated paper and adhesive operations. Tesa SE differentiates via precision coating capabilities that serve electronics and automotive packaging segments.
Gummed tapes are paper-based adhesive strips activated by water to form permanent fiber-to-fiber bonds with corrugated surfaces, typically manufactured through starch or dextrin adhesive saturation of kraft backings at controlled viscosity levels. Water-activated tapes dominate e-commerce packaging due to their tamper-evident seal integrity and recyclability compatibility with corrugated waste streams. Specialty tapes command premium positioning in industrial applications requiring heat resistance or reinforced fiberglass backings. Biodegradable materials represent the fastest-growing material category as brand owners face packaging waste accountability mandates.
FDA regulations govern indirect food contact adhesives in gummed tapes used for agricultural and food product packaging. EPA guidelines on volatile organic compound emissions affect adhesive formulation choices in domestic manufacturing facilities. OSHA workplace exposure standards influence solvent-free adhesive adoption across converter operations. Stakeholders must monitor evolving extended producer responsibility frameworks that will reshape material specifications and recycling infrastructure requirements.
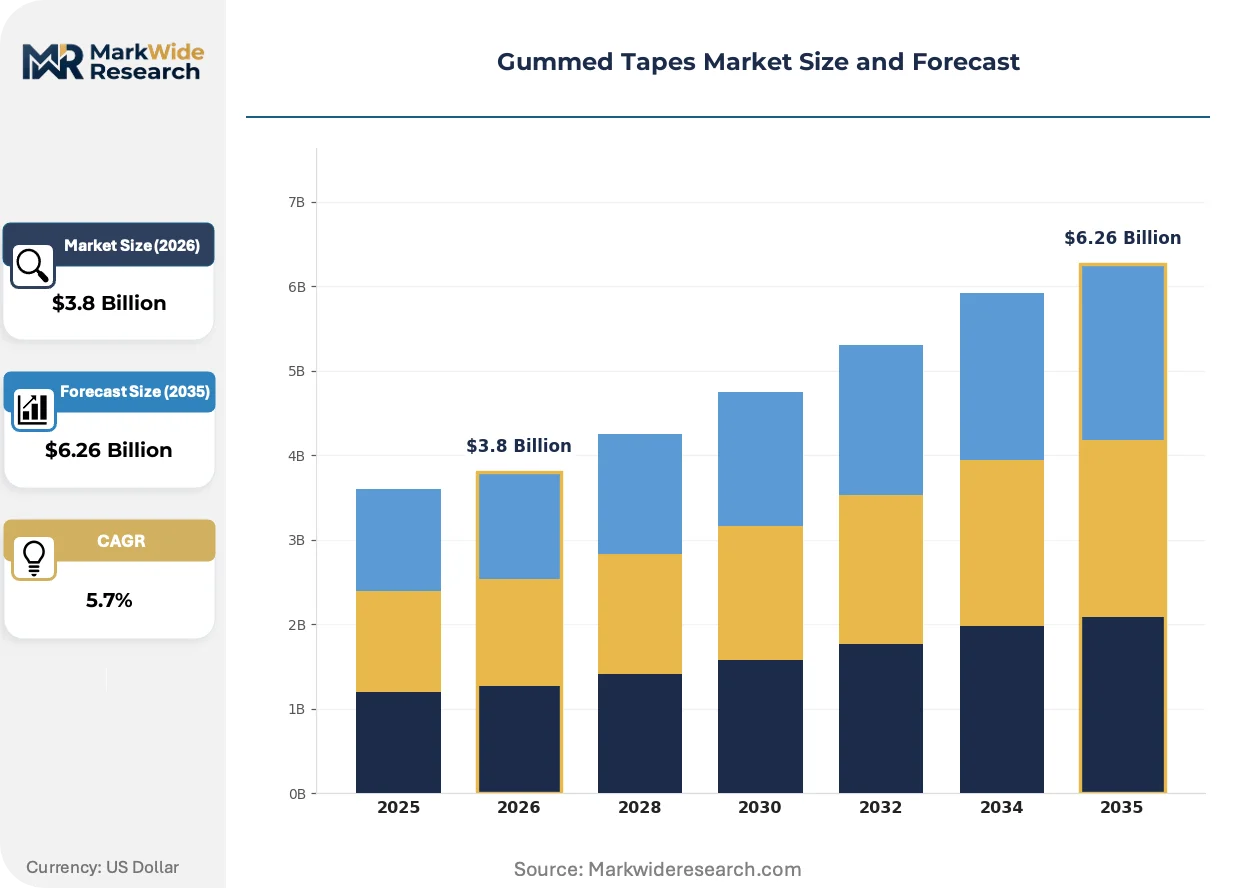
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to abandon plastic-based sealing solutions in favor of biodegradable fiber alternatives, restructuring raw material sourcing across the value chain.
Growth Catalysts
- E-commerce Fulfillment Surge:Fulfillment centers in Germany and the Netherlands are mandating water-activated tapes for carton security due to their tamper-evident fiber bonds. This operational standard is spreading to cross-border logistics hubs.
- REACH Compliance Deadlines:The European Chemicals Agency is phasing out certain synthetic adhesive components, pushing converters toward starch and dextrin formulations that align with gummed tape chemistry.
- Automotive Export Packaging:German automotive parts exporters require heat-resistant reinforced tapes for overseas shipment integrity, creating specialized demand for fiberglass-backed grades.
Market Restraints
- Kraft Pulp Price Volatility:European paper mills face input cost pressure from energy-intensive pulping processes, compressing margins for tape converters dependent on virgin fiber backings.
- Application Equipment Concentration:Water-activated tape dispensers require capital investment that small-scale e-commerce operators in Eastern Europe cannot absorb, limiting addressable market expansion.
- Pressure-Sensitive Substitution:Hot-melt and acrylic adhesive tapes from integrated polymer suppliers offer immediate tack without moisture activation, capturing time-sensitive packaging segments.
Strategic Opportunities
- Poland Manufacturing Expansion:The country's packaging cluster offers lower-cost conversion capacity for serving Central European e-commerce growth with localized production.
- Food-Contact Certification:FDA-compliant adhesive formulations for agricultural packaging open North American export channels for European converters meeting indirect food contact standards.
- Digital Printing Integration:Combining water-activated tapes with on-demand printed branding enables converters to capture value from customized unboxing experiences in premium retail segments.
Industry Challenges
- Adhesive Formulation Expertise Gap:Converter operations lack chemists capable of optimizing starch viscosity for varying humidity conditions across seasonal production cycles.
- Extended Producer Responsibility Compliance:The EU Green Deal's evolving waste accountability frameworks require traceability systems that small converters cannot implement without external certification support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gummed Tapes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Activated Tapes, Pressure-Sensitive Tapes, Specialty Tapes, Double-Sided Tapes Application: Packaging, Crafting, Industrial, Labeling Material: Papers, Plastics, Fibers, Biodegradable Materials End User: Retail, E-commerce, Manufacturing, Shipping |
| Companies Covered | 3M Company, Intertape Polymer Group, Shurtape Technologies, Tesa SE, Nitto Denko Corporation, PPM Industries SpA, Vibac Group, Berry Global, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gummed Tapes Market Strategic Shifts
Automation of tape application and adhesive formulation is compressing labor dependency while regulatory pressure on packaging waste is accelerating material innovation cycles across European manufacturing.
Precision coating control systems is automating adhesive saturation consistency in kraft backings. High-volume e-commerce fulfillment operators in Germany are deploying these systems to reduce tape waste from uneven glue distribution. This automation is compressing quality variation between production batches and reducing manual inspection headcount.
REACH authorization requirements for synthetic polymers is redirecting research investment toward bio-based dextrin and modified starch adhesives. The regulation's sunset clauses for certain petrochemical binders are forcing reformulation timelines that favor established European converters with in-house laboratories. Food-contact packaging segments are responding fastest due to parallel FDA compliance needs for export markets.
Consolidated procurement by multinational e-commerce platforms is displacing fragmented distributor relationships. Amazon and Zalando-scale operators in Germany and the Netherlands are negotiating direct supply agreements with tape converters, bypassing traditional packaging distributors. This concentration is most visible in the Benelux region where fulfillment density supports dedicated production lines.
Gummed Tapes Market Segmentation
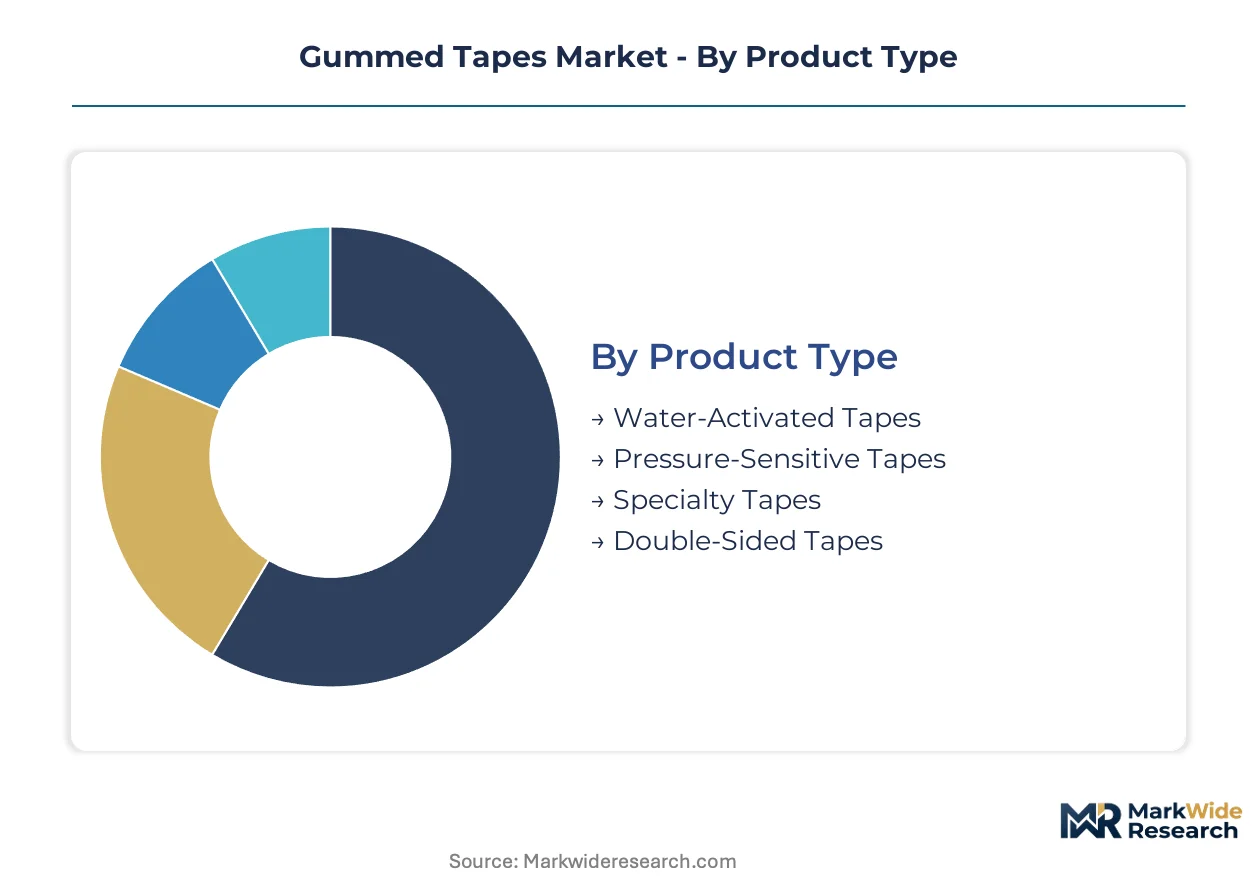
Gummed tape buyers select products based on activation method, substrate durability, and regulatory compliance requirements. Segmentation reveals how e-commerce fulfillment centers, industrial exporters, and craft retailers prioritize different performance attributes and price points.
Product Type:
Buyers in this category differentiate by activation speed, bond permanence, and equipment requirements for their packaging lines.
- Water-Activated Tapes:Starch or dextrin adhesives saturate kraft backings to create permanent fiber-to-fiber bonds with corrugated surfaces upon moisture contact. German automotive parts exporters and Netherlands fulfillment centers specify these for tamper-evident carton security. E-commerce platforms mandate this format for recyclability compliance with EU Packaging and Packaging Waste Regulation requirements.
- Pressure-Sensitive Tapes:Hot-melt or acrylic adhesives provide immediate tack without moisture activation or specialized dispensers. Small-scale Eastern European e-commerce operators favor these for lower capital equipment thresholds. Time-sensitive packaging segments accept weaker corrugated bonds in exchange for application speed.
- Specialty Tapes:Reinforced fiberglass backings or heat-resistant formulations serve industrial applications requiring dimensional stability under thermal stress.
- Double-Sided Tapes:Adhesive coatings on both substrate faces enable mounting and splicing applications in manufacturing environments.
Volume sits with Water-Activated Tapes; growth tilts toward Specialty Tapes.
Application:
End-use environments dictate adhesive chemistry selection and backing reinforcement levels.
- Packaging:Carton sealing operations dominate tape consumption across e-commerce fulfillment networks. German and Netherlands distribution centers specify water-activated formats for automated case-sealing lines. REACH compliance deadlines for synthetic adhesives push converters toward starch-based formulations in this high-volume segment.
- Industrial:Heat-resistant reinforced tapes secure automotive components for overseas shipment integrity. German exporters require fiberglass-backed grades that withstand temperature fluctuations during containerized transport.
- Crafting:Decorative and archival-quality paper tapes serve hobbyist and educational markets with lower volume but premium positioning.
- Labeling:Printable kraft surfaces enable on-demand branding integration for customized unboxing experiences in premium retail segments.
Packaging commands the largest share; Industrial applications are expanding most quickly.
Material:
Substrate selection determines recyclability credentials and compliance with extended producer responsibility frameworks.
- Papers:Virgin and recycled kraft backings provide the standard substrate for water-activated tapes. European paper mills face energy-intensive pulping cost pressures that compress converter margins. Kraft pulp price volatility from these mills directly impacts tape production economics.
- Biodegradable Materials:Modified starch films and cellulose derivatives align with EU Green Deal waste accountability mandates. Brand owners facing packaging waste accountability requirements specify these substrates fastest. The EU Packaging and Packaging Waste Regulation accelerates converter migration toward biodegradable alternatives.
- Plastics:Polypropylene and PVC backings persist in pressure-sensitive formats despite regulatory pressure.
- Fibers:Glass and synthetic fiber reinforcements provide tensile strength for heavy-duty industrial applications.
Papers dominate current volume; Biodegradable Materials show the steepest expansion trajectory.
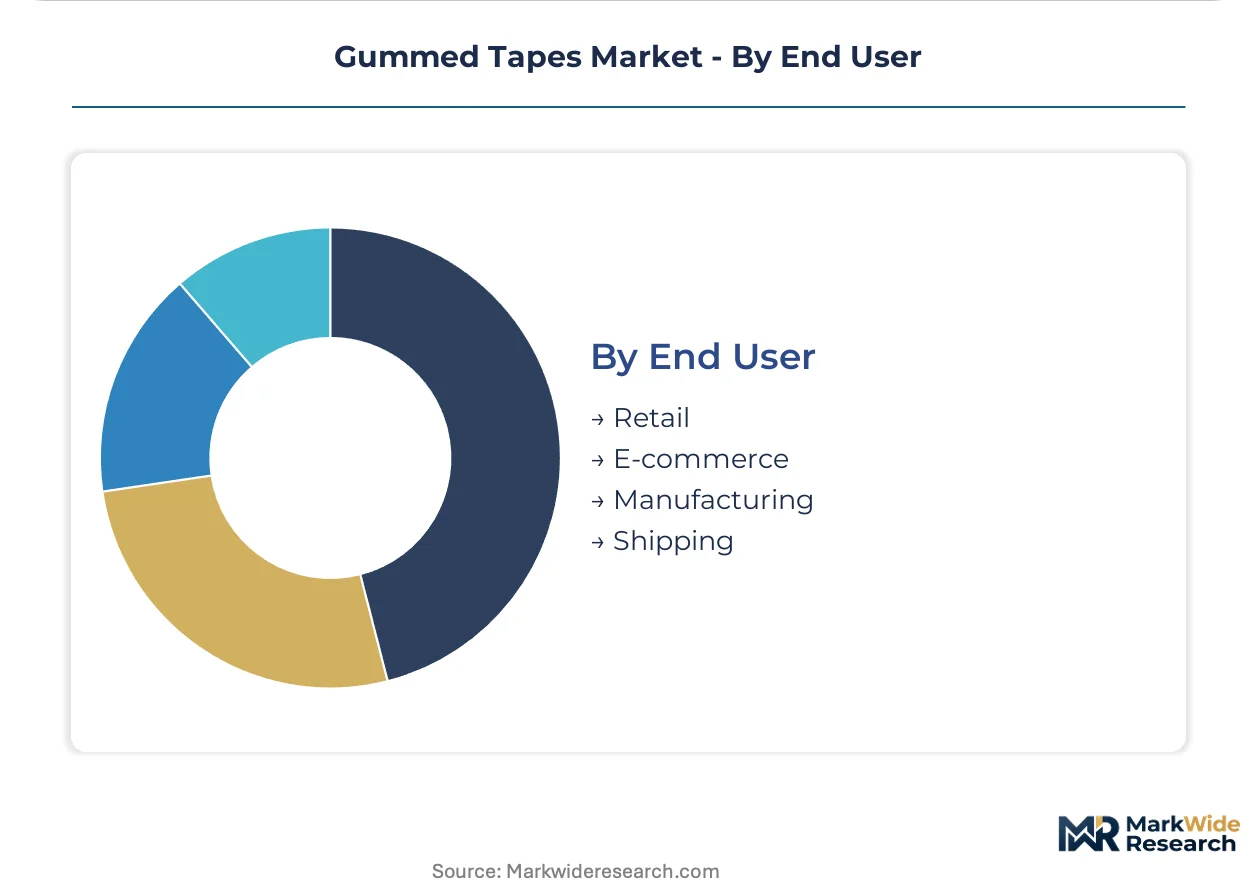
End User:
Procurement scale and technical specification authority separate enterprise buyers from fragmented small-account demand.
- E-commerce:Amazon and Zalando-scale operators negotiate direct supply agreements with tape converters, bypassing traditional packaging distributors. Consolidated procurement concentrates demand in Germany and the Netherlands where fulfillment density supports dedicated production lines. These buyers mandate water-activated tapes for recyclability and tamper-evidence.
- Manufacturing:Automotive parts exporters require heat-resistant reinforced tapes with certified performance specifications. German industrial buyers specify fiberglass-backed grades for overseas shipment integrity.
- Retail:Brick-and-mortar chains and specialty stores procure through distributor relationships with fragmented order patterns.
- Shipping:Third-party logistics providers balance cost and performance across diverse customer requirements.
E-commerce captures the highest volume concentration; Manufacturing offers the most specialized premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European kraft paper mills anchor regional substrate supply for adhesive tape converters, with German automotive exporters and Netherlands fulfillment centers driving specialized demand for tamper-evident sealing solutions.
Germany
Automotive parts exporters in Stuttgart and Munich require heat-resistant reinforced tapes for overseas shipment integrity. The EU Packaging and Packaging Waste Regulation mandates biodegradable fiber alternatives for export packaging. The Rhine-Ruhr industrial corridor hosts converter operations supplying fiberglass-backed grades to containerized logistics networks.
Netherlands
Rotterdam and Venlo fulfillment centers mandate water-activated tapes for automated carton-sealing lines serving cross-border e-commerce. REACH compliance deadlines from the European Chemicals Agency phase out synthetic adhesive components in favor of starch formulations. The Randstad logistics cluster concentrates procurement scale for direct converter supply agreements.
United States
FDA regulations govern indirect food contact adhesives in agricultural packaging applications across California's Central Valley and Florida's produce belt. EPA guidelines on volatile organic compound emissions affect adhesive formulation choices in domestic manufacturing facilities. The Southeast packaging corridor from Georgia to the Carolinas hosts converter capacity serving e-commerce distribution networks.
Poland
Lower-cost conversion capacity in Warsaw and Krakow packaging clusters targets Central European e-commerce growth with localized production. Extended producer responsibility frameworks from the EU Green Deal reshape material specifications for export-bound converters. The Silesian industrial region develops traceability systems for waste accountability compliance.
Japan
Precision electronics manufacturers in Osaka and Nagoya specify coated tapes for cleanroom packaging applications. METI standards influence adhesive performance specifications for industrial export packaging. The Kanto region around Tokyo hosts converter operations integrating digital printing for customized unboxing experiences in premium retail segments.
Gummed Tapes Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable substrate specialization and automation integration. The market structure reflects moderate consolidation among integrated paper-adhesive operators alongside fragmented regional converters. Three archetypes dominate: multinational polymer science specialists, integrated kraft-to-tape manufacturers, and precision coating technicians serving electronics segments. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters secure pulp supply agreements and fulfillment center direct contracts.
Within the multinational specialist tier, 3M Company and Nitto Denko Corporation exemplify polymer science infrastructure applied to industrial-grade formulations. Tesa SE occupies a position representing precision coating capabilities for automotive and electronics packaging segments. Intertape Polymer Group anchors the integrated manufacturing archetype through captive paper and adhesive operations across North American supply chains.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group |
| Shurtape Technologies |
| Tesa SE |
| Nitto Denko Corporation |
| PPM Industries SpA |
| Vibac Group |
| Berry Global |
| Avery Dennison Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal waste accountability mandates gate qualified supply and premium-tier pricing access for converters seeking automotive and e-commerce certification. Kraft pulp availability from European mills and adhesive formulation expertise constrain tiered positioning across buyer segments.
Pricing Analysis
Equipment-bundling arrangements separate premium converter relationships from unbundled commodity transactions. Three-tier pricing structure across certified food-contact, industrial reinforced, and standard economy levels reflects starch viscosity grades and REACH compliance investment. Cost compression in standard grades intensifies because Eastern European operators lack dispenser capital for water-activated adoption. Small-scale e-commerce merchants exhibit highest price sensitivity; German automotive exporters accept premium positioning for heat-resistant fiberglass specifications.
Supply Chain Analysis
Kraft paper supply rests on German, Swedish, and Finnish pulp mill operations with energy-intensive production economics. Starch adhesive feedstocks, fiberglass reinforcement yarns, and precision coating equipment anchor converter input dependencies. Single-source vulnerability concentrates in specialized dextrin formulations from established European chemical suppliers. Distribution runs through direct fulfillment center contracts for Amazon-scale operators and fragmented distributor networks for craft and retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized adhesive formulation capacity represents the binding constraint propping premium-tier pricing across automotive and food-contact segments. Qualified chemist scarcity limits rapid supply expansion regardless of pulp substrate availability.
For Market Incumbents: Acquire in-house starch modification laboratories to defend against pressure-sensitive tape substitution from polymer specialists. Secure long-term kraft pulp offtake agreements with Rhine-Ruhr corridor mills. Invest in FDA-compliant adhesive certification to capture North American agricultural packaging export channels before REACH sunset clauses accelerate competitor migration. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation in Germany and the Netherlands opens a window for biodegradable substrate specialization serving consolidated e-commerce procurement. Target Poland's underdeveloped Central European fulfillment infrastructure with localized water-activated tape conversion. Pursue direct supply agreements with mid-scale logistics operators bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Amazon and Zalando direct converter contract announcements are the leading indicator that procurement concentration has reached inflection. Position for 5-10 year horizon consolidation around integrated paper-adhesive operators with precision coating capabilities. Monitor REACH authorization timelines for synthetic polymer phase-outs as acquisition timing signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber sourcing from Scandinavian mills insulates margin from energy cost volatility. |
| FDA Food-Contact Certification Investment | Regulatory approval unlocks California Central Valley agricultural packaging export demand. |
| Precision Coating Automation Deployment | German fulfillment centers specify adhesive saturation consistency for waste reduction. |
| Biodegradable Substrate R&D Partnership | Modified starch film development aligns with EU Green Deal extended producer responsibility. |
| Direct E-Commerce Supply Agreement | Rotterdam and Venlo fulfillment density supports dedicated production line economics. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tape converter plant managers, e-commerce fulfillment procurement leads, automotive packaging engineers, and kraft mill sales directors combined with ECHA REACH substance databases, EU Packaging and Packaging Waste Regulation implementation documents, and FDA indirect food contact guidance. Bottom-up production capacity estimates triangulated against top-down end-use consumption models.
Data-stream reconciliation across shipment volumes, adhesive formulation patent filings, and fulfillment center equipment procurement tracked segment trajectories over the projection horizon. Segmentation modeling incorporated activation method, substrate durability grade, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from production capacity expansion announcements and buyer procurement scale concentration patterns. Kraft pulp price indices and synthetic adhesive component sunset timelines fed industry-specific forecast sensitivity.
Caveats apply where REACH authorization delays or kraft mill energy cost spikes could materially shift the outlook. Forecasts reflect assumptions about e-commerce fulfillment automation adoption rates and biodegradable substrate performance certification timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Mastic Tapes Market
Tapes
Splicing Tapes Market
Tapes
Labels, Tapes and Films Market
Tapes
Tabbing Tapes Market
Tapes
Aluminum Foil Tape Market
Tapes
Metal Foil Tapes Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Tape and Label Adhesives Market
Tapes
Tissue Tapes Market
Tapes
Hand Wrappers Market
Tapes
Tape Unwinder Market
Tapes
Moisture Barrier Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Foil Tapes Market
Tapes
Application Tapes Market