
 Seam Tapes Market | 2026-2036
Seam Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Seam Tapes Market Analysis
Technical outerwear brands is collapsing the historical split between mass-market sportswear and expedition-grade apparel, forcing seam tape suppliers to serve both performance tiers simultaneously. Toray Industries Inc. leverages its polymer science heritage to dominate high-end membrane-to-tape integration. Bemis Associates Inc. anchors North American supply through vertically controlled thermal-bonding operations. DingZing Advanced Material Inc. competes on polyurethane formulation breadth across Asian manufacturing hubs.
Seam tapes are thermoplastic adhesive strips, typically 15-40 mm wide, applied under heat and pressure to seal stitched seams against water ingress in laminated textiles. Polyurethane-based tapes deliver superior elasticity for stretch garments, while polyethylene formulations dominate cost-sensitive industrial protective gear. Single-sided tape leads apparel volume due to simpler application on two-layer constructions, though double-sided tape captures expanding automotive interior panel bonding. Fabric tape variants command premium positioning in military and firefighter gear where substrate compatibility determines field reliability.
REACH compliance through ECHA restricts solvent-based adhesive chemistries across European supply chains, while EPA PFAS guidance in the United States pushes fluorocarbon-free alternatives into development pipelines. China's GB standards for textile safety, enforced by SAMR, create parallel certification requirements for export-oriented manufacturers. Stakeholders must decide whether to consolidate around water-based polyurethane platforms or maintain parallel solvent and solvent-free production lines as regulatory divergence between jurisdictions widens.
Market Dynamics
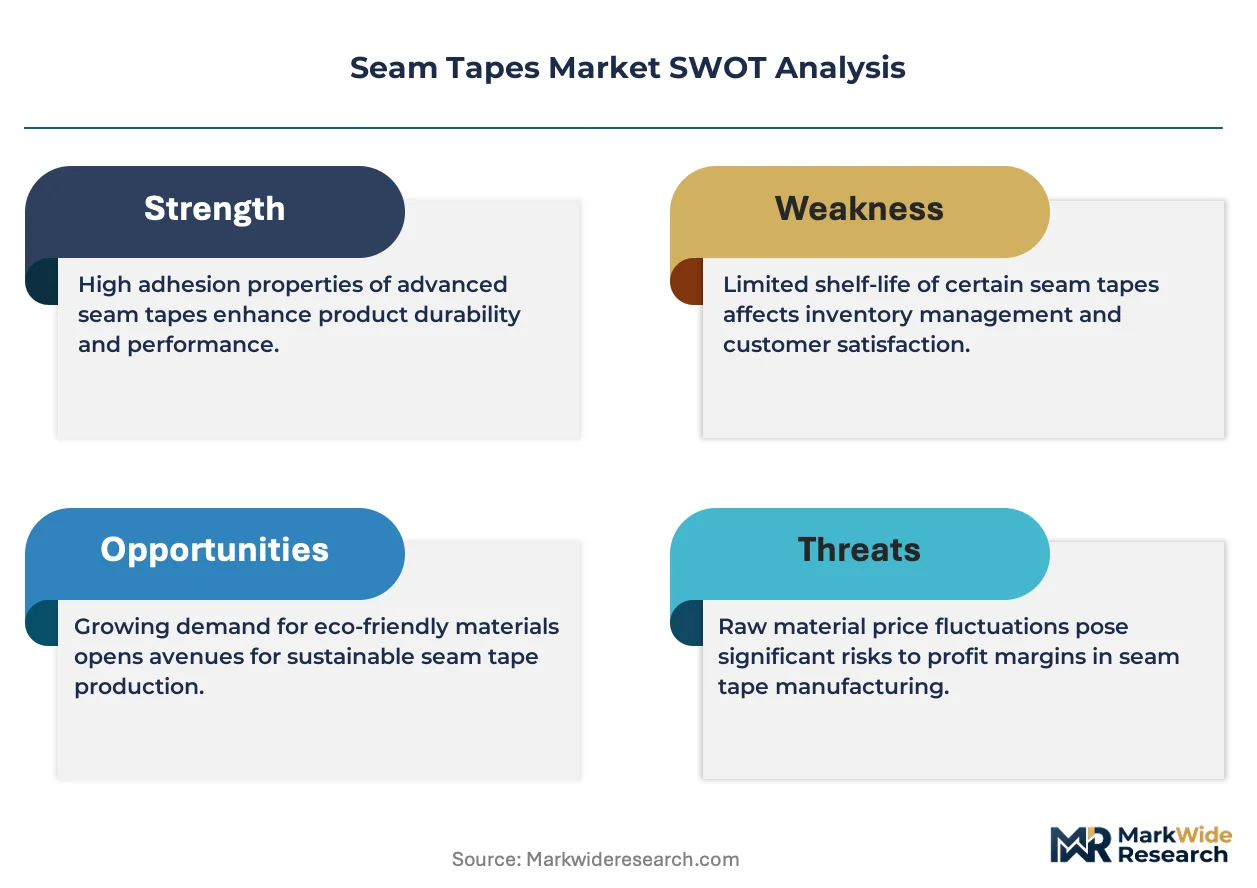
PFAS phase-out mandates across North America and Europe are forcing wholesale adhesive chemistry transitions, collapsing established supplier qualification timelines and redistributing competitive advantage toward polymer science specialists with solvent-free polyurethane platforms already validated.
Growth Catalysts
- REACH chemical restrictions:ECHA enforcement against solvent-based adhesives accelerates water-based polyurethane tape adoption across European technical apparel supply chains, compressing certification cycles for compliant suppliers.
- Outdoor apparel waterproofing mandates:Expedition-grade brands now require seam sealing on mid-market product lines, expanding addressable tape volume beyond historical performance-tier boundaries.
- Vietnam textile manufacturing concentration:Export-oriented garment hubs in Ho Chi Minh City and Hanoi generate concentrated demand for high-throughput tape application systems serving North American and European brand compliance requirements.
Market Restraints
- Polyol feedstock volatility:Crude-linked polyurethane raw material costs swing tape gross margins unpredictably, compressing profitability for formulation specialists without backward integration into petrochemical supply.
- Chinese supply concentration:DingZing and regional competitors control mid-tier polyurethane tape capacity, creating geographic single-source risk for brands seeking dual-qualified suppliers.
- Fluorocarbon-free performance gap:PFAS-restricted alternatives currently deliver inferior wash durability versus legacy chemistries, limiting adoption in military and first-responder gear where field reliability is non-negotiable.
Strategic Opportunities
- Automotive interior panel bonding:Double-sided tape applications in electric vehicle cabin assembly expand beyond traditional apparel end-uses, opening industrial volume scales with different margin structures.
- India technical textile manufacturing:PLI scheme incentives for synthetic fabric production in Tamil Nadu and Gujarat create nascent demand for seam sealing infrastructure serving domestic and export markets.
- ISO 14001 environmental certification:Brand procurement teams increasingly mandate verified sustainable manufacturing processes, creating preference premiums for suppliers with validated lifecycle credentials.
Industry Challenges
- Adhesive formulation chemist scarcity:Deep expertise in thermoplastic polyurethane rheology and substrate bonding physics concentrates at a handful of polymer science programs, constraining R&D team scaling.
- Multi-jurisdiction certification complexity:Simultaneous compliance with EPA PFAS guidance, ECHA REACH restrictions, and China's GB textile safety standards extends product launch timelines and fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seam Tapes Market |
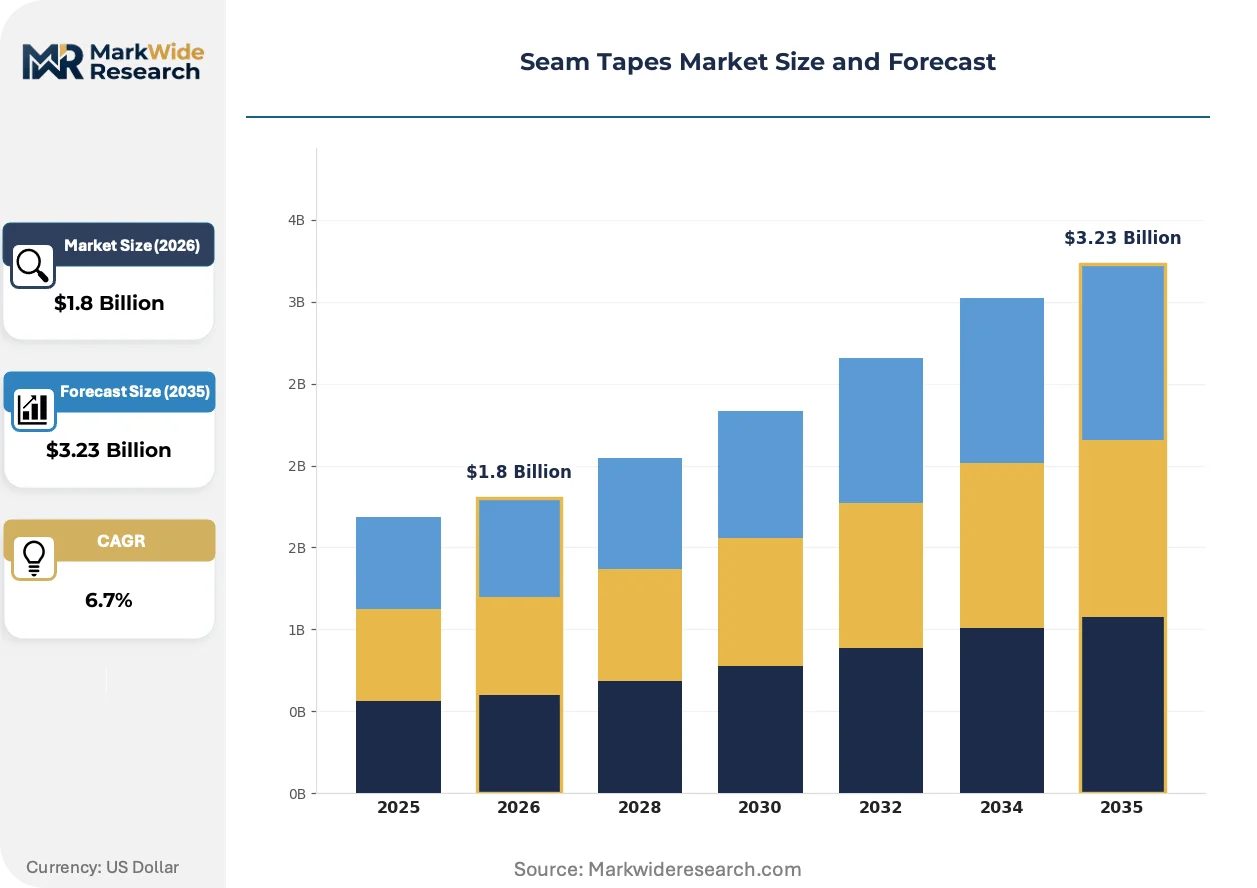
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tape, Double-Sided Tape, Fabric Tape, PVC Tape Application: Apparel, Footwear, Industrial, Automotive Material: Polyethylene, Polyester, Nylon, Polyurethane End User: Manufacturers, Retailers, Contractors, Consumers |
| Companies Covered | Bemis Associates Inc., Toray Industries Inc., HiMEL Corp., Sealon Co. Ltd., Essentra PLC, Gerlinger Industries, Adhesive Films, Inc., Loxy AS., DingZing Advanced Material Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seam Tapes Market Emerging Trajectories
Active chemistry transitions, application automation, and procurement model compression are simultaneously reshaping how seam tape suppliers compete on performance validation, manufacturing scale, and customer technical service.
Hot-melt reactive polyurethane adhesive technology is fragmenting established tape application methodologies by enabling inline bonding at lower activation temperatures, reducing thermal damage risk on delicate membrane laminates. Ski and alpine apparel manufacturers in Austria and Switzerland are piloting these systems to maintain waterproof breathability ratings through repeated wash cycles. The technology is fragmenting competitive positioning between thermal-bonding equipment suppliers and adhesive formulators, as equipment-agnostic chemistries reduce switching costs.
EPA PFAS guidance under the Toxic Substances Control Act is accelerating fluorocarbon-free adhesive development timelines, forcing reformulation of legacy seam sealants across outdoor apparel supply chains serving North American retailers. Industrial consequence includes accelerated qualification testing costs and temporary performance trade-offs in wash durability. Military and firefighter gear segments are most affected, responding with extended field-testing protocols before specification changes.
Direct technical collaboration between tape suppliers and membrane manufacturers is displacing arm's-length component procurement, as brands demand pre-validated laminate-to-tape systems rather than discrete material sourcing. Toray Industries and comparable polymer science specialists now embed application engineers at customer technical centers in Japan and Germany. This pattern is most visible in expedition-grade outerwear verticals where failure liability concentrates with finished goods brands.
Seam Tapes Market Segmentation
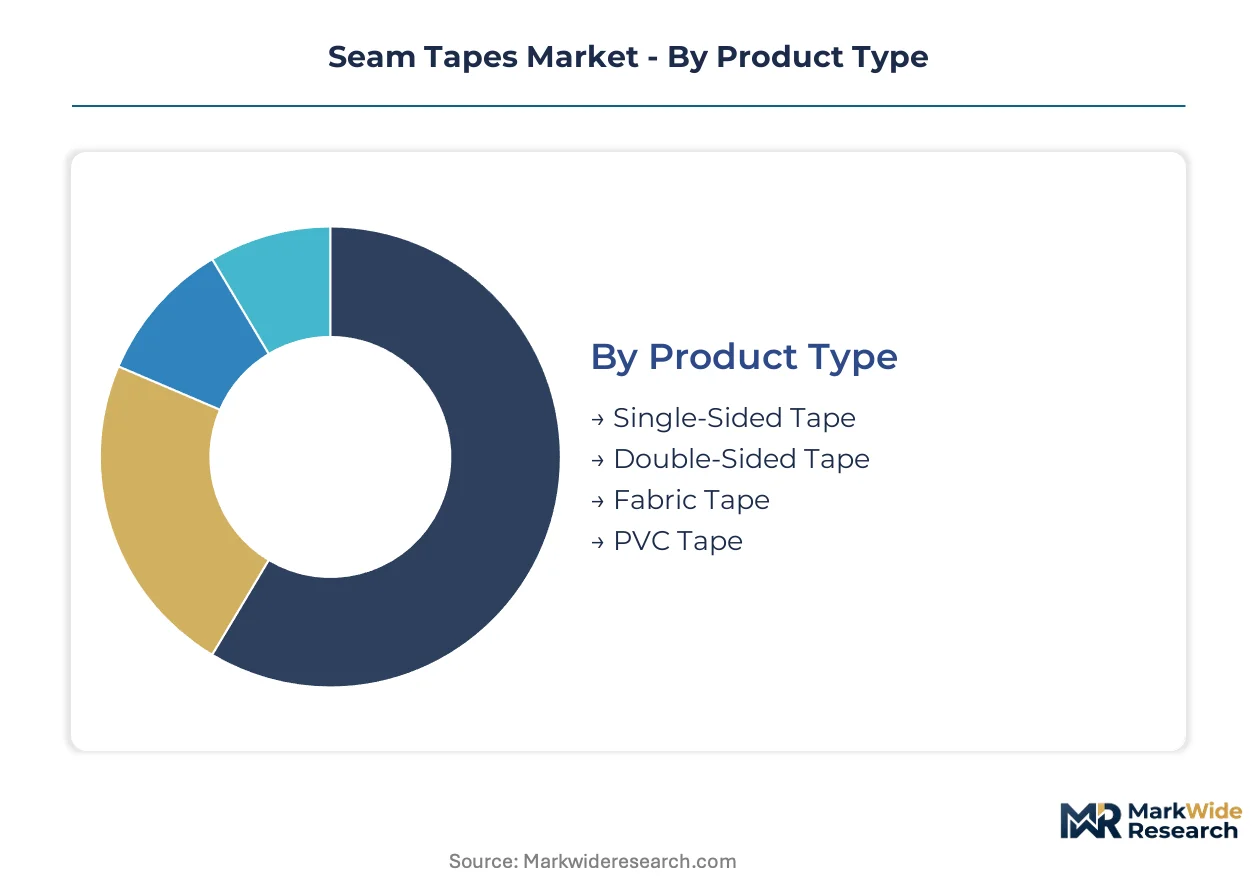
Seam tape specification varies sharply by end-use performance requirements and regulatory exposure. Material chemistry and application method determine which segments serve export-led technical apparel versus domestic industrial markets.
Product Type:
Single-sided tape dominates Asian export garment manufacturing serving European and North American brands, while double-sided variants concentrate in domestic automotive assembly operations across Germany, Japan, and the United States.
- Single-Sided Tape:Thermoplastic adhesive applied to one substrate surface, typically 15-25 mm width, activated at 120-150°C for two-layer textile constructions. Vietnamese and Bangladeshi garment exporters serving REI and Patagonia compliance requirements consume the highest volumes, though PFAS transition costs compress margins for water-based polyurethane formulations.
- Double-Sided Tape:Adhesive coating on both faces enables panel-to-panel bonding without stitching, critical for automotive interior assembly and membrane-to-membrane sealing in expedition tents. Tesla and BYD electric vehicle programs in California and Shenzhen are expanding specification beyond traditional apparel boundaries.
- Fabric Tape:Reinforced woven or nonwoven carrier substrates bonded with thermoplastic adhesive, specified where mechanical stress exceeds film tape limits. German firefighter gear manufacturers and Japanese alpine rescue equipment suppliers mandate this grade for field reliability.
- PVC Tape:Legacy chlorinated formulation retained in cost-sensitive industrial protective gear where elasticity requirements are minimal. Chinese domestic construction and mining safety equipment represents residual demand as REACH and state-level restrictions phase out vinyl chloride chemistries.
Single-sided tape holds the largest share; momentum sits with double-sided tape as automotive interior bonding specifications proliferate.
Application:
Cost tier stratification separates premium-positioned expedition apparel from economy-grade industrial protective equipment, with automotive applications commanding intermediate pricing through volume scale.
- Apparel:Waterproof seam sealing for laminated outerwear across performance tiers, from Arc'teryx expedition shells to Uniqlo blocktech casual rainwear. Austrian and Swiss alpine brands pilot hot-melt reactive systems to preserve membrane breathability ratings through wash cycles.
- Footwear:Boot and shoe upper sealing where stitched seams meet waterproof membrane booties. Italian and Portuguese luxury leather footwear manufacturers specify polyurethane tapes compatible with chrome-tanned substrates.
- Industrial:Chemical protective suits, hazmat enclosures, and cleanroom garments where seam integrity determines safety certification. US OSHA and EU PPE Directive compliance drive specification toward validated suppliers with ISO 9001 quality systems.
- Automotive:Interior panel bonding, headliner assembly, and NVH reduction applications expanding beyond traditional textile end-uses. German OEMs in Stuttgart and Munich specify tapes meeting VDA 275 fogging standards for cabin air quality.
Apparel generates the highest absolute volume; automotive applications are climbing the fastest as electric vehicle platform architectures multiply bonding points per vehicle.
Material:
Supply concentration for polyol feedstocks in Northeast China and the US Gulf Coast shapes regional cost structures and formulation availability for tape manufacturers.
- Polyurethane:Thermoplastic elastomer delivering superior elasticity and low-temperature flexibility for stretch garments and alpine equipment. DingZing Advanced Material and comparable Asian formulators compete on polyurethane breadth across Ho Chi Minh City and Dhaka manufacturing hubs.
- Polyethylene:Lower-cost olefin formulation dominating industrial protective gear and disposable medical applications where wash durability is secondary to initial cost. Saudi Aramco and SABIC feedstock integration advantages concentrate supply in Middle Eastern and Asian production.
- Polyester:Saturated polymer with hydrolysis resistance for high-humidity environments and marine applications. Japanese and South Korean suppliers leverage PTA and MEG backward integration for cost-competitive specialty grades.
- Nylon:Polyamide carrier substrates and adhesive modifiers for high-tensile applications in military load-bearing equipment and firefighter gear. Invista and Ascend Performance Materials control caprolactam supply for North American and European tape specialists.
Polyurethane holds the largest share; polyethylene is gaining share fastest as industrial protective equipment volumes expand in India and Southeast Asia.
End User:
Customer type determines technical service intensity, with manufacturers demanding application engineering support while retailers and contractors prioritize availability and price stability.
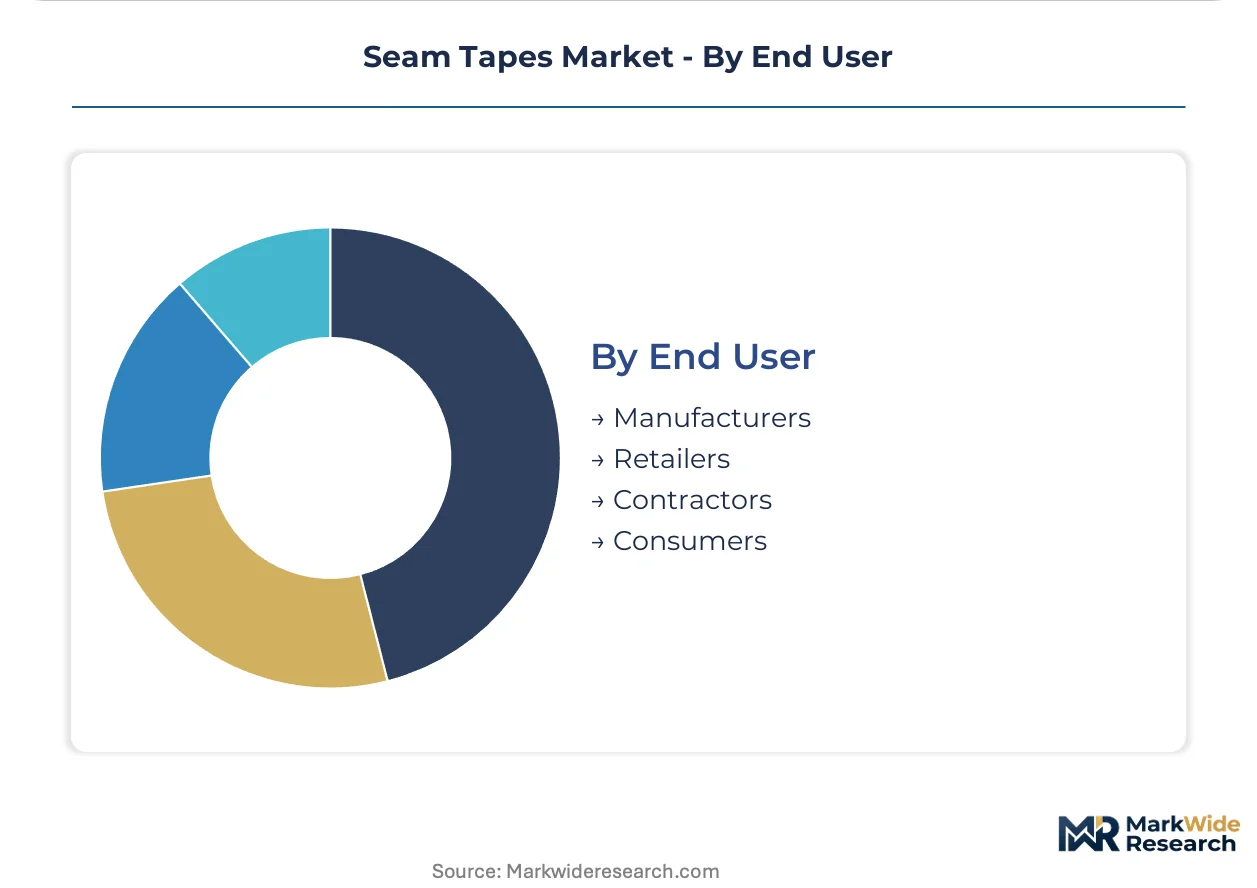
- Manufacturers:Technical apparel brands, automotive tier suppliers, and industrial equipment producers requiring validated laminate-to-tape systems. Direct collaboration with membrane suppliers like Toray Industries displaces arm's-length component procurement in expedition-grade verticals.
- Retailers:Outdoor specialty chains and mass-market sporting goods distributors sourcing private-label seam sealing services. REI, Decathlon, and comparable players specify compliance with restricted substance lists exceeding regulatory minimums.
- Contractors:Industrial laundries, repair services, and field maintenance operations applying tape for retrofit waterproofing and damage repair. Mining and oilfield services in Alberta and Western Australia represent concentrated demand for heavy-duty fabric tape.
- Consumers:DIY repair kits and aftermarket tent and garment sealing products, typically lower-specification grades sold through Amazon and outdoor specialty e-commerce. Performance claims face limited verification compared to B2B specifications.
Manufacturers hold the largest share; contractors are expanding most quickly as industrial equipment fleet maintenance cycles shorten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane tape manufacturing clusters in China, Vietnam, and Germany supply the bulk of export-oriented technical apparel demand. REACH enforcement in Europe and EPA PFAS guidance in North America are reshaping regional formulation requirements.
China
Export garment manufacturers in Guangdong and Zhejiang provinces drive single-sided tape consumption for North American and European brand compliance. SAMR enforces GB textile safety standards parallel to REACH requirements. DingZing Advanced Material anchors polyurethane formulation supply from manufacturing bases in Dongguan and Suzhou.
Vietnam
Ho Chi Minh City and Hanoi garment hubs generate concentrated demand for high-throughput tape application systems serving REI and Patagonia supply chains. The Ministry of Industry and Trade monitors chemical import regulations for adhesive raw materials. Binh Duong province hosts expanding technical textile finishing capacity requiring seam sealing infrastructure.
Germany
Automotive interior panel bonding specifications from Stuttgart and Munich OEMs expand double-sided tape applications beyond apparel. ECHA REACH restrictions accelerate water-based polyurethane adoption across European supply chains. Bavarian and Baden-Württemberg industrial clusters concentrate membrane-to-tape integration expertise.
United States
EPA PFAS guidance under the Toxic Substances Control Act forces fluorocarbon-free adhesive transitions across outdoor apparel brands. OSHA compliance requirements drive specification toward validated suppliers in industrial protective equipment. Pacific Northwest and Colorado outdoor apparel design centers demand pre-validated laminate-to-tape systems.
India
PLI scheme incentives for synthetic fabric production in Tamil Nadu and Gujarat create nascent seam sealing demand for domestic and export markets. BIS certification requirements align with EU and North American restricted substance lists. Surat and Tiruppur textile clusters are integrating waterproof breathable membrane laminates.
Seam Tapes Market Vendor Landscape
Concentration sits with polymer science specialists controlling membrane-to-tape integration and vertically integrated thermal-bonding operators. The market structures around three archetypes: multinational chemical conglomerates with backward integration into petrochemical feedstocks, regional formulation specialists competing on polyurethane breadth, and application equipment suppliers capturing value through system integration. Dominant competitive moves include direct technical collaboration with membrane manufacturers and geographic expansion into Vietnamese and Indian manufacturing hubs.
Among Japanese polymer science conglomerates, Toray Industries Inc. exemplifies the integrated membrane-to-tape archetype through captive materials science capabilities. Bemis Associates Inc. represents North American vertically controlled thermal-bonding operations. DingZing Advanced Material Inc. anchors the Asian formulation specialist tier competing on polyurethane platform breadth across Ho Chi Minh City and Dhaka supply chains.
| Leading Market Players |
|---|
| Bemis Associates Inc. |
| Toray Industries Inc. |
| HiMEL Corp. |
| Sealon Co. Ltd. |
| Essentra PLC |
| Gerlinger Industries |
| Adhesive Films, Inc. |
| Loxy AS. |
| DingZing Advanced Material Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between polyurethane tape formulators and Vietnamese garment exporters lock in both polyol feedstock access and eighteen-month price visibility against crude-linked volatility. These arrangements concentrate margin protection among suppliers with captive petrochemical relationships while forcing spot-market buyers into quarterly repricing cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates expedition-grade membrane-to-tape systems from industrial protective gear and disposable medical applications. Price differentiation rests on certification grade—ISO 9001-validated suppliers command fifteen to twenty percent premiums over uncertified competitors—and volume scale, with automotive OEMs extracting steeper discounts than apparel brands. Cost compression in mid-tier polyurethane formulations is intensifying because REACH-compliant water-based adhesive R&D expenses are not yet amortized across production volumes. Industrial laundries and field maintenance contractors exhibit the highest price sensitivity, while Arc'teryx-tier expedition brands prioritize field reliability over unit cost.
Supply Chain Analysis
China, Vietnam, and Germany anchor global seam tape manufacturing, with Dongguan and Suzhou housing DingZing's polyurethane formulation capacity, Ho Chi Minh City concentrating high-throughput garment application systems, and Bavarian industrial clusters specializing in membrane-to-tape integration. Raw material dependencies draw from Saudi Aramco and SABIC for polyethylene feedstocks, Northeast Chinese polyol producers for thermoplastic polyurethane precursors, and Invista's caprolactam supply for nylon carrier substrates. Single-source vulnerability concentrates in Chinese mid-tier polyurethane capacity, where regional competitors control export-oriented volume. Distribution runs through technical textile manufacturing clusters in Bangladesh, Tamil Nadu, and Portugal, with finished tape reaching end-users via membrane laminators and automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seam tape demand is accelerating through a regulatory inflection—PFAS phase-out mandates across North America and Europe are collapsing established supplier qualification timelines and redistributing competitive advantage toward polymer science specialists with solvent-free platforms already validated.
For Market Incumbents: Secure backward integration into polyol feedstocks or captive petrochemical supply to defend margins against crude-linked volatility. Invest in ECHA REACH pre-certification for water-based polyurethane platforms before EPA PFAS guidance hardens into enforceable rulemaking, compressing qualification windows for laggards.
For New Entrants and Emerging Players: Application engineering services for Indian technical textile manufacturers represent the most penetrable white-space target, as PLI scheme incentives in Tamil Nadu and Gujarat outpace local seam sealing infrastructure. Pursue partnership models with Surat and Tiruppur membrane laminators lacking in-house tape application expertise.
For Investors and Strategic Acquirers: Regional formulation specialists with validated solvent-free polyurethane platforms and existing SAMR GB standard compliance offer the strongest acquisition thesis. Watch for EPA enforcement action timelines against fluorocarbon-containing adhesives as the inflection signal that revalues compliant supplier portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | DingZing and Asian competitors are adding water-based polyurethane lines to serve REACH-compliant European demand. |
| Backward Integration | Toray Industries leverages captive polymer science capabilities to control membrane-to-tape integration costs. |
| Green Manufacturing Transition | Fluorocarbon-free adhesive development pipelines accelerate as EPA PFAS guidance forces chemistry transitions. |
| Long-term Supply Agreement | Vietnamese garment exporters lock in tape supply through eighteen-month offtake contracts with polyol price collars. |
| Joint Venture | Automotive interior panel bonding specifications from Stuttgart OEMs drive partnerships between tape suppliers and EV platform engineers. |
Methodological Framework
Desk research of customs and trade flow databases, ECHA regulatory filings, and SEC 10-K disclosures preceded structured interviews with polyurethane formulation chemists, technical apparel procurement directors, automotive tier supplier quality engineers, and Vietnamese garment factory operations managers. Primary fieldwork combined plant visits to Dongguan and Ho Chi Minh City manufacturing clusters with remote sessions across European membrane laminators. Secondary validation drew from SAMR GB standard documentation, EPA PFAS guidance dockets, and synthetic fabric production statistics. Bottom-up volume estimates triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Variance decomposition across product type, application, material chemistry, and end-user category shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling applied to baseline volume data. Industry-specific forecast inputs included polyol price elasticity coefficients and regulatory compliance cost pass-through assumptions for REACH and EPA PFAS transitions.
Underlying assumptions cover sustained PFAS phase-out enforcement, polyol feedstock price correlation with crude benchmarks, and Vietnamese textile export growth, with deviation risk concentrated in regulatory timeline delays and alternative adhesive performance gaps. Recalibration cycles align with material shifts in EPA rulemaking, ECHA enforcement patterns, and Indian PLI scheme implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Twist Tube Market
Tapes
Tape Applicator Machines Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Galley Tapes Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Washi Tapes Market
Tapes
PVC Tapes Market
Tapes
Removal Strips Market
Tapes
Pucker Free Tapes Market
Tapes
Paper Gummed Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Smart Card Tapes Market
Tapes
Global Electrical Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Tissue Tapes Market