
 Shrink - Sleeve Wrapping Machinery Market | 2026-2036
Shrink - Sleeve Wrapping Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink - Sleeve Wrapping Machinery Market Analytics
Remote diagnostics and predictive maintenance subscriptions is shifting how shrink-sleeve wrapping machinery vendors capture lifetime value. Polypack leverages its installed base to sell uptime guarantees rather than standalone hardware. Texwrap Packaging anchors its North American presence through specialized service contracts that lock in multi-year relationships.
Shrink-sleeve wrapping machinery applies heat-shrinkable polymer film around products using a combination of sleeve applicators, heat tunnels, and conveyor systems operating at temperatures between 150°C and 300°C depending on film substrate; the equipment serves primarily to secure multi-packs, protect surfaces, and enable 360-degree branding. Automatic equipment dominates volume shipments as beverage producers pursue throughput rates exceeding 600 bottles per minute, while semi-automatic units retain margin pools in craft distillery and regional dairy operations where batch flexibility outweighs speed. PETG film compatibility commands premium positioning as brands demand clarity and recyclability, though polyethylene remains the workhorse material for cost-sensitive food packaging lines.
FDA regulations on indirect food contact materials constrain tunnel construction and airflow design for machinery serving US food packaging customers. EMA and REACH compliance in Europe compels manufacturers to certify film handling components for chemical safety and thermal emission thresholds. Stakeholders must weigh retrofit compatibility against full-line replacement as sustainability mandates tighten and energy recovery systems become standard specification rather than optional upgrade.
Market Dynamics
Beverage bottlers converting from traditional labeling to full-body sleeve formats are compressing equipment replacement cycles and forcing tunnel redesigns for lower-emission heat systems under tightening environmental mandates.
Growth Catalysts
- EU F-Gas Regulation:Equipment makers must redesign heat tunnel systems for lower emissions, accelerating replacement demand across European bottling lines.
- PETG film compatibility:Brands demanding clarity and recyclability specifications pull premium machinery upgrades across cosmetics and premium beverage segments.
- German precision engineering clusters:Turnkey line suppliers concentrated in Stuttgart and Munich regions capture cross-border demand from French and Italian bottlers.
Market Restraints
- Fluorinated gas input costs:Heat tunnel refrigerant prices fluctuate with phasedown schedules under Montreal Protocol amendments, squeezing margin on mid-range equipment.
- Supply concentration in Baden-Württemberg:Precision servo motor and control system suppliers cluster in southern Germany, creating single-source vulnerability for non-European OEMs.
- Polyethylene film technical ceiling:Lower clarity and recyclability certification barriers constrain cost-sensitive food packaging lines from accessing premium brand contracts.
Strategic Opportunities
- India craft distillery segment:Semi-automatic units retain margin pools where batch flexibility outweighs speed, with FSSAI labeling mandates driving first-time equipment purchases.
- Remote diagnostics convergence:IoT sensor networks and predictive analytics platforms unlock multi-year service contracts and uptime guarantee revenue streams.
- CSRD disclosure requirements:European corporates must report packaging machinery energy intensity, creating specification pull for heat recovery systems as standard rather than upgrade.
Industry Challenges
- Heat tunnel airflow certification:FDA indirect food contact material approvals and EMA thermal emission thresholds impose 14-18 month validation timelines for new tunnel designs.
- Legacy line integration:Retrofit compatibility with existing conveyor geometries and control architectures fragments engineering resource allocation across custom projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink - Sleeve Wrapping Machinery Market |
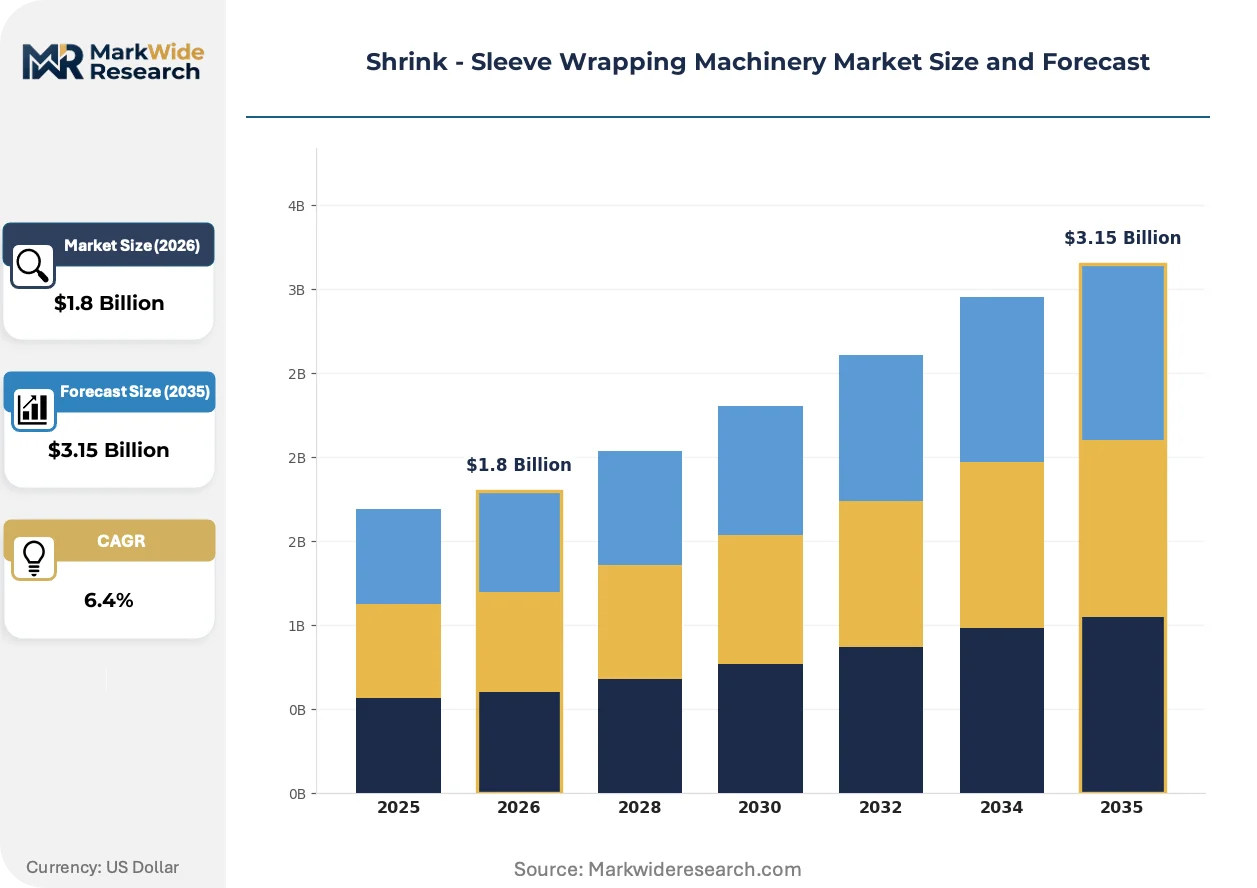
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Automatic, Semi-Automatic, Manual, Handheld Application: Beverages, Food Packaging, Pharmaceuticals, Personal Care Material: Polyethylene, Polypropylene, PVC, PETG End User: Manufacturers, Distributors, Retailers, E-commerce |
| Companies Covered | Polypack, Texwrap Packaging, ARPAC LLC, Axon, Duravant, Eastey Enterprises, Kliklok-Woodman, Massman Automation Designs, PDC International Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink - Sleeve Wrapping Machinery Market Evolving Landscape
Equipment vendors are capturing lifetime value through service-layer monetization rather than hardware margins alone, with thermal efficiency and connectivity becoming the primary axes of product differentiation.
Infrared pre-heating modules are absorbing energy management functions previously handled by conventional convection tunnels, enabling beverage producers to cut gas consumption by half while maintaining throughput above 600 bottles per minute. PETG-compatible systems with ceramic emitter arrays command premium positioning as sustainability audits intensify across European retail supply chains.
REACH chemical safety certification now governs film handling component materials across all machinery serving EU customers, compelling manufacturers to substitute legacy coatings and bearing lubricants with approved alternatives. The regulation's downstream pressure falls heaviest on mid-tier OEMs without in-house compliance laboratories, accelerating consolidation toward vertically integrated suppliers with captive testing facilities.
Service contract unbundling is separating hardware procurement from uptime guarantees, with bottlers in North America and Western Europe demanding outcome-based agreements that penalize vendors for unplanned downtime. Polypack and Texwrap Packaging anchor regional presence through specialized multi-year relationships, while smaller competitors struggle to underwrite performance risk without installed base scale.
Shrink - Sleeve Wrapping Machinery Market Segmentation
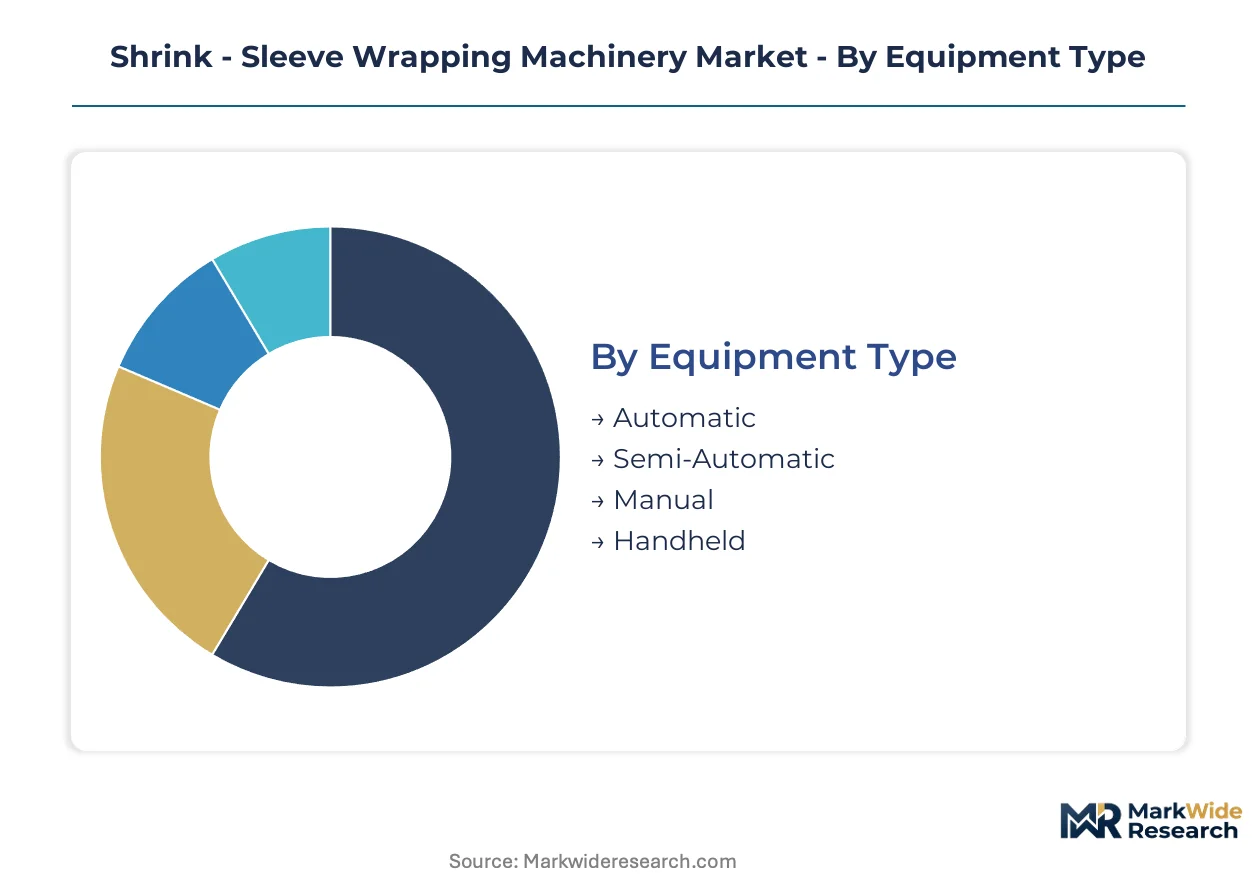
Equipment specification, throughput requirements, and film substrate compatibility create distinct purchasing cohorts across the shrink-sleeve wrapping machinery landscape. Buyers segment sharply between high-speed beverage bottlers demanding 600+ bottles per minute and craft operators prioritizing batch flexibility over velocity.
Equipment Type:
Throughput mandates and labor cost structures differentiate buyers most sharply in this category.
- Automatic:Conveyor-fed systems integrate sleeve applicators, heat tunnels, and control architectures for continuous operation at 150°C to 300°C. Beverage bottlers in Germany and France specify these for lines exceeding 600 bottles per minute under EU F-Gas Regulation compliance deadlines.
- Semi-Automatic:Batch-fed configurations allow manual loading with automated sleeve placement and tunnel shrink. Craft distilleries in India and regional dairies in Italy select these where product changeovers outpace the economics of full automation.
- Manual:Operator-dependent sleeve application without conveyor integration serves micro-producers and pilot lines.
- Handheld:Portable heat guns and sleeve dispensers handle irregular geometries and short runs.
Automatic equipment leads volumes today; semi-automatic configurations are gaining share fastest among emerging craft segments.
Application:
Regulatory exposure and branding surface area determine machinery specification intensity.
- Beverages:Multi-pack collation and 360-degree label replacement dominate throughput requirements. Bottlers converting from traditional labeling to full-body sleeves compress replacement cycles and force tunnel redesigns for lower-emission heat systems.
- Food Packaging:FDA indirect food contact material approvals constrain tunnel construction and airflow design. Polyethylene film compatibility remains standard for cost-sensitive lines despite recyclability certification barriers.
- Pharmaceuticals:EMA thermal emission thresholds and tamper-evidence requirements govern equipment selection.
- Personal Care:PETG film clarity specifications pull premium machinery upgrades for shelf differentiation.
Beverage applications anchor installed base scale; personal care represents the steepest expansion trajectory as cosmetics brands pursue 360-degree branding.
Material:
Recyclability certification and optical clarity stratify machinery compatibility tiers.
- PETG:Glycol-modified polyester delivers glass-like transparency and established recycling streams. Premium beverage and cosmetics brands in Germany and France specify PETG-compatible systems with ceramic emitter arrays.
- Polyethylene:Cost-dominant workhorse for food packaging lines with lower clarity tolerance.
- Polypropylene:Higher shrink force suits multi-pack geometries with irregular contours.
- PVC:Declining share under REACH chemical safety pressure and retail sustainability audits.
Polyethylene dominates shipment volumes; PETG is climbing the fastest as CSRD disclosure requirements intensify across European supply chains.
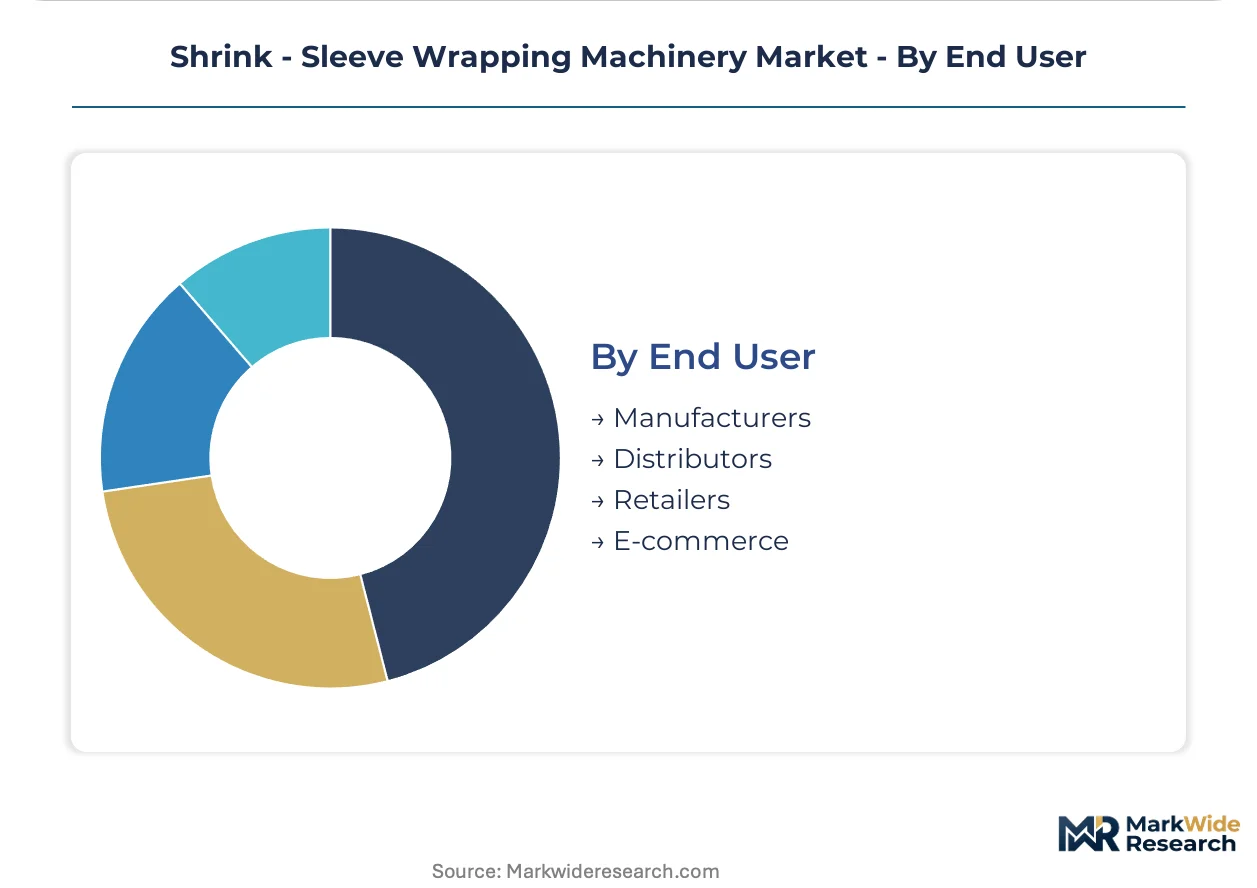
End User:
Capital deployment models and service contract appetite distinguish procurement behavior.
- Manufacturers:Direct equipment ownership with in-house maintenance capability. Large beverage producers in Germany pursue outcome-based agreements penalizing vendors for unplanned downtime.
- Distributors:Equipment-as-a-service arrangements for co-packing and seasonal demand spikes.
- Retailers:Private-label packaging lines with standardized film specifications.
- E-commerce:Protective wrap requirements for multi-unit fulfillment with variable pack sizes.
Manufacturers retain the largest installed base; e-commerce channels are expanding most quickly as fulfillment complexity multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as equipment makers seek lower compliance costs outside the EU's tightening F-Gas framework, while precision engineering clusters in southern Germany retain design authority despite manufacturing migration.
Germany
Beverage bottlers in Stuttgart and Munich regions compress replacement cycles for heat tunnel systems under EU F-Gas Regulation deadlines. EMA thermal emission thresholds govern pharmaceutical-grade machinery specifications. Baden-Württemberg's precision servo motor suppliers anchor turnkey line exports to French and Italian bottlers.
United States
Craft distillery and regional dairy operations sustain semi-automatic equipment demand where batch flexibility outweighs speed. FDA indirect food contact material approvals constrain tunnel construction for food packaging customers. Chicago-area OEMs specialize in retrofit compatibility engineering for legacy conveyor geometries.
India
FSSAI labeling mandates drive first-time equipment purchases among craft distilleries adopting shrink-sleeve formats. The country's national food safety regulator enforces packaging material traceability standards. Maharashtra's industrial corridors host emerging fabrication capacity serving domestic beverage brands.
France
Cosmetics brands pursuing 360-degree branding pull premium PETG-compatible machinery upgrades. ANSM chemical safety requirements align with REACH certification for film handling components. Lyon-area packaging engineering consultancies bridge specification gaps between retail brand requirements and equipment capabilities.
Italy
Regional dairy cooperatives retain semi-automatic configurations for seasonal product changeovers. The national industrial standards body enforces CE marking conformity for heat tunnel exports. Emilia-Romagna's food processing machinery cluster supplies shrink-sleeve integration for Parmigiano-Reggiano and wine co-packing lines.
Shrink - Sleeve Wrapping Machinery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with turnkey solution providers commanding premium positioning in high-throughput beverage applications while regional fabricators capture replacement parts and retrofit services. The vendor landscape organizes around three archetypes: German precision engineering houses with captive testing facilities, North American service-contract specialists monetizing installed base scale, and Asian fabricators competing on delivery speed for standardized configurations. Consolidation pressure falls heaviest on mid-tier OEMs lacking in-house compliance laboratories, driving acquisition activity toward vertically integrated suppliers with REACH certification capabilities.
Among North American service-contract specialists, Polypack and Texwrap Packaging exemplify the shift toward uptime-guarantee revenue models rather than standalone hardware margins. Polypack leverages its installed base to underwrite performance risk through multi-year agreements, while Texwrap Packaging anchors regional presence through specialized relationships locking in recurring service revenue. Both occupy positions where outcome-based contracting separates sustainable operators from competitors dependent on equipment sales alone.
| Leading Market Players |
|---|
| Polypack |
| Texwrap Packaging |
| ARPAC LLC |
| Axon |
| Duravant |
| Eastey Enterprises |
| Kliklok-Woodman |
| Massman Automation Designs |
| PDC International Corp |
| Others |
Value Network & Pricing Analysis
Fluorinated gas refrigerant costs cascade from Montreal Protocol phasedown schedules through heat tunnel manufacturing tiers, compressing margins on mid-range equipment while premium PETG-compatible systems with ceramic emitter arrays sustain pricing power through EMA thermal emission certification.
Pricing Analysis
Distributor margins absorb regulatory compliance burdens upstream, compressing channel economics for non-European OEMs lacking captive testing facilities. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked German turnkey lines from Asian fabricators competing on delivery speed. Price differentiation hinges on REACH certification grade and after-sales service bundling. Pricing pressure stems from F-Gas Regulation redesign costs, with craft distillery buyers in India exhibiting highest price sensitivity and German beverage bottlers least.
Supply Chain Analysis
Precision servo motor supply rests on Baden-Württemberg engineering clusters, with control system fabrication concentrated in Stuttgart and Munich regions. Ceramic emitter arrays draw from Japanese specialty thermal component producers, while heat-shrinkable polymer film feeds from South Korean and Chinese resin suppliers. Single-source vulnerability runs through southern Germany for non-European OEMs. Distribution runs through turnkey line integrators for high-throughput beverage applications and regional fabricators for retrofit services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where PETG film compatibility specifications and CSRD energy intensity disclosure mandates pull machinery upgrades toward premium tiers with embedded heat recovery systems.
For Market Incumbents: Acquire REACH certification laboratory capacity to underwrite compliance timelines that fragment mid-tier competitors. Capture Baden-Württemberg precision motor suppliers through upstream control arrangements, insulating against single-source exposure while EMA thermal emission thresholds extend validation cycles to 14-18 months. For New Entrants and Emerging Players: The price-point gap between premium German turnkey lines and standardized Asian configurations opens white-space at the mid-tier for FSSAI-compliant semi-automatic units serving India's craft distillery segment. Target Maharashtra's industrial corridors with localized fabrication partnerships, using remote diagnostics subscriptions as the go-to-market anchor for multi-year service relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier OEMs lack in-house compliance laboratories and cannot absorb 14-18 month EMA validation timelines. The 5-10 year viability window favors vertically integrated suppliers with captive testing facilities and installed base scale to underwrite outcome-based uptime guarantees. Watch F-Gas Regulation amendment schedules as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Servo Motors | Captive supply from Baden-Württemberg clusters insulates against single-source vulnerability for non-European OEMs. |
| REACH Certification Laboratory Investment | In-house testing facilities compress EMA validation timelines and accelerate pharmaceutical-grade machinery approvals. |
| Remote Diagnostics Platform Launch | IoT sensor networks unlock multi-year service contracts and uptime guarantee revenue streams beyond hardware margins. |
| Ceramic Emitter Array Partnership | Japanese thermal component alliances secure PETG-compatible system supply for European sustainability audit compliance. |
| India Manufacturing Footprint Establishment | Maharashtra fabrication capacity addresses FSSAI labeling mandate demand without EU F-Gas compliance cost burdens. |
Research Methodology
Multiple input streams — plant engineers at beverage bottling facilities, OEM procurement teams, aftermarket service heads, and regulatory affairs leads at machinery manufacturers — were reconciled against customs records, EU F-Gas Regulation filings, SEC equipment supplier disclosures, and trade association shipment data. Bottom-up equipment unit economics were triangulated with top-down market sizing across automatic, semi-automatic, manual, and handheld equipment categories.
Historical shipment trajectories were cross-referenced against panel input from maintenance directors and packaging engineering consultancies to model adoption curves across the projection horizon. Segmentation dimensions included equipment type, application intensity, film substrate compatibility, and end-user capital deployment model. CAGRs were derived from regression analysis of replacement cycle compression under environmental mandates, with F-Gas Regulation redesign deadlines and CSRD disclosure requirements as key forecast inputs.
Caveats apply where Montreal Protocol amendment schedules or REACH chemical safety scope expansions could materially shift the outlook for heat tunnel system specifications and validation timelines. A small set of named triggers — EMA thermal emission threshold revisions, FSSAI labeling mandate enforcement intensity, and ceramic emitter array supply disruptions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
High Vacuum Filling Machine Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market