
 Electrical Shielding Tape Market | 2026-2036
Electrical Shielding Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Shielding Tape Market Analysis
Asset-light leasing models for precision coating equipment is reconfiguring competitive entry barriers, allowing specialized converters to challenge integrated material suppliers without capital-heavy investments. Nitto Denko Corporation leverages its polymer synthesis capabilities to sustain captive supply of proprietary acrylic adhesives. 3M anchors North American demand through deep specification relationships with aerospace Tier-1 contractors. Holland Shielding Systems BV competes via electromagnetic compatibility testing bundled with tape supply, creating stickier customer workflows.
Electrical shielding tape comprises laminated or coated flexible substrates—typically copper, aluminum, or nickel-graphite composites with pressure-sensitive adhesive layers—engineered to attenuate electromagnetic interference across frequencies from kilohertz to gigahertz ranges. The primary purpose is isolating sensitive circuitry from external field coupling while preventing emission leakage from high-speed or high-power components. Conductive product variants command the widest specification footprint across automotive and aerospace applications, whereas metal foil configurations concentrate margin pools in defense and medical imaging segments where attenuation consistency requirements are most stringent. Thermal adhesive technology remains the default bonding method for power electronics modules, though self-adhesive formulations are gaining specification share in telecommunications enclosures where reworkability matters.
FCC Part 15 emission limits in the United States, EU Electromagnetic Compatibility Directive 2014/30/EU, and China's GB/T 9254 standard collectively tighten shielding effectiveness thresholds, forcing tape suppliers to validate products against cascading test protocols. ECHA substance-of-very-high-concern listings are additionally restricting legacy flame-retardant additives, pushing reformulation cycles toward phosphorus-nitrogen synergists. Stakeholders must monitor how automotive OEMs integrate shielding tape specifications into platform-level electromagnetic architecture decisions rather than treating them as commodity procurement afterthoughts.
Market Dynamics
High-voltage EV architectures are multiplying electromagnetic interference nodes faster than legacy shielding specifications can accommodate, forcing tape suppliers to co-develop platform-level electromagnetic architectures with automotive OEMs rather than compete as commodity vendors.
Growth Catalysts
- REACH substance restrictions:ECHA listings on legacy flame retardants are redirecting European formulation strategies toward phosphorus-nitrogen synergists, opening specification windows for compliant adhesive platforms.
- EV power electronics:Automotive manufacturers are expanding procurement of conductive shielding materials as battery management systems and inverters multiply shielding points per vehicle.
- China cable assembly scale:Domestic electronics manufacturing capacity concentration is pulling regional demand for copper and aluminum foil tape configurations.
Market Restraints
- Copper price volatility:Primary metal input costs swing with commodity exchange fluctuations, compressing converter margins on fixed-price aerospace contracts.
- Adhesive supply concentration:Captive acrylic polymer production remains concentrated among integrated chemical groups, limiting independent converter backward integration options.
- Technical performance ceilings:Attenuation consistency above 40 GHz remains elusive for pressure-sensitive adhesive laminates, restricting specification in next-generation radar modules.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and component assembly are creating virgin demand for shielding materials in previously import-dependent supply chains.
- Medical imaging shielding:MRI gradient coil manufacturers are specifying nickel-graphite composite tapes for patient-accessible component isolation.
- Telecommunications reworkability:Self-adhesive formulations are gaining share in 5G small cell enclosures where field service access matters more than permanent bonding.
Industry Challenges
- Electromagnetic compatibility certification timelines:FCC Part 15 and EU Directive 2014/30/EU test protocol stacking extends product validation cycles by 8-14 months.
- Polymer synthesis talent scarcity:Formulation chemists with pressure-sensitive adhesive and conductive filler compounding expertise command premium compensation in tight labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Shielding Tape Market |
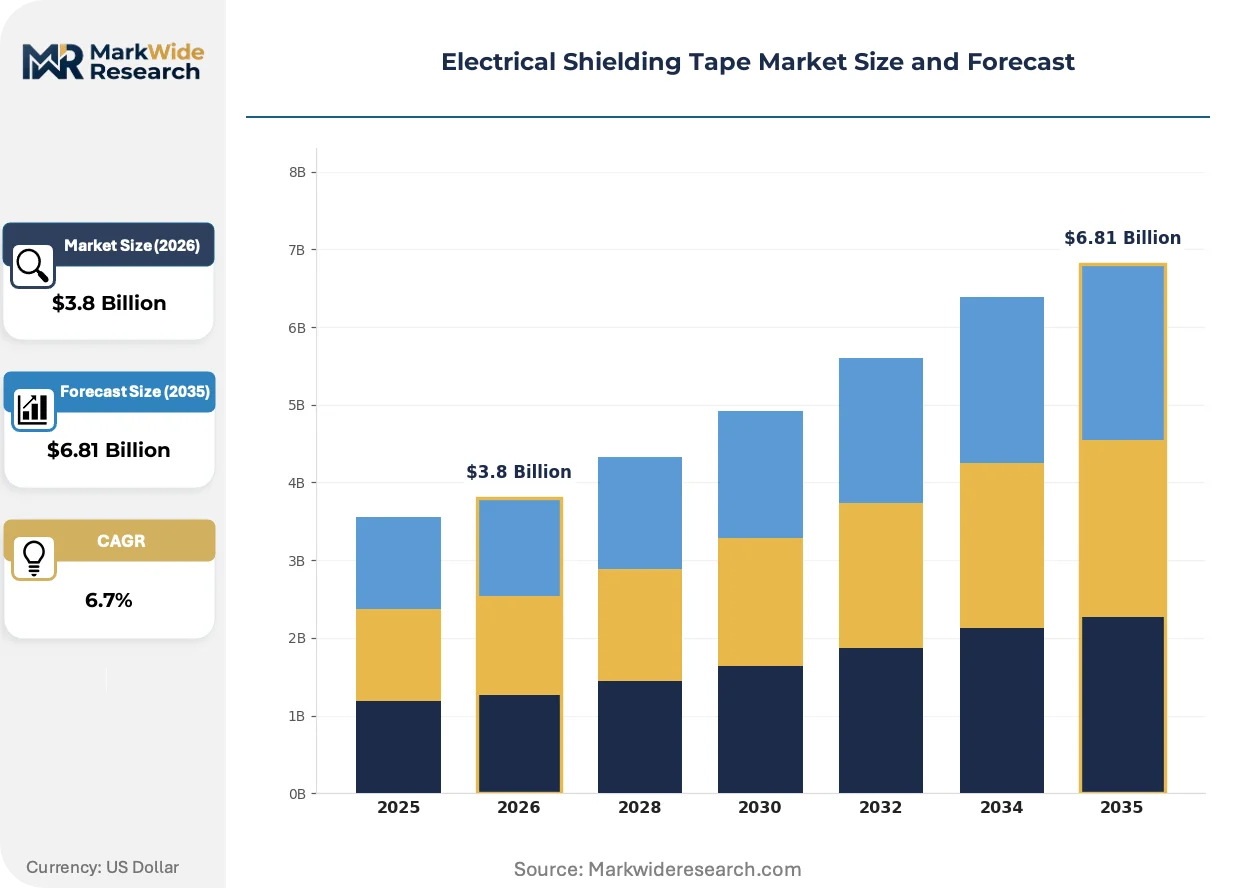
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive, Non-Conductive, Metal Foil, Fabric Application: Automotive Electronics, Telecommunications, Aerospace, Industrial Equipment Technology: Thermal Adhesive, Pressure Sensitive, Self-Adhesive, Laminated End User: Manufacturers, Contractors, DIY Enthusiasts, Electrical Engineers |
| Companies Covered | 3M, Nitto Denko Corporation, Avery Dennison Corporation, Scapa Group Ltd., Intertape Polymer Group, Shurtape Technologies, LLC, Advance Tapes International, Holland Shielding Systems BV, RTP Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Shielding Tape Market Emerging Trajectories
Shielding tape technology is bifurcating between ultra-thin flexible configurations for consumer electronics and thermally robust laminates for power modules, with digitization of manufacturing processes enabling mass customization at previously unattainable scale.
Printed conductive ink patterning is digitizing legacy die-cut tape workflows. Automotive Tier-1 suppliers are adopting inkjet-deposited silver-nanowire grids on polyimide substrates for antenna-integrated body panels. This approach is digitizing converter business models by collapsing tooling costs and enabling lot-size-one production economics previously reserved for prototyping.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon-free adhesive solvent choices. Industrial tape coaters are retrofitting drying lines to accommodate waterborne acrylic systems with equivalent peel adhesion. Medical device manufacturers in Germany and France are qualifying these reformulated products ahead of 2030 reduction mandates.
Specification bundling is displacing standalone product procurement. Aerospace contractors in the United States are awarding electromagnetic compatibility testing and tape supply as combined contracts, locking out pure-product competitors. This pattern concentrates in defense and satellite manufacturing clusters where attenuation documentation carries liability weight exceeding material cost considerations.
Electrical Shielding Tape Market Segmentation
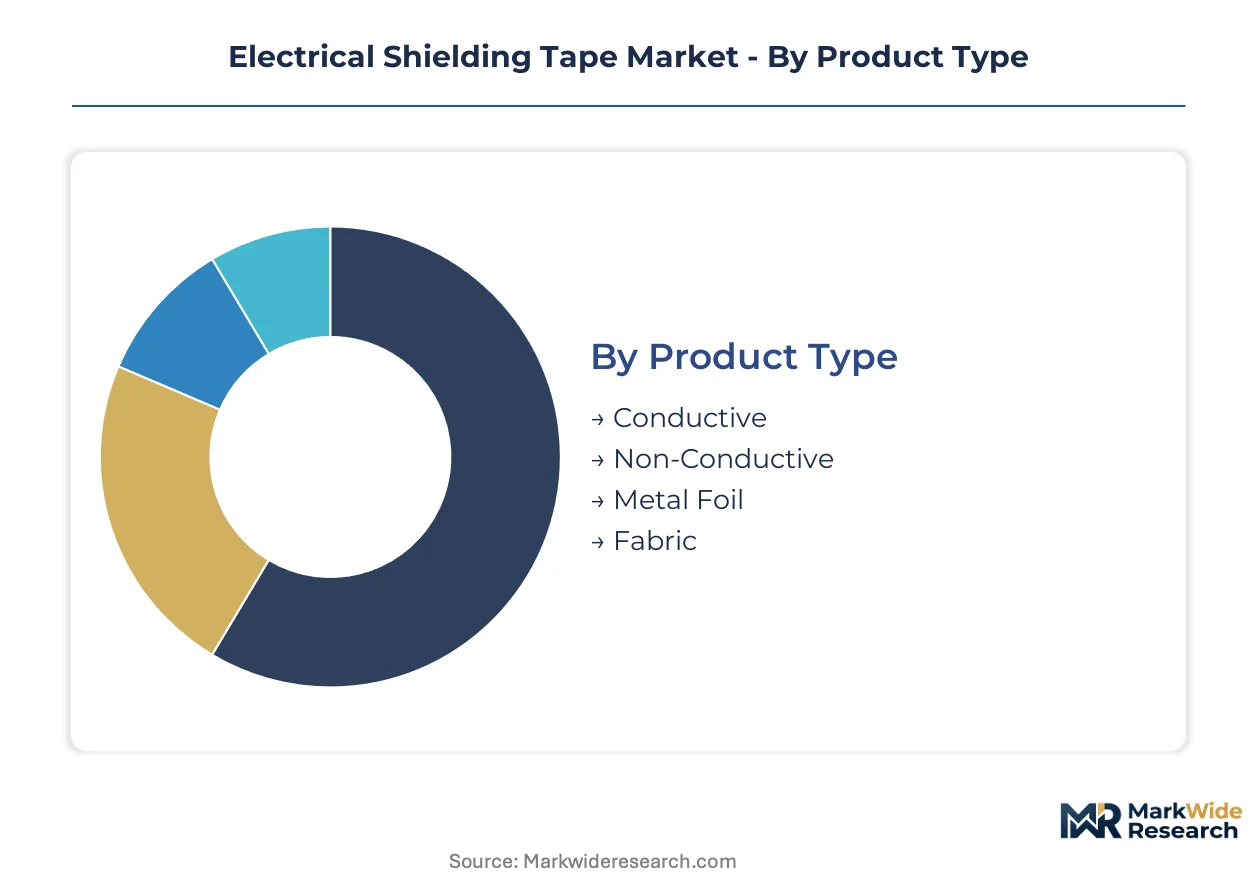
Electrical shielding tape specifications diverge sharply across voltage classes and frequency ranges, forcing suppliers to maintain parallel product architectures. Segmentation discipline separates commodity converters from specialists capable of co-development with automotive and aerospace OEMs.
Product Type:
Shielding effectiveness requirements span from kilohertz interference suppression in industrial motors to gigahertz attenuation in 5G antenna arrays, dictating substrate and filler selection.
- Conductive:Copper or silver-filled acrylic adhesives laminated to polyimide or polyester films deliver surface resistivity below 0.05 ohms per square. Automotive battery management system manufacturers in Germany and China are expanding procurement as 800V architectures multiply shielding nodes per vehicle.
- Metal Foil:Pure copper or aluminum foils with conductive pressure-sensitive adhesives provide the highest attenuation consistency across temperature extremes. Defense contractors and MRI equipment manufacturers specify these configurations where failure carries liability exposure exceeding material costs.
- Non-Conductive:Polymer substrates with dielectric properties isolate high-voltage nodes without electromagnetic attenuation functions. Grid infrastructure contractors deploy these for phase separation in switchgear assemblies.
- Fabric:Woven nickel-graphite or silver-plated nylon composites offer conformability for irregular geometries. Medical device manufacturers specify fabric tapes for patient-contacting components requiring flexibility.
The dominant share belongs to Conductive, while Metal Foil is closing the gap fastest.
Application:
End-use concentration determines margin structure, with aerospace and medical applications commanding specification premiums over automotive volume contracts.
- Automotive Electronics:EV power modules and inverter assemblies require thermal-adhesive shielding tapes rated to 150°C continuous operation. Tier-1 suppliers in Japan and South Korea are qualifying next-generation formulations for 800V platforms.
- Aerospace:Satellite and avionics applications demand traceable attenuation documentation across -65°C to 200°C operational windows. FCC Part 15 and EU Directive 2014/30/EU test protocol stacking extends validation cycles, locking in incumbent suppliers.
- Telecommunications:5G small cell enclosures favor self-adhesive formulations enabling field rework. Tower operators in India and Brazil prioritize installation speed over permanent bonding.
- Industrial Equipment:Motor drives and power converters specify cost-optimized copper foil configurations. Chinese domestic manufacturing scale is pulling regional demand concentration.
Aerospace captures the highest margin pool, though Automotive Electronics generates the steepest volume expansion trajectory.
Technology:
Bonding chemistry selection trades thermal performance against reworkability, with regulatory solvent restrictions forcing capital-intensive coating line retrofits.
- Thermal Adhesive:Epoxy or silicone-based systems cure under heat to form permanent bonds with thermal conductivity above 1.5 W/mK. Power electronics module assemblers specify these for junction temperature management.
- Pressure Sensitive:Acrylic or rubber-based tackified adhesives enable immediate bonding without cure cycles. REACH substance restrictions on legacy flame retardants are redirecting European formulation strategies toward phosphorus-nitrogen synergists.
- Self-Adhesive:Repositionable silicone formulations allow multiple attachment cycles. Telecommunications field service operations value reworkability over bond strength.
- Laminated:Multi-layer constructions combining conductive substrates with dielectric interlayers address complex shielding-grounding requirements. Aerospace contractors bundle these with electromagnetic compatibility testing services.
Thermal Adhesive maintains the largest installed base, while Pressure Sensitive formulations are gaining specification share fastest.
End User:
Procurement sophistication varies from engineered specifications to price-driven spot purchasing, fragmenting supplier engagement models.
- Manufacturers:OEMs and Tier-1 suppliers issue multi-year supply agreements with embedded electromagnetic compatibility validation requirements. Automotive and aerospace producers dominate this category.
- Contractors:Installation and maintenance firms purchase through distribution with technical support dependencies. Grid infrastructure and telecommunications deployment contractors concentrate demand.
- Electrical Engineers:Design-phase specification authority determines downstream procurement lock-in. Engineers in Germany and the United States increasingly integrate shielding architecture at platform level rather than component selection.
- DIY Enthusiasts:Consumer electronics repair and hobbyist applications drive small-format retail packaging. E-commerce channels capture this dispersed demand.
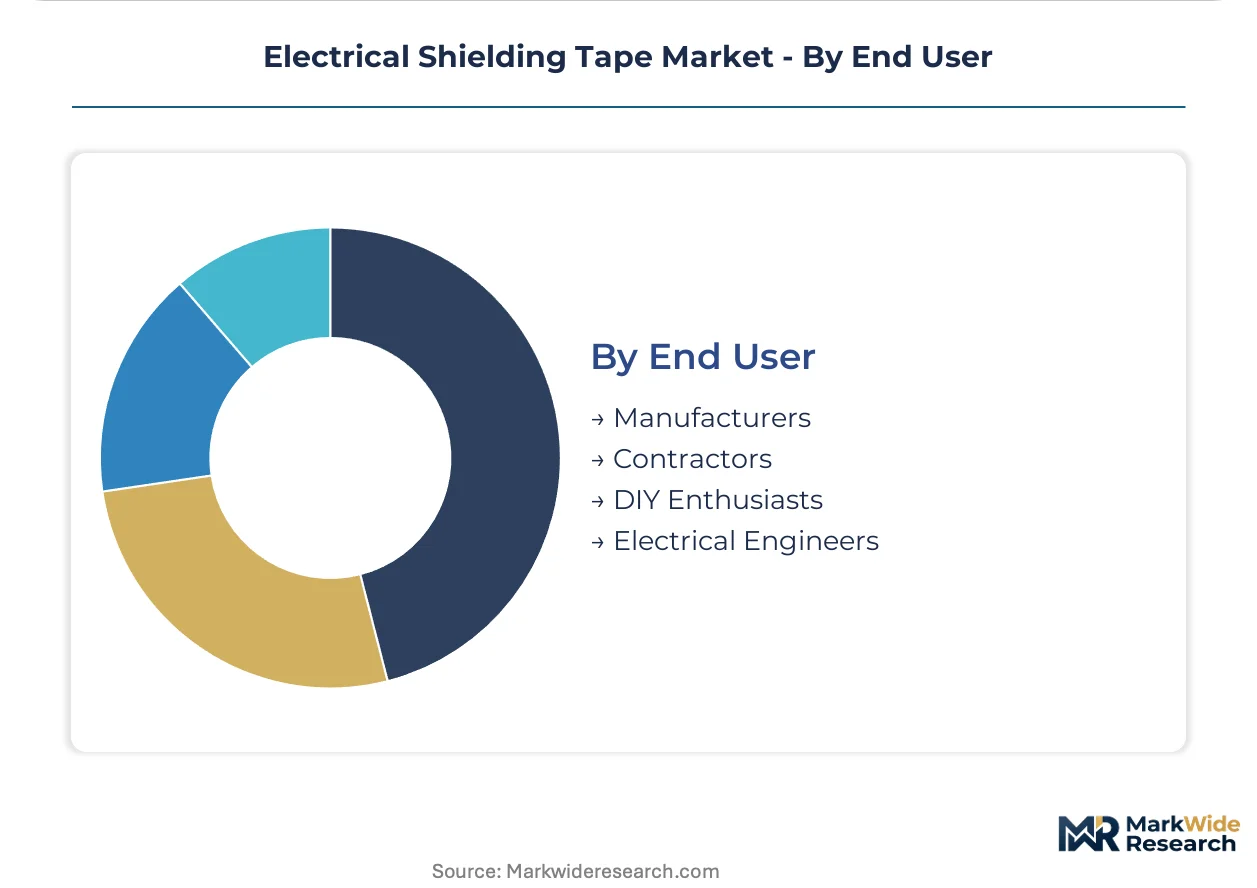
Manufacturers control the specification pipeline, while Contractors represent the most price-sensitive volume segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for domestic electronics manufacturing are redirecting investment flows across major economies, with subsidy programs in India, China, and the United States reshaping regional procurement patterns for shielding materials.
China
Domestic cable assembly capacity expansion in Guangdong and Jiangsu provinces is absorbing copper and aluminum foil tape volumes at scale. GB/T 9254 electromagnetic compatibility standards enforce stricter shielding effectiveness thresholds than legacy specifications. Shenzhen and Dongguan electronics clusters are integrating tape procurement into platform-level electromagnetic architecture decisions rather than component-level spot purchasing.
United States
Aerospace Tier-1 contractors in Seattle and Wichita are bundling electromagnetic compatibility testing with tape supply contracts. FCC Part 15 emission limits tighten validation protocols for satellite and avionics applications. Southern California defense manufacturing corridors concentrate demand for traceable attenuation documentation across extended temperature windows.
Germany
Automotive OEMs in Stuttgart and Munich are qualifying next-generation conductive formulations for 800V EV platforms. REACH substance-of-very-high-concern listings restrict legacy flame-retardant additives, pushing reformulation toward phosphorus-nitrogen synergists. Bavarian medical device manufacturers are ahead of schedule on F-Gas Regulation compliance for hydrofluorocarbon-free adhesive solvents.
India
PLI scheme incentives for semiconductor and component assembly are creating virgin demand in previously import-dependent supply chains. BIS certification requirements are tightening quality thresholds for shielding materials used in telecommunications infrastructure. Karnataka and Tamil Nadu electronics manufacturing clusters are scaling procurement of self-adhesive formulations for 5G small cell deployment.
Japan
Tier-1 automotive suppliers in Nagoya and Tokyo are co-developing platform-level electromagnetic architectures with tape converters. METI industrial standards guide pressure-sensitive adhesive qualification for power electronics modules. Osaka-based polymer synthesis operations sustain captive supply chains for proprietary acrylic formulations.
Electrical Shielding Tape Market Vendor Landscape
On the supply side, the industry is tiered between integrated material suppliers with captive polymer synthesis and specialized converters leveraging asset-light equipment leasing. Japanese and North American chemical groups anchor the premium tier through proprietary adhesive platforms. European specialists compete via electromagnetic compatibility testing bundling. The dominant competitive moves involve specification bundling with validation services and retrofitting coating lines for waterborne solvent compliance.
Among integrated material suppliers, 3M and Nitto Denko Corporation occupy positions defined by polymer synthesis depth and aerospace specification relationships. Holland Shielding Systems BV exemplifies the European specialist archetype competing through bundled testing workflows. These three companies represent the structural segmentation between chemical integration, specification authority, and service-anchored positioning that characterizes competitive dynamics in this market.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Scapa Group Ltd. |
| Intertape Polymer Group |
| Shurtape Technologies, LLC |
| Advance Tapes International |
| Holland Shielding Systems BV |
| RTP Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese copper foil coating lines is compressing spot pricing for standard-grade shielding tapes while tightening specification premiums for aerospace-certified configurations. Automotive OEMs exploit this utilization asymmetry to extract volume concessions from commodity converters, leaving margin defense to integrated suppliers with captive polymer synthesis.
Pricing Analysis
Certification level creates the primary spread across shielding tape tiers. Three-tier pricing structure across aerospace-grade, automotive-qualified, and industrial-economy levels reflects electromagnetic compatibility documentation burdens and temperature rating differentials. Pricing pressure stems from Chinese domestic overcapacity in copper foil lamination, which erodes spot margins on fixed-price contracts. Contractors and installation firms represent the most price-sensitive volume segment, whereas satellite manufacturers accept substantial premiums for traceable attenuation validation.
Supply Chain Analysis
Extended payment terms from automotive Tier-1 suppliers are forcing independent converters into supply-chain finance facilities to bridge working capital gaps. Raw material sourcing concentrates in China for copper foil and acrylic adhesive monomers, with Japan and Germany anchoring specialty polymer synthesis. The supply chain rests on captive acrylic production among integrated chemical groups, creating single-source vulnerability for independent converters. Distribution runs through direct specification relationships with aerospace contractors and electronics manufacturing service distributors for automotive volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical shielding tape market is cycling through a capacity-led recovery as EV platform rollouts absorb excess coating line utilization. Copper price normalization and 800V architecture proliferation are restoring pricing power to specification-anchored suppliers.
For Market Incumbents: Harden electromagnetic compatibility testing capabilities to defend against pure-product competitors in aerospace and satellite manufacturing clusters. Deepen backward integration into phosphorus-nitrogen flame-retardant adhesive platforms ahead of REACH substance restriction deadlines. Lock in multi-year platform-level co-development agreements with automotive OEMs to insulate volume contracts from spot-price volatility. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized electronics manufacturing corridors where shielding material supply chains remain import-dependent. Target telecommunications field service segments with repositionable self-adhesive formulations that bypass thermal adhesive cure infrastructure requirements. Lead with waterborne solvent compliance credentials to capture EU F-Gas Regulation retrofit demand ahead of integrated suppliers' coating line conversions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision coating equipment leasing models, enabling asset-light entry by specialized converters. Five-to-ten year viability favors acquisition targets with validated aerospace specification relationships and captive polymer synthesis capabilities. Watch for inflection when automotive OEMs consolidate electromagnetic architecture decisions from component procurement to platform engineering, signaling specification authority concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Level Electromagnetic Co-Development | Automotive OEMs in Germany and China are embedding tape specifications into 800V architecture decisions. |
| Waterborne Adhesive Coating Line Retrofit | EU F-Gas Regulation compliance is forcing capital deployment toward hydrofluorocarbon-free solvent systems. |
| Electromagnetic Compatibility Testing Bundling | Aerospace contractors in Seattle and Wichita are awarding combined validation and supply contracts. |
| India PLI Corridor Supply Localization | Semiconductor assembly incentives in Karnataka and Tamil Nadu are creating virgin demand for shielding materials. |
| Printed Conductive Ink Patterning Investment | Silver-nanowire inkjet deposition on polyimide is digitizing converter tooling economics for lot-size-one production. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the electrical shielding tape value chain. Primary interviews engaged procurement directors at automotive Tier-1 suppliers, electromagnetic compatibility test engineers at aerospace contractors, coating line operators at flexible substrate converters, and polymer synthesis chemists at adhesive manufacturers. Secondary validation drew from FCC Part 15 emission test filings, ECHA substance-of-very-high-concern listings, METI industrial standard publications, and customs trade data for copper foil and acrylic monomer flows. Bottom-up segment sizing triangulated against top-down market aggregation across conductive, metal foil, and fabric product configurations.
Calibration against historical capacity utilization rates and automotive production forecasts anchored the projection framework. Segmentation dimensions modeled include product type, application voltage class, bonding technology, and end-user procurement sophistication across the analysis window. CAGRs were derived from elasticity-adjusted volume projections tied to EV power electronics node multiplication and telecommunications infrastructure deployment cycles. Copper commodity price scenarios and REACH regulatory phase-in schedules fed sensitivity testing.
Stress conditions across copper price volatility bands, automotive platform transition timing, and adhesive reformulation compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about specification bundling adoption rates and coating line retrofit completion trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tabletop Tape Dispensers Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Gummed Tapes Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Raffia Tapes Market
Tapes
Acoustic Tape Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Washi Tapes Market
Tapes
Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Seam Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Tissue Tapes Market
Tapes
Nano Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market