
 Gaffers Tape Market | 2026-2036
Gaffers Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Gaffers Tape Market Analysis
The gaffers tape market is recalibrating around a widening split between premium cloth-backed formulations and commodity-grade polypropylene alternatives. 3M leverages its adhesive chemistry portfolio to dominate high-performance segments where residue-free removal commands price premiums. Shurtape Technologies anchors North American supply through specialized distribution to Pro AV Companies and regional film studios. Tesa SE competes in European theater supply chains with ISO-certified products tailored to German stage safety standards.
Gaffers tape is a heavy-duty pressure-sensitive adhesive tape constructed from woven cotton or synthetic cloth laminated with a rubber-based or synthetic adhesive system, engineered for temporary bonding with clean removal on cables, flooring, and equipment surfaces. Heavy-Duty Gaffers variants capture the strongest margin pools due to extended wear resistance demanded in multi-week film productions and outdoor event installations. Standard Gaffers remains the volume base across theater production budgets, while Double-Sided Gaffers grows fastest in sports broadcast rigging where discrete cable management matters. Material selection increasingly stratifies: cotton dominates premium tiers for conformability, polypropylene penetrates cost-sensitive event management procurement, and PVC faces substitution pressure from regulatory constraints.
Regulatory frameworks reshape product development and market access across multiple geographies. California Air Resources Board enforces VOC limits that restrict solvent-based adhesive formulations sold into entertainment industry supply chains. REACH compliance in Europe mandates disclosure of rubber adhesive constituents, elevating documentation costs for imported products. OSHA workplace safety standards in the United States drive flame-retardant certification requirements for stage and studio applications. Stakeholders must monitor evolving chemical restriction schedules and certification reciprocity agreements between regional enforcement bodies to anticipate formulation investment cycles and geographic supply reallocation.
Market Dynamics
California's Title 17 VOC regulations are forcing adhesive reformulation across the entire gaffers tape supply chain, compressing margins for solvent-based manufacturers while creating certification premiums for compliant low-emission producers.
Growth Catalysts
- Film Production Resurgence:United States film studios are expanding on-location shoots requiring heavy-duty cloth variants with extended weather resistance. Multi-week outdoor productions drive premium tape procurement cycles.
- REACH Compliance:European chemical disclosure mandates for rubber adhesive constituents are elevating documentation costs for imported products, advantaging domestic ISO-certified manufacturers with established supply chain transparency.
- Broadcast Infrastructure Modernization:Germany's stage construction standards and theater safety certifications are concentrating premium product demand in specialized distribution channels serving professional AV integrators.
Market Restraints
- Natural Rubber Volatility:Crude oil price fluctuations directly impact synthetic rubber adhesive input costs, compressing margins for manufacturers without backward integration into polymer supply.
- Asian Supply Concentration:Woven cotton fabric production clusters in specific East Asian manufacturing zones create geographic vulnerability to regional logistics disruptions and tariff fluctuations.
- Polypropylene Substitution:Lower-cost synthetic backing materials are displacing cotton in cost-sensitive event management procurement, eroding volume in standard-grade segments.
Strategic Opportunities
- Flame-Retardant Certification Gap:OSHA workplace safety standards for stage applications are creating underserved demand for certified products in regional theater supply chains lacking compliant local suppliers.
- Double-Sided Sports Broadcast:Discrete cable management requirements in mobile sports production units are accelerating uptake of specialized adhesive configurations for temporary rigging installations.
- Low-Emission Formulation Premium:California Air Resources Board enforcement is generating price premiums for compliant products sold into entertainment industry supply chains with strict environmental procurement policies.
Industry Challenges
- Adhesive Chemist Scarcity:Formulation expertise for residue-free removal properties is concentrating among aging specialist workforces, constraining R&D velocity for mid-tier manufacturers.
- Certification Timeline Compression:Multi-jurisdiction flame-retardant testing requirements for stage applications are extending product launch cycles and freezing working capital in inventory awaiting approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaffers Tape Market |
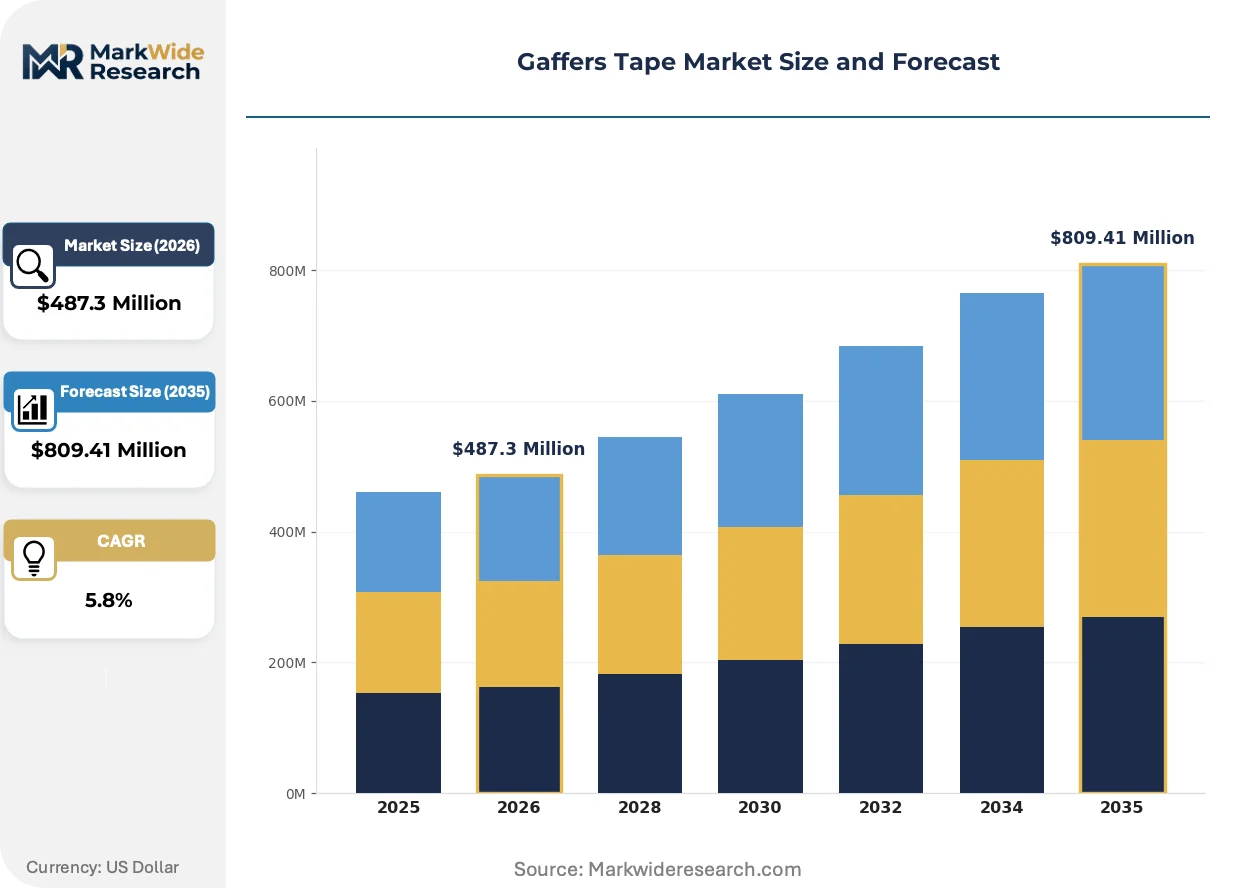
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gaffers, Heavy-Duty Gaffers, Double-Sided Gaffers, Glow in the Dark Material: Cotton, Polypropylene, PVC, Cloth Application: Film Production, Theater Production, Event Management, Sports End User: Pro AV Companies, Event Organizers, Film Studios, Performers |
| Companies Covered | 3M, Shurtape Technologies, Pro Tapes & Specialties, Tesa SE, Berry Global, Scapa Group, Intertape Polymer Group, Polyken, Advance Tapes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaffers Tape Market Emerging Trajectories
Water-based acrylic adhesive systems are displacing solvent-based formulations across premium gaffers tape segments, driven by regulatory pressure and residue-performance convergence that narrows the performance gap between compliant and traditional products.
Hot-melt pressure-sensitive adhesive technology is electrifying manufacturing efficiency for low-VOC product lines. German stage equipment suppliers are adopting these formulations at accelerated pace to preempt REACH enforcement actions. The technology is compressing the cost premium between compliant and legacy solvent-based products, reshaping competitive positioning in European theater supply chains.
California Air Resources Board Title 17 amendments are restricting volatile organic compound content in entertainment industry adhesive products. Manufacturers serving Los Angeles and San Francisco production hubs are reformulating rubber-based systems to meet emission thresholds. Heavy-duty cloth variants face the steepest compliance burden due to adhesive load requirements for multi-surface bonding.
Buyer consolidation among national event management companies is compressing supplier negotiation cycles and demanding volume-tier pricing transparency. Regional distributors serving independent film studios are losing share to direct manufacturer relationships with procurement teams at consolidated rental houses. This pattern is most visible in Texas and Georgia production corridors where infrastructure investment has concentrated production activity.
Gaffers Tape Market Segmentation
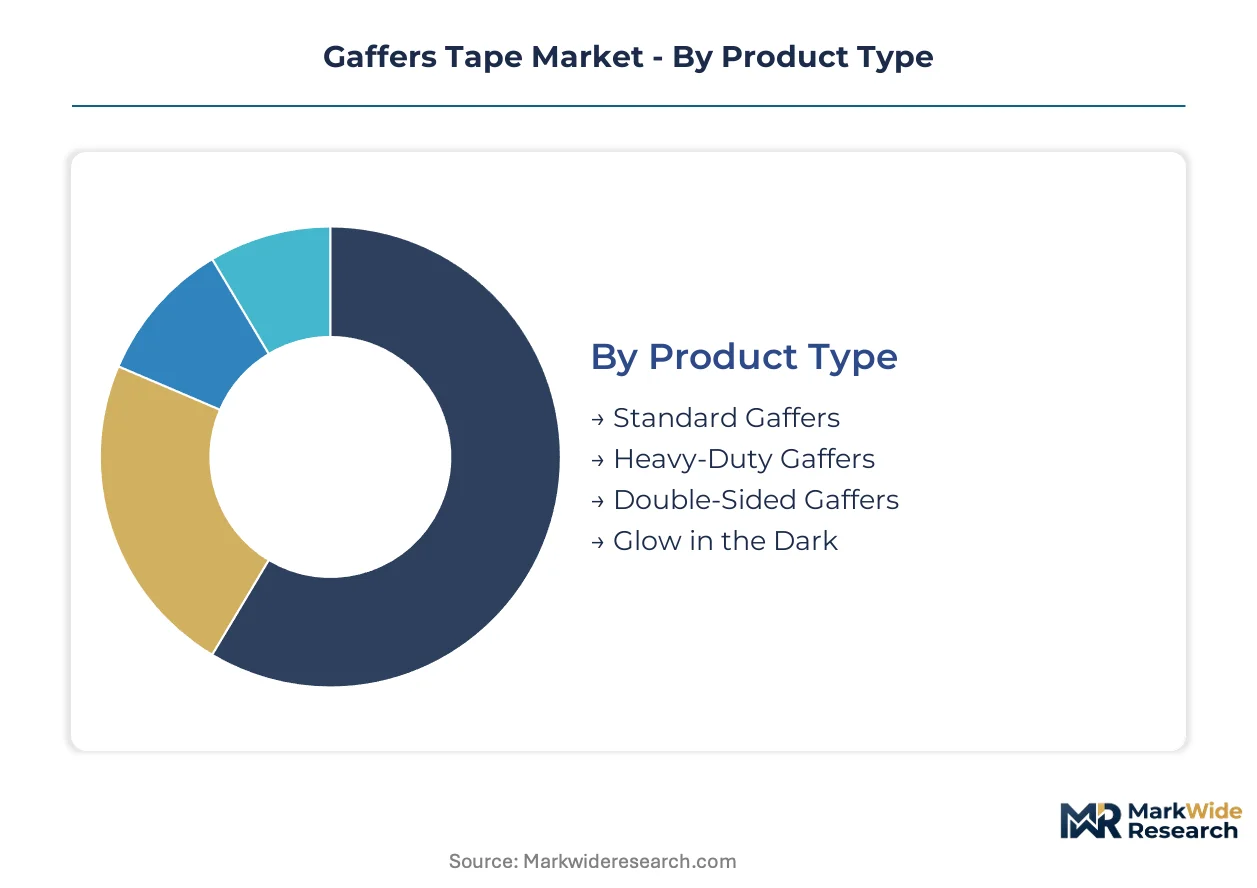
Segmentation in gaffers tape markets reveals how certification requirements and material specifications stratify procurement across entertainment industry verticals. Each dimension carries distinct regulatory burdens that reshape supplier positioning and margin structures.
Product Type:
Flame-retardant certification from OSHA and regional theater safety boards concentrates on specific product tiers, with heavy-duty variants facing the steepest compliance thresholds for stage and studio applications.
- Heavy-Duty Gaffers:Woven cotton cloth backing with high adhesive load engineered for multi-week film productions and outdoor weather exposure. United States film studios in California and Georgia drive procurement of residue-free formulations that meet CARB Title 17 VOC thresholds for on-location shoots.
- Double-Sided Gaffers:Pressure-sensitive adhesive on both faces enables discrete cable routing without visible tape lines. Sports broadcast rigging in mobile production units across Germany and the United States accelerates uptake as broadcasters modernize infrastructure for temporary installations.
- Standard Gaffers:Baseline cotton or synthetic cloth construction serves theater production budgets with moderate wear requirements.
- Glow in the Dark:Photoluminescent pigment integration for emergency egress marking and low-visibility stage applications.
Leading the category by volume: Standard Gaffers. Expanding most quickly: Double-Sided Gaffers.
Material:
Raw material selection determines REACH documentation intensity in European supply chains and California emission compliance costs for rubber adhesive systems.
- Cotton:Woven natural fiber dominates premium tiers for conformability and clean removal on sensitive surfaces. German stage construction standards and theater safety certifications concentrate demand among ISO-certified suppliers serving professional AV integrators.
- Polypropylene:Lower-cost synthetic backing displaces cotton in cost-sensitive event management procurement, eroding margin in standard-grade segments.
- PVC:Faces substitution pressure from regulatory constraints on halogenated materials in European theater supply chains.
- Cloth:Synthetic or blended woven constructions balance durability with weight reduction for touring productions.
Commanding premium pricing: Cotton. Gaining share fastest: Polypropylene.
Application:
End-use verticals stratify by procurement sophistication, with film production and theater segments demanding certified products while event management prioritizes cost efficiency.
- Film Production:Multi-week on-location shoots require heavy-duty cloth variants with extended weather resistance and residue-free removal. California studios face CARB enforcement pressure for low-emission adhesive procurement.
- Theater Production:Permanent and touring stage installations drive flame-retardant certification requirements under OSHA workplace safety standards.
- Event Management:Cost-sensitive procurement favors polypropylene alternatives for short-duration temporary installations.
- Sports:Mobile broadcast rigging and venue conversions create discrete cable management demand for specialized adhesive configurations.
Generating highest revenue concentration: Film Production. Showing steepest expansion trajectory: Sports.
End User:
Buyer consolidation among national rental houses is compressing supplier negotiation cycles and demanding volume-tier pricing transparency across end-user categories.
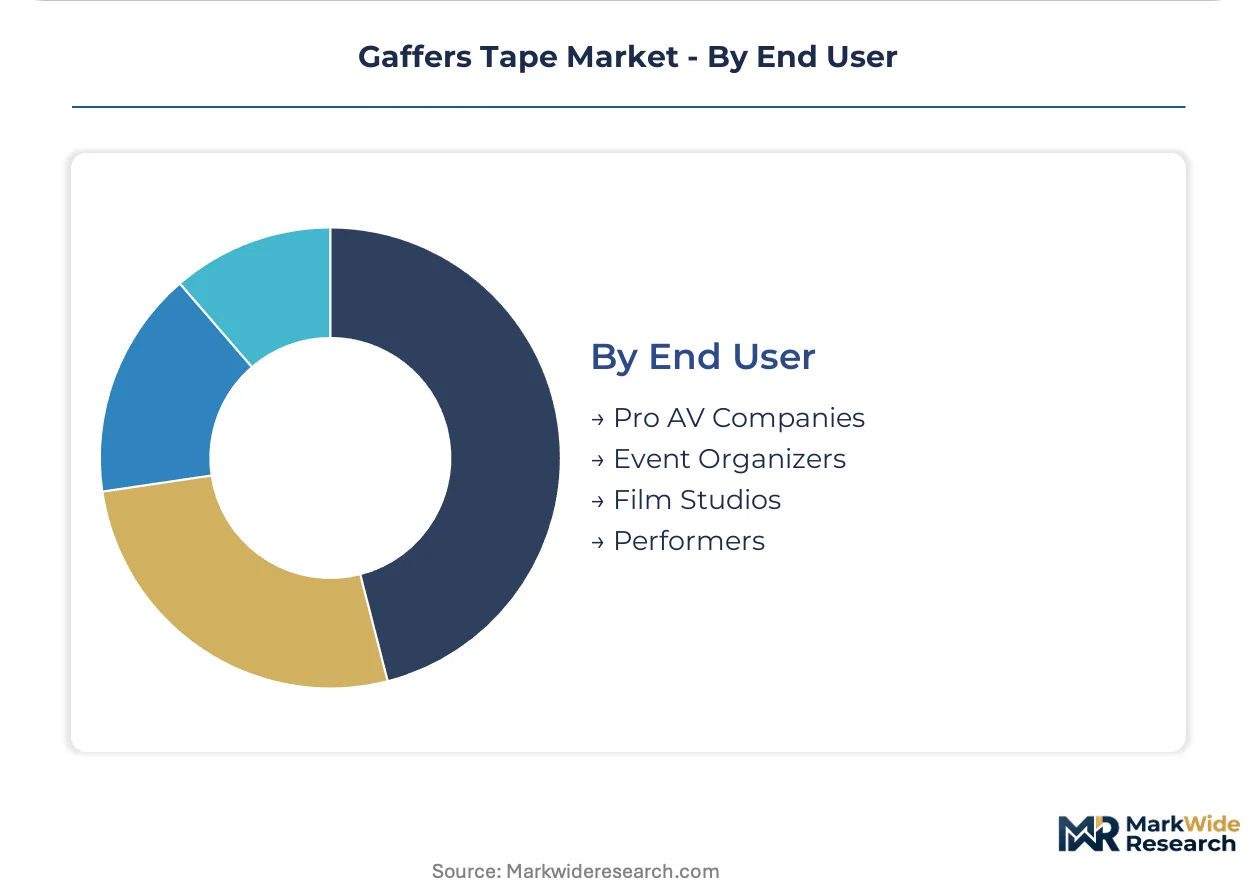
- Pro AV Companies:Professional integrators serving broadcast and corporate clients prioritize ISO-certified products with documented supply chain transparency for REACH compliance.
- Film Studios:Major production facilities in California, Georgia, and Texas concentrate procurement of CARB-compliant heavy-duty formulations for on-location shoots.
- Event Organizers:Consolidated national rental houses drive commoditization pressure in standard-grade segments.
- Performers:Individual artists and small touring acts represent fragmented, price-sensitive demand.
Holding largest procurement scale: Film Studios. Experiencing fastest demand growth: Pro AV Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors production demand through its concentration of film studios executing multi-week on-location shoots requiring heavy-duty cloth variants. The city's entertainment infrastructure generates procurement pull for residue-free formulations that balance performance with regulatory compliance.
United States
California's Title 17 VOC regulations from CARB force adhesive reformulation for solvent-based manufacturers serving Los Angeles and San Francisco production hubs. Georgia's expanding studio infrastructure in the Atlanta corridor concentrates procurement of weather-resistant heavy-duty variants for outdoor filming. Texas production corridors attract direct manufacturer relationships as consolidated rental houses centralize purchasing power.
Germany
Broadcast infrastructure investment and stage construction standards drive premium product uptake among professional AV integrators. REACH compliance mandates elevate documentation costs for rubber adhesive constituents, advantaging domestic ISO-certified suppliers with established supply chain transparency. Berlin and Hamburg theater districts concentrate demand for flame-retardant certified products meeting workplace safety standards.
United Kingdom
London's West End theater district sustains procurement of cotton-backed premium tiers for touring productions requiring conformability on sensitive surfaces. The country's national chemical regulator enforces disclosure requirements that reshape import competitiveness. Manchester and Birmingham event management clusters increasingly specify polypropylene alternatives for cost-sensitive temporary installations.
China
Woven cotton fabric production clusters in specific East Asian manufacturing zones supply backing materials to global tape converters. The country's Ministry of Ecology and Environment implements emission controls that affect adhesive formulation choices for export-oriented producers. Shenzhen and Guangzhou electronics manufacturing corridors generate secondary demand for cable management applications in broadcast equipment assembly.
Japan
Tokyo's broadcast infrastructure modernization drives uptake of specialized adhesive configurations for discrete cable routing in mobile production units. METI industrial standards influence product specification patterns across professional AV integrators. Osaka and Nagoya manufacturing bases support precision coating operations for premium-grade tape exports.
Gaffers Tape Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market structure that stratifies between premium formulation specialists and volume-driven commodity suppliers. The vendor base organizes into three tiers: multinational adhesive chemistry houses with proprietary polymer portfolios, regional fabricators serving specialized distribution channels, and contract manufacturers supplying private-label programs for consolidated rental houses. Dominant competitive moves include geographic expansion into production corridor clusters and portfolio diversification toward low-emission compliant formulations.
Within the multinational tier, 3M anchors high-performance segments where residue-free removal commands price premiums. Shurtape Technologies occupies a position among North American specialists distributing through Pro AV channels and regional film studio procurement. Tesa SE exemplifies European theater supply chain integration with products aligned to German stage safety standards. These three represent distinct archetypes: chemistry-led innovation, regional distribution density, and certification-aligned specialization.
| Leading Market Players |
|---|
| 3M |
| Shurtape Technologies |
| Pro Tapes & Specialties |
| Tesa SE |
| Berry Global |
| Scapa Group |
| Intertape Polymer Group |
| Polyken |
| Advance Tapes |
| Others |
Supply Flow & Price Mechanics
Consolidated national rental houses in the United States and Germany have concentrated procurement leverage, forcing a shift from spot-market purchasing to annual volume contracts with tiered rebate structures tied to flame-retardant certification tiers.
Pricing Analysis
Residue-free removal performance anchors value-based pricing premiums for heavy-duty cloth variants used in multi-week film productions. Three-tier pricing structure across premium, standard, and economy levels stratifies by adhesive load and certification status, with CARB Title 17 compliance commanding substantial markups in California procurement. Cost compression in polypropylene-backed standard grades is intensifying because event management buyers prioritize unit economics over performance specifications. Event organizers exhibit the highest price sensitivity, while film studios in Georgia and Texas demonstrate inelastic demand for certified heavy-duty formulations.
Supply Chain Analysis
Domestic-content preferences in German stage construction procurement are reshaping sourcing patterns for REACH-compliant rubber adhesive systems. Woven cotton fabric production clusters in China, Vietnam, and India supply backing materials to global converters, while synthetic rubber feedstocks draw from South Korean and Thai petrochemical corridors. Single-source vulnerability concentrates in East Asian woven fabric zones subject to regional logistics disruptions. Distribution runs through specialized Pro AV distributors in North America and ISO-certified theater supply houses in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gaffers tape market functions as a cost-of-compliance story where CARB Title 17 enforcement has erected a regulatory moat that solvent-based manufacturers cannot cross without reformulation investment.
For Market Incumbents: Extend certification portfolios into flame-retardant OSHA tiers to preempt competitor encroachment in theater supply chains. Deepen backward integration into water-based acrylic adhesive production to defend margin position against raw material volatility in synthetic rubber markets. Capacity addition in Georgia production corridors captures procurement consolidation among Atlanta-based film studios. For New Entrants and Emerging Players: REACH in Germany opens a window for domestic ISO-certified manufacturers to displace import-dependent competitors facing elevated documentation costs for rubber adhesive constituents. Target underserved regional theater supply chains in Texas and the United Kingdom lacking compliant local flame-retardant suppliers. Pursue direct manufacturer relationships with consolidated rental houses as a go-to-market angle, bypassing distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European manufacturers with established REACH compliance infrastructure but constrained working capital for California market entry. Long-term viability hinges on dual-jurisdiction certification capability spanning CARB and REACH enforcement zones. Watch for adhesive chemist workforce scarcity as an inflection indicator constraining R&D velocity industry-wide.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Emission Formulation Investment | CARB Title 17 compliance unlocks premium pricing in California entertainment procurement corridors. |
| Flame-Retardant Certification Expansion | OSHA workplace safety standards create defensible positioning in theater supply chains lacking compliant suppliers. |
| Backward Integration into Adhesive Production | In-house water-based acrylic capacity insulates margins from synthetic rubber price volatility. |
| Direct Rental House Relationships | Bypassing distributors captures volume-tier pricing transparency with consolidated national event management companies. |
| Double-Sided Product Line Extension | Sports broadcast infrastructure modernization in Germany and the United States accelerates specialized adhesive uptake. |
Methodological Framework
Multi-period observation of film production activity indices, broadcast infrastructure capex disclosures, and stage construction permit data anchored the trend analysis, supplemented by interviews with adhesive chemists, Pro AV procurement directors, theater technical directors, and event rental house operations managers. Secondary validation drew from California Air Resources Board enforcement records, REACH substance registration databases, OSHA workplace safety citation data, and customs trade flows for woven cotton fabrics. Bottom-up segment sizing triangulated against top-down industry value estimates derived from entertainment industry production spend proxies.
Input-output matrices mapped raw material cost trajectories through formulation tiers to end-use pricing across the projection horizon. Segmentation dimensions modeled include product type, material specification, application vertical, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical production activity against tape consumption intensity ratios, with sensitivity testing around natural rubber price volatility and regulatory enforcement acceleration scenarios.
The model assumes a particular technology adoption path for water-based acrylic systems; alternative pathways involving hot-melt pressure-sensitive adhesive breakthroughs would alter the outlook for solvent-based manufacturer survival. Forecasts reflect assumptions about REACH disclosure burden stability and CARB enforcement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tabbing Tapes Market
Tapes
Nano Tapes Market
Tapes
Hand Wrappers Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Filament Tapes Market
Tapes
Custom Printed Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Masking Tape Market
Tapes
Hydrocolloid Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Carry Handle Tape Market
Tapes
Industrial Tapes Market
Tapes
Sterilization Tape Market
Tapes
Strapping Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market