
 US Electric Enclosure Market | 2026-2036
US Electric Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Enclosure Market Analytics
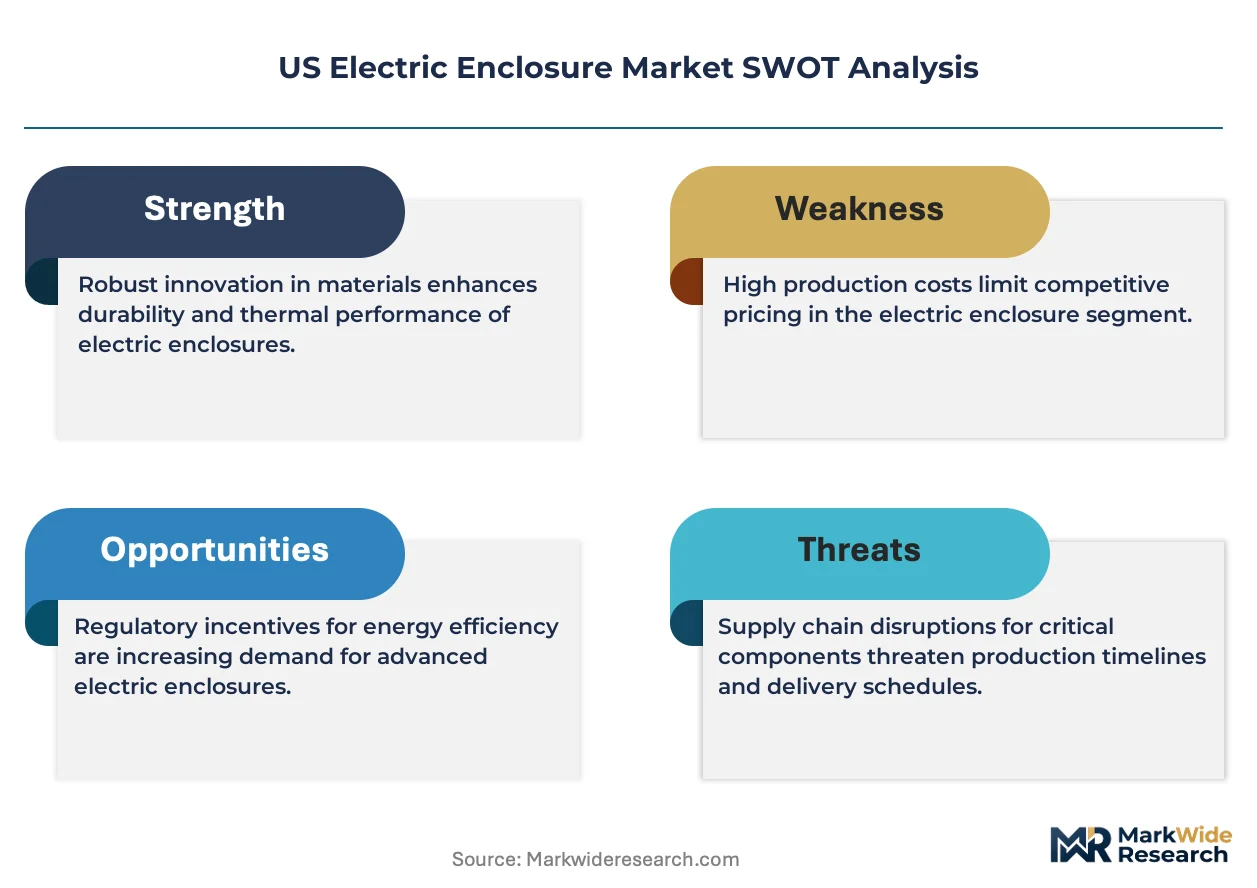
Aftermarket service revenue is reconfiguring margin capture across the US electric enclosure value chain. nVent leverages its thermal management integration to command premium positioning in data center applications. Emerson Electric Co. sustains deep relationships with industrial automation buyers through channel control and specification engineering. Schneider Electric anchors its competitive stance with end-to-end electrical infrastructure bundling that reduces procurement complexity for utilities.
US electric enclosures are sealed housings—typically fabricated from cold-rolled steel, aluminum, or thermoplastic composites with NEMA or IP ingress protection ratings—designed to shield electrical components from environmental hazards, electromagnetic interference, and unauthorized access. Floor-mounted steel enclosures dominate manufacturing and utility deployments due to load-bearing capacity and modularity for breaker panels and switchgear assemblies. Wall-mounted aluminum variants are gaining share in telecommunications edge installations where weight reduction and corrosion resistance offset material cost premiums. Plastic and composite enclosures serve outdoor distributed energy resource applications where non-conductive properties and UV stability satisfy revised IEEE standards.
NEMA enclosure type classifications and UL 50/50E listing requirements govern product compliance and market access across US jurisdictions. The EPA's emerging PFAS restrictions and OSHA electrical safety directives are pressuring manufacturers toward revised gasket materials and arc-flash containment designs. Stakeholders must monitor state-level building code adoptions in Texas, Virginia, and Arizona, as these jurisdictions set precedent for enclosure fire-resistance and seismic-rating specifications that suppliers will need to satisfy ahead of broader national harmonization.
Market Dynamics
Hyperscale data center construction in Texas, Virginia, and Arizona is compressing lead times for NEMA-rated floor-mounted enclosures and forcing manufacturers to pre-position inventory near cluster zones.
Growth Catalysts
- NEMA Type 3R/4X enclosure demand:Outdoor renewable energy interconnection mandates from FERC Order 2023 are requiring weatherproof housing for inverter and transformer equipment across utility-scale solar deployments.
- Texas:ERCOT grid instability and backup power mandates are driving procurement of arc-resistant switchgear enclosures for critical facility hardening.
- Thermal management integration:Liquid cooling compatibility in enclosure designs is capturing premium positioning as AI training clusters exceed 50kW per rack density thresholds.
Market Restraints
- Cold-rolled steel input volatility:Domestic mill capacity constraints and Section 232 tariff uncertainty are compressing gross margins on standard steel cabinet production.
- PFAS gasket material phaseout:EPA restrictions on fluorinated sealing compounds are forcing reformulation cycles that delay UL 50E recertification timelines by 8-14 months.
- Aluminum alloy supply concentration:Primary smelter dependence on Quebec and Iceland imports creates exposure to energy-price-driven ingot cost spikes.
Strategic Opportunities
- Arizona:Phoenix-Mesa data center corridor expansion offers underpenetrated demand for seismic-rated enclosure skids that satisfy local building code amendments ahead of national adoption.
- Modular busway integration:Converging power distribution and enclosure systems into factory-integrated skids reduces field wiring labor for hyperscale contractors.
- Infrastructure Investment and Jobs Act:Grid modernization grants are creating specification pathways for smart grid-ready enclosures with embedded sensor mounting provisions.
Industry Challenges
- UL 508A panel shop certification backlog:Third-party testing lab capacity constraints are extending time-to-market for custom enclosure-assembly configurations.
- Arc-flash containment engineering:IEEE 1584 calculation complexity requires specialized electrical safety expertise that mid-tier fabricators struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Enclosure Market |
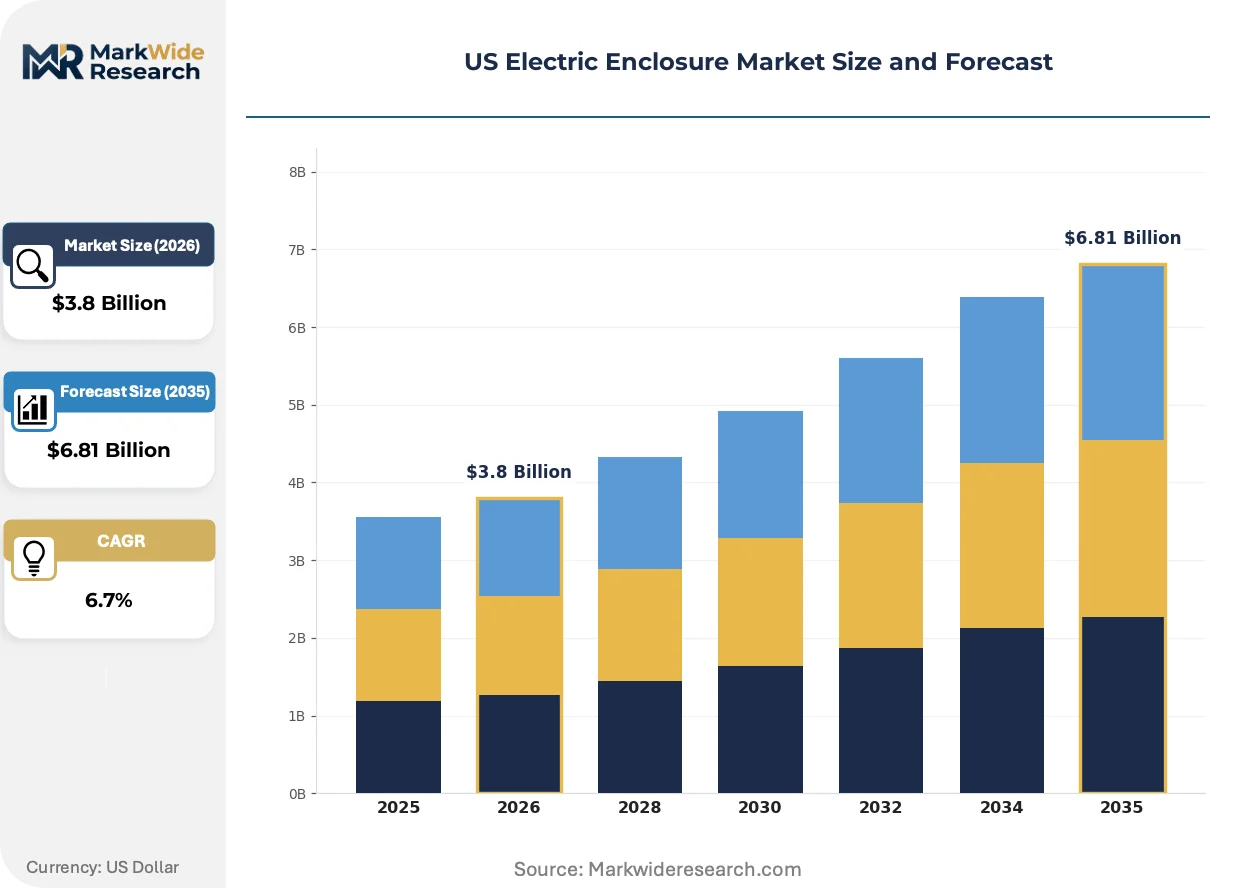
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Floor-Mounted, Underground, Portable Material: Steel, Aluminum, Plastic, Composite End User: Manufacturing, Telecommunications, Utilities, Data Centers Installation Type: Indoor, Outdoor, On-Site, Off-Site |
| Companies Covered | nVent, Emerson Electric Co., Schneider Electric, Rittal, Legrand SA, ABB, Hubbell, Siemens AG, Eaton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Enclosure Market Evolving Landscape
Active cooling integration and material substitution are redefining enclosure value propositions as thermal loads outpace legacy passive dissipation limits in high-density deployments.
Die-cast aluminum heat sink enclosures with embedded liquid cooling channels are rendering obsolete traditional steel cabinets with bolt-on external radiators in AI data center applications. Hyperscale operators in Northern Virginia are specifying these units for 100kW+ rack densities. The shift is compressing supplier margins on commodity steel fabrication while rewarding thermal engineering capabilities.
OSHA's updated electrical safety directive on arc-flash hazard labeling is mandating revised warning placard placement and legibility standards across NEMA enclosure categories. Industrial automation buyers are now requiring documentation packages that demonstrate compliance during pre-qualification. Food and beverage processing facilities face the tightest enforcement windows due to wet-location exposure risks.
Specification engineering services are unbundling from product sales as enclosure vendors compete for early-stage design influence. Engineering-procurement-construction firms in Texas are retaining dedicated enclosure consultants for hyperscale projects rather than relying on distributor generalists. This behavior shift concentrates margin capture with technical specialists and fragments traditional channel relationships.
US Electric Enclosure Market Segmentation
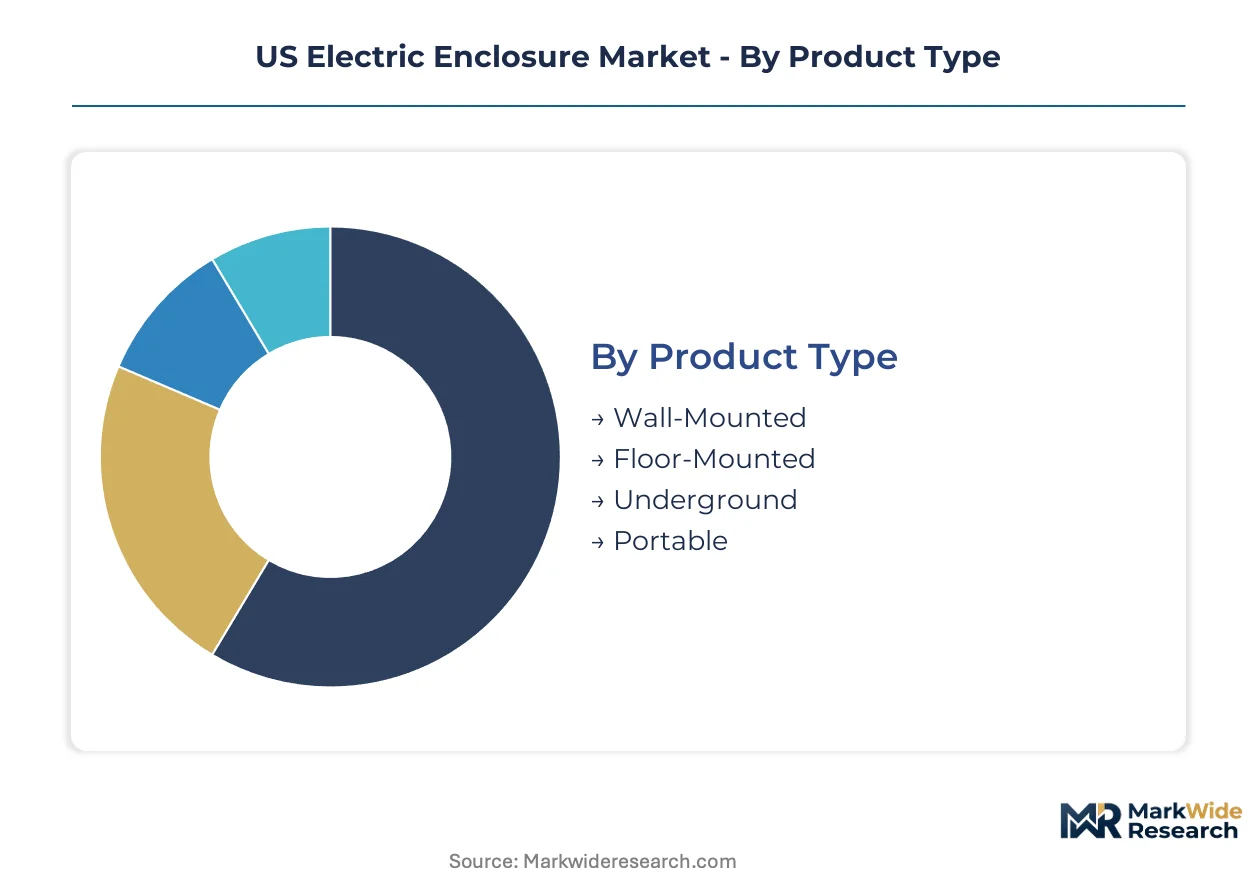
Enclosure procurement patterns diverge sharply across deployment contexts, with hyperscale data centers demanding thermal-engineered floor-mounted steel while edge telecommunications prioritize lightweight wall-mounted aluminum. Material selection and installation method determine compliance pathways, lead times, and margin structures for fabricators serving distinct buyer workflows.
Product Type:
Mounting configuration dictates load-bearing requirements, spatial footprints, and modularity for electrical component housing.
- Floor-Mounted:Cold-rolled steel cabinets with NEMA 3R/12 ratings support breaker panels and switchgear assemblies in manufacturing floors and utility substations. Texas and Virginia hyperscale facilities are compressing lead times for these units as rack densities exceed 50kW thresholds.
- Wall-Mounted:Aluminum enclosures reduce structural loading in telecommunications edge installations where corrosion resistance offsets material cost premiums. Arizona's Phoenix-Mesa corridor is driving specification volume for seismic-rated wall-mount variants ahead of national code harmonization.
- Underground:NEMA 6P submersible housings serve utility vault applications with gasket-sealed ingress protection against groundwater intrusion.
- Portable:Temporary power distribution skids support construction sites and emergency response deployments requiring rapid relocation.
Floor-mounted configurations command the established base. The steepest expansion runs through wall-mounted segments.
Material:
Substrate selection trades off thermal conductivity, electromagnetic shielding, and regulatory compliance cost against application-specific environmental exposure.
- Steel:Cold-rolled carbon steel dominates manufacturing and utility deployments due to structural rigidity and cost efficiency at scale. Section 232 tariff uncertainty and domestic mill capacity constraints are compressing gross margins on standard cabinet production.
- Aluminum:Die-cast heat sink enclosures with embedded liquid cooling channels serve AI training clusters exceeding 100kW per rack in Northern Virginia facilities. Primary smelter dependence on Quebec and Iceland imports creates exposure to energy-price-driven ingot cost spikes.
- Plastic:Non-conductive thermoplastic housings satisfy revised IEEE standards for outdoor distributed energy resource applications requiring UV stability.
- Composite:Fiberglass-reinforced polymer enclosures combine corrosion immunity with reduced weight for coastal and chemical processing environments.
Steel retains volume leadership across legacy infrastructure. Aluminum is climbing the fastest as thermal management integration commands premium positioning.
End User:
Buyer category determines specification complexity, certification requirements, and channel access patterns for enclosure vendors.
- Data Centers:Hyperscale operators in Texas, Virginia, and Arizona are pre-positioning inventory near cluster zones and demanding factory-integrated skids with modular busway convergence. Liquid cooling compatibility now gates supplier qualification.
- Manufacturing:Industrial automation buyers require OSHA-compliant arc-flash labeling and documentation packages demonstrating IEEE 1584 calculation compliance during pre-qualification.
- Utilities:Grid modernization grants under the Infrastructure Investment and Jobs Act are creating specification pathways for smart grid-ready enclosures with embedded sensor mounting provisions.
- Telecommunications:Edge computing deployments favor wall-mounted aluminum for weight reduction in distributed antenna systems and 5G small cell housings.
Data center procurement is expanding most quickly. Manufacturing maintains the deepest installed base.
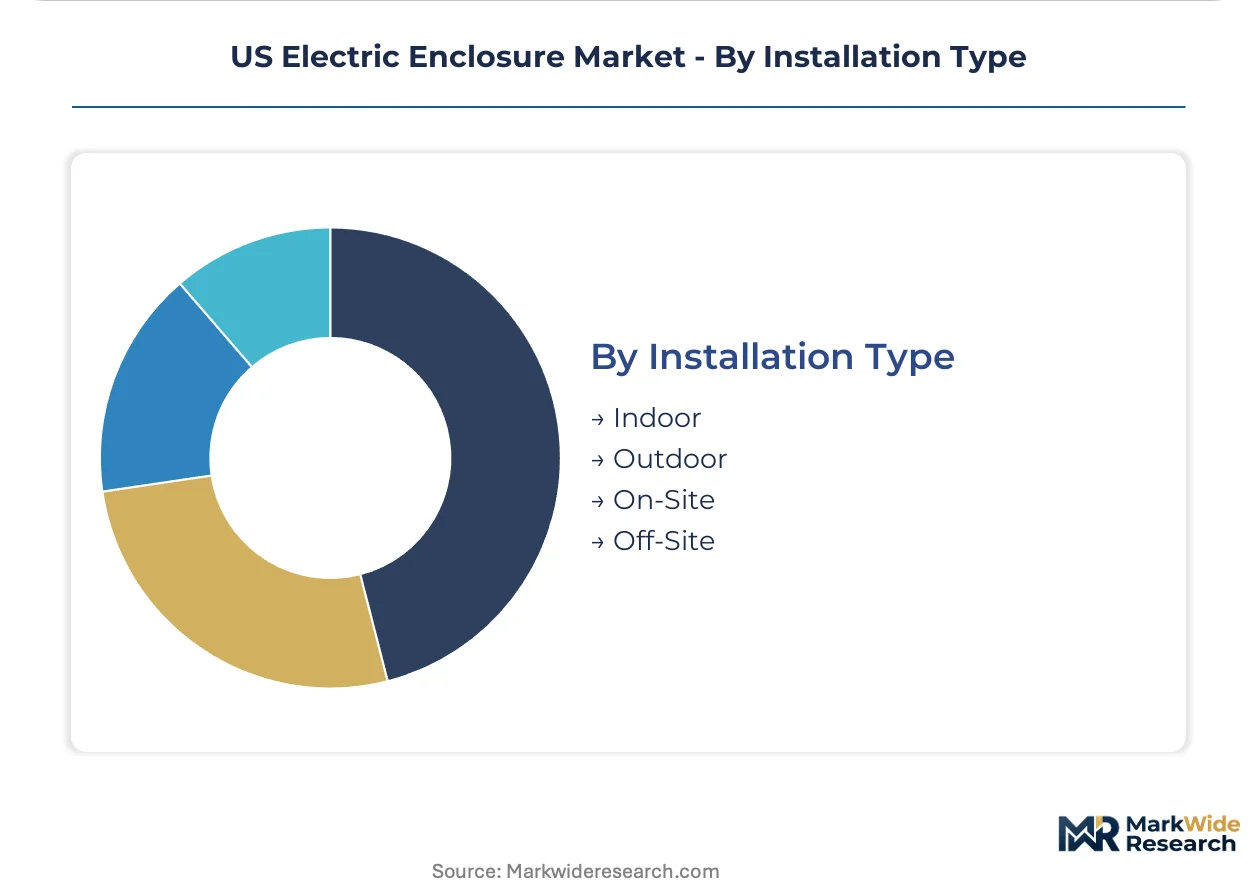
Installation Type:
Deployment location and assembly timing determine environmental sealing requirements, labor cost allocation, and project schedule risk.
- Outdoor:NEMA 3R/4X weatherproof housings satisfy FERC Order 2023 mandates for utility-scale solar inverter and transformer interconnection equipment.
- Indoor:Controlled-environment NEMA 1/12 enclosures serve manufacturing floors and commercial building electrical rooms with standard dust and drip protection.
- On-Site:Field-wired assemblies face UL 508A panel shop certification backlogs that extend time-to-market for custom configurations.
- Off-Site:Factory-integrated skid systems reduce field wiring labor for hyperscale contractors in Texas and Virginia.
Indoor installation commands the established base. Outdoor segments are gaining share fastest as renewable interconnection mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas, Virginia, and Arizona consume electric enclosures through hyperscale data center procurement channels that prioritize thermal-engineered floor-mounted steel, while other states distribute demand across manufacturing floors and utility substations with conventional NEMA-rated specifications.
Texas
ERCOT grid instability and backup power mandates are driving arc-resistant switchgear enclosure procurement for critical facility hardening. EPA PFAS restrictions are forcing gasket material reformulations that delay UL 50E recertification timelines. Dallas-Fort Worth and Austin data center clusters are compressing lead times as rack densities exceed 50kW thresholds.
Virginia
Northern Virginia hyperscale operators are specifying die-cast aluminum heat sink enclosures with embedded liquid cooling channels for AI training clusters surpassing 100kW per rack. FERC Order 2023 renewable interconnection mandates are expanding NEMA 3R/4X outdoor housing demand. Loudoun County and Prince William County anchor the nation's densest data center corridor.
Arizona
Phoenix-Mesa data center corridor expansion is generating underpenetrated demand for seismic-rated enclosure skids satisfying local building code amendments. OSHA electrical safety directives are mandating revised arc-flash hazard labeling documentation. Tempe and Chandler submarkets are seeing factory-integrated skid systems reduce field wiring labor for hyperscale contractors.
California
Utility-scale solar deployments under state renewable portfolio standards are requiring weatherproof inverter and transformer enclosures per revised IEEE standards. The state's building energy efficiency codes are tightening fire-resistance specifications for electrical infrastructure. Silicon Valley edge computing facilities favor wall-mounted aluminum for weight reduction in distributed antenna systems.
Illinois
Manufacturing automation buyers in Chicago metro industrial corridors require OSHA-compliant arc-flash labeling and IEEE 1584 calculation documentation during pre-qualification. Grid modernization grants under federal infrastructure programs are creating specification pathways for smart grid-ready enclosures. Rockford and Peoria manufacturing clusters maintain deep installed base demand for floor-mounted steel cabinets.
US Electric Enclosure Market Competitive Landscape
Capability concentration sits with thermal engineering specialists; scale advantage sits with diversified electrical infrastructure conglomerates. The vendor base stratifies across three tiers: integrated power distribution bundlers, thermal management specialists, and regional fabrication shops serving panel assembly channels. Dominant competitive moves include factory-integrated skid system development and specification engineering service unbundling to capture early-stage design influence.
Among diversified electrical infrastructure providers, Schneider Electric and Eaton exemplify the bundling archetype that reduces procurement complexity for utility and industrial automation buyers. nVent occupies a position representing the thermal management integration specialist tier commanding premium positioning in data center applications. These three anchors demonstrate how competitive positioning diverges between scale-driven end-to-end solution providers and capability-focused thermal engineering specialists.
| Leading Market Players |
|---|
| nVent |
| Emerson Electric Co. |
| Schneider Electric |
| Rittal |
| Legrand SA |
| ABB |
| Hubbell |
| Siemens AG |
| Eaton |
| Others |
Value Network & Pricing Analysis
Section 232 tariff exposure on cold-rolled steel inputs determines both pricing tier spreads and supply chain shape across the US electric enclosure market. Buyers face widening cost differentials between domestic mill sourcing and import-dependent alternatives, while fabricators reconfigure procurement geography to manage landed cost volatility.
Pricing Analysis
Long-term offtake contracts dominate hyperscale data center procurement, insulating buyers from spot steel volatility while locking in thermal-engineered premium tiers. Price differentiation hinges on UL 50E certification grade and liquid cooling integration depth, with arc-resistant switchgear configurations commanding substantial premiums over standard NEMA 12 cabinets. Cost compression in commodity steel fabrication is intensifying because domestic mill capacity constraints limit supply elasticity. Manufacturing automation buyers exhibit highest price sensitivity due to specification standardization, while data center operators prioritize thermal performance over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in Quebec and Iceland for primary aluminum ingot creates vulnerability to energy-price-driven cost spikes that ripple through die-cast enclosure production. Cold-rolled steel draws from domestic mills in Indiana, Ohio, and Pennsylvania, with Section 232 tariff exposure elevating landed cost uncertainty for non-NAFTA sourcing. PFAS gasket material phaseout under EPA restrictions presents regulatory chokepoint risk for UL 50E recertification timelines. Distribution runs through electrical distributor networks and direct EPC contractor channels, with specification engineering services increasingly unbundled from product sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale data center construction represents an early-cycle expansion story for thermal-engineered enclosure demand. AI training cluster density thresholds exceeding 100kW per rack accelerate specification upgrades across Texas, Virginia, and Arizona facilities.
For Market Incumbents: Build thermal engineering capability moats through liquid cooling integration IP and factory-integrated skid system development. Consolidate specification engineering talent to capture early-stage design influence before EPC contractor procurement finalization. Arc-flash containment expertise scarcity and UL 508A certification backlogs present defensible barriers against commodity fabricator encroachment. For New Entrants and Emerging Players: Build out seismic-rated enclosure production capacity targeting Arizona's Phoenix-Mesa corridor ahead of national building code harmonization. Penetrate the underdeveloped modular busway integration segment where factory pre-wiring reduces field labor costs for hyperscale contractors. Lead with specification engineering consulting services to establish technical credibility before product qualification. For Investors and Strategic Acquirers: EPA PFAS restrictions reshape the acquisition landscape by devaluing gasket material inventories and elevating reformulation-ready targets. Long-term viability centers on thermal management integration capabilities and data center channel relationships rather than commodity steel fabrication scale. Monitor FERC Order 2023 implementation velocity as inflection indicator for outdoor NEMA 3R/4X demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Engineering Acquisition | Liquid cooling IP consolidation secures premium positioning in Northern Virginia AI clusters. |
| Factory-Integrated Skid Development | Pre-wired busway convergence reduces field labor for Texas hyperscale contractors. |
| Specification Engineering Service Launch | Early design influence captures margin before EPC procurement finalization. |
| Seismic-Rated Product Certification | Arizona building code compliance opens Phoenix-Mesa corridor penetration. |
| PFAS-Free Gasket Reformulation | EPA-compliant sealing compounds prevent UL 50E recertification delays. |
Research Methodology
Operator-level perspectives from data center facility managers, EPC contractor procurement leads, electrical distributor specification engineers, and UL panel shop certification specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FERC filings, OSHA electrical safety directives, EPA regulatory dockets, and state-level building code adoption records in Texas, Virginia, and Arizona. Bottom-up enclosure shipment analysis triangulated against top-down hyperscale construction permit data.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories under varying data center power density assumptions and renewable interconnection mandate implementation speeds. Segmentation dimensions included mounting configuration, material substrate, end-user category, and installation type, with thermal load thresholds and NEMA rating requirements as industry-specific forecast inputs. CAGRs derived from shipment volume trends, capacity expansion announcements, and specification upgrade cycles.
Practitioners should monitor steel tariff policy revisions, EPA PFAS restriction enforcement timelines, and IEEE 1584 calculation standard updates for early signals of forecast deviation. Quarterly review of hyperscale construction permit issuance, domestic mill capacity utilization rates, and UL 50E recertification backlog durations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Busbar Trunking System Market
Electrical Equipment
Motor Protection Devices Market