
 US Cables Market | 2026-2036
US Cables Market Size, Share, and Industry Trends Forecast 2026-2036
US Cables Market Insights
The Inflation Reduction Act is decoupling domestic cable sourcing from historic import dependency patterns. Southwire Company leverages its vertically integrated copper rod mills to anchor Georgia-based production capacity. Prysmian Group sustains submarine and high-voltage specialization through continuous R&D investment in extrusion technologies. Belden Inc. differentiates industrial ethernet cable portfolios for factory automation and process control environments.
Cables are insulated electrical conductors engineered to transmit power or data across specified voltage ratings, temperature tolerances, and shielding configurations, with copper and aluminum cores jacketed in thermoplastic or cross-linked polyethylene compounds. Power cables dominate material tonnage deployed across utility grid hardening and renewable interconnection projects. Fiber optic cables represent the fastest-expanding product category as hyperscale data centers and 5G backhaul networks multiply strand-count requirements. Twisted pair installations retain substantial share in commercial building retrofits where cost constraints limit full fiber conversion.
NEC standards administered by the National Electrical Code and OSHA electrical safety mandates govern installation practices and product certification across US jurisdictions. The Federal Energy Regulatory Commission and state public utility commissions shape transmission investment timelines through interconnection queue reform and rate-base approval mechanisms. Stakeholders must monitor evolving Buy America thresholds and domestic content calculations as Treasury Department guidance crystallizes implementation pathways.
Market Dynamics
The Inflation Reduction Act's domestic content bonus credits are restructuring procurement patterns across transmission and distribution infrastructure, forcing developers to requalify supplier bases against Treasury Department guidance timelines.
Growth Catalysts
- Interconnection Queue Reform:FERC Order 2023 accelerates high-voltage transmission project approvals, compressing permitting timelines for cross-regional renewable energy zones in Texas and the Midwest.
- Data Center Power Density:Hyperscale facilities in Northern Virginia and Phoenix are driving 345kV and 500kV cable demand as rack densities exceed 50kW per unit.
- Grid Hardening Mandates:State public utility commissions in California and Florida are requiring undergrounding of wildfire-exposed distribution circuits, expanding medium-voltage cable deployment.
Market Restraints
- Copper Rod Supply Concentration:Domestic copper rod production clusters in Arizona and Utah, creating geographic vulnerability to smelter outages and concentrate price volatility.
- Cross-Linked Polyethylene Lead Times:Specialized compounding capacity for HVDC insulation remains concentrated among three North American producers, extending procurement cycles.
- Submarine Cable Vessel Scarcity:Global installation vessel availability constrains offshore wind export cable deployment along the Atlantic Coast.
Strategic Opportunities
- Buy America Threshold Navigation:Treasury Department domestic content calculations create first-mover advantage for manufacturers with captive copper rod and compounding capabilities.
- Industrial Ethernet Convergence:Factory automation and power-over-ethernet standards are merging cable specifications, opening integrated product portfolios for process control environments.
- Grid-Scale Battery Interconnection:ERCOT and CAISO queue positions for battery storage projects are multiplying medium-voltage collector cable requirements in Texas and California desert regions.
Industry Challenges
- Extrusion Technician Shortage:Specialized high-voltage cable manufacturing requires decade-long apprenticeship pipelines that regional technical colleges have not scaled to match project demand.
- NEC 2023 Code Adoption Lag:State-by-state electrical code adoption creates product certification fragmentation, forcing manufacturers to maintain multiple testing protocols.
- Legacy Paper-Insulated Cable Decommissioning:Urban infrastructure replacement projects encounter asbestos-handling protocols and right-of-way disputes that compress installation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cables Market |
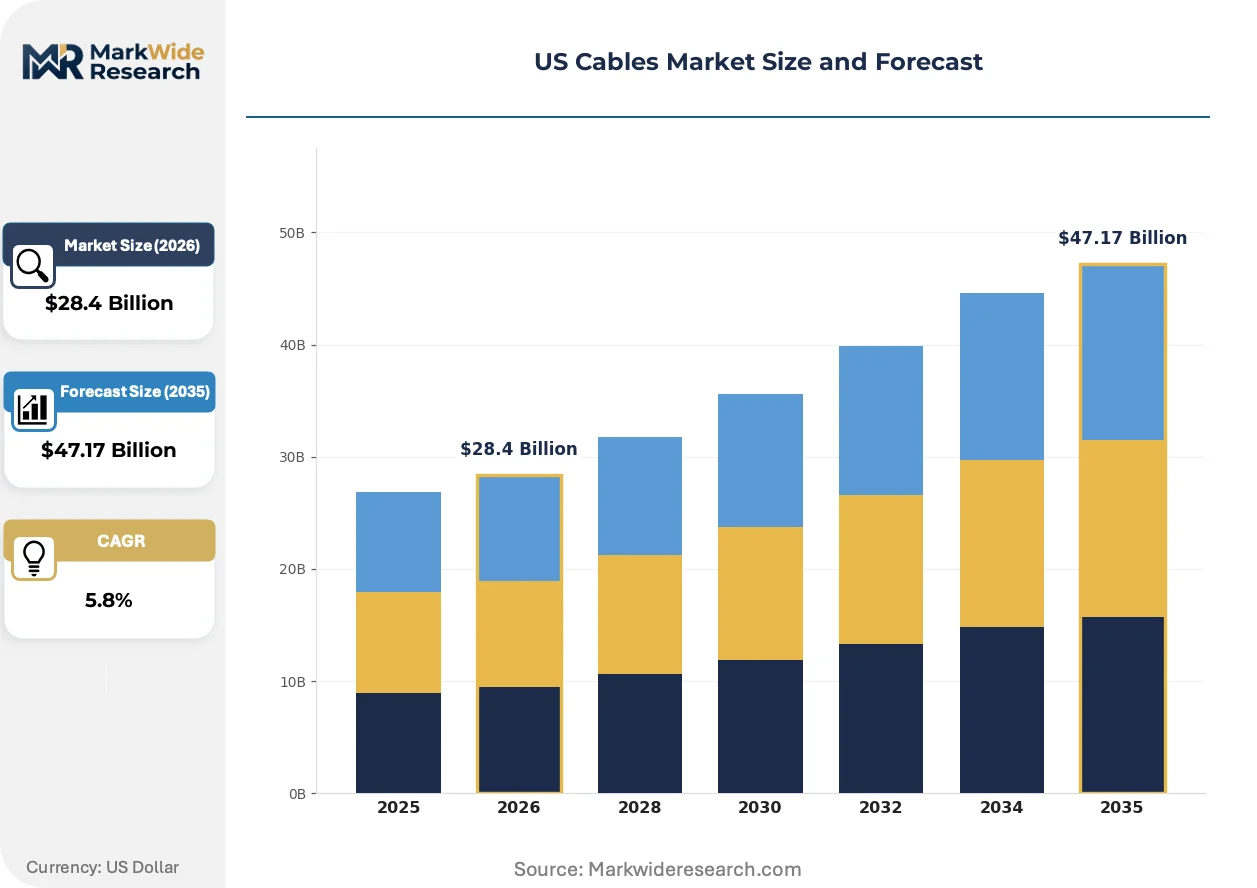
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial Cables, Fiber Optic Cables, Twisted Pair Cables, Power Cables Installation Type: Indoor, Outdoor, Underground, Aerial Material: Copper, Aluminum, Fiber Glass, Plastic End User: Telecommunications, Construction, Automotive, Energy |
| Companies Covered | Southwire Company, Prysmian Group, Belden Inc., Encore Wire Corporation, Nexans, LS Cable & System, Amphenol Corporation, CommScope Holding Company, TE Connectivity, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cables Market Trends and Innovations
Extrusion chemistry and conductor architecture are converging to address thermal cycling demands from bidirectional power flows and higher operating temperatures in congested corridors.
High-temperature superconducting (HTS) cable systems are unifying fault-current limiting and power transmission functions in dense urban substations. Consolidated Edison and American Electric Power are piloting HTS installations in Manhattan and Columbus. This unifying architecture reduces right-of-way requirements by eliminating separate reactor infrastructure.
OSHA's updated electrical safety standards and NFPA 70E arc-flash requirements are mandating flame-retardant jacket compounds in industrial environments. Compound suppliers are reformulating halogen-free thermoplastic elastomers to meet both OSHA workplace safety and EPA environmental release thresholds. Petrochemical facilities on the Gulf Coast are replacing legacy PVC installations ahead of insurance renewal cycles.
Engineering-procurement-construction firms are consolidating cable specification authority, compressing distributor influence in utility-scale procurement. Burns & McDonnell and Quanta Services are embedding preferred manufacturer lists in master service agreements, displacing traditional electrical distributor bidding. This concentration is most visible in ERCOT and PJM interconnection projects where EPCs self-perform installation.
US Cables Market Segmentation
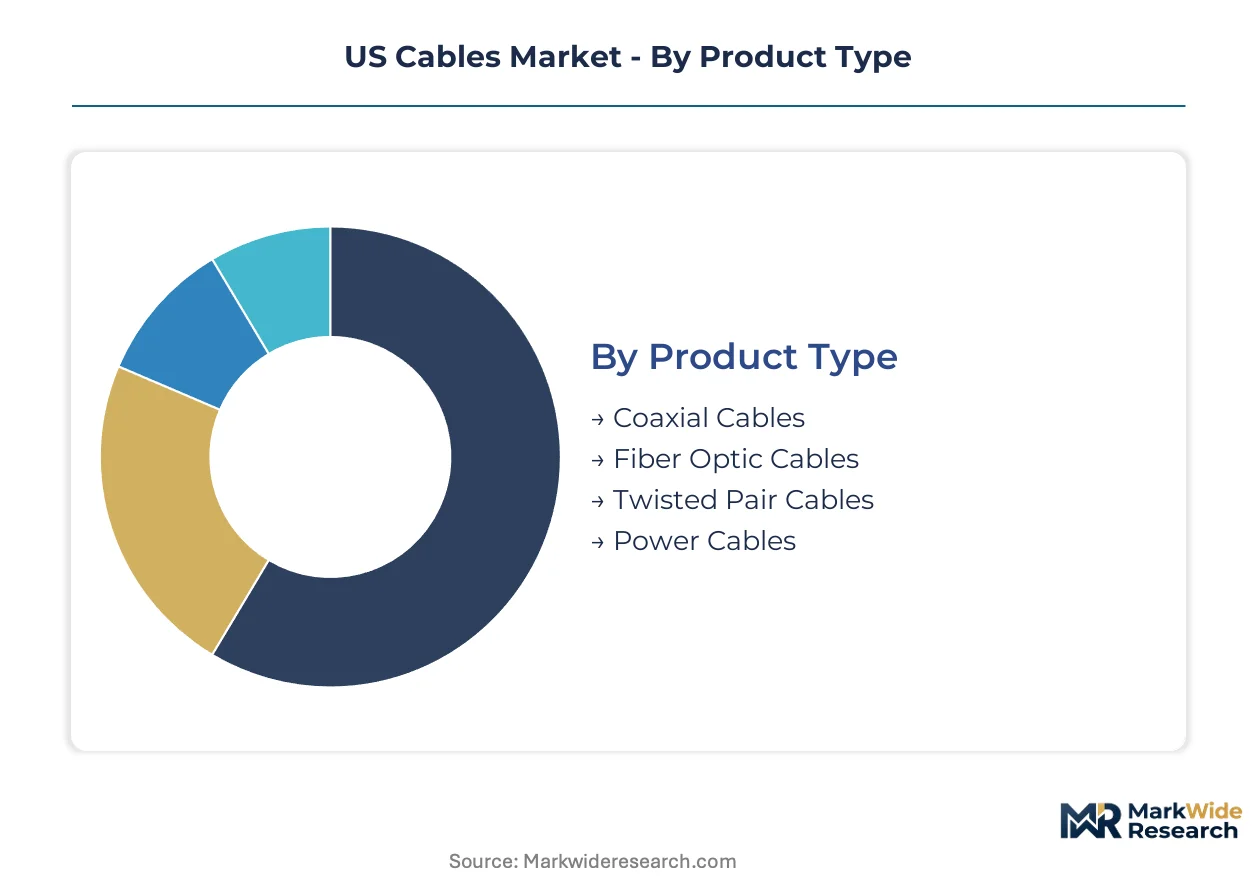
Segmentation in the US cables market reflects divergent technical specifications, regulatory exposure, and procurement economics across infrastructure verticals. Buyers prioritize voltage ratings, environmental hardening, and domestic content compliance depending on end-use application.
Product Type:
Buyers differentiate primarily by bandwidth requirements, power transmission capacity, and installation environment constraints.
- Power Cables:These conductors feature copper or aluminum cores insulated with cross-linked polyethylene or ethylene propylene rubber, rated from 600V distribution through 500kV transmission. Utility-scale solar and wind interconnection projects in Texas and California are concentrating procurement for high-voltage extruded cables as FERC Order 2023 accelerates queue processing.
- Fiber Optic Cables:Glass fiber strands transmit data via light pulses, with single-mode designs dominating long-haul and hyperscale data center applications. Northern Virginia and Phoenix metro areas are driving dense fiber count demand as rack densities exceed 50kW per unit and AI training clusters multiply interconnection requirements.
- Coaxial Cables:Center conductor designs with dielectric insulation and braided shielding retain niche broadband distribution roles.
- Twisted Pair Cables:Copper conductor pairs with varying twist rates support Ethernet and telephony in cost-constrained commercial retrofits.
Power cables lead volumes today; fiber optic cables are gaining share fastest.
Installation Type:
Site conditions and regulatory exposure determine whether specifications prioritize moisture resistance, mechanical protection, or aerial sag tolerance.
- Underground:Direct-burial and conduit-rated designs incorporate water-blocking tapes and armored jackets for soil contact and rodent protection. California and Florida public utility commissions are mandating undergrounding of wildfire-exposed distribution circuits, expanding medium-voltage demand across PG&E and FPL service territories.
- Outdoor:UV-stabilized jackets and temperature-rated compounds address aerial and pad-mounted transformer connections in exposed environments.
- Indoor:Plenum and riser-rated jackets meet NEC flame spread and smoke generation limits for building interiors.
- Aerial:Messenger-supported and self-supporting designs optimize right-of-way economics in rural transmission corridors.
Underground installations command premium pricing; outdoor specifications see the steepest expansion trajectory.
Material:
Conductivity requirements, weight constraints, and cost structures drive material selection across voltage classes.
- Copper:Electrolytic tough pitch and oxygen-free high-conductivity grades deliver maximum ampacity in constrained spaces. Domestic rod production concentrates in Arizona and Utah, creating geographic vulnerability to smelter outages that cable manufacturers with captive rod mills are positioned to mitigate.
- Aluminum:Lighter weight and lower cost per ampacity favor long-span transmission and large-conductor distribution applications.
- Fiber Glass:Strength members and dielectric components reinforce aerial and submarine cable mechanical performance.
- Plastic:Jacket compounds span PVC, polyethylene, and halogen-free thermoplastic elastomers meeting OSHA and EPA thresholds.
Copper dominates revenue value; aluminum is climbing the fastest on renewable interconnection tonnage.
End User:
Procurement sophistication and specification authority vary sharply between regulated utilities, private infrastructure developers, and industrial integrators.
- Energy:Investor-owned utilities, independent power producers, and grid-scale battery developers specify transmission and distribution infrastructure. ERCOT and CAISO interconnection queues for battery storage projects are multiplying medium-voltage collector cable requirements across Texas and California desert regions.
- Telecommunications:Wireless carriers and fiber network operators drive strand-count specifications for 5G backhaul and data center interconnects.
- Construction:Commercial and residential electrical contractors select building wire and low-voltage cabling based on NEC adoption cycles and local inspector familiarity.
- Automotive:Electric vehicle charging infrastructure and in-vehicle high-voltage harnesses impose thermal cycling and electromagnetic compatibility requirements.
Energy sector procurement leads absolute spend; telecommunications specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled extrusion technicians and specialized wire-drawing workforces cluster in Georgia, Arizona, and the industrial Midwest, anchoring domestic production capacity for high-voltage transmission and industrial cable manufacturing.
Texas
ERCOT interconnection queues for utility-scale solar and battery storage projects are multiplying medium-voltage collector cable demand across West Texas and the Panhandle. FERC Order 2023 accelerates transmission permitting timelines, compressing procurement cycles for 345kV extruded cables. Houston and Dallas-Fort Worth serve as procurement hubs where EPC firms consolidate specification authority for renewable zone infrastructure.
California
PG&E wildfire mitigation mandates are driving undergrounding of distribution circuits in high-fire-threat districts, expanding medium-voltage cable deployment across the Sierra Nevada foothills. California Public Utilities Commission rate-base approvals for grid hardening create predictable demand visibility through 2030. Silicon Valley hyperscale data centers and Central Valley solar projects concentrate procurement for both fiber optic and high-voltage power cables.
Southeast
Georgia-based copper rod production anchors vertically integrated cable manufacturing, with captive smelting capacity insulating against Arizona concentrate price volatility. Southwire Company's Carrollton operations exemplify this backward integration model. Florida Power & Light undergrounding mandates for hurricane resilience are expanding submarine and direct-burial cable demand along the Atlantic and Gulf coasts.
Midwest
PJM interconnection reform and Ohio-Indiana renewable energy zones are accelerating 500kV transmission procurement across the Corn Belt. Regional technical colleges in Michigan and Illinois struggle to scale high-voltage cable apprenticeship pipelines to match project demand. Chicago serves as a distribution hub where EPC master service agreements are displacing traditional electrical distributor bidding for utility-scale projects.
Southwest
Arizona copper concentrate smelting creates geographic vulnerability to outage-driven rod price spikes that cable manufacturers with captive supply chains mitigate. Phoenix metro hyperscale data centers are driving dense fiber count demand as AI training clusters multiply interconnection requirements. Nevada and Utah utility-scale solar projects concentrate procurement for aluminum conductor transmission cables across the desert Southwest.
US Cables Market Competitive Landscape
The competitive structure tilts toward vertically integrated manufacturers with captive copper rod and compounding capabilities. Three to five national-scale producers dominate high-voltage transmission and utility procurement, while regional specialists and industrial-cable focused players occupy mid-tier positions. Strategic archetypes include backward-integrated rod mill operators, submarine and HVDC specialists, and industrial ethernet focused manufacturers. Competitive moves center on Treasury Department domestic content qualification and EPC master service agreement embedding.
Among US-based integrated producers, Southwire Company and Encore Wire Corporation exemplify the captive supply chain archetype with in-house copper rod production. Prysmian Group occupies a position representing submarine and high-voltage specialization through continuous extrusion technology investment. Belden Inc. sits within the industrial connectivity tier, anchoring factory automation and process control cable portfolios. Nexans and LS Cable & System represent European and Korean-origin competitors respectively, competing on HVDC insulation chemistry and offshore wind export cable capabilities.
| Leading Market Players |
|---|
| Southwire Company |
| Prysmian Group |
| Belden Inc. |
| Encore Wire Corporation |
| Nexans |
| LS Cable & System |
| Amphenol Corporation |
| CommScope Holding Company |
| TE Connectivity |
| Others |
Pricing and Supply Chain Analysis
Family-owned cable manufacturers with multi-generational operational control anchor pricing discipline through captive copper rod production and long-term utility relationships. Their ownership structure insulates margin strategies from quarterly earnings pressure while enabling sustained investment in domestic compounding capacity that Treasury Department guidance now rewards.
Pricing Analysis
Bundled engineering-procurement-construction contracts dominate utility-scale procurement while unbundled distributor sales persist in commercial retrofit segments. Three-tier pricing structure across premium, standard, and economy levels separates HVDC submarine cables with decade-long warranties from commodity building wire. Price differentiation hinges on UL certification tier and volume scale, with hyperscale data center buyers commanding lowest unit economics. Cost compression in standard-voltage distribution cables is intensifying because Arizona smelter concentrate volatility feeds directly into rod pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand while electrical distributors serve contractor-driven commercial construction. Domestic copper rod production draws from Arizona and Utah smelters; cross-linked polyethylene compounding feeds from Gulf Coast petrochemical complexes. Supply chain risk centers on single-source vulnerability for specialized HVDC insulation resin. Distribution runs through EPC master service agreements that consolidate specification authority away from traditional distributor bidding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas-to-California arbitrage opportunities emerge from divergent ERCOT and CAISO interconnection queue processing speeds, compressing procurement timelines in Texas while California rate-base approvals extend demand visibility.
For Market Incumbents: Extend backward integration into copper rod production to capture Treasury Department domestic content bonuses before guidance crystallizes. Anchor EPC master service agreements in ERCOT and PJM territories where Burns & McDonnell and Quanta Services consolidate specification authority. Defend against Korean and European HVDC specialists by accelerating extrusion technician apprenticeship pipelines at regional technical colleges. For New Entrants and Emerging Players: E-commerce procurement platforms for industrial ethernet cables offer lowest barrier-to-entry given Belden Inc.'s channel concentration in factory automation. Target medium-voltage collector cable demand multiplying across Texas battery storage zones where incumbent capacity constraints create installation backlogs. Pursue power-over-ethernet convergence specifications that merge power transmission and data cabling for process control environments. For Investors and Strategic Acquirers: Electrical infrastructure-focused private equity is the most active acquirer in this space, rolling up regional distributors and specialty compounders ahead of Buy America threshold enforcement. Five-to-ten year viability hinges on captive copper supply chains and EPC relationship embedding. Monitor FERC interconnection queue reform implementation velocity as inflection indicator for transmission cable demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Copper Rod Integration | Qualifies manufacturers for Inflation Reduction Act domestic content bonuses Treasury Department calculates. |
| EPC Master Service Agreement Embedding | Consolidates specification authority with engineering-procurement-construction firms displacing distributor influence. |
| High-Voltage Extrusion Apprenticeship Scaling | Addresses decade-long technician pipelines that regional technical colleges have not matched to project demand. |
| Power-over-Ethernet Convergence R&D | Merges power transmission and data cabling specifications for factory automation process control environments. |
| Submarine Cable Installation Vessel Chartering | Mitigates global vessel scarcity constraining Atlantic Coast offshore wind export cable deployment. |
Research Methodology
Direct dialogue with utility procurement officers, EPC project managers, cable manufacturing plant engineers, and compound supplier technical directors grounded qualitative assessment. Secondary validation drew from FERC interconnection queue filings, EIA generation capacity data, SEC 10-K disclosures from listed manufacturers, and Treasury Department guidance documents. Bottom-up and top-down triangulation cross-checked regional demand clusters against national infrastructure investment patterns.
Analytical lens combined bottom-up project pipeline aggregation with top-down macro infrastructure spend allocation across the projection horizon. Segmentation dimensions modeled include voltage rating tier, installation environment specification, conductor material grade, and end-use vertical regulatory exposure. CAGRs were derived from installation volume trajectories indexed to interconnection queue processing rates and data center power density scaling assumptions.
The model assumes a particular technology adoption path; alternative pathways for high-temperature superconducting cable systems would alter the outlook if Consolidated Edison and American Electric Power pilots expand beyond Manhattan and Columbus substations. Forecasts reflect assumptions about FERC Order 2023 implementation velocity and state public utility commission undergrounding mandate adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Low Voltage Cable Accessories Market
Cables
Twisted Pair Cable Market
Cables
Submarine Cables Market
Cables
Anti-Static Space Wires Market
Cables
Polyurethane Cable Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Cable Tray Market
Cables
Copper Stranded Wire Market
Cables
Radio Frequency Cables Market
Cables
Cable Testers Market
Cables
Asia-Pacific Cable Joints Market
Cables
Data Center Wire and Cable Market
Cables
Usb Data Cable Market
Cables
Latin America Wire and Cable Market
Cables
EDM Wires Market
Cables
Cable Organisers Market