
 High-Speed Interconnects Market | 2026-2036
High-Speed Interconnects Market Size, Share, and Industry Trends Forecast 2026-2036
High-Speed Interconnects Market Foresight
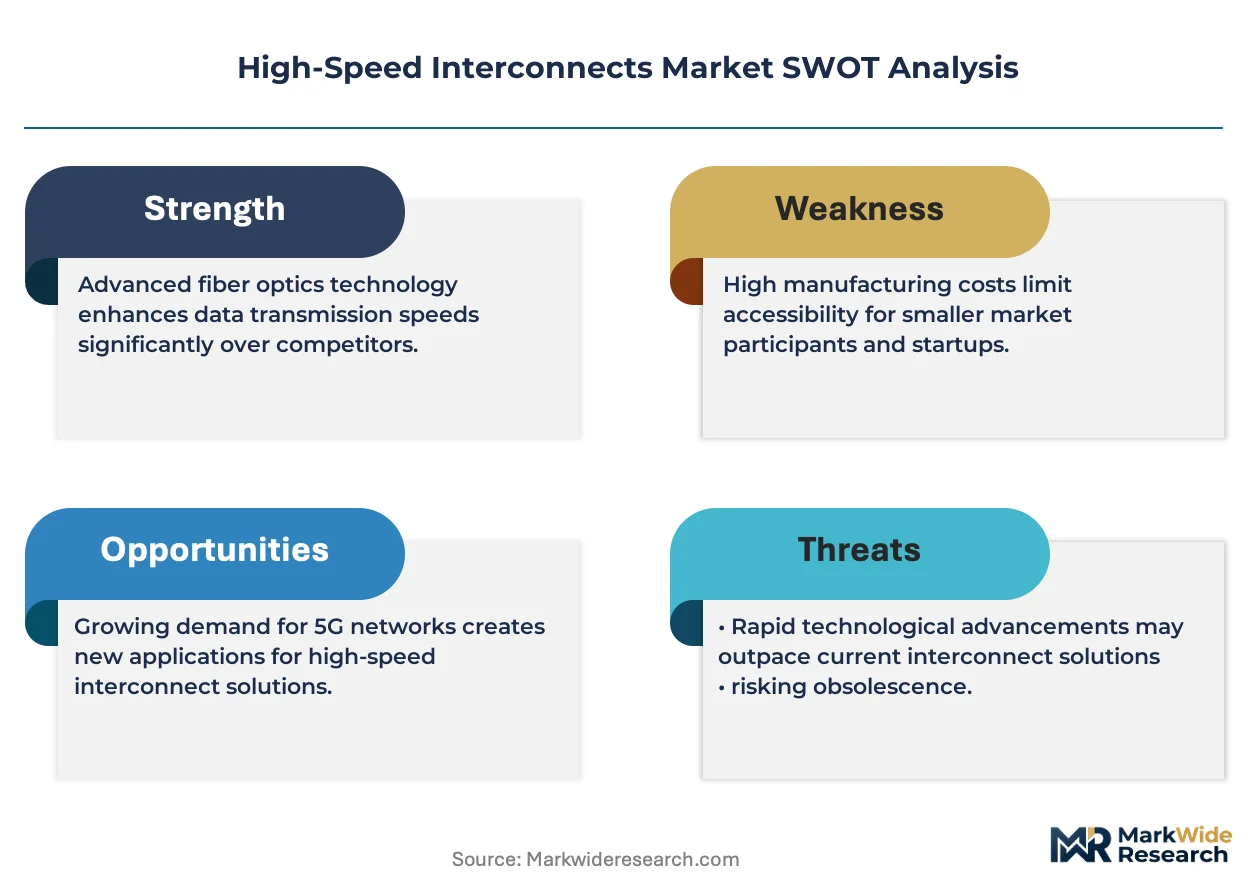
Platform licensing revenue is tilting toward optical and co-packaged interconnect ecosystems as data center architectures disaggregate. Broadcom leverages its merchant silicon position to extend reach into co-packaged optics. Intel sustains R&D intensity around PCI Express retimer and active electrical cable portfolios. Molex anchors high-volume manufacturing scale across backplane and cable assembly operations.
High-speed interconnects are signal transmission assemblies engineered to operate at data rates exceeding 56 Gbps per lane, employing differential signaling, controlled impedance substrates, and advanced materials such as low-Dk glass-reinforced laminates to preserve signal integrity across backplanes, cables, and chip-to-chip interfaces. Their primary purpose is to eliminate bandwidth bottlenecks between processors, memory, and networking silicon in compute-intensive systems. Active cables now capture expanding margin pools as thermal and reach limitations push copper solutions toward shorter channels, while fiber optic interconnects lead growth in hyperscale data center spine-leaf architectures where link distances exceed ten meters. PCI Express technology dominates server-internal connectivity, though Thunderbolt and USB segments compete for peripheral and consumer device attachment.
FCC equipment authorization rules govern electromagnetic emissions for U.S.-deployed interconnect hardware, while the EU RoHS directive and REACH framework restrict hazardous substance use in European-sold cable and connector assemblies. China's GB standards and MIIT certification requirements shape product formulations for the country's domestic server and telecommunications equipment procurement. Stakeholders must monitor evolving signaling standards from PCI-SIG and IEEE alongside material compliance deadlines to align roadmap investments with certification timelines.
Market Dynamics
Co-packaged optics adoption is compressing traditional pluggable transceiver architectures as hyperscale operators redesign rack-level thermal and density constraints. This architectural pivot forces interconnect suppliers to recalibrate assembly processes, test protocols, and material specifications simultaneously.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases in cooling systems accelerates liquid-cooled interconnect deployments in Frankfurt and Amsterdam data center clusters.
- Hyperscale spine-leaf expansion:Cloud operators in Northern Virginia and Singapore are installing fiber-rich backbones exceeding 400 Gbps per lane, pulling demand for active optical cables.
- Halogen-free substrate mandates:China's GB standards and RoHS-aligned procurement specifications redirect laminate sourcing toward low-Dk glass-reinforced alternatives.
Market Restraints
- Copper thermal ceiling:Passive direct-attach copper reaches physical bandwidth-distance limits below seven meters, forcing premature fiber conversion in mid-reach server-storage links.
- Optical component supply concentration:III-V semiconductor laser fabrication concentrates in Taiwan and Japan, exposing procurement timelines to single-source wafer constraints.
- REACH substance restrictions:ECHA candidate list expansions complicate flame-retardant formulations in cable jacketing, requiring reformulation cycles that extend qualification timelines.
Strategic Opportunities
- India sovereign cloud buildout:MEITY infrastructure incentives and domestic data localization mandates create captive demand for PCI Express retimers and active electrical cables.
- Co-packaged optics convergence:Silicon photonics integration with switch ASICs enables new merchant silicon entrants to bypass traditional pluggable module ecosystems.
- Direct liquid cooling attachment:Cold plate integration with high-density interconnect backplanes opens service contracts for thermal-mechanical co-design in Frankfurt and Singapore facilities.
Industry Challenges
- Signal integrity engineering scarcity:Specialists capable of 112 Gbps PAM4 channel simulation and equalization algorithm development command premium compensation, constraining R&D scaling.
- PCI-SIG certification backlog:Retimer and redriver compliance testing queue lengths at authorized labs extend product launch windows by four to six months.
- Legacy server refresh friction:Enterprise data centers running PCIe 4.0 infrastructure face forklift upgrade costs to accommodate 5.0 and 6.0 signaling rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Speed Interconnects Market |
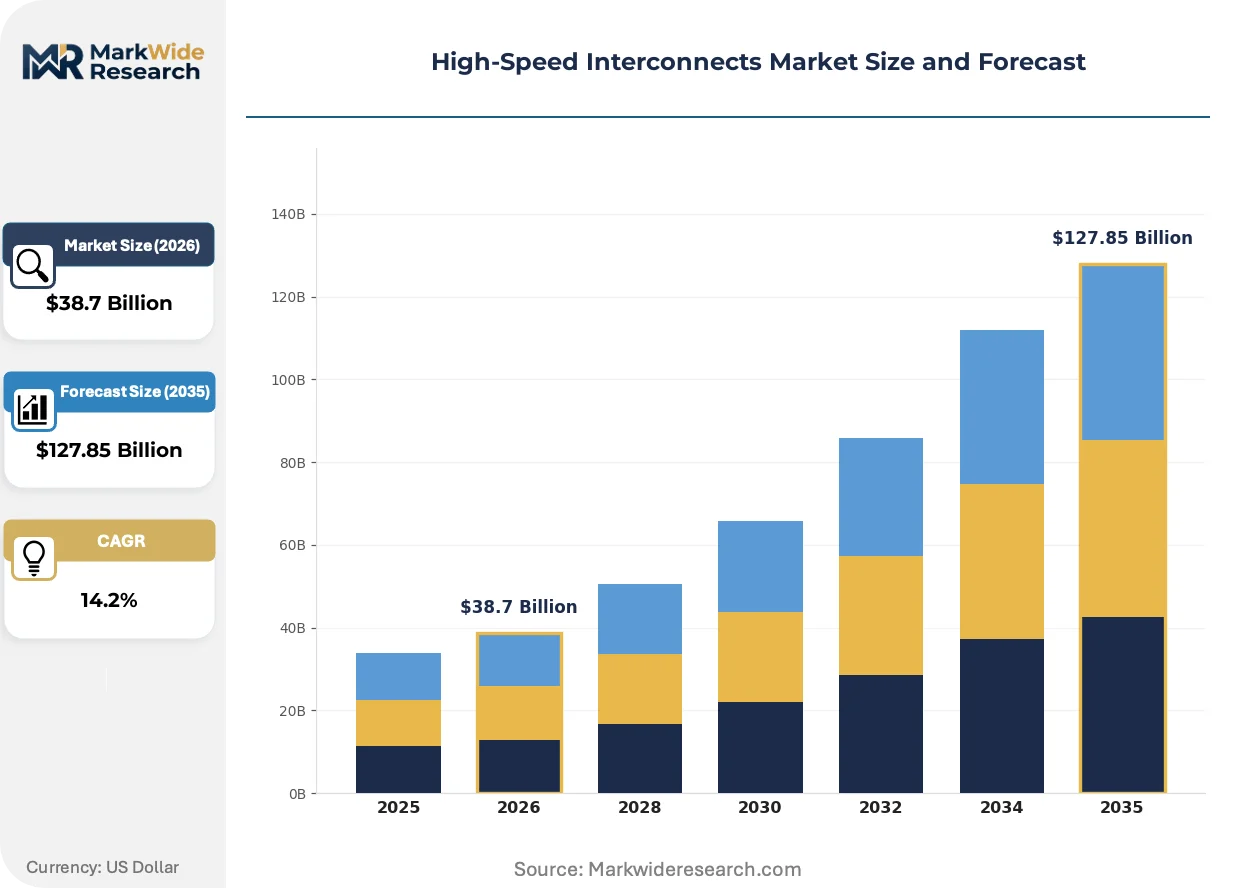
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Cables, Passive Cables, Fiber Optic, PCB Interconnects Technology: Thunderbolt, USB, HDMI, PCI Express Application: Data Centers, Telecommunications, Consumer Electronics, Automotive Systems End User: OEMs, Retailers, Enterprises, System Integrators |
| Companies Covered | Molex, Samtec, Broadcom, Sumitomo Electric Industries, Cisco Systems, Intel, TE Connectivity, Nexans, Amphenol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Speed Interconnects Market Shifts & Advancements
Photonic integration is collapsing the boundary between switch silicon and optical I/O, while regulatory chemistry constraints and procurement centralization reshape how interconnects are specified, tested, and deployed.
Linear-drive pluggable optics eliminate the DSP from transceiver modules, reducing power consumption by nearly half compared to retimed alternatives. Meta and Google infrastructure teams are qualifying these designs for 800 Gbps links in 2026 deployments. The stripped-down architecture is rendering obsolete the complex power-hungry retimer ecosystems that dominated 400 Gbps generation designs.
REACH Annex XIV additions now restrict short-chain chlorinated paraffins in cable jacketing compounds sold across EU member states. Compounders in Germany and France are accelerating halogen-free thermoplastic elastomer qualifications to maintain data center certification eligibility. Nordic operators with aggressive Scope 3 targets are demanding full material disclosure documentation upstream of assembly procurement.
Hyperscale direct sourcing is bypassing traditional distribution channels for high-volume optical transceiver and active cable contracts. Amazon Web Services and Microsoft Azure procurement teams now negotiate directly with contract manufacturers in Thailand and Vietnam for backplane assemblies. This disintermediation concentrates specification power in Seattle and Redmond engineering groups while compressing margin pools for value-added distributors.
High-Speed Interconnects Market Segmentation
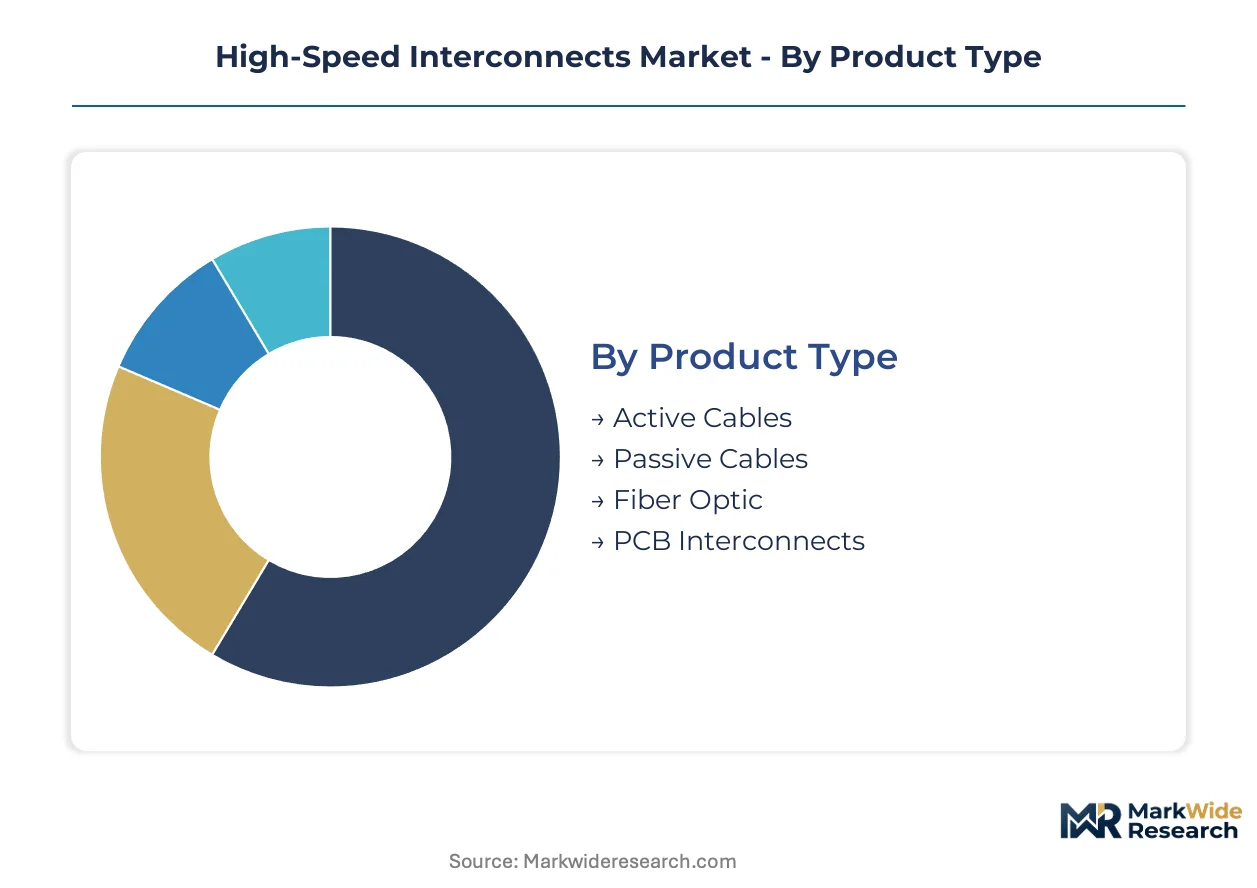
High-speed interconnect procurement patterns diverge sharply across deployment environments. Signal reach requirements, thermal budgets, and compliance frameworks reshape how suppliers configure product portfolios for each buyer category.
Product Type:
Signal integrity demands span from chip-to-chip links to kilometer-scale fiber runs.
- Active Cables:Signal conditioning electronics embedded within connector housings extend copper reach beyond passive limits. Hyperscale data centers in Northern Virginia and Singapore deploy these for 7-15 meter rack-to-rack connections where full optical conversion remains cost-prohibitive.
- Fiber Optic:Single-mode and multimode assemblies transmit at 400 Gbps and 800 Gbps across spine-leaf architectures. Frankfurt and Amsterdam facilities favor these for liquid-cooled environments where the EU F-Gas Regulation has accelerated thermal density upgrades.
- Passive Cables:Direct-attach copper maintains dominance in sub-3-meter server-storage links. Cost-sensitive enterprise data centers specify these for PCIe 5.0 internal connectivity.
- PCB Interconnects:Backplane and midplane assemblies route signals across server motherboard substrates. Intel and AMD reference designs dictate connector density specifications for ODM manufacturing in Taiwan.
Established volume favors passive cables; emerging adoption favors active cables.
Technology:
Protocol roadmaps determine bandwidth ceilings and backward compatibility requirements.
- PCI Express:The dominant server-internal interconnect protocol advances through 64 GT/s signaling rates. PCI-SIG certification queues for retimer and redriver components currently extend product launch timelines.
- Thunderbolt:Intel's royalty-bearing specification consolidates display and data transport for professional workstations. Creative production houses in Los Angeles and London specify these for external GPU and high-resolution monitor attachment.
- USB:Universal charging and peripheral attachment protocol spans consumer and enterprise environments. USB-IF compliance testing shapes connector mechanical specifications for cable assemblers in Dongguan.
- HDMI:Display interface protocol for consumer electronics and digital signage. Gaming monitor manufacturers in Shenzhen drive demand for 2.1 specification cables supporting 48 Gbps bandwidth.
PCI Express commands the largest installed base; Thunderbolt claims the steepest expansion trajectory in professional segments.
Application:
End-use thermal and density constraints dictate material and form factor selection.
- Data Centers:Hyperscale and colocation facilities consume the highest interconnect volumes per square meter. Co-packaged optics redesigns are compressing traditional pluggable transceiver architectures in these environments.
- Telecommunications:5G fronthaul and midhaul networks require weatherized optical assemblies. China's MIIT certification requirements govern product formulations for domestic base station deployments.
- Consumer Electronics:Laptop and smartphone manufacturers prioritize thin-profile cable assemblies. REACH Annex XIV restrictions on chlorinated paraffins are forcing compound reformulations for EU-bound products.
- Automotive Systems:In-vehicle infotainment and ADAS sensor networks demand vibration-resistant connectors. German OEMs specify these for zonal E/E architectures in electric vehicle platforms.
Data centers absorb the premium margin pool; automotive systems present the longest qualification cycles.
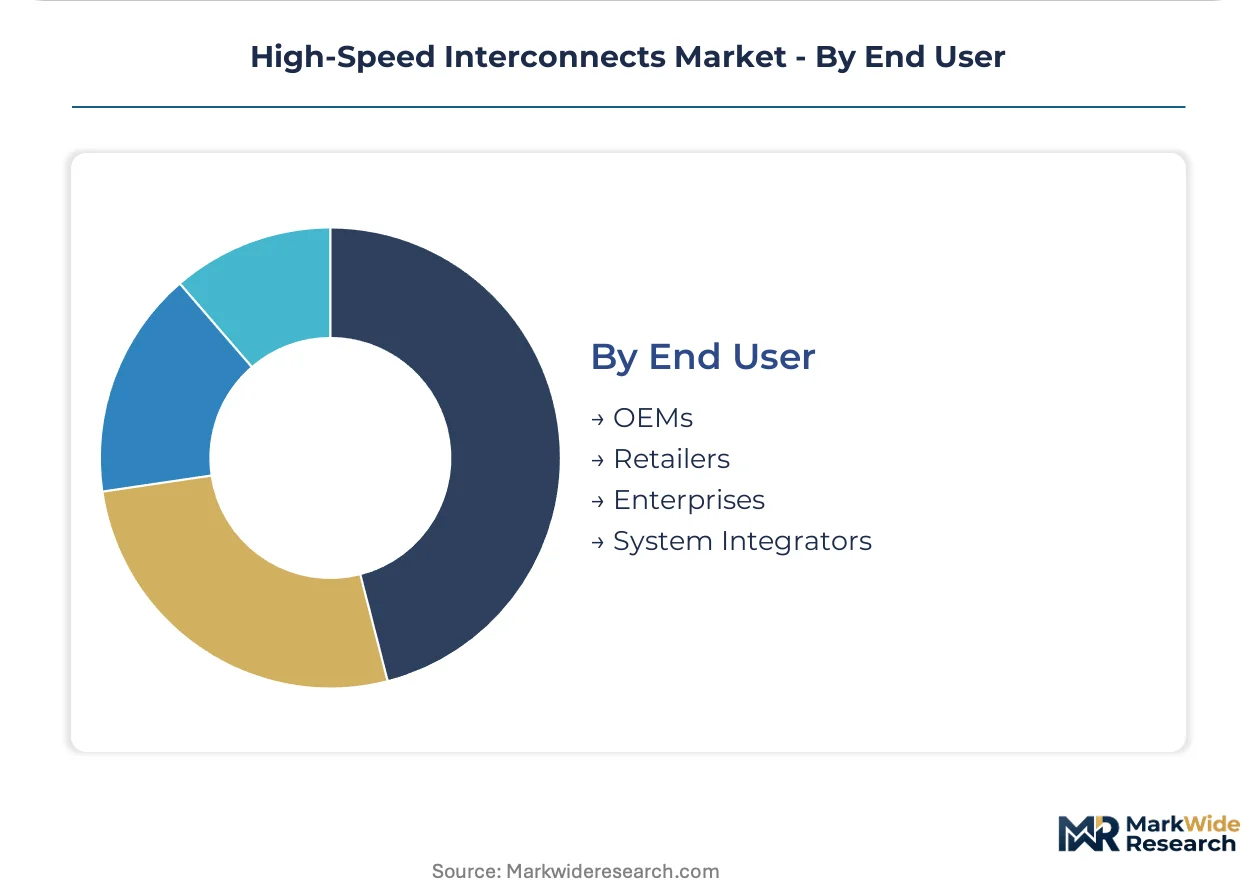
End User:
Procurement centralization and technical specification authority vary across buyer types.
- OEMs:Original equipment manufacturers wield direct specification power over connector and cable vendors. Dell and HPE engineering teams in Texas and California set mechanical and electrical requirements for ODM partners.
- Enterprises:Corporate IT departments purchase through distribution for retrofit and expansion projects. These buyers prioritize backward compatibility with existing PCIe 4.0 infrastructure.
- System Integrators:Value-added resellers configure custom server and storage solutions. Indian integrators serving MEITY sovereign cloud projects are sourcing PCI Express retimers in rising volumes.
- Retailers:Consumer-facing channels stock standardized cable lengths for aftermarket replacement. Amazon and Best Buy assortments concentrate on USB and HDMI specifications.
OEMs concentrate engineering influence; system integrators are gaining share fastest in emerging buildout markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale operators in Northern Virginia exhibit the lowest price sensitivity for optical interconnects, while European colocation buyers in secondary markets face compressed procurement budgets under energy cost pressures.
United States
Cloud infrastructure expansion in Northern Virginia and Dallas-Fort Worth drives demand for 800 Gbps active optical cables. FCC equipment authorization rules govern electromagnetic emissions for deployed hardware. Seattle and Redmond engineering teams now negotiate directly with Asian contract manufacturers, bypassing traditional distribution channels.
China
Domestic server production for sovereign compute infrastructure accelerates PCI Express retimer consumption. MIIT certification requirements and GB standards shape product formulations for telecommunications equipment. Yangtze River Delta manufacturing clusters in Suzhou and Shanghai dominate backplane assembly output for global ODM partners.
Germany
Frankfurt and Amsterdam data center clusters prioritize liquid-cooled interconnect deployments under EU F-Gas Regulation phasedown timelines. ECHA REACH restrictions on chlorinated paraffins force cable jacketing reformulations. Bavarian compounders accelerate halogen-free thermoplastic elastomer qualifications to maintain certification eligibility.
India
MEITY infrastructure incentives and data localization mandates create captive demand for PCI Express retimers and active electrical cables. Domestic certification requirements from BIS shape product testing protocols. Karnataka and Telangana data center corridors near Bangalore and Hyderabad attract hyperscale buildouts requiring high-density interconnect backplanes.
Japan
III-V semiconductor laser fabrication concentrates in Tokyo-Osaka industrial corridors, exposing procurement timelines to single-source wafer constraints. METI industrial policy supports silicon photonics R&D investments. Yokohama and Osaka facilities supply critical optical components for 400 Gbps and 800 Gbps transceiver modules.
High-Speed Interconnects Market Competitive Landscape
Merchant silicon specialists and precision connector fabricators split the market into distinct capability zones. The vendor base concentrates around three strategic tiers: integrated component suppliers controlling ASIC and photonics convergence, high-volume assembly houses scaling backplane manufacturing, and specialized cable compounders managing material compliance. Dominant competitive moves include co-packaged optics partnerships with hyperscale operators and backward integration into halogen-free substrate supply.
Within the integrated component tier, Broadcom and Intel exemplify divergent strategic postures. Broadcom occupies a position extending merchant silicon reach into co-packaged optics ecosystems. Intel anchors R&D intensity around PCI Express retimer portfolios. Molex sits within the high-volume manufacturing archetype, scaling backplane and cable assembly operations across global facilities.
| Leading Market Players |
|---|
| Molex |
| Samtec |
| Broadcom |
| Sumitomo Electric Industries |
| Cisco Systems |
| Intel |
| TE Connectivity |
| Nexans |
| Amphenol |
| Others |
Supply & Pricing Matrix
Shanghai-Ningbo container corridor freight volatility feeds directly into landed cost spreads between Taiwan-sourced photonics and Vietnam-assembled cable harnesses, compressing margin pools for distributors while amplifying specification power for hyperscale buyers negotiating direct with contract manufacturers.
Pricing Analysis
Service contract and thermal-mechanical co-design revenue now drives lifetime value differentiation across interconnect portfolios. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled backplane assemblies with direct cold plate integration from passive copper alternatives. Cost compression in active optical cable tiers is intensifying because hyperscale procurement teams in Seattle and Redmond negotiate direct with Asian contract manufacturers, bypassing traditional distribution markups. Enterprise data centers running legacy PCIe 4.0 infrastructure exhibit the highest price sensitivity, while Northern Virginia hyperscale operators show minimal elasticity for 800 Gbps fiber deployments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for backplane assembly procurement. Manufacturing concentrates in Taiwan, Vietnam, and Thailand for high-volume cable and connector output. III-V semiconductor laser fabrication rests on single-source wafer supply from Tokyo-Osaka industrial corridors, while low-Dk glass-reinforced laminate sourcing is tethered to Yangtze River Delta chemical processing clusters. Logistics chokepoint vulnerability concentrates in Shanghai-Ningbo port congestion and Taiwan Strait maritime routing. Distribution runs through direct hyperscale procurement channels that disintermediate traditional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against silicon photonics substitution that collapses traditional pluggable transceiver architectures into co-packaged switch ASIC designs, eroding the discrete module ecosystem that has sustained merchant interconnect suppliers for two decades.
For Market Incumbents: Insulate core backplane and retimer franchises through backward integration into halogen-free substrate supply, securing laminate allocation priority as EU REACH restrictions tighten compound formulations. Deepen captive supply of PCI Express redriver silicon to offset margin compression from linear-drive pluggable optics adoption by Meta and Google infrastructure teams. Prioritize certification investment at PCI-SIG authorized labs to compress four-to-six month compliance queues that currently delay product launches. For New Entrants and Emerging Players: Establish a beachhead in India's MEITY sovereign cloud buildout, where domestic data localization mandates and BIS certification requirements create procurement friction that favors local system integrators over established global suppliers. Target PCI Express retimer demand in Karnataka and Telangana data center corridors near Bangalore and Hyderabad, positioning active electrical cable assemblies for liquid-cooled rack architectures. Pursue channel partnerships with Indian value-added resellers serving government cloud tenders rather than competing head-to-head with Broadcom and Intel direct sales operations. For Investors and Strategic Acquirers: Merchant silicon specialists with co-packaged optics roadmaps represent the most defensible acquisition archetype in a five-to-ten year window where photonic integration collapses traditional module boundaries. Signal integrity engineering talent scarcity commands premium compensation and constrains R&D scaling for all but the largest incumbents. Watch for inflection when PCI-SIG publishes PCIe 7.0 signaling specifications, which will force forklift upgrades across enterprise data centers still operating PCIe 4.0 infrastructure and trigger replacement demand for active cable and retimer components.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Partnership | Silicon photonics integration with switch ASICs enables bypass of traditional pluggable module ecosystems at hyperscale operators. |
| Halogen-Free Substrate Backward Integration | Captive supply of low-Dk glass-reinforced laminates secures allocation priority under EU REACH and China GB standard compliance deadlines. |
| Liquid-Cooled Backplane Service Contract | Thermal-mechanical co-design agreements with Frankfurt and Singapore facilities open recurring revenue streams beyond component sales. |
| PCI-SIG Certification Pre-Investment | Reserved testing slots at authorized labs compress four-to-six month compliance queues that currently extend product launch windows. |
| India System Integrator Channel Partnership | MEITY sovereign cloud procurement through local value-added resellers navigates BIS certification friction for foreign suppliers. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with data center infrastructure engineers, PCI-SIG working group participants, compound semiconductor procurement leads, thermal-mechanical design specialists, and hyperscale supply chain managers informed demand-side assumptions. Secondary sources include FCC equipment authorization databases, ECHA REACH candidate list updates, MIIT certification registries, PCI-SIG compliance testing records, and hyperscaler capital expenditure disclosures. Bottom-up segment sizing triangulates against top-down infrastructure investment forecasts across the analysis window.
Calibration against historical adoption curves for PCIe 4.0 through 6.0 signaling transitions shapes the projection framework. The model segments by product type, technology protocol, application environment, and end-user procurement authority, with additional disaggregation by thermal architecture and compliance jurisdiction. CAGRs derive from fitted diffusion curves applied to hyperscale capex trajectories and sovereign infrastructure incentive allocations. Key inputs include III-V semiconductor wafer supply constraints, PCI-SIG specification roadmaps, and EU F-Gas Regulation phasedown timelines affecting liquid-cooled deployment rates.
Sensitivities concentrate around silicon photonics substitution velocity, Taiwan-Japan laser fabrication supply disruptions, and REACH Annex XIV expansion scope affecting cable jacketing formulations. Forecasts embed assumptions about PCI Express retimer demand persistence against linear-drive pluggable optics displacement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Organisers Market
Cables
Submarine Cable System Market
Cables
XLPE Cables Market
Cables
Europe Cable Joints Market
Cables
SATA Power Cable Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Middle East Cable Market
Cables
Europe Cable Accessories Market
Cables
Multicore Cables Market
Cables
Submarine Cabling Systems Market
Cables
EPR Cable Market
Cables
Downhole Cables Market
Cables
Instrumentation Cables Market
Cables
United States Cable Accessories Market
Cables
Low-Temperature Cable Market
Cables
Global Cable Blowing Equipment Market