
 Cloud IT Infrastructure Hardware Market | 2026-2036
Cloud IT Infrastructure Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud IT Infrastructure Hardware Market Outlook
Enterprise-grade server specifications with liquid cooling compatibility and NVMe-oF support is redrawing procurement priorities across hyperscale and colocation buyers. Dell Inc. leverages its integrated supply chain to dominate rack server shipments into North American cloud campuses. Hewlett Packard Enterprise Development LP anchors its position through specialized blade server architectures optimized for high-performance computing densities. Intel Corporation competes on semiconductor process leadership, though its foundry strategy navigates mounting capital intensity.
Cloud IT infrastructure hardware encompasses the physical compute, storage, and networking equipment deployed in data centers to deliver virtualized computing resources over networks, typically operating at 48V DC power with chassis designed for N+1 redundancy and hot-swappable components. Servers represent the largest product type segment by installed base, while hyper-converged infrastructure captures margin pools through integrated software-defined management layers. Rack servers sustain volume leadership among technology variants, though cloud storage solutions are expanding fastest as object storage tiers displace traditional SAN architectures in AI training pipelines.
The EPA Energy Star program and the EU F-Gas Regulation are tightening environmental performance standards for cooling systems and refrigerants used in data center infrastructure, directly shaping equipment specifications and import compliance costs. The FCC governs electromagnetic emissions from networking hardware sold into US facilities, while ISO 27001 certification requirements from enterprise buyers filter vendor eligibility across procurement shortlists. Stakeholders must weigh capital deployment timing against evolving efficiency mandates and silicon supply constraints as workload specialization accelerates.
Market Dynamics
Generative AI workload density is forcing hyperscale operators to re-architect power and cooling specifications, compressing procurement cycles for liquid-cooled chassis while tightening supplier qualification timelines.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates for power usage effectiveness in new data center installations accelerate replacement cycles for legacy air-cooled infrastructure across European cloud campuses.
- Hyperscale AI training clusters:Demand for GPU-dense server configurations concentrates procurement volume among operators building multi-gigawatt facilities in the United States.
- NVMe-oF protocol adoption:Storage-class memory fabrics reduce latency bottlenecks in AI inference pipelines, pulling infrastructure refresh budgets toward composable disaggregated architectures.
Market Restraints
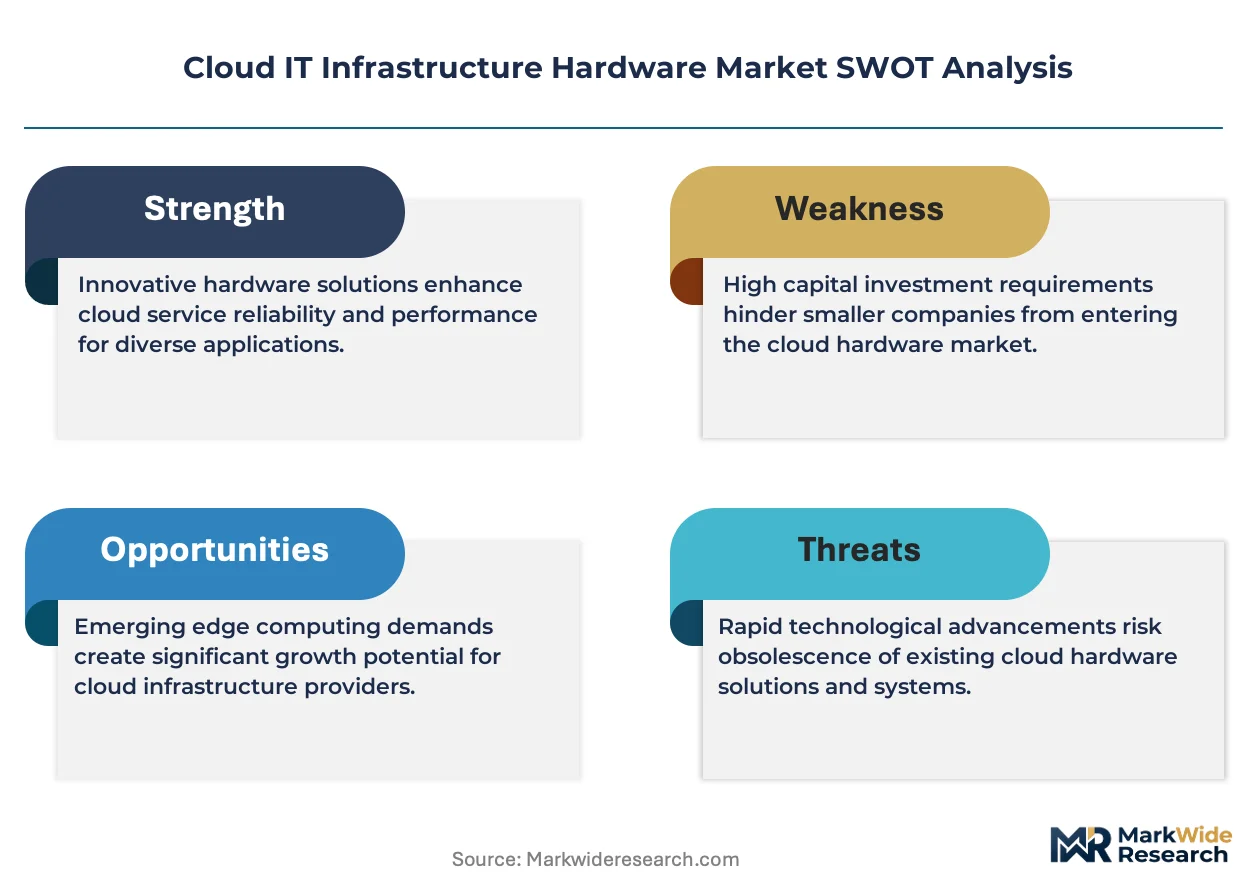
- Silicon supply concentration:Advanced node semiconductor fabrication clusters in Taiwan create single-point-of-failure exposure for high-performance server CPU and GPU availability.
- Copper and rare earth price volatility:Raw material input swings for power distribution units and magnet-based cooling compressors squeeze margin predictability for rack-level system integrators.
- EU F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon refrigerants limit retrofit options for existing chiller plants, extending depreciation timelines for older facilities.
Strategic Opportunities
- India cloud infrastructure buildout:Data center capacity expansion in Mumbai and Hyderabad creates greenfield procurement windows for modular prefabricated power and cooling modules.
- Edge AI inference nodes:Distributed micro-data centers for autonomous systems and industrial IoT pull demand for ruggedized, thermally-optimized compact server form factors.
- ISO 27001 certification differentiation:Enterprise buyers filter vendor eligibility through information security management mandates, creating margin capture for pre-certified equipment suppliers.
Industry Challenges
- Liquid cooling engineering talent scarcity:Specialized thermal design and direct-to-chip plumbing expertise concentrates among a narrow pool of system architects, extending deployment timelines.
- DC power distribution retrofit complexity:Legacy 208V AC facilities face stranded asset risk when migrating to 48V DC bus architectures for GPU-intensive racks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud IT Infrastructure Hardware Market |
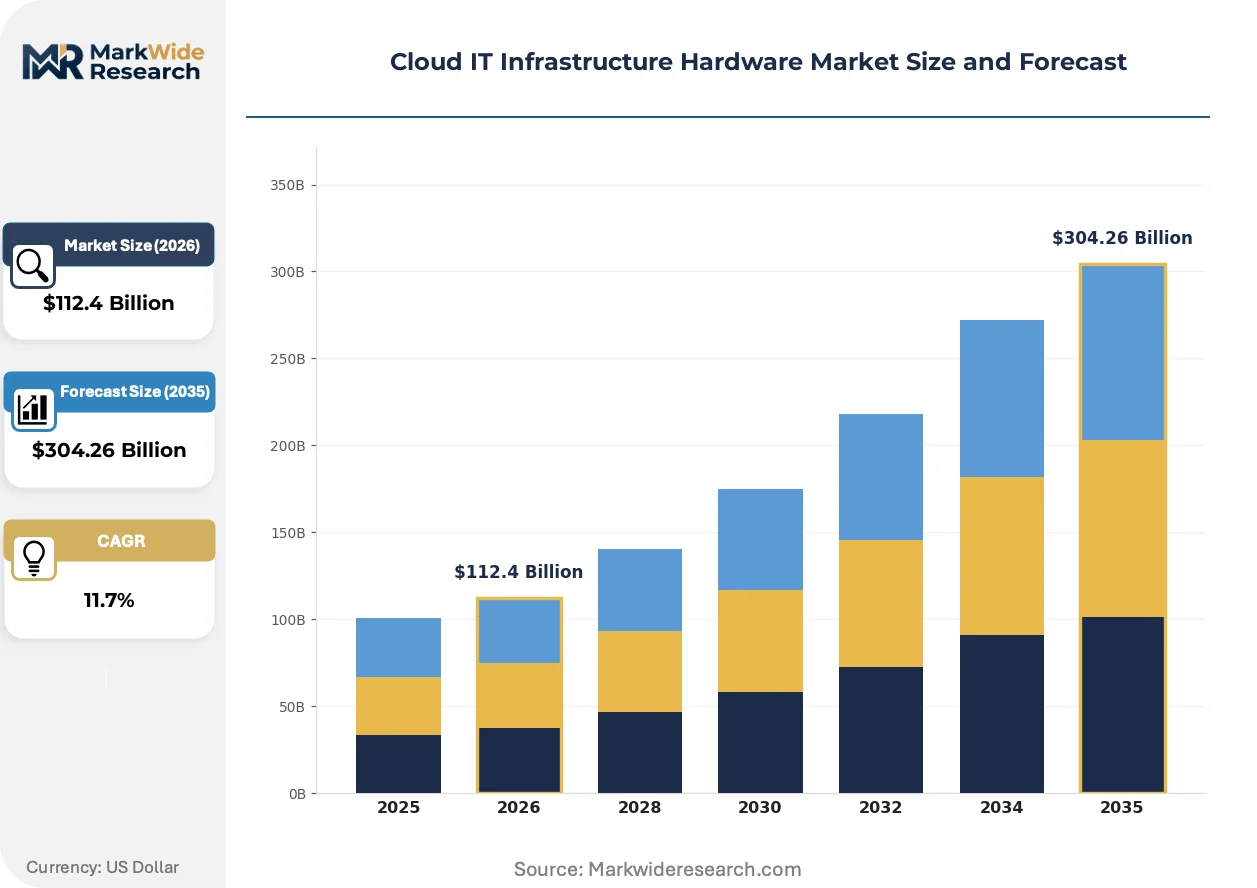
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $304.26 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servers, Switches, Routers, Storage Devices Technology: Blade Servers, Rack Servers, Hyper-Converged Infrastructure, Cloud Storage Solutions End User: Businesses, Service Providers, Government Agencies, Educational Institutions Deployment: On-Premises, Off-Premises, Hybrid Cloud, Multi-Cloud |
| Companies Covered | Amazon Web Services, Inc., Hewlett Packard Enterprise Development LP, Dell Inc., IBM Corporation, Cisco Systems, Inc., Intel Corporation, Oracle Corporation, Lenovo Group Ltd., NetApp Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud IT Infrastructure Hardware Market Strategic Shifts
Hardware abstraction layers and software-defined control planes are decoupling physical infrastructure from workload placement, enabling resource pooling that stretches refresh cycles while demanding new supplier capabilities.
Composable disaggregated infrastructure is decomposing server, storage, and networking resources into independently scalable pools connected via PCIe fabrics and CXL memory coherence. Hyperscale operators in the United States are deploying these architectures at rack scale to improve GPU utilization rates. The approach compresses traditional three-year server replacement cycles by allowing component-level upgrades without chassis swaps.
REACH substance restrictions and the EU F-Gas Regulation are tightening material compliance for cooling systems and electronic components sold into European facilities. Equipment vendors must reformulate thermal interface materials and transition to natural refrigerant loops. Rack-level system integrators face elongated qualification timelines as they certify new supply chains against evolving substance thresholds.
Enterprise buyers are consolidating procurement authority through cloud-adjacent colocation partners rather than direct OEM relationships. Channel intermediaries with integrated deployment and managed services capabilities capture margin pools previously retained by hardware manufacturers. This pattern concentrates most visibly in financial services verticals across Germany and the United Kingdom, where compliance-heavy buyers outsource infrastructure lifecycle management.
Cloud IT Infrastructure Hardware Market Segmentation
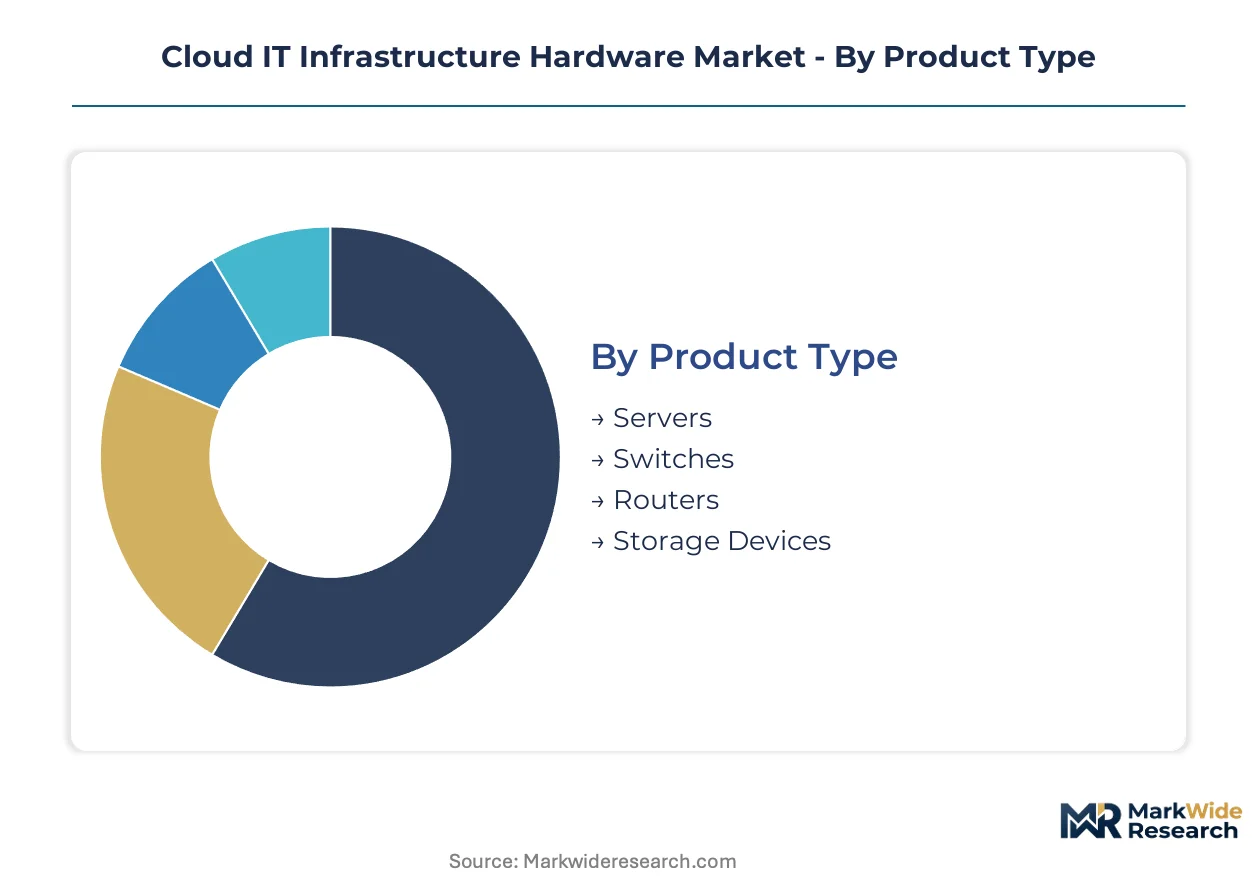
Workload specialization and efficiency mandates are fragmenting procurement patterns across hardware categories. Buyers now segment investments by thermal density, software-defined manageability, and compliance posture rather than raw compute metrics alone.
Product Type:
Margin pools concentrate in storage-class memory and high-throughput switching silicon where supply constraints sustain pricing power.
- Servers:CPU and GPU chassis with liquid cooling compatibility dominate hyperscale procurement volumes. Demand clusters in United States multi-gigawatt campuses where generative AI training clusters require 100kW+ rack densities.
- Storage Devices:NVMe-oF arrays and object storage tiers displace legacy SAN architectures in AI inference pipelines. Procurement accelerates where EPA Energy Star efficiency thresholds filter vendor shortlists for federal cloud deployments.
- Switches:High-radix Ethernet fabrics for east-west traffic in GPU clusters.
- Routers:Inter-campus and DCI connectivity hardware for distributed training workloads.
The dominant share belongs to Servers, while Storage Devices is closing the gap fastest.
Technology:
Adoption velocity splits between established form factors and disaggregated architectures that stretch refresh cycles.
- Rack Servers:Standard 19-inch chassis sustain volume leadership through backward compatibility with legacy data center footprints. Procurement concentrates among colocation operators in Germany and the United Kingdom seeking ISO 27001-certified hardware for financial services tenants.
- Hyper-Converged Infrastructure:Software-defined compute-storage fusion captures margin through integrated lifecycle management. Demand pulls from educational institutions and mid-market businesses outsourcing infrastructure operations to channel partners.
- Blade Servers:High-density modular architectures for HPC density requirements.
- Cloud Storage Solutions:Object and file services optimized for unstructured data growth.
Rack Servers retain installed base leadership, though Hyper-Converged Infrastructure expands most quickly at the edge.
End User:
Procurement authority consolidation through intermediaries is redistributing margin between direct OEM and managed service channels.
- Service Providers:Hyperscale and colocation operators aggregate demand for multi-gigawatt campus builds. United States cloud providers drive GPU-dense server specifications while filtering vendors through FCC electromagnetic emissions compliance for networking hardware.
- Businesses:Enterprise buyers in financial services verticals outsource lifecycle management to cloud-adjacent colocation partners. Procurement shifts from direct OEM relationships to channel intermediaries with integrated deployment capabilities.
- Government Agencies:Federal and state entities with mandated efficiency and security certifications.
- Educational Institutions:Research universities with HPC and AI training requirements.
Service Providers command the largest procurement volume, while Businesses are migrating fastest to as-a-service consumption models.
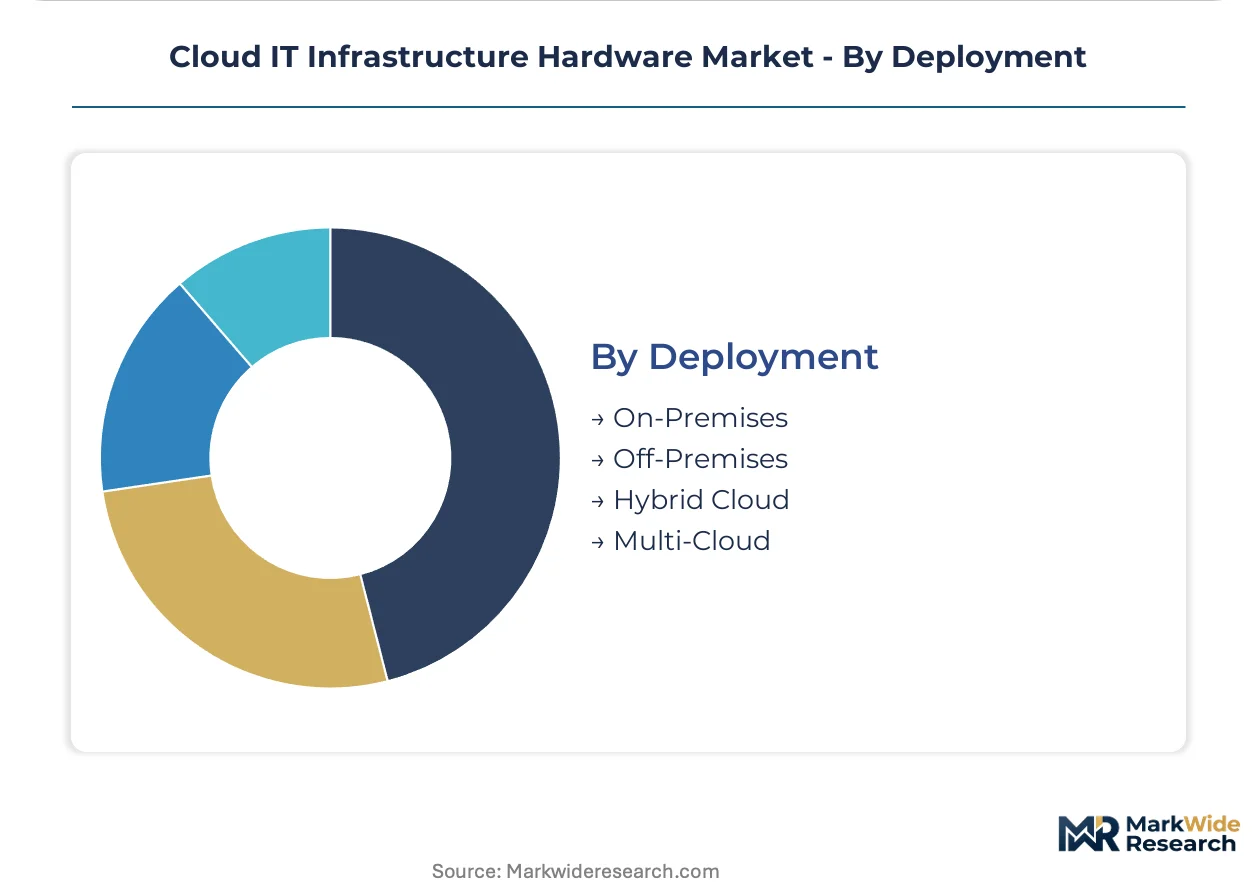
Deployment:
Physical infrastructure location decisions increasingly hinge on power availability, regulatory jurisdiction, and latency requirements rather than capital efficiency alone.
- Off-Premises:Third-party data center and public cloud capacity absorbs GPU-intensive workloads unsuited to legacy facility power densities. EU Energy Efficiency Directive mandates accelerate European migration from on-premises air-cooled infrastructure.
- Hybrid Cloud:Split workload placement between owned facilities and public cloud enables compliance-sensitive data to remain on-premises while burst compute shifts off-site. Demand concentrates among regulated industries navigating GDPR data residency requirements.
- On-Premises:Retained for latency-critical or classified workloads in government and defense.
- Multi-Cloud:Distributed deployment across competing hyperscale providers for vendor risk mitigation.
Off-Premises deployment holds the dominant share, while Hybrid Cloud configurations are gaining share fastest among regulated enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced node semiconductor fabrication clusters in Taiwan concentrate supply-side risk for high-performance server components. Hyperscale operators are diversifying procurement across multiple geographies to mitigate single-point-of-failure exposure. Demand patterns split between AI training cluster buildouts and efficiency-mandated infrastructure replacement cycles.
United States
Multi-gigawatt campus construction by cloud providers drives GPU-dense server procurement volumes. The EPA Energy Star program filters vendor eligibility for federal cloud deployments through mandated efficiency thresholds. Northern Virginia and Phoenix data center clusters absorb the majority of hyperscale capacity expansion.
Germany
Financial services verticals outsource infrastructure lifecycle management to cloud-adjacent colocation partners. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in cooling system retrofits. Frankfurt and Berlin facilities face elongated qualification timelines for new thermal interface material certifications.
China
Domestic cloud providers accelerate server procurement for generative AI training clusters. MIIT governs electromagnetic emissions standards for networking hardware deployed in state-owned facilities. Yangtze River Delta data center clusters concentrate capacity expansion around Shanghai and Hangzhou.
India
Mumbai and Hyderabad data center buildouts create greenfield procurement windows for modular power and cooling modules. The CEA mandates power distribution standards for new facility interconnects. Karnataka's Bangalore cluster attracts hyperscale operator investment for AI inference workload placement.
United Kingdom
Enterprise buyers consolidate procurement authority through managed service intermediaries rather than direct OEM relationships. GDPR data residency requirements pull hybrid cloud deployment decisions toward domestic facilities. London and Slough data center corridors concentrate colocation capacity for regulated industries.
Cloud IT Infrastructure Hardware Market Competitive Environment
Concentration sits with integrated system vendors possessing captive supply chains and direct hyperscale relationships. The vendor base stratifies across three tiers: full-stack infrastructure providers, component specialists, and channel-anchored system integrators. Strategic moves center on liquid cooling engineering acquisitions and modular data center partnership structures to capture greenfield deployment windows.
Among integrated infrastructure providers, Dell Inc. and Hewlett Packard Enterprise Development LP exemplify the full-stack archetype through rack and blade server portfolios. Intel Corporation occupies a position as the semiconductor process anchor whose foundry strategy navigates capital intensity pressures. These three entities represent the dominant competitive anchors shaping procurement specifications and supplier qualification timelines across hyperscale and enterprise segments.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Hewlett Packard Enterprise Development LP |
| Dell Inc. |
| IBM Corporation |
| Cisco Systems, Inc. |
| Intel Corporation |
| Oracle Corporation |
| Lenovo Group Ltd. |
| NetApp Inc. |
| Others |
Value Chain & Pricing Dynamics
EPA Energy Star certification gates both hyperscale vendor qualification and price differentiation across server tiers, compressing margins for air-cooled legacy suppliers while sustaining premiums for liquid-cooled chassis meeting federal efficiency thresholds. The interplay between regulatory compliance costs and procurement volume concentration shapes how rack-level system integrators negotiate component sourcing against finished-system pricing power.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by imposing refrigerant phase-down costs that separate premium natural-cooling systems from standard retrofit-limited equipment. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 27001 certification status, liquid cooling compatibility, and NVMe-oF integration depth. Cost compression in standard-tier rack servers is intensifying because copper and rare earth price volatility squeezes power distribution unit margins. Colocation operators in Germany and the United Kingdom demonstrate highest price sensitivity due to outsourced lifecycle management contracts, while United States hyperscale campus builders absorb premium pricing for GPU-dense configurations.
Supply Chain Analysis
Strategic stockpiling of advanced node semiconductors dominates inventory strategy over just-in-time approaches as Taiwan fabrication concentration creates single-point-of-failure exposure for CPU and GPU availability. Supply draws from Taiwan, South Korea, and the United States for high-performance silicon, with copper busbars and rare earth magnets for cooling compressors sourced from China and Australia. Tariff exposure on networking hardware components imported under FCC electromagnetic emissions compliance requirements threatens margin predictability. Distribution runs through direct OEM relationships for hyperscale operators and channel-anchored system integrators for enterprise buyers outsourcing infrastructure lifecycle management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from efficiency-mandated replacement cycle compression as EU Energy Efficiency Directive deadlines force infrastructure refresh decisions. Capital deployment timing now favors suppliers with pre-certified liquid cooling portfolios.
For Market Incumbents: Consolidate liquid cooling engineering capabilities through specialized thermal design acquisitions before talent scarcity extends deployment timelines further. Lock in multi-year supply agreements for advanced node semiconductors from Taiwan and South Korea fabrication clusters to defend against single-source vulnerability. Channel control through integrated deployment partnerships with cloud-adjacent colocation operators captures margin pools migrating away from direct OEM relationships. For New Entrants and Emerging Players: ISO 27001 certification fast-track positions emerging suppliers for financial services vertical procurement shortlists in Germany and the United Kingdom where compliance-heavy buyers consolidate authority through intermediaries. Edge AI inference nodes for autonomous systems and industrial IoT represent the most penetrable white-space, with ruggedized compact server form factors underserved by incumbent rack-focused portfolios. Go-to-market through modular prefabricated power and cooling module partnerships in India bypasses established hyperscale supply relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled chassis manufacturing as GPU-dense rack densities demand specialized thermal engineering and direct-to-chip plumbing expertise. Long-term viability favors vertically integrated system vendors with captive semiconductor sourcing and direct hyperscale relationships over component specialists facing margin compression. Acquisition target archetype: mid-cap thermal engineering firms with certified natural refrigerant loop designs. The signal to watch is hyperscale operator qualification timeline compression for new liquid-cooled suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Engineering Acquisition | Secures scarce thermal design talent before hyperscale qualification windows close. |
| Modular Data Center Partnership | Captures greenfield procurement in Mumbai and Hyderabad buildouts. |
| ISO 27001 Certification Investment | Unlocks financial services vertical shortlists in Germany and United Kingdom. |
| Advanced Node Supply Agreement | Mitigates Taiwan concentration risk for GPU-dense server CPU sourcing. |
| Channel Integration with Colocation Operators | Captures margin pools migrating from direct OEM relationships. |
Study Parameters
A standing panel of hyperscale infrastructure procurement directors, thermal engineering specialists, colocation operator executives, and FCC compliance officers provided ongoing calibration against primary fieldwork with secondary validation. Primary interviews encompassed server OEM product managers, liquid cooling system architects, data center facility engineers, and enterprise IT procurement leads. Secondary sources included SEC 10-K filings, hyperscaler capital expenditure disclosures, EPA Energy Star certification databases, and EU F-Gas Regulation compliance filings. Bottom-up unit shipment modeling triangulated against top-down infrastructure investment forecasts.
Consistency checks validated volume and value outputs against hyperscale campus buildout announcements and regional data center capacity expansion tracking across the analysis window. Segmentation dimensions modeled included product type, technology form factor, end user procurement authority structure, and deployment location relative to regulatory jurisdiction. CAGRs were derived from weighted average growth across component-level and system-level demand drivers. Industry-specific inputs incorporated GPU cluster density specifications, power usage effectiveness mandate timelines, and semiconductor node transition schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained generative AI training cluster investment and EU regulatory compliance deadline adherence; material deviation would warrant model refresh. Revision becomes warranted when Taiwan semiconductor supply disruption or copper price volatility crosses thresholds that alter hyperscale procurement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
Three-Proof Laptop Market
IT Hardware
India IT Hardware Market
IT Hardware
Industrial Motherboards Market
IT Hardware
USB 3.0 Market
IT Hardware
Middle East and Africa IT Device Market
IT Hardware
Tablet PC Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Global IT Hardware Market
IT Hardware
Server Chassis Market
IT Hardware
PC Case Market
IT Hardware
Europe IT Device Market
IT Hardware
Single Board Computer Market