
 Compression Testing Machines Market | 2026-2036
Compression Testing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Testing Machines Market Outlook
EU Green Deal construction decarbonization targets are recalibrating demand toward energy-efficient building material validation across Europe. MTS Systems Corporation leverages servo-hydraulic precision to anchor high-stakes aerospace certification programs. ZwickRoell dominates European calibration networks with deep channel control over accredited testing laboratories. Instron Corporation differentiates through automated multi-axis systems that compress cycle times for automotive OEMs.
Compression testing machines apply controlled axial load to specimens to determine compressive strength, yield point, and deformation characteristics under standardized strain rates, typically ranging from 0.005 to 500 mm/min depending on material class. These systems serve primary industrial functions in construction material certification, aerospace component qualification, and automotive crash-structure validation where failure-mode prediction carries liability weight. Electromechanical architectures now lead unit shipments across quality control floors due to lower energy draw and reduced hydraulic fluid maintenance, while servo-hydraulic configurations retain margin concentration in dynamic fatigue and multi-axis simulation where load fidelity above 1000 kN commands premium positioning. Digital instrumentation overlays are displacing analog readout systems fastest among research and development laboratories seeking real-time data acquisition integration.
ASTM International governs North American test method harmonization through E9 and C39 protocols that directly specify machine stiffness and alignment tolerances. ISO 7500-1 and JIS B 7733 shape European and Japanese market access by mandating force measurement uncertainty bands and calibration traceability chains. China's GB/T 7314 and SAMR metrology enforcement are tightening import compliance for foreign equipment suppliers. Stakeholders must monitor how regional divergence in automated testing protocol adoption reshapes R&D investment allocation and aftermarket software subscription models.
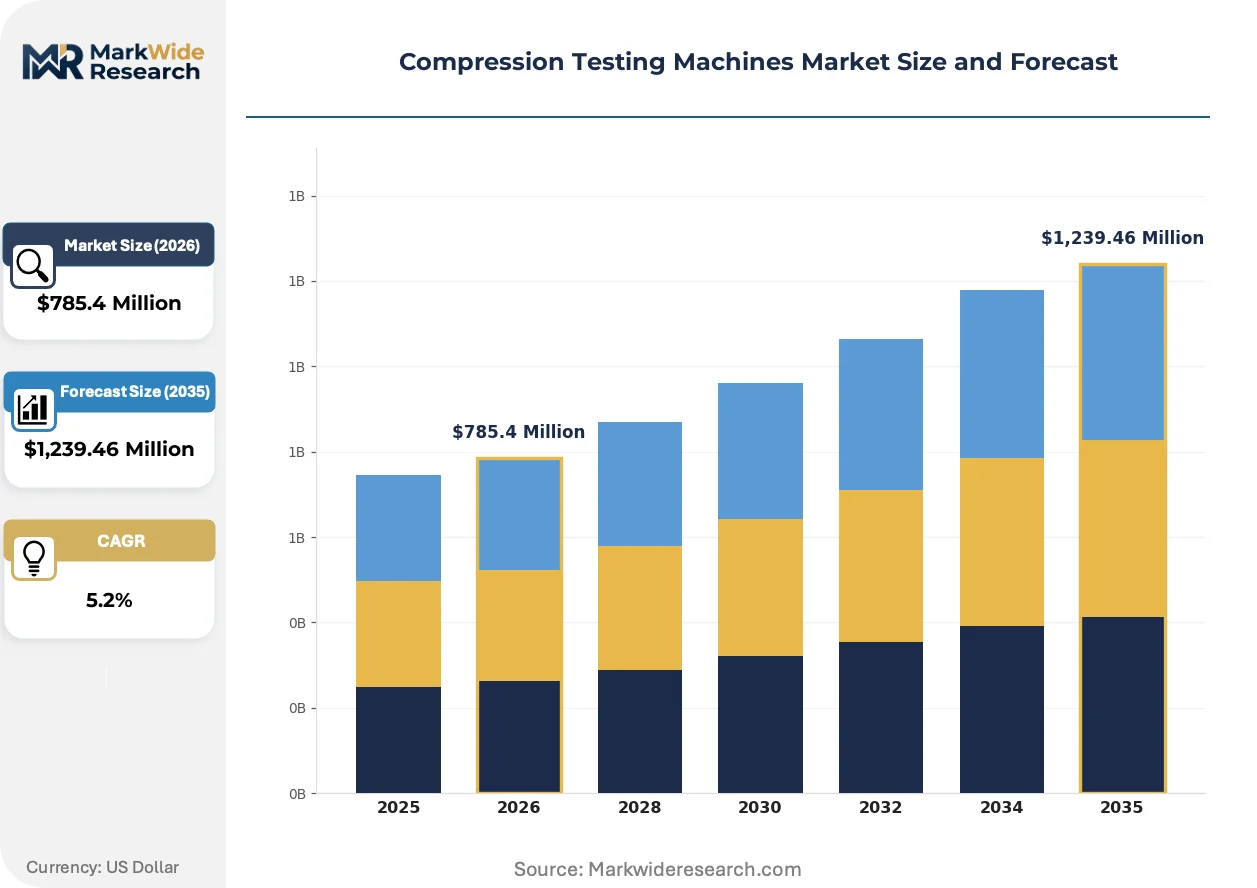
Market Dynamics
Servo-hydraulic architectures face displacement pressure from electromechanical systems as energy costs and maintenance burdens reshape capital equipment procurement in materials testing laboratories.
Growth Catalysts
- EU Green Deal decarbonization mandates:Building material certification requirements are tightening across European member states, forcing construction firms to validate compressive strength of low-carbon concrete and recycled aggregates through accredited testing protocols.
- Automotive crash-structure validation:Electric vehicle platforms demand expanded crush-zone testing as battery pack protection requirements elevate structural load-bearing specifications for OEM validation programs.
- ASTM E9 protocol harmonization:North American aerospace suppliers are consolidating testing equipment purchases to meet unified stiffness and alignment tolerance standards, reducing supplier fragmentation in procurement.
Market Restraints
- High-precision load cell import dependency:German and Japanese sensor suppliers control critical force measurement component supply, exposing equipment manufacturers to currency volatility and allocation constraints.
- Servo-hydraulic fluid maintenance burden:Hydraulic oil contamination risks and environmental disposal regulations are elevating total cost of ownership for dynamic fatigue testing configurations above electromechanical alternatives.
- ISO 7500-1 calibration traceability complexity:Multi-site laboratory operators face fragmented national accreditation body requirements that extend equipment commissioning timelines and elevate compliance overhead.
Strategic Opportunities
- India PLI scheme for domestic manufacturing:Bureau of Indian Standards certification requirements for construction equipment are creating localized assembly incentives for foreign suppliers seeking public infrastructure contract access.
- Cloud-based data acquisition convergence:Real-time telemetry integration with laboratory information management systems is opening subscription revenue streams among pharmaceutical and medical device validation facilities.
- Recycled polymer composite testing:Packaging and automotive lightweighting programs are generating demand for compression characterization of fiber-reinforced thermoplastics outside traditional metals-dominated applications.
Industry Challenges
- Metrology technician scarcity:Force calibration and alignment verification expertise is concentrating among aging specialist workforces, constraining service network expansion for precision equipment vendors.
- Legacy analog system integration friction:Research laboratories with installed bases of mechanical testing frames face data format incompatibility when overlaying digital instrumentation for multi-site collaboration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Testing Machines Market |
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,239.46 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Servo-hydraulic, Digital End User: Construction, Aerospace, Automotive, Manufacturing Application: Material Testing, Quality Control, Research & Development, Compliance Testing Technology: Static, Dynamic, Multi-axis, Automated |
| Companies Covered | Admet, Schenck, MTS Systems Corporation, Dewetron, Bauer, Instron Corporation, Shimadzu Corporation, Tinius Olsen, ZwickRoell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Testing Machines Market Strategic Shifts
Digital instrumentation overlays and automated specimen handling are compressing testing cycle times while elevating data integrity standards across quality control and research environments.
Robotic specimen loading systems are automating repetitive compression sequences in high-throughput construction material laboratories. Tier-1 automotive suppliers in Germany and Japan are deploying these configurations to support 24-hour validation schedules for platform component releases. Labor cost arbitrage is diminishing as a competitive variable where throughput consistency determines contract awards.
REACH substance restrictions on hydraulic fluids are accelerating electromechanical architecture adoption in European testing facilities. Equipment manufacturers are redesigning actuator assemblies to eliminate mineral oil dependencies while maintaining load fidelity above 500 kN. Aerospace qualification programs in France and Italy are piloting these configurations for static strength verification.
Consolidated procurement through centralized laboratory networks is displacing distributed purchasing authority among multinational materials suppliers. Chemical and cement producers are mandating unified equipment specifications across regional quality control sites to ensure inter-laboratory correlation. This concentration is most visible in Germany, where dense validation laboratory clusters serve automotive and construction material supply chains.
Compression Testing Machines Market Segmentation
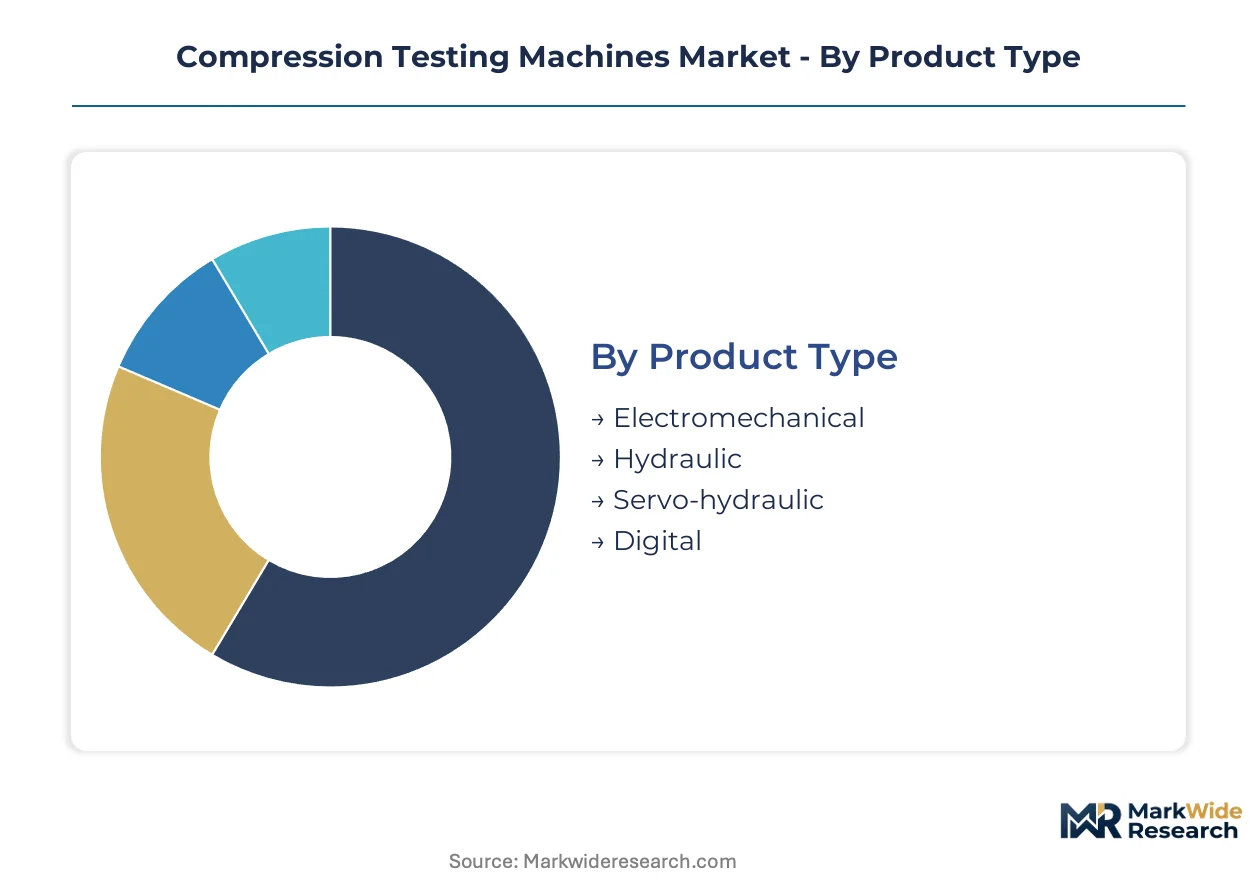
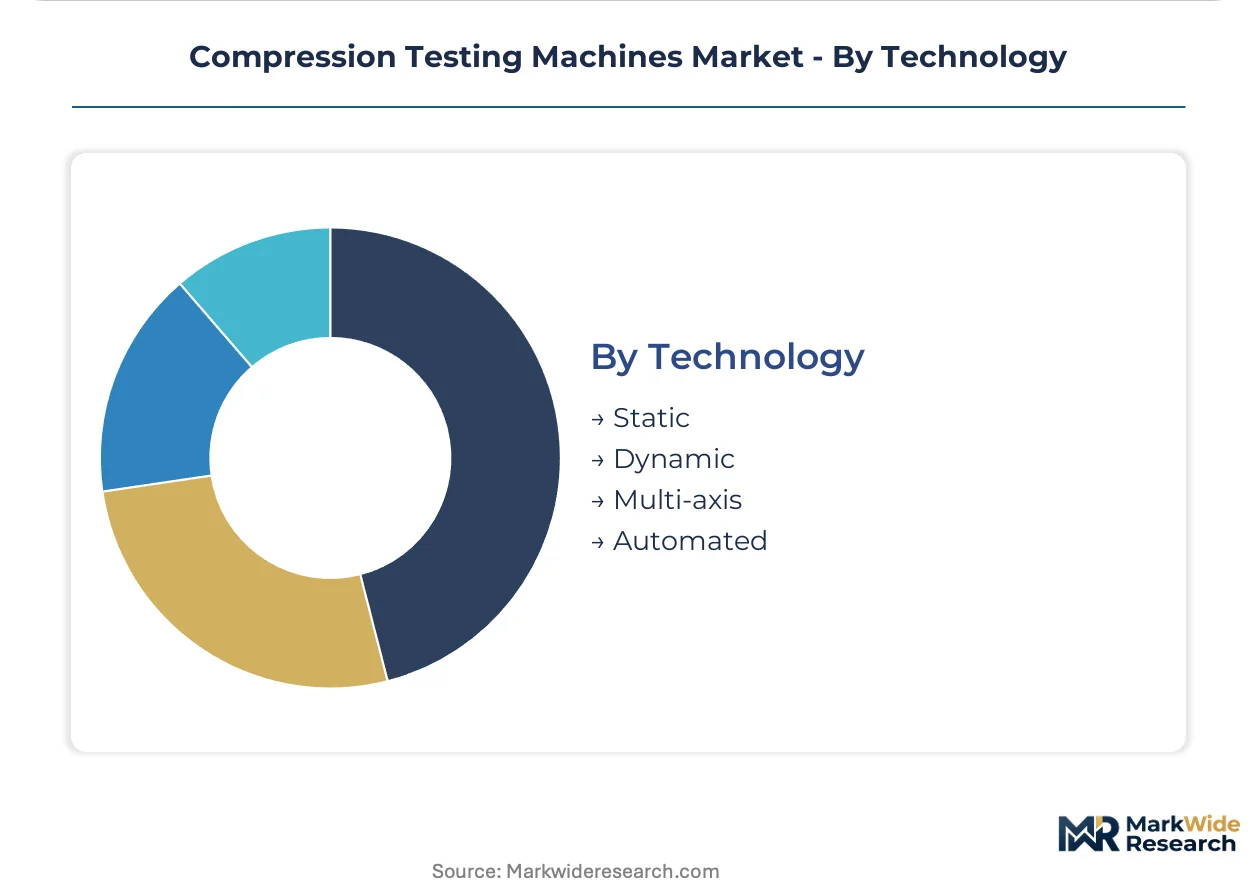
Compression testing machines segment across four dimensions that determine capital allocation priorities. Product architecture dictates energy footprint and maintenance burden. End-user concentration in automotive and construction channels shapes regional demand patterns. Application specificity separates commodity quality-control installations from premium R&D configurations.
Product Type:
Standardization dominates the low-force range below 500 kN, while customization intensity escalates with load capacity and dynamic testing requirements.
- Electromechanical:Ball-screw and belt-drive actuators convert rotary motor motion into precise linear displacement with energy efficiency above 85%. Construction material laboratories in Germany and Japan are standardizing on these architectures to eliminate hydraulic fluid handling costs under REACH substance restrictions.
- Servo-hydraulic:Closed-loop hydraulic systems with servo-valve control deliver load fidelity above 1000 kN with frequency response to 100 Hz for fatigue simulation. Aerospace suppliers in France retain these configurations for airframe component qualification where dynamic loading reproduces flight-cycle stress.
- Hydraulic:Open-loop hydraulic presses serve static compression requirements in emerging markets where capital constraints override precision demands.
- Digital:Instrumentation overlays with real-time data acquisition retrofit existing mechanical frames in research environments.
Leading the category by volume: Electromechanical. Expanding most quickly: Servo-hydraulic in aerospace validation.
End User:
Customer concentration varies by procurement authority—centralized laboratory networks versus distributed plant-floor installations.
- Automotive:OEM validation programs for electric vehicle crash structures demand multi-axis compression simulation with battery pack protection specifications. Tier-1 suppliers in Germany operate 24-hour testing schedules to support platform release cycles.
- Construction:Cement and aggregate producers require accredited compressive strength verification under EU Green Deal decarbonization protocols for low-carbon concrete formulations.
- Aerospace:Airframe manufacturers specify stiffness and alignment tolerances per ASTM E9 for structural component qualification.
- Manufacturing:Metal fabrication and polymer processing facilities deploy quality-control testing for batch release authorization.
Highest procurement concentration: Automotive. Steepest expansion trajectory: Construction under tightening building material certification.
Application:
Workflow integration separates standalone quality-control stations from embedded research environments with laboratory information management system connectivity.
- Quality Control:Repetitive batch testing with automated specimen handling compresses cycle times in high-throughput construction material laboratories. Robotic loading systems from German suppliers support unattended overnight operation.
- Research & Development:Multi-site data collaboration requires digital instrumentation with cloud-based telemetry integration for pharmaceutical and medical device validation facilities.
- Material Testing:Standardized protocol execution per ISO 7500-1 and ASTM C39 governs construction material certification.
- Compliance Testing:Regulatory submission documentation demands calibration traceability chains through national accreditation bodies.
Dominant by installed base: Quality Control. Gaining share fastest: R&D with cloud convergence.
Technology:
Architecture selection trades capital cost against test sophistication—static configurations for commodity strength verification versus dynamic systems for fatigue life prediction.
- Automated:Robotic specimen handling and automated extensometer positioning eliminate operator-induced variability in high-volume automotive validation programs.
- Multi-axis:Combined compression-torsion loading reproduces complex stress states in aerospace bearing and fastener qualification.
- Dynamic:Servo-hydraulic actuation with closed-loop control executes fatigue protocols with frequency response requirements.
- Static:Constant-rate displacement testing serves fundamental compressive strength determination in construction material certification.
Highest shipment volume: Static. Climbing the fastest: Automated with labor cost arbitrage diminishing as throughput consistency determines contract awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for compression testing equipment through its dense automotive validation laboratory cluster serving OEM and Tier-1 suppliers. Equipment procurement concentrates where electric vehicle platform development accelerates structural load-bearing verification requirements.
Germany
Automotive crash-structure validation for electric vehicle battery protection drives equipment procurement across Stuttgart, Munich, and Wolfsburg laboratory networks. EU Green Deal decarbonization mandates under REACH substance restrictions accelerate electromechanical architecture adoption to eliminate hydraulic fluid dependencies. Bavaria's aerospace qualification facilities in Augsburg pilot servo-hydraulic configurations for airframe component certification.
United States
Aerospace suppliers consolidate testing equipment purchases to meet ASTM E9 protocol harmonization for stiffness and alignment tolerance standards. FAA certification requirements for structural component qualification elevate precision demands in Seattle and Wichita manufacturing corridors. Boeing and Lockheed Martin validation programs in Everett and Fort Worth anchor high-capacity servo-hydraulic system deployment.
China
Construction material certification expands under GB/T 7314 standard enforcement and SAMR metrology compliance tightening for imported equipment. Low-carbon concrete validation requirements proliferate in Yangtze River Delta infrastructure projects. Shanghai and Suzhou laboratory networks standardize on automated quality-control configurations for high-throughput batch testing.
Japan
JIS B 7733 calibration traceability mandates shape equipment procurement for automotive and electronics material validation. METI industrial standardization programs accelerate digital instrumentation overlay adoption in Osaka and Nagoya testing facilities. Toyota and Honda validation laboratories in Aichi Prefecture deploy multi-axis compression systems for lightweight structural component qualification.
India
Bureau of Indian Standards certification requirements under the PLI scheme for domestic manufacturing create localized assembly incentives for construction equipment suppliers. Highway and rail infrastructure expansion in Maharashtra and Gujarat elevates compressive strength verification demand for cement and aggregate producers. Mumbai-Pune industrial corridor laboratories standardize on electromechanical architectures to reduce hydraulic maintenance burdens in tropical operating conditions.
Compression Testing Machines Market Competitive Environment
Premium-margin players sit above commodity-margin players across calibration network depth and servo-hydraulic load fidelity specialization. The vendor base organizes into three tiers: precision equipment specialists with accredited laboratory relationships, diversified industrial automation conglomerates with materials testing divisions, and regional fabricators serving emerging market price sensitivity. Consolidation pressure concentrates among mid-scale European and North American suppliers seeking geographic coverage expansion. Dominant competitive moves include strategic partnerships with national accreditation bodies for calibration service exclusivity and technology licensing agreements for digital instrumentation module integration.
Within the precision equipment specialist tier, ZwickRoell and MTS Systems Corporation exemplify divergent strategic positioning around load capacity specialization and end-market concentration. ZwickRoell anchors European calibration network control through deep channel relationships with accredited testing laboratories. MTS Systems Corporation occupies a position in high-stakes aerospace and automotive certification where servo-hydraulic precision above 1000 kN commands premium positioning. Instron Corporation represents the automated multi-axis system vector, targeting automotive OEM cycle time compression requirements. Among diversified industrial technology conglomerates, Shimadzu Corporation and Tinius Olsen sit within broader analytical and testing equipment portfolios that leverage shared distribution infrastructure across materials science applications.
| Leading Market Players |
|---|
| Admet |
| Schenck |
| MTS Systems Corporation |
| Dewetron |
| Bauer |
| Instron Corporation |
| Shimadzu Corporation |
| Tinius Olsen |
| ZwickRoell |
| Others |
Value Chain & Pricing Dynamics
Electromechanical actuator migration from servo-hydraulic architectures compresses both energy operating costs and supplier field service dependencies, concentrating procurement leverage among equipment vendors with in-house ball-screw manufacturing capabilities in Germany and Japan. This technology transition simultaneously elevates price competition in the sub-500 kN segment while tightening margin capture for dynamic fatigue configurations above 1000 kN where load fidelity certification remains scarce.
Pricing Analysis
Throughput-based pricing anchors equipment procurement decisions, with automotive OEMs contracting for guaranteed validation cycle volumes rather than capital asset ownership. Price differentiation separates ISO 7500-1 accredited laboratory configurations from uncertified plant-floor installations, while REACH compliance bundling commands premium positioning in European markets. Pricing pressure stems from electromechanical architecture commoditization below 500 kN as Chinese suppliers enter mid-tier segments. Construction material laboratories exhibit highest price sensitivity due to public infrastructure budget constraints, whereas aerospace qualification programs demonstrate lowest sensitivity given liability exposure from component failure.
Supply Chain Analysis
Calibration traceability certification gates market access, forcing equipment manufacturers to anchor final assembly in Germany, Japan, and the United States where national accreditation body relationships concentrate. Critical component dependencies include German and Japanese load cells, Swiss linear encoder systems, and Italian servo-valve assemblies for high-force dynamic configurations. Single-source vulnerability in precision force measurement sensors exposes equipment vendors to allocation constraints from Bosch Sensortec and Kyowa Electronic Instruments. Distribution runs through accredited laboratory networks and OEM procurement consortia rather than open distributor channels, with long-term service contracts bundling calibration scheduling and spare parts provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
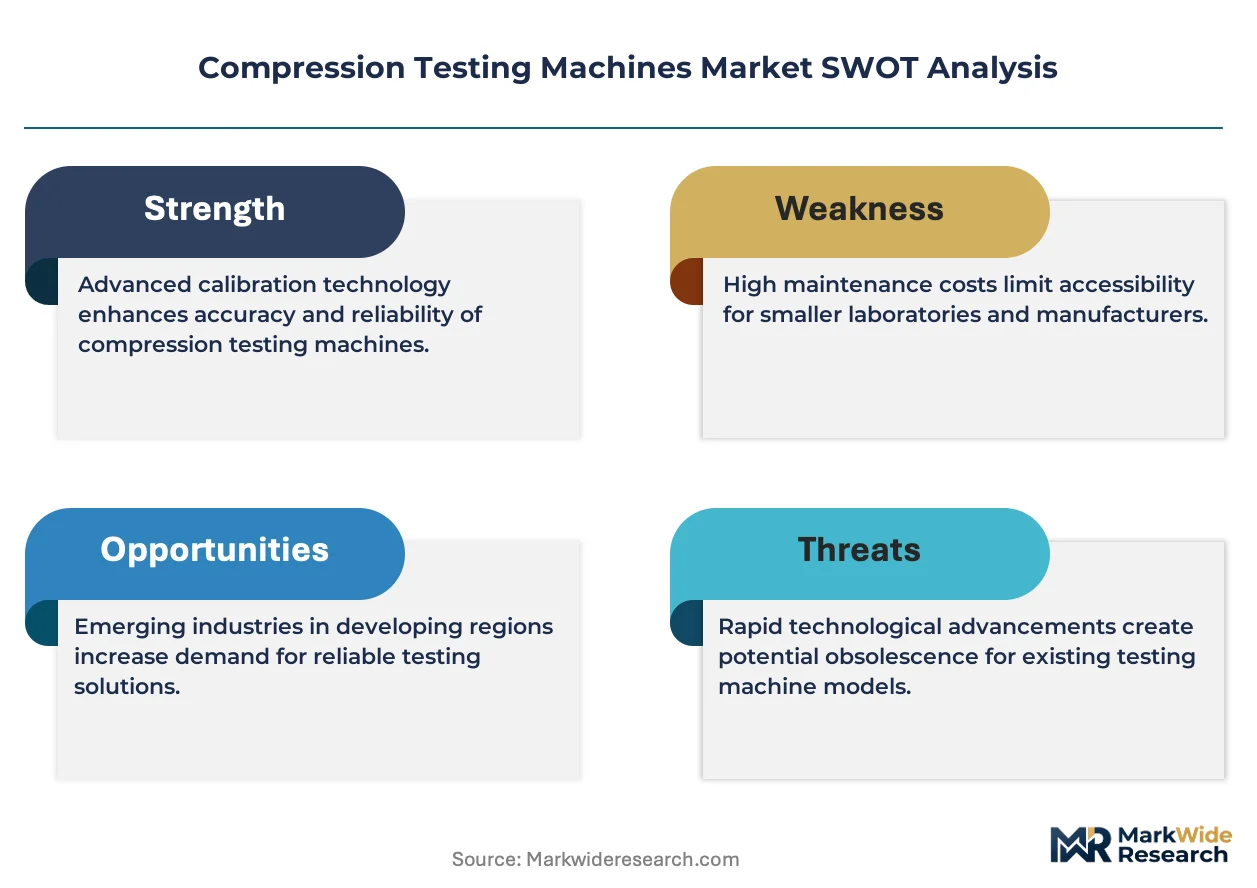
Market consolidation accelerates as REACH substance restrictions and ISO 7500-1 calibration complexity force mid-scale European suppliers into strategic exits. Equipment vendors without accredited laboratory channel control face margin compression from both premium specialists and emerging Asian competitors.
For Market Incumbents: Acquire calibration service networks in Germany and Japan to lock in national accreditation body exclusivity. Incumbents must backward integrate into load cell manufacturing to reduce dependency on Bosch Sensortec and Kyowa allocation cycles, while embedding cloud-based telemetry modules to capture recurring software subscription revenue from pharmaceutical validation facilities threatened by robotic specimen handling entrants. For New Entrants and Emerging Players: The premium-economy price-point gap in the 250-500 kN construction material segment offers white-space entry for electromechanical systems with modular digital instrumentation overlays. Target India's Bureau of Indian Standards certification pathway under PLI scheme incentives for localized assembly partnerships. Penetrate through aftermarket retrofit kits for legacy analog frames in research laboratories facing data format incompatibility friction, rather than competing head-to-head in greenfield aerospace procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial automation conglomerates seeking materials testing division expansion. Long-term viability favors precision equipment specialists with captive calibration network density and servo-hydraulic load fidelity above 1000 kN. Monitor SAMR enforcement intensity in China as inflection indicator for import compliance cost escalation affecting foreign equipment supplier margins.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Acquisition | Secures national accreditation body exclusivity in Germany and Japan, locking out competitors from aerospace qualification programs. |
| Electromechanical Actuator Manufacturing | Eliminates hydraulic fluid dependencies under REACH restrictions while reducing energy operating costs for construction laboratories. |
| Cloud Telemetry Integration | Opens subscription revenue streams among pharmaceutical LIM-connected validation facilities seeking real-time multi-site collaboration. |
| India PLI Localization | Enables Bureau of Indian Standards certification access for public infrastructure contracts in Maharashtra and Gujarat. |
| Robotic Specimen Handling Deployment | Compresses cycle times for 24-hour automotive OEM validation schedules in Stuttgart and Wolfsburg laboratory networks. |
Study Parameters
Independent corroboration across equipment procurement managers at Tier-1 automotive suppliers, laboratory directors at accredited testing facilities, and aftermarket service heads at precision equipment vendors underwrites the qualitative findings. Primary interviews with calibration technicians, OEM platform engineers, and construction material quality control supervisors combined with secondary validation from ASTM International protocol documentation, ISO 7500-1 accreditation records, SEC 10-K filings of listed testing equipment manufacturers, and customs trade data for compression testing machine imports. Bottom-up triangulation across product architecture shipment volumes and top-down reconciliation against end-user capital expenditure disclosures anchored segment-level sizing.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects, with electromechanical architecture adoption curves, servo-hydraulic maintenance cost escalation, and digital instrumentation overlay penetration modeled separately. Segmentation dimensions include product type, end-user concentration, application workflow integration, and technology sophistication tier. CAGRs derive from logistic diffusion curves fitted to historical equipment replacement cycles and regulatory mandate implementation timelines, with EU Green Deal decarbonization compliance deadlines and electric vehicle platform release schedules as primary forecast inputs.
Inputs from national accreditation body certification databases and OEM procurement consortium contract disclosures were available through the study window; gaps in privately held supplier cost structures and unreported aftermarket service contract terms introduce uncertainty bands around margin estimates. Forecasts reflect assumptions regarding REACH enforcement continuity and SAMR import compliance trajectory without contingency for abrupt regulatory suspension. A model refresh is warranted upon material change in EU Green Deal building material certification timeline or battery pack protection specification revision by major automotive OEMs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Digital Inspection Tools Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
EMC Testing Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
RFID Tester Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
LCR Meter Market
Test and Measurement
India Electrical Testing Services Market