
 Fire Resistance Cable Market | 2026-2036
Fire Resistance Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resistance Cable Market Intelligence
Consolidation among data center operators and hyperscale cloud buyers is repositioning procurement leverage toward volume-contract suppliers. Prysmian Group leverages its integrated energy cable portfolio to anchor long-term infrastructure contracts across European and North American utility networks. Nexans S.A. competes through specialized fire-rated solutions for tunnel and transit applications, while KEI Industries Ltd. dominates price-sensitive segments in South Asian construction markets through localized manufacturing scale.
Fire resistance cable comprises insulated conductors engineered to maintain circuit integrity under extreme thermal exposure, typically employing mica tape wrapping, silicone rubber compounds, or magnesium oxide mineral insulation to withstand temperatures exceeding 750°C for prescribed durations. Its primary purpose is to sustain emergency power, fire alarm, and evacuation system functionality during active combustion events in occupied structures. Halogen-free and low smoke variants command premium positioning in commercial and transit infrastructure where toxic fume mitigation determines specification compliance, while mineral insulated cable leads in industrial process environments demanding the highest thermal endurance. PVC-insulated fire-rated products occupy mature, cost-driven segments where regulatory minimums rather than performance optimization guide procurement.
The EU Construction Products Regulation (CPR) mandates standardized fire performance classifications for cables installed in permanent buildings across member states, directly elevating demand for Euroclass B2ca and Cca certified products. In the United States, the National Electrical Code (NEC) enforced by local authorities having jurisdiction shapes market access through listings requirements for fire-resistive cable systems in high-rise and critical facility applications. China's GB standards administered by SAMR impose flammability and smoke density thresholds that foreign suppliers must navigate for market participation. Stakeholders must monitor divergence between regional test protocols and emerging material innovations that could reset compliance cost structures without warning.
Market Dynamics
The EU Construction Products Regulation is compressing specification windows for fire-rated cabling, forcing manufacturers to recertify legacy product lines while mineral insulated and halogen-free variants capture premium positioning in high-rise and transit infrastructure.
Growth Catalysts
- CPR Euroclass Mandates:The EU Construction Products Regulation elevates demand for B2ca and Cca certified cables across Germany, France, and Italy as member states tighten enforcement in commercial buildings.
- Data Center Power Density:Hyperscale operators in Virginia and Frankfurt are specifying halogen-free fire resistance cable for emergency power distribution to meet insurer requirements and local building codes.
- Mineral Insulated Technology:Magnesium oxide insulated cable withstands temperatures exceeding 1000°C, enabling circuit integrity in tunnel ventilation and industrial process environments where standard mica tape fails.
Market Restraints
- Copper Price Volatility:Mineral insulated cable requires 30-40% more copper conductor than polymeric alternatives, exposing margins to London Metal Exchange price swings.
- Specialized Manufacturing Concentration:Continuous mineral insulated cable production lines concentrate in Italy and the UK, creating supply vulnerability for Asian and North American project timelines.
- Silicone Rubber Feedstock Limits:Fire-rated flexible cable depends on silicone compound availability, with European chemical producers operating at constrained capacity.
Strategic Opportunities
- India High-Rise Construction:Mumbai and Delhi metro expansions and residential tower mandates under the National Building Code create demand for imported fire-rated cable as domestic certification capacity lags.
- Renewable Energy Storage:Battery energy storage systems require fire resistance cable for thermal runaway containment, with California and Texas utility-scale projects driving specification.
- Smart Building Integration:Power over Ethernet convergence with fire alarm systems creates demand for dual-certified cable meeting both data transmission and fire performance standards.
Industry Challenges
- Certification Timeline Compression:CPR testing at notified bodies in Germany and the UK extends lead times to 16-24 weeks, delaying project deliveries.
- Cross-Border Standard Divergence:Fire resistance cable approved under BS 6387 in the UK requires separate UL 2196 testing for US high-rise applications, fragmenting product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resistance Cable Market |
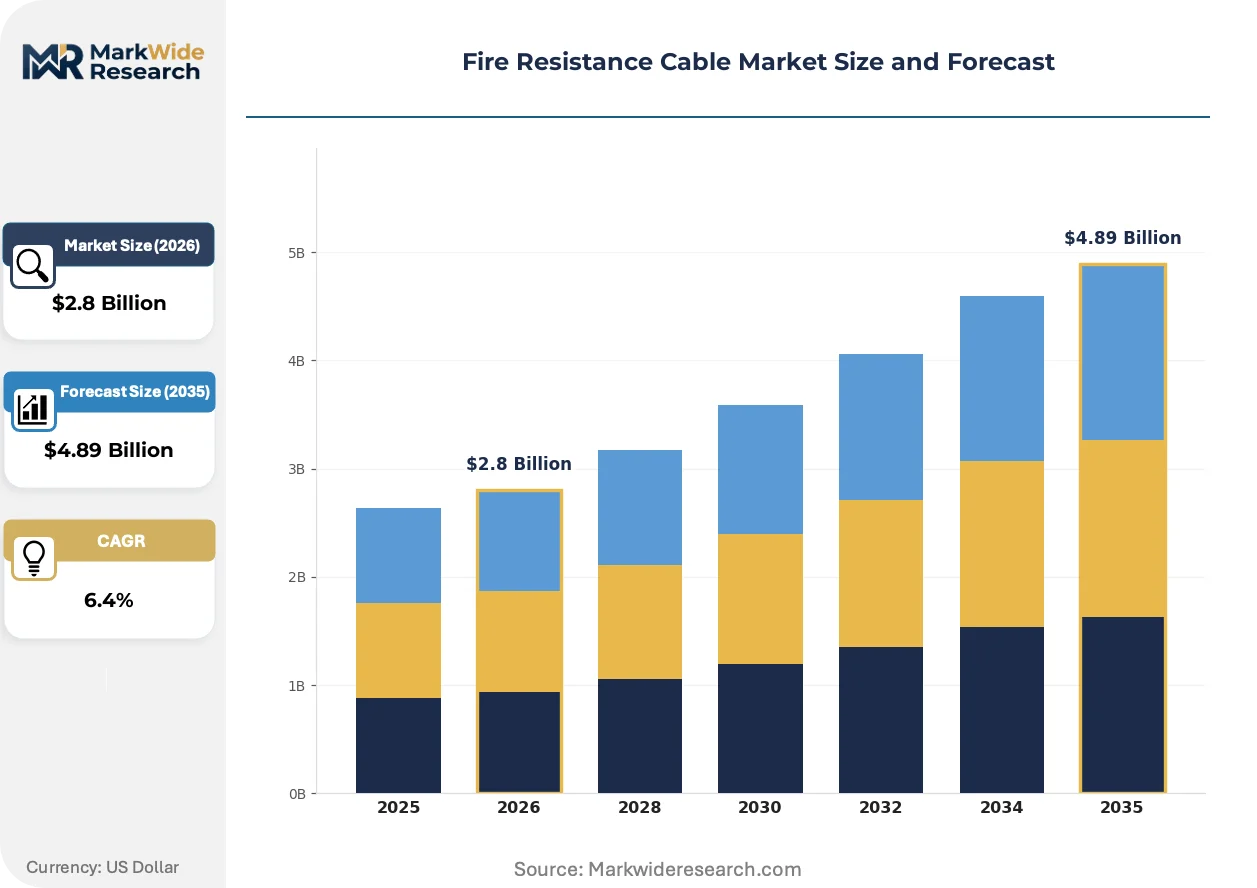
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Smoke, Halogen-Free, Mineral Insulated, PVC Application: Construction, Automotive, Oil & Gas, Renewable Energy Installation: Indoor, Outdoor, Underground, Marine End User: Telecommunications, Power Generation, Manufacturing, Infrastructure |
| Companies Covered | Prysmian Group, Nexans S.A., Leoni AG, NKT Group, LS Cable & System, Elsewedy Electric, KEI Industries Ltd., Belden Inc., Southwire Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resistance Cable Market Strategic Shifts & Innovations
Material science advances and procurement centralization are restructuring how fire resistance cable is specified, tested, and supplied across construction and infrastructure verticals.
Silicone rubber compounds with enhanced ceramic-forming additives are absorbing thermal shock loads that previously required mineral insulation, allowing data center operators in Northern Virginia and Frankfurt to specify lighter, more flexible cable for emergency circuits without sacrificing 90-minute circuit integrity ratings.
The EU F-Gas Regulation and accompanying REACH restrictions on halogenated flame retardants are accelerating halogen-free compound development, compelling compounders in Belgium and the Netherlands to reformulate low-smoke zero-halogen sheathing materials ahead of 2025 substance evaluation deadlines.
Volume-contract procurement by hyperscale cloud operators is compressing distributor margins and consolidating specification authority with engineering-procurement-construction firms in Texas and Singapore, who now mandate factory witness testing and lot-traceable mica tape documentation as standard commercial terms.
Fire Resistance Cable Market Segmentation
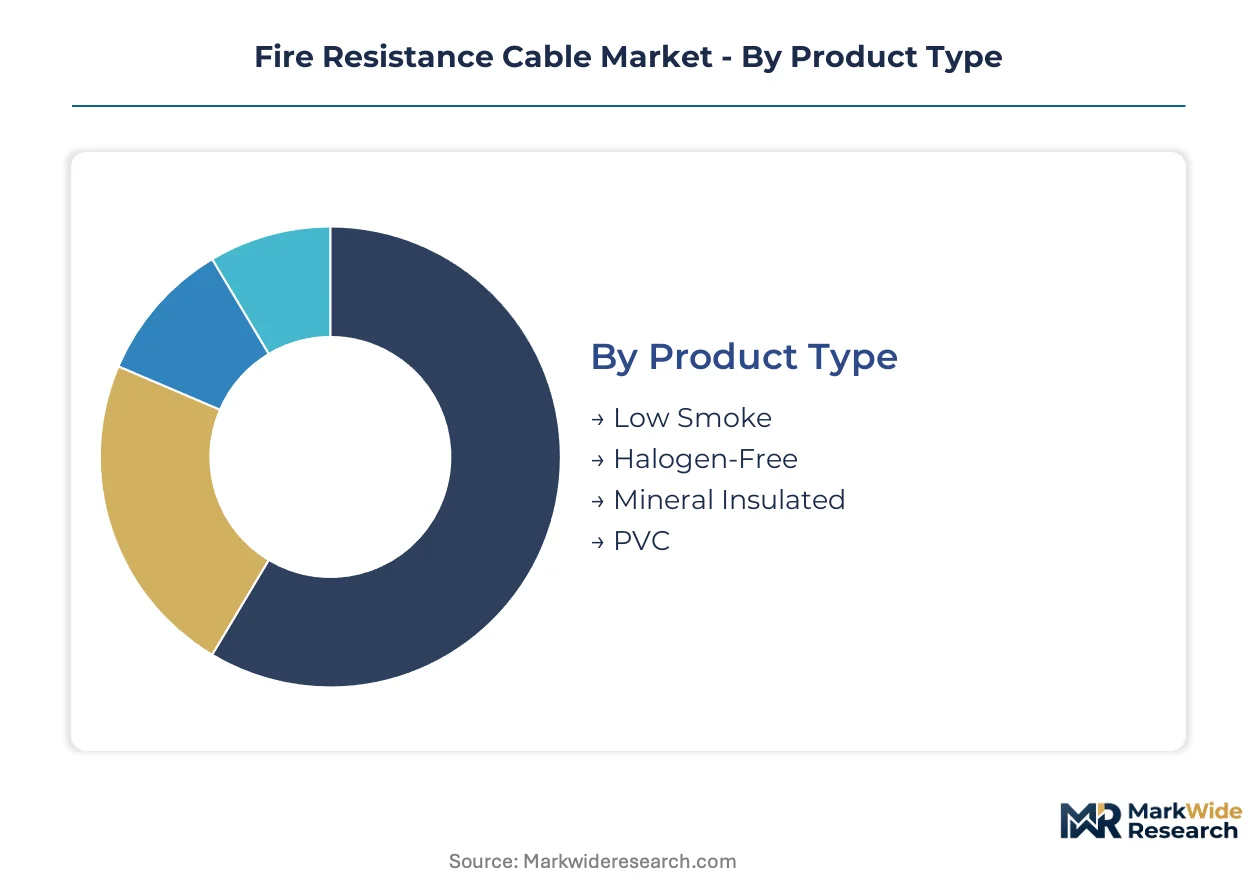
Fire resistance cable specification diverges sharply between standalone emergency systems and embedded building infrastructure, with mineral insulated and halogen-free variants commanding premium positioning in integrated safety networks while PVC-based products serve retrofit and cost-constrained standalone installations.
Product Type:
Mineral insulated and halogen-free cables anchor integrated building safety systems where circuit integrity must survive total combustion exposure, whereas low-smoke and PVC variants occupy standalone applications with shorter duration requirements.
- Low Smoke:Polymeric compounds engineered to limit optical density during pyrolysis, specified in UK rail tunnels and Singapore mass transit where visibility maintenance determines evacuation protocol. London Underground's Crossrail extension standardized this grade for platform-to-surface emergency lighting circuits.
- Halogen-Free:Thermoplastic or cross-linked polyolefin insulation eliminating corrosive gas release, dominating data center procurement in Frankfurt and Northern Virginia where equipment corrosion risks override raw material cost considerations. ECHA REACH substance restrictions accelerate specification migration from halogenated alternatives.
- Mineral Insulated:Magnesium oxide packed copper conductors withstand continuous temperatures exceeding 1000°C, specified in tunnel ventilation and industrial furnace environments where no polymeric alternative survives.
- PVC:Cost-optimized fire-rated insulation meeting minimum regulatory thresholds, prevalent in residential retrofit markets and developing economy construction where price elasticity dominates procurement decisions.
PVC leads volumes today; halogen-free is gaining share fastest.
Application:
Construction absorbs the majority of fire resistance cable procurement through embedded electrical distribution, while automotive and renewable energy represent emerging standalone system categories with distinct thermal endurance requirements.
- Construction:High-rise electrical distribution, fire alarm loops, and emergency power circuits integrated into building structural elements. Germany's CPR enforcement elevates Euroclass B2ca specification in Berlin and Munich commercial towers.
- Automotive:Battery enclosure protection and charging infrastructure fire containment, with OEMs in Stuttgart and Detroit specifying 90-minute circuit integrity for high-voltage architectures.
- Oil & Gas:Offshore platform and refinery process safety systems where hydrocarbon pool fires demand extended duration ratings beyond standard building codes.
- Renewable Energy:Battery energy storage system containment cabling, with California utility-scale projects driving thermal runaway protection specification.
Construction dominates absolute volume; renewable energy shows the steepest expansion trajectory.
Installation:
Indoor embedded systems concentrate value capture through complex routing and termination requirements, while outdoor and marine installations demand specialized sheathing compounds that alter margin structures.
- Indoor:Vertical risers, ceiling plenums, and floor cavities in occupied structures, requiring plenum-rated jacketing and bend-radius flexibility for conduit installation. New York City Local Law 126 mandates this category in high-rise residential.
- Outdoor:Façade-mounted emergency circuits and external fire pump feeds exposed to weathering, utilizing UV-stabilized halogen-free sheathing common in Australian commercial construction.
- Underground:Tunnel and subway distribution requiring moisture-resistant mineral insulation or laminated polymer barriers, specified in London's Thames Tideway and Paris Metro extensions.
- Marine:Offshore platform and vessel emergency systems meeting IMO FTP Code requirements, with North Sea operators specifying braided armor over mineral insulated cores.
Indoor installation commands the largest share; marine applications expand most quickly on offshore wind growth.
End User:
Telecommunications and power generation operators drive standardization through centralized procurement, while manufacturing and infrastructure sectors fragment across project-specific engineering specifications.
- Telecommunications:Hyperscale data center operators in Ashburn and Dublin standardizing halogen-free fire resistance for emergency power distribution, with EPC firms mandating lot-traceable mica documentation.
- Power Generation:Nuclear and conventional plant safety-related circuits requiring seismic qualification alongside fire rating, with EDF specification in France setting regional benchmark.
- Manufacturing:Automotive paint shops and semiconductor cleanrooms integrating fire resistance with chemical resistance requirements, fragmenting across process-specific standards.
- Infrastructure:Airport, hospital, and transit authority procurement with divergent local amendments to national codes, creating specification complexity for pan-national suppliers.
Telecommunications leads procurement scale; infrastructure delivers the most fragmented but highest-margin project mix.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces the EU's strictest CPR compliance timelines, while the United States relies on fragmented local authority enforcement that creates specification inconsistency across state lines. China and India represent the fastest procurement expansion, driven by high-rise construction mandates and data center buildouts.
United States
Hyperscale data centers in Northern Virginia and Dallas-Fort Worth anchor procurement volume for halogen-free fire resistance cable. The National Electrical Code shapes market access through local authority enforcement, with New York City Local Law 126 mandating specific installation categories in high-rise residential towers. Ashburn's data center cluster concentrates demand from cloud operators specifying lot-traceable mica documentation.
Germany
Berlin and Munich commercial towers drive Euroclass B2ca specification under aggressive CPR enforcement by federal building authorities. The EU F-Gas Regulation and REACH restrictions on halogenated flame retardants compel compounders to reformulate sheathing materials ahead of substance evaluation deadlines. Industrial process environments in the Ruhr region specify mineral insulated cable for furnace and tunnel ventilation systems.
China
GB standards administered by SAMR impose flammability and smoke density thresholds that foreign suppliers must navigate for market participation. High-rise construction across Shanghai and Shenzhen concentrates demand for fire-rated distribution cable under tightened National Building Code enforcement. Battery energy storage projects in Jiangsu and Guangdong provinces specify thermal runaway containment cabling for utility-scale installations.
India
Mumbai and Delhi metro expansions create demand for imported fire-rated cable as domestic certification capacity lags behind construction timelines. The National Building Code mandates fire resistance specifications in residential towers above specified height thresholds. Telangana and Karnataka data center clusters are emerging as procurement nodes for halogen-free emergency power distribution.
United Kingdom
London's Crossrail extension and Thames Tideway tunnel standardized low-smoke cable grades for platform-to-surface emergency lighting and underground distribution. BS 6387 certification requirements operate alongside divergent EU CPR frameworks post-Brexit, fragmenting supplier product portfolios. Manchester and Birmingham high-rise commercial construction sustains demand for Euroclass Cca certified products.
Fire Resistance Cable Market Key Industry Players
Italian and British producers anchor the premium mineral insulated tier; South Asian and North American fabricators hold volume-contract positions in cost-sensitive segments. The vendor base concentrates around three strategic archetypes: integrated energy cable conglomerates with utility network anchoring, specialized fire-rated solution providers for tunnel and transit applications, and localized manufacturers dominating price-driven construction markets. Competitive dynamics center on long-term infrastructure contract capture and recertification speed under compressed CPR timelines.
Among integrated cable conglomerates, Prysmian Group and Nexans S.A. occupy positions representing the premium infrastructure tier, with Prysmian exemplifying portfolio breadth across European and North American utility networks and Nexans representing specialized fire-rated positioning. KEI Industries Ltd. sits within the localized manufacturing archetype, anchoring price-sensitive segment presence through South Asian production scale. These three companies illustrate the geographic and capability stratification shaping procurement leverage consolidation.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans S.A. |
| Leoni AG |
| NKT Group |
| LS Cable & System |
| Elsewedy Electric |
| KEI Industries Ltd. |
| Belden Inc. |
| Southwire Company |
| Others |
Cost & Logistics Intelligence
Mineral insulated cable production lines in Italy and the UK are consolidating output capacity while silicone rubber compound shortages in Belgium and the Netherlands simultaneously reshape procurement economics and geographic sourcing priorities for fire-rated cable buyers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for PVC-based fire resistance cable, compressing margins for European and North American producers of commodity-grade products. Three-tier pricing structure across mineral insulated, halogen-free, and PVC levels reflects certification complexity and copper intensity rather than brand premium alone. Cost compression in the PVC tier is intensifying because South Asian fabricators operate with localized copper sourcing and lower labor overheads. Data center operators in Northern Virginia and Frankfurt exhibit the least price sensitivity, prioritizing lot-traceable mica documentation and Euroclass B2ca certification over unit cost.
Supply Chain Analysis
Copper conductor supply rests on Chilean and Peruvian mining output, with magnesium oxide mineral insulation drawing from Austrian and Slovakian specialty chemical processors. Silicone rubber feedstocks hinge on German and Dutch petrochemical complexes operating at constrained capacity. Single-source vulnerability concentrates in continuous mineral insulated cable production equipment, where Italian and British machinery builders dominate global installed base. Distribution runs through engineering-procurement-construction firms in Texas and Singapore who consolidate volume-contract procurement for hyperscale data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire resistance cable market functions as a stable compounder anchored by regulatory ratchets that mandate progressively stricter fire performance standards across construction and infrastructure verticals.
For Market Incumbents: Hedge copper price exposure through long-term offtake agreements with Chilean and Peruvian miners, insulating margins on mineral insulated cable where conductor intensity runs highest. Accelerate recertification investments at German and UK notified bodies to compress CPR testing timelines before competitor capacity comes online. Defensive positioning against South Asian price competition requires emphasizing factory witness testing and lot-traceable documentation that commodity producers cannot replicate. For New Entrants and Emerging Players: Ceramic-forming silicone rubber compounds with enhanced thermal shock absorption offer a technology-first wedge into data center emergency circuit specifications in Northern Virginia and Frankfurt. Target India's high-rise construction segment where domestic certification capacity lags behind Mumbai and Delhi metro expansion timelines. A go-to-market angle anchored to EPC contractor partnerships in Telangana and Karnataka data center clusters bypasses established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap cable fabricators with halogen-free compound formulation capabilities but limited mineral insulated production scale. The five-to-ten-year viability window favors targets with notified body relationships in Germany and the UK that accelerate CPR compliance timelines. Watch copper price volatility and REACH substance evaluation deadlines as inflection indicators that could reset competitive cost structures without warning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Conductor Supply | Captive sourcing from Chilean mining operations insulates margins on mineral insulated cable against London Metal Exchange volatility. |
| Halogen-Free Compound Reformulation | Belgian and Dutch chemical producers meeting EU F-Gas Regulation deadlines capture specification authority from halogenated alternatives. |
| Notified Body Certification Investment | German and UK testing capacity expansion compresses 16-24 week CPR lead times that currently delay project deliveries. |
| Long-Term EPC Contractor Agreements | Texas and Singapore engineering-procurement-construction firms consolidate procurement leverage for hyperscale data center operators. |
| Regional Manufacturing Footprint Expansion | Indian domestic production scale addresses Mumbai and Delhi metro demand as imported cable certification bottlenecks persist. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with cable procurement managers at hyperscale data center operators, EPC contractor specification engineers, and notified body certification specialists. Secondary validation draws from EU Construction Products Regulation enforcement records, National Electrical Code local authority amendments, SAMR GB standards documentation, and customs trade data on copper conductor and mineral insulation flows. Bottom-up demand modeling triangulates against top-down construction spend and data center capex projections.
Rate-of-change decomposition across product type, application, installation environment, and end-user industry generates volume and value outputs over the projection horizon. Segmentation dimensions include mineral insulated versus halogen-free versus PVC insulation technology, construction versus automotive versus renewable energy application, indoor versus outdoor versus underground versus marine installation, and telecommunications versus power generation versus infrastructure end-user. CAGRs derive from regression analysis of historical certification timelines, copper price elasticity, and regulatory enforcement intensity.
The model holds under stable copper supply conditions and consistent CPR enforcement timelines; deviation in REACH substance evaluation deadlines or EU F-Gas Regulation implementation would shift compound availability and reformulation cost structures. A small set of named triggers warrants ongoing watch: copper price volatility, notified body capacity constraints, and halogen-free compound production bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Mineral Insulated (MI) Cable Market
Cables
Usb Data Cable Market
Cables
LED Cable Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Audio and Video Cables Market
Cables
Class 1E Electric Cables Market
Cables
Cable Market
Cables
Active Optical Cable Market
Cables
Cable Flange Market
Cables
Cable Tags Market
Cables
Global Cable Blowing Equipment Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Network Cable Tester Market
Cables
Cable Accessories Market
Cables
Solar Cable Market
Cables
Submarine Cabling Systems Market