
 All Flash Storage Market | 2026-2036
All Flash Storage Market Size, Share, and Industry Trends Forecast 2026-2036
All Flash Storage Market Analysis
REACH chemical compliance is realigning material sourcing and manufacturing cost structures for solid-state storage arrays. Dell Technologies leverages vertical integration across NAND supply chains to sustain margin control. Pure Storage differentiates through software-defined architectures that reduce hardware refresh cycles. Huawei Technologies anchors significant production capacity for enterprise-grade flash systems across Asian markets.
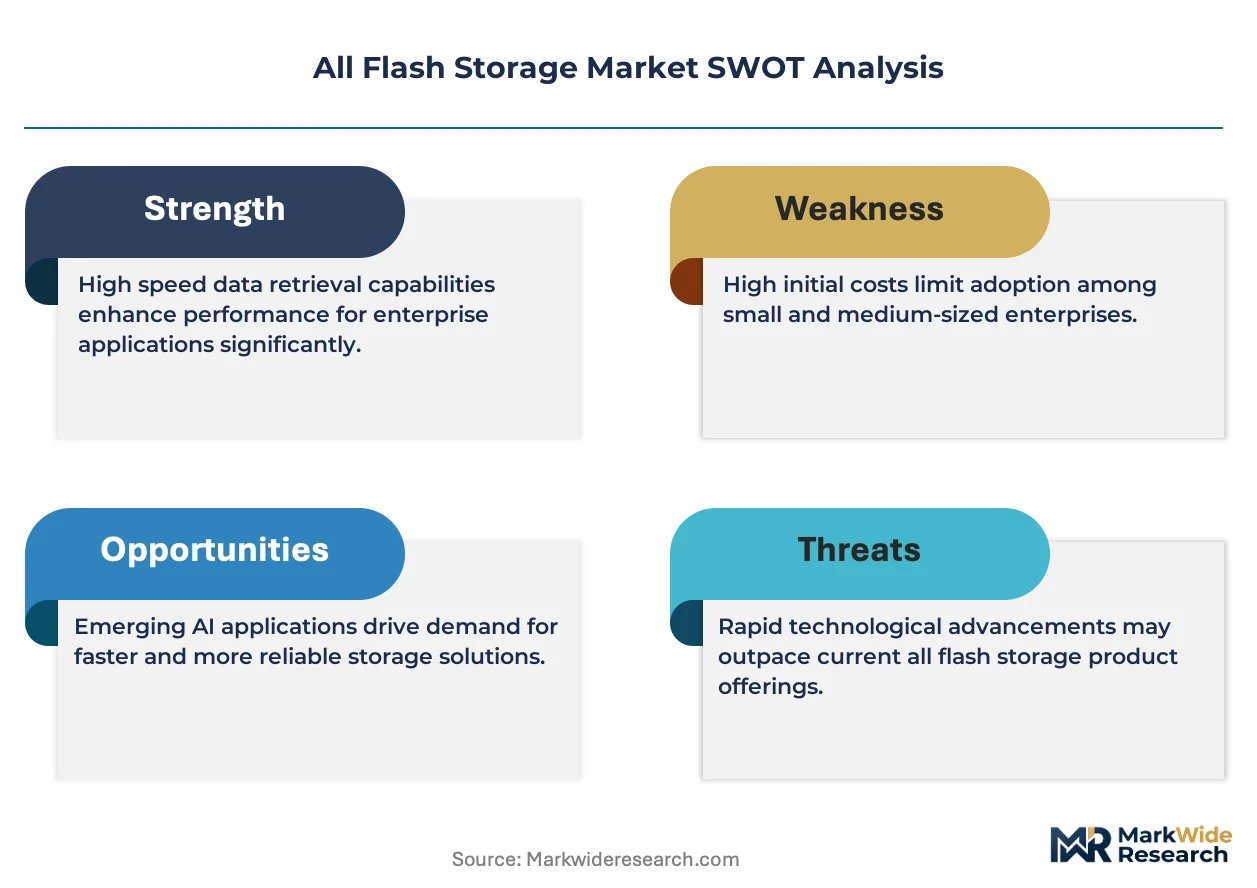
All flash storage denotes data storage systems built exclusively on NAND flash memory, typically employing NVMe over Fabrics or PCIe interfaces to deliver sub-100 microsecond latency and millions of IOPS per array. These systems replace hybrid or disk-based architectures in latency-critical workloads such as real-time analytics, high-frequency trading, and virtualized infrastructure. Unified storage configurations lead enterprise deployments by consolidating block, file, and object protocols within single platforms. NVMe interface adoption represents the fastest-expanding segment as datacenter operators retire SAS and SATA interconnects. On-premises deployment retains the largest installed base, though hybrid cloud configurations are capturing incremental growth from regulated industries seeking burst capacity.
FCC equipment authorization rules govern electromagnetic emissions for flash storage systems sold into US infrastructure, while EU RoHS and REACH frameworks restrict hazardous substances in printed circuit boards and solder materials. Japan's METI energy efficiency standards shape power consumption benchmarks for enterprise storage installations. ISO 27001 certification requirements increasingly filter procurement decisions at financial services and healthcare organizations. Stakeholders must weigh interface transition timelines against legacy protocol support obligations when committing to multi-year refresh cycles.
Market Dynamics
NVMe over Fabrics adoption is compressing refresh cycles across enterprise datacenters, forcing incumbents to rearchitect controller silicon and software stacks around disaggregated storage pools rather than monolithic arrays.
Growth Catalysts
- EU AI Act data localization mandates:Financial services firms in Frankfurt and Amsterdam are pre-positioning flash capacity to satisfy sovereign inference requirements.
- High-frequency trading infrastructure:Chicago and London exchanges demand sub-50 microsecond latency for order matching engines, disqualifying hybrid disk systems from RFP consideration.
- PCIe Gen5 interface penetration:New server platforms from Intel and AMD double lane bandwidth, enabling denser flash packaging without controller bottlenecks.
Market Restraints
- NAND wafer supply concentration:Three Korean and Taiwanese foundries control 78% of advanced node output, creating allocation risk during demand spikes.
- RoHS solder material restrictions:EU ECHA substance bans force manufacturers to qualify alternative metallurgy, extending qualification timelines by 8-14 months.
- QLC endurance limitations:Write-intensive workloads in transactional databases degrade quad-level cell media faster than TLC alternatives, narrowing applicable use cases.
Strategic Opportunities
- India BIS mandatory certification:Local assembly requirements for government cloud infrastructure create captive demand for flash arrays with domestic firmware signing.
- Computational storage convergence:Processing-in-memory architectures from Samsung and SK Hynix merge analytics and storage tiers, reducing data movement overhead.
- Japan METI carbon footprint labeling:Power efficiency disclosures favor all-flash replacements of legacy disk farms in Tokyo and Osaka metro datacenters.
Industry Challenges
- Firmware security certification backlog:Common Criteria EAL4+ evaluations for financial sector procurement now queue 18-24 months at accredited laboratories.
- Legacy SAN protocol support obligations:Fibre Channel and iSCSI backward compatibility consumes 40% of controller development resources despite declining attachment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All Flash Storage Market |
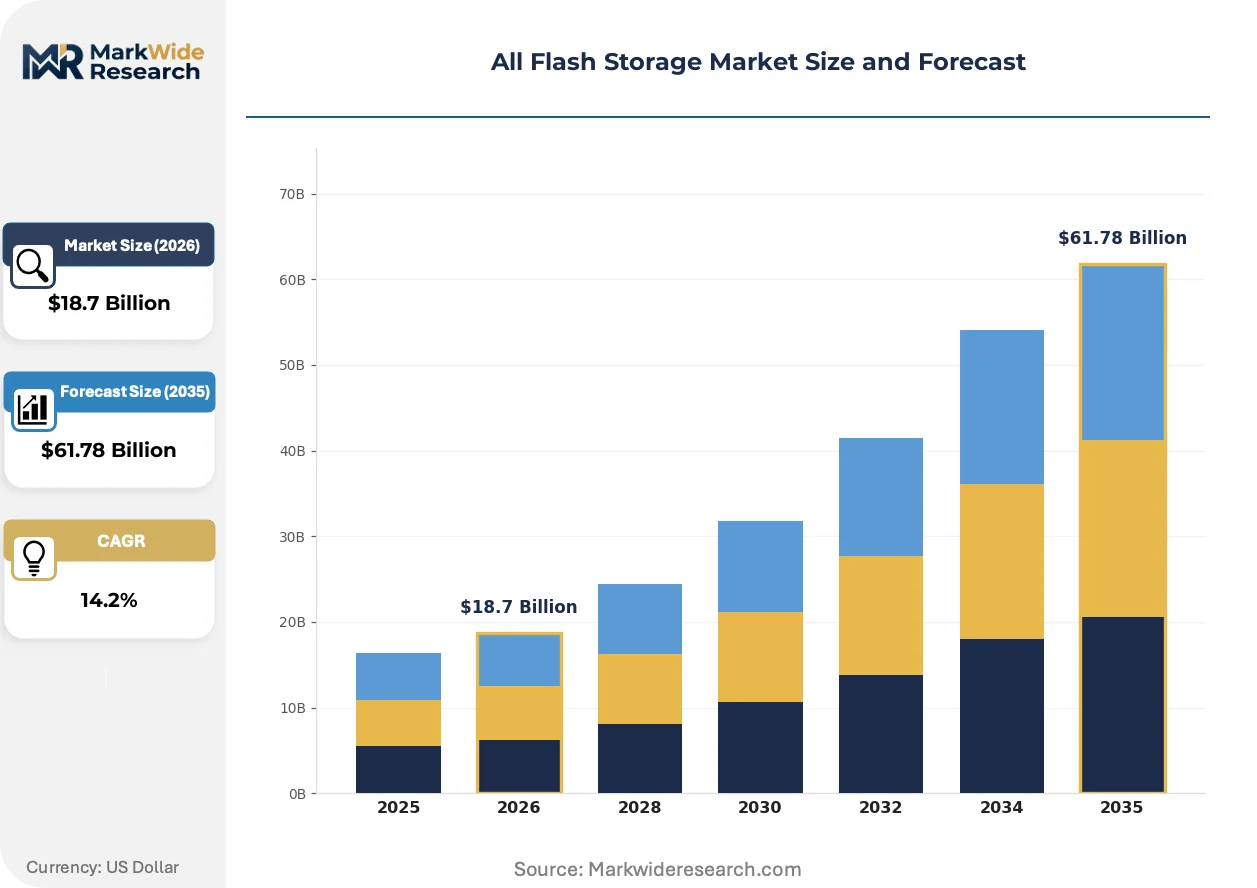
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unified Storage, Block Storage, File Storage, Object Storage End User: Cloud Service Providers, Enterprise, SMB, Government Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud Interface Type: SAS, SATA, NVMe, FC |
| Companies Covered | Dell Technologies, NetApp, Pure Storage, Hewlett Packard Enterprise, IBM Corporation, Huawei Technologies, Hitachi, Western Digital, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All Flash Storage Market Emerging Trajectories
Storage-class memory hierarchies are collapsing the distinction between volatile and persistent tiers, with byte-addressable media forcing software-defined architectures to rewrite caching algorithms and failure-domain assumptions.
Computational storage drives with embedded ARM cores is modularizing array intelligence, pushing RAID, encryption, and compression functions from central controllers directly onto NAND modules. Hyperscale operators in Oregon and Virginia are qualifying these devices for object storage disaggregation, stripping out traditional storage server overhead. The structural compression of controller BOM costs is enabling new entrants to compete on firmware differentiation alone.
EU CSRD sustainability disclosure rules now mandate Scope 3 emissions reporting for ICT infrastructure, capturing embodied carbon in flash module manufacturing. German automotive OEMs and French banking consortiums are inserting these requirements into storage RFP scoring matrices. Suppliers with verified lifecycle data from Korean foundries secure preference in Brussels-procured contracts.
Consumption-based financing models are displacing capital purchase cycles for midmarket enterprises, with equipment-as-a-service contracts bundling hardware, software, and refresh guarantees into per-terabyte-month pricing. Channel partners in Texas and Illinois are retraining sales organizations around annuity economics rather than upfront margin capture. Healthcare verticals with constrained capex budgets show highest contract velocity under this structure.
All Flash Storage Market Segmentation
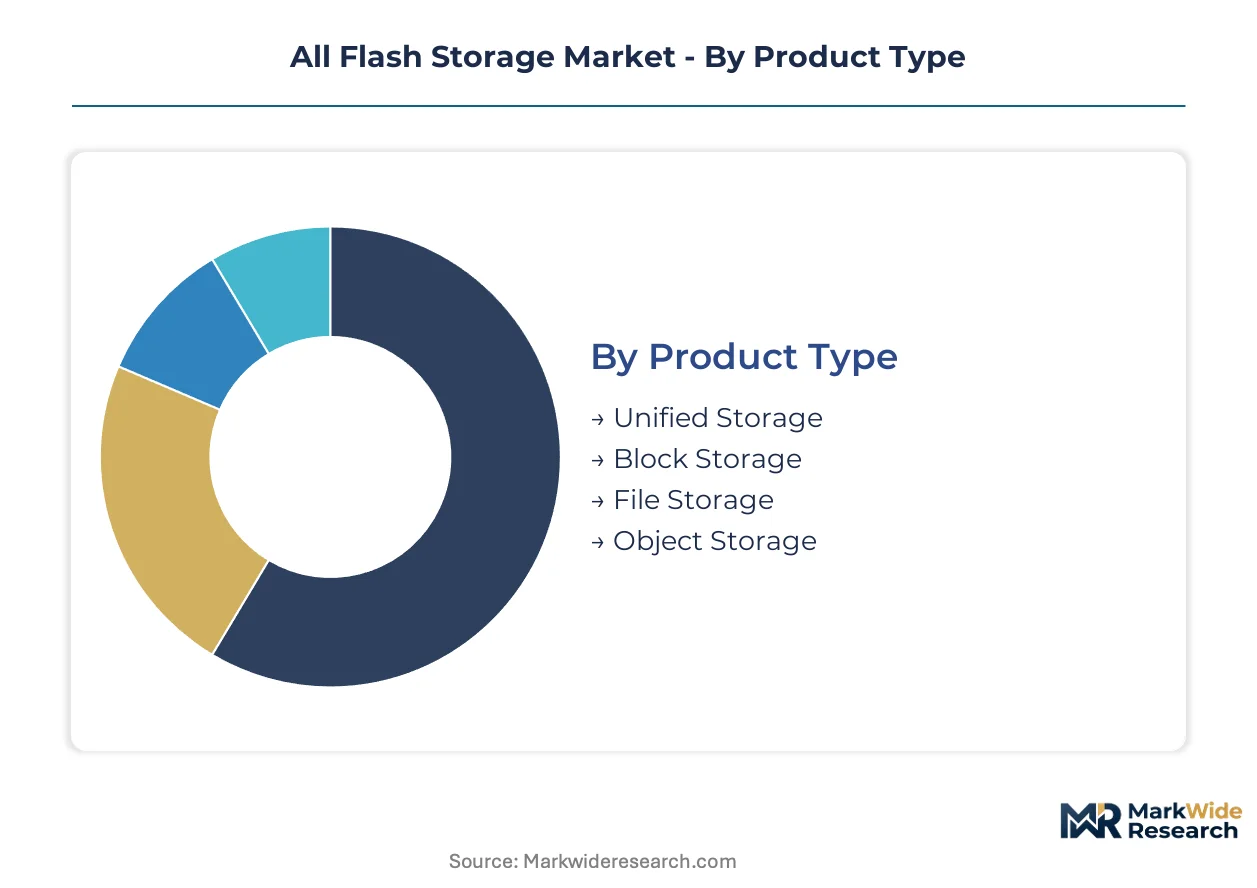
Segmentation in all-flash storage reveals how interface transitions and deployment preferences reshape procurement patterns. Understanding these divisions exposes where legacy protocol obligations clash with next-generation performance requirements across buyer categories.
Product Type:
Volume deployments cluster around consolidated platforms, while specialized architectures command premium positioning in latency-sensitive environments.
- Unified Storage:Consolidates block, file, and object protocols within single controller domains. Financial services firms in Frankfurt and Amsterdam deploy these systems to satisfy EU AI Act data localization mandates without protocol silos.
- Block Storage:Delivers raw LUN presentation optimized for database and virtualized workloads. High-frequency trading venues in Chicago and London specify sub-50 microsecond latency configurations that disqualify hybrid alternatives from RFP consideration.
- File Storage:NFS and SMB protocol serving for unstructured data repositories. Media production houses leverage these systems for 4K/8K rendering pipelines.
- Object Storage:Flat namespace architecture for cloud-native and archival applications. Hyperscale operators in Oregon and Virginia qualify these for S3-compatible disaggregation.
Today's leader: Unified Storage. Tomorrow's challenger: Object Storage.
End User:
Procurement authority concentrates with operators managing sovereign infrastructure, while commercial buyers prioritize consumption flexibility.
- Cloud Service Providers:Hyperscale operators purchasing at petabyte scale with custom firmware requirements. These buyers in Virginia and Oregon drive NVMe over Fabrics qualification timelines.
- Enterprise:Fortune 500 organizations with multi-protocol legacy obligations. German automotive OEMs insert EU CSRD Scope 3 emissions scoring into storage RFP matrices.
- SMB:Midmarket organizations adopting equipment-as-a-service contracts. Healthcare verticals in Texas and Illinois show highest contract velocity under per-terabyte-month structures.
- Government:Sovereign cloud and defense procurement with certification backlogs. India's BIS mandatory certification creates captive demand for arrays with domestic firmware signing.
Enterprise dominates current procurement volume. Cloud Service Providers are climbing the fastest.
Deployment Model:
Physical control preferences fragment across regulatory exposure and burst capacity requirements.
- On-Premises:Captive datacenter installations with full operational sovereignty. Retains the largest installed base as regulated industries maintain direct media control.
- Hybrid Cloud:Tiered architectures spanning owned infrastructure and burst capacity. French banking consortiums deploy these configurations for GDPR-sensitive primary data with anonymized analytics in public tiers.
- Public Cloud:Fully managed flash services from hyperscale operators. Startups in Bangalore and São Paulo adopt these for zero-capex scaling.
- Private Cloud:Dedicated single-tenant environments within service provider facilities. Japanese financial institutions favor these for METI energy efficiency compliance with outsourced operations.
On-Premises holds current dominance. Hybrid Cloud offers the steepest expansion trajectory.
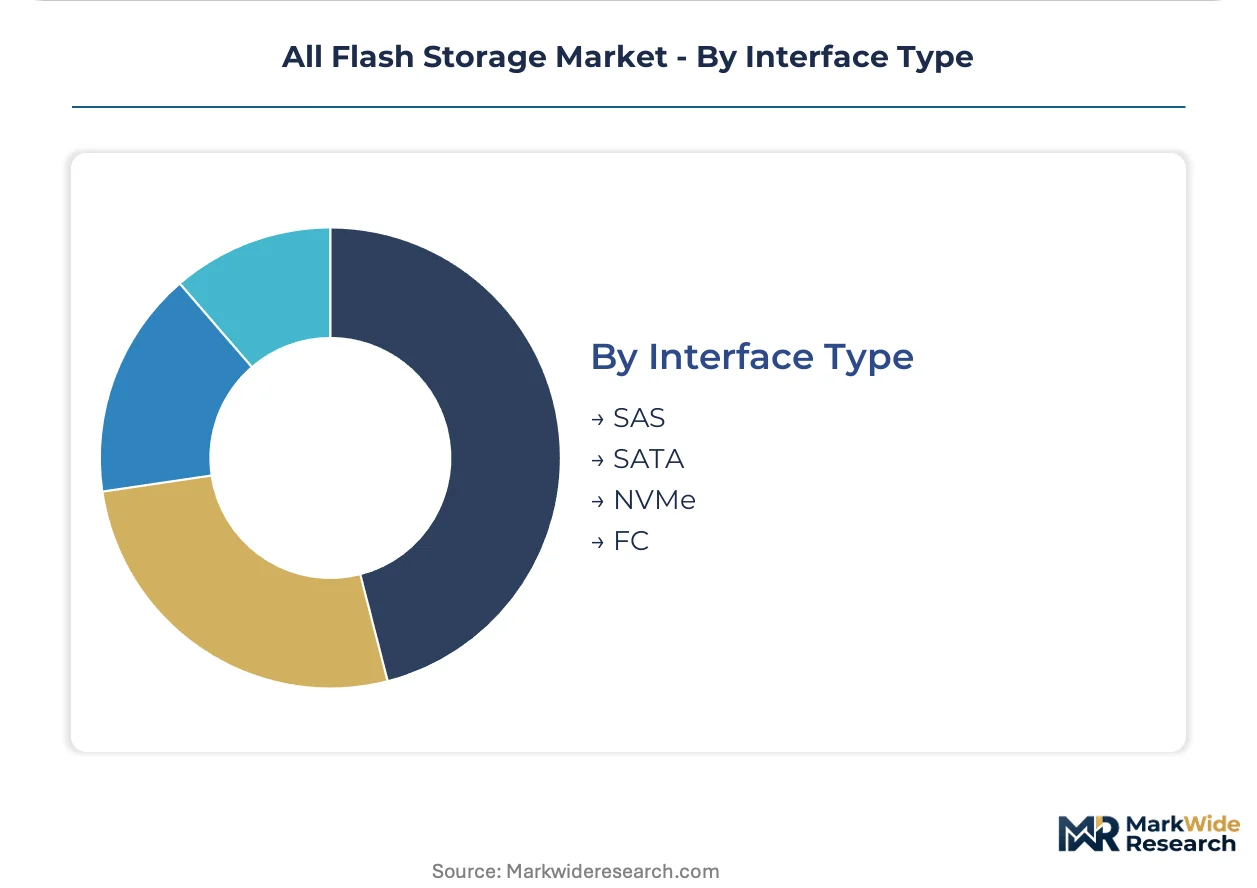
Interface Type:
Protocol transition timelines determine controller development allocation and backward compatibility burdens.
- NVMe:PCIe-attached flash with sub-100 microsecond latency and millions of IOPS per array. Intel and AMD server platforms with PCIe Gen5 double lane bandwidth, enabling denser packaging without controller bottlenecks.
- SAS:Serial-attached SCSI legacy interconnect for existing infrastructure. Declining attachment rates consume 40% of controller development resources despite phase-out timelines.
- SATA:Legacy disk-era interface surviving in cost-optimized tiers. Budget-constrained education and municipal buyers in US Midwest maintain these attachments.
- FC:Fibre Channel protocol for established SAN fabrics. Large German and US healthcare networks preserve these investments for MRI and PACS archival systems.
NVMe commands technology leadership. FC persists as the stubborn incumbent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
All-flash storage infrastructure originated in Silicon Valley datacenters during the 2000s, then scaled through German automotive and Japanese financial clusters before diffusing to sovereign cloud deployments across Asia-Pacific and Europe.
United States
Hyperscale operators in Virginia and Oregon drive NVMe over Fabrics qualification timelines for petabyte-scale procurement. FCC equipment authorization rules govern electromagnetic emissions for systems deployed into federal and financial infrastructure. Chicago and New York metro exchanges demand sub-50 microsecond latency configurations that disqualify hybrid alternatives from RFP consideration.
Germany
Frankfurt and Amsterdam financial services firms pre-position flash capacity to satisfy EU AI Act data localization mandates. REACH chemical compliance and EU CSRD sustainability disclosure rules reshape procurement scoring matrices for German automotive OEMs. Bavarian and Baden-Württemberg industrial clusters embed these requirements into supplier qualification protocols.
Japan
Tokyo and Osaka metro datacenters replace legacy disk farms under METI energy efficiency standards and carbon footprint labeling requirements. Japanese financial institutions favor private cloud configurations for outsourced operations with compliance guarantees. Kanto and Kansai industrial corridors concentrate enterprise-grade flash deployment for manufacturing analytics.
India
BIS mandatory certification for government cloud infrastructure creates captive demand for arrays with domestic firmware signing. Bangalore and Hyderabad hyperscale campuses adopt public cloud flash services for zero-capex scaling. Maharashtra and Karnataka state procurement policies increasingly specify local assembly requirements for sovereign data infrastructure.
South Korea
Seoul Capital Area semiconductor foundries anchor advanced NAND wafer supply for enterprise-grade flash systems. MFDS-equivalent standards for data integrity and national cybersecurity frameworks shape financial sector procurement. Busan-Ulsan industrial complexes integrate these storage tiers into shipbuilding and heavy manufacturing digitalization programs.
All Flash Storage Market Vendor Landscape
The competitive structure tilts toward vertically integrated technology conglomerates with captive NAND supply chains. Dell Technologies leverages backward integration across memory foundries to sustain margin control against pure-play array vendors. Three strategic archetypes dominate: diversified IT infrastructure conglomerates, software-defined storage specialists, and Asian electronics conglomerates with semiconductor fabrication assets. Competitive moves concentrate on controller silicon rearchitecture and qualification acceleration for NVMe over Fabrics deployments.
Within the diversified infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions spanning server, storage, and networking portfolios with global service footprints. Pure Storage exemplifies the software-defined specialist archetype through subscription-based consumption models that reduce hardware refresh cycles. Huawei Technologies anchors the Asian conglomerate vector with significant production capacity for enterprise-grade systems across regional markets. IBM Corporation represents the legacy technology integrator position with mainframe-attached storage heritage and financial sector certification depth.
| Leading Market Players |
|---|
| Dell Technologies |
| NetApp |
| Pure Storage |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Huawei Technologies |
| Hitachi |
| Western Digital |
| Lenovo |
| Others |
Supply Flow & Price Mechanics
NAND wafer costs cascade through three distinct pricing tiers before reaching end-user procurement decisions. Korean and Taiwanese foundry output feeds into controller silicon packaging, where PCIe Gen5 qualification premiums separate enterprise-grade arrays from midmarket configurations. FCC equipment authorization and EU REACH compliance burdens accumulate at each conversion stage, compressing margins for vendors without captive NAND supply.
Pricing Analysis
Equipment-as-a-service contracts now dominate midmarket procurement, collapsing upfront capital expenditure into per-terabyte-month operational line items. Price differentiation rests on firmware certification depth and domestic-content compliance rather than raw hardware specifications. Cost compression in the SMB tier intensifies as channel partners in Texas and Illinois retrain sales organizations around annuity economics. Cloud service providers exhibit lowest price sensitivity due to petabyte-scale purchasing power, while healthcare verticals with constrained capex budgets drive highest contract velocity under subscription structures.
Supply Chain Analysis
India's BIS mandatory certification and domestic firmware signing requirements are forcing manufacturers to localize final assembly and software loading operations. Advanced NAND wafer production concentrates in South Korea and Taiwan, with controller silicon design anchored in the United States and Israel. Raw material dependencies span silicon substrates from Japanese suppliers, specialty gases from German chemical conglomerates, and lead-free solder materials qualified under EU RoHS restrictions. Single-source vulnerability persists at the foundry level where three suppliers control advanced node output. Distribution runs through authorized channel partners with certified technical capabilities for enterprise deployment and ongoing firmware maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The all-flash storage market compounds steadily as datacenter infrastructure refresh cycles compress under NVMe over Fabrics adoption. Sovereign data localization mandates across multiple jurisdictions ensure durable replacement demand regardless of macroeconomic fluctuations.
For Market Incumbents: Acquire controller silicon design capabilities to reduce dependence on merchant semiconductor suppliers. Dell Technologies and Hewlett Packard Enterprise should deepen backward integration into NAND packaging operations to defend margin position against pure-play array vendors. Firmware security certification depth represents the critical lever for financial sector retention as Common Criteria EAL4+ evaluation queues extend to 24 months. For New Entrants and Emerging Players: Enter via India's government cloud infrastructure segment where BIS mandatory certification creates captive demand for arrays with domestic firmware signing. Target healthcare verticals in Texas and Illinois with equipment-as-a-service contracts that bypass incumbent capital sales relationships. White-space exists in computational storage convergence where processing-in-memory architectures reduce data movement overhead for analytics workloads. For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined architectures enable firmware-only differentiation without captive NAND supply. Long-term viability favors vendors with verified lifecycle data from Korean foundries for EU CSRD Scope 3 emissions compliance. Target acquisition archetype: subscription-based storage specialists with healthcare and financial sector certification depth. Watch for inflection where PCIe Gen6 interface standards trigger controller silicon rearchitecture and qualification acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Silicon Rearchitecture | NVMe over Fabrics qualification timelines compress refresh cycles for hyperscale operators in Virginia. |
| Firmware Security Certification Investment | Common Criteria EAL4+ depth secures financial sector procurement in Frankfurt and Amsterdam. |
| Domestic Assembly Localization | India BIS certification requirements create captive demand for government cloud infrastructure. |
| Subscription Model Transition | Per-terabyte-month pricing captures healthcare verticals with constrained capex budgets in Texas. |
| Sustainability Data Verification | Verified Korean foundry lifecycle data secures preference in Brussels-procured contracts. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster informing cross-validation. Datacenter infrastructure directors, storage procurement officers at financial services firms, channel sales executives, and firmware engineering leads contributed structured interviews. Secondary sources include hyperscaler capex disclosures, SEC filings from diversified IT infrastructure conglomerates, EU regulatory filings under CSRD and AI Act frameworks, and customs data for NAND module trade flows. Bottom-up demand aggregation across end-user segments triangulates against top-down supply-side capacity assessments.
Granularity-level modeling extends to interface type transitions, deployment model preferences, and certification tier penetration across the projection horizon. Segmentation dimensions include product architecture, end-user procurement authority, physical deployment location, and protocol interface generation. CAGRs derive from installed base replacement velocity and net new capacity absorption patterns. Industry-specific inputs incorporate PCIe lane bandwidth evolution, foundry node transition timelines, and sovereign cloud procurement policy shifts.
Inputs from hyperscaler infrastructure teams and channel partner networks were available through the study window; gaps in classified defense procurement introduce uncertainty bands around government segment estimates. Forecasts reflect assumptions regarding interface transition timelines, regulatory certification backlog resolution, and NAND wafer supply allocation stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
NAND Flash Memory Market
Data Storage
Blu-Ray Drive Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Germany Data Center Storage Market
Data Storage
Storage and Management Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Americas Flash Memory Market
Data Storage
Universal Flash Storage Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Storage Area Network Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Middle East and Africa AMH and Storage Systems Market
Data Storage
Archival Grade Blu-Ray Discs Market