
 Burst Strength Tester Market | 2026-2036
Burst Strength Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Burst Strength Tester Market Intelligence
The integration of cloud-based software for data analytics and compliance reporting is restructuring the traditional hardware-centric sales model. Thwing-Albert Instrument Company leverages its long-standing reputation in materials testing to offer integrated software and hardware packages. PRESTO specializes in providing robust, application-specific testers for the paper and packaging industries in emerging economies. Labthink International competes on the basis of advanced sensor technology and global service networks.
A burst strength tester is a quality control instrument designed to measure the rupture resistance of materials like paper, board, and textiles. It operates by applying controlled hydraulic or pneumatic pressure to a clamped sample until failure, recording the peak pressure in units such as PSI. Pneumatic testers maintain a significant share for standard applications, while digital models with automated data logging are gaining traction in the packaging and plastics segments. The textiles application remains a mature and stable segment for these devices.
Compliance with international standards such as ISO 2758 for paper and ISO 13938-2 for textiles is a critical purchasing factor for end-users. National-level specifications, including ASTM D774 in the United States and GB/T 454 in China, further dictate instrument calibration and testing protocols. Future product development will focus on integrating machine learning for predictive failure analysis and reducing material waste during quality control.
Market Dynamics
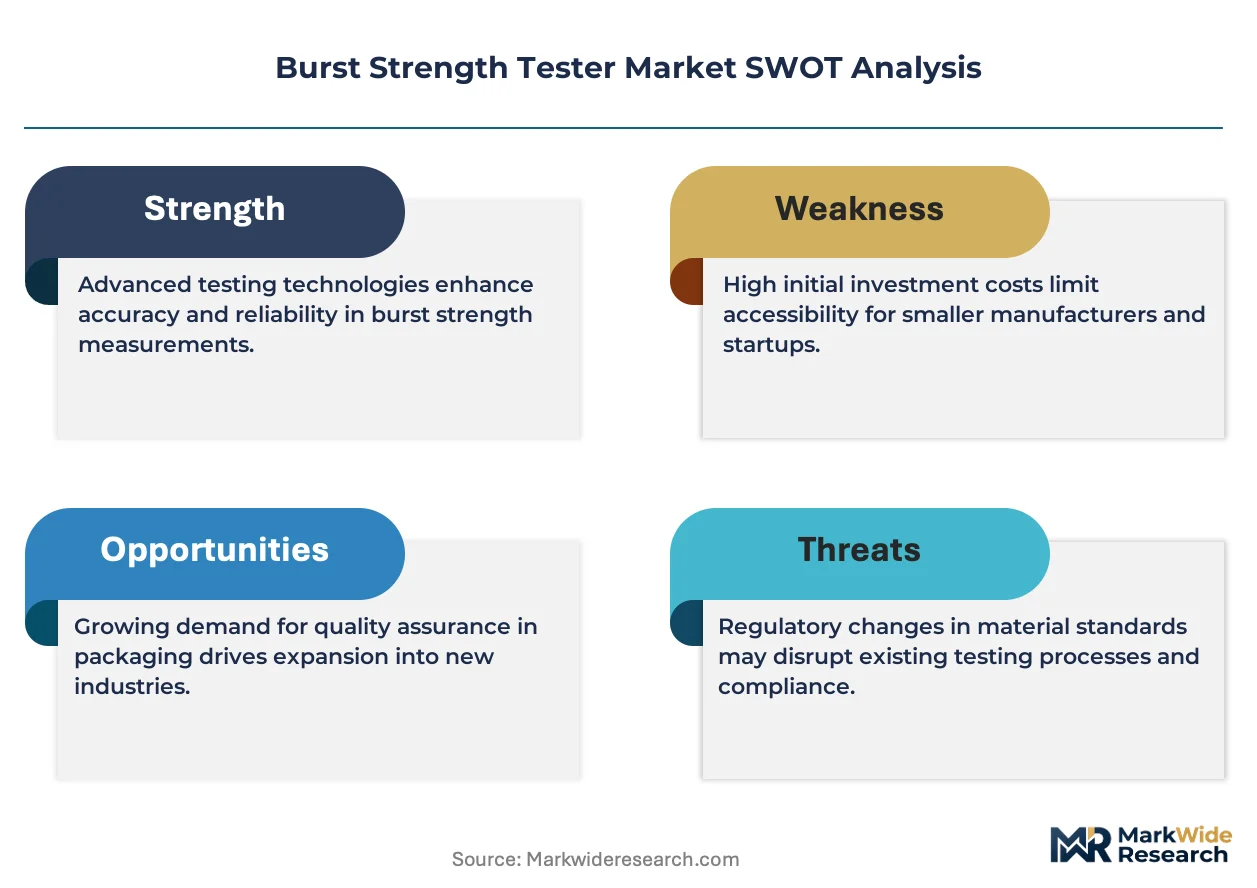
The central force shaping the market is the shift in material science, particularly the widespread adoption of recycled paperboard and advanced flexible composites in packaging. This evolution demands more precise, repeatable, and data-rich burst strength validation, moving beyond traditional mechanical testing capabilities.
Growth Catalysts
- E-commerce Packaging Demands:The expansion of e-commerce logistics chains necessitates more durable corrugated boxes and mailers to survive transit, directly fueling demand for testers to verify material specifications.
- Advanced Materials Adoption:The use of non-woven textiles in medical applications and composite materials in lightweight automotive parts requires precise burst strength characterization to ensure product safety and performance.
- Regulatory Compliance Mandates:Adherence to international standards like ISO 2758 for paper and national specifications such as China's GB/T 454 makes calibrated testing equipment a mandatory asset for market access.
Market Restraints
- High Capital Outlay:The significant initial investment for advanced digital burst strength testers with automated data logging and environmental controls can be prohibitive for smaller manufacturers and testing labs.
- Technical Calibration Requirements:Maintaining the accuracy of hydraulic and pneumatic systems necessitates specialized technicians and frequent, costly calibration, which increases the total cost of ownership over the instrument's lifecycle.
- Availability of Alternative Tests:For certain flexible films and thin paper grades, alternative material property tests like tear strength and tensile strength can provide sufficient quality data, substituting the need for a burst tester.
Strategic Opportunities
- Integration with Predictive Analytics:Leveraging machine learning algorithms to analyze burst test data offers an opportunity to predict material failure points in production, enabling proactive quality control and reducing waste.
- Testing for Biodegradable Materials:The growing market for bio-plastics and compostable packaging films creates a new application frontier, requiring burst strength data to validate the integrity of sustainable materials.
- Expansion in Industrializing Economies:Rising quality control standards in the food and beverage packaging sectors across Southeast Asia and Latin America represent an underpenetrated geographic opportunity for instrument sales.
Industry Challenges
- Skilled Technician Shortage:A deficit of operators trained in both materials science and data analysis for cloud-connected instruments hinders the effective deployment and utilization of modern testers' advanced features.
- Data Integration Complexity:Connecting new digital burst testers with legacy Manufacturing Execution Systems (MES) and enterprise resource planning (ERP) software on the factory floor poses significant interoperability challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burst Strength Tester Market |
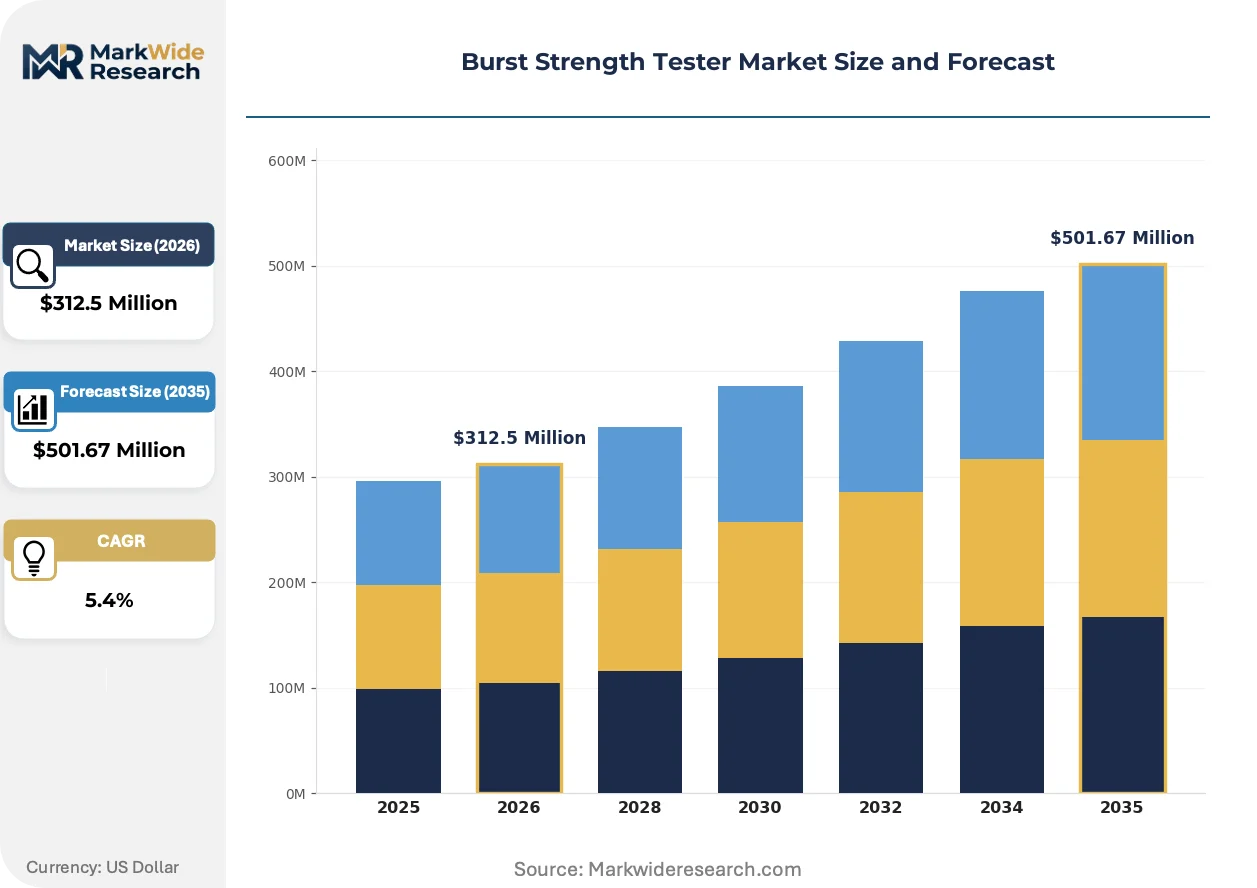
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Mechanical, Pneumatic, Hydraulic Application: Textiles, Plastics, Packaging, Composites End User: Manufacturers, R&D Labs, Quality Control, Educational Institutions Technology: Computerized, Manual, Semi-Automatic, Automated |
| Companies Covered | Thwing-Albert Instrument Company, James Heal, PRESTO, TESTEX, Asian Test Equipments, GESTER, Qualitest International, Pacorr, Labthink International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burst Strength Tester Market Strategic Shifts & Innovations
The market's trajectory is defined by a fundamental transition from standalone, mechanical test instruments to integrated, data-driven quality assurance platforms. This evolution connects the physical point of material failure directly with digital process control, supply chain verification, and regulatory compliance workflows.
Digital testers featuring automated sample clamping, integrated sensors, and direct software connectivity are becoming prevalent. The packaging and plastics industries are key adopters, seeking to enhance testing accuracy and throughput. This technology is automating the entire quality control sequence, from pressure application to data capture and certificate generation, significantly reducing operator influence and error.
Global adherence to ISO 13938-2 for textiles establishes a critical benchmark for fabric burst strength evaluation. This standard specifies precise testing conditions, including diaphragm dimensions and pressurization rates, which directly shapes instrument design for textile producers. The technical textiles segment, encompassing materials for geotextiles and protective apparel, must invest in compliant equipment to ensure product reliability and global market access.
A shift from one-time hardware transactions to integrated hardware-and-software service models is altering commercial relationships. Customers in regulated sectors increasingly procure comprehensive packages that bundle the instrument with ongoing calibration, data analytics, and automated compliance reporting software. This trend is most visible in the medical device packaging industry in Europe and the United States, where data integrity and audit trails are critical.
Burst Strength Tester Market Segmentation
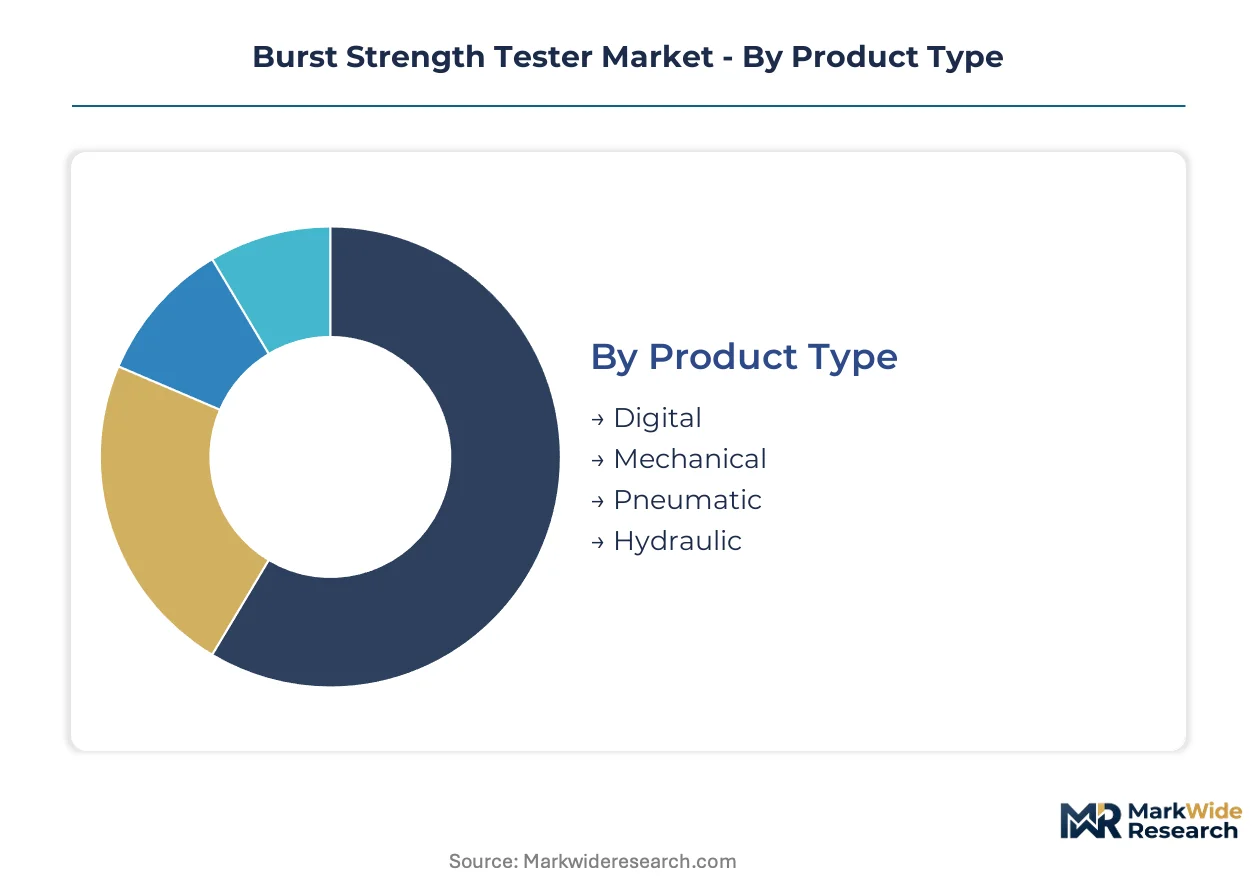
The Burst Strength Tester market's structure reflects diverse testing requirements across various industries and material types. Understanding these segments helps identify specific technological needs and market opportunities for instrument manufacturers. Precise segmentation allows companies to tailor product development and service offerings to distinct end-user demands.
Product Type:
The market for burst strength testers is differentiated by the underlying mechanism used to apply pressure, influencing precision and application scope.
- Digital:These testers integrate electronic sensors and microprocessors for precise pressure measurement and automated data logging. Demand concentrates in the packaging and plastics segments seeking enhanced accuracy and reduced operator error in quality control.
- Mechanical:Mechanical testers rely on physical gauges and manual operation, offering a cost-effective solution for basic burst strength assessments. These models find use in smaller manufacturing facilities requiring straightforward, robust equipment.
- Pneumatic:Pneumatic testers utilize air pressure to apply force, maintaining a significant share for standard applications due to their consistent pressure application. Their adoption is widespread in the paper and board industries for routine quality checks.
- Hydraulic:Hydraulic testers employ liquid pressure to generate high forces, making them suitable for materials requiring substantial burst strength evaluation. These instruments are critical for testing heavy-duty textiles and composite materials.
Mature deployment sits with Mechanical testers. Newer deployment is concentrated in Digital models.
Application:
Burst strength testing finds critical application across a spectrum of materials, each presenting unique testing challenges and compliance needs.
- Textiles:This segment involves evaluating the resistance of woven and non-woven fabrics to rupture, crucial for apparel, upholstery, and technical textiles. Compliance with ISO 13938-2 establishes a critical benchmark for fabric burst strength evaluation.
- Plastics:Burst strength testing for plastics primarily focuses on films, sheets, and molded components, ensuring their integrity under stress. This application is vital for food packaging and medical device manufacturing.
- Packaging:The packaging sector, particularly corrugated boxes and flexible packaging, relies heavily on burst strength testers to verify material durability against transit stresses. The expansion of e-commerce logistics chains directly fuels demand in this area.
- Composites:Testing composite materials, including those for lightweight automotive parts and industrial applications, requires precise burst strength characterization. This ensures product safety and performance in demanding environments.
The Packaging application represents the fastest-growing trajectory, driven by e-commerce demands.
End User:
Various organizational types utilize burst strength testers, each with distinct purchasing criteria and operational requirements.
- Manufacturers:Production facilities integrate burst strength testers directly into their quality assurance processes to monitor material consistency and product integrity. These users prioritize repeatability and integration with factory floor systems.
- R&D Labs:Research and development laboratories employ these instruments for material characterization, new product development, and performance optimization. Their focus often lies on advanced features and data analysis capabilities.
- Quality Control:Dedicated quality control departments and third-party testing houses use burst strength testers for compliance verification and incoming material inspection. Adherence to national and international standards like ASTM D774 is a critical purchasing factor for these entities.
- Educational Institutions:Universities and technical colleges utilize burst strength testers for teaching materials science principles and conducting academic research. These institutions often seek versatile and user-friendly equipment.
Manufacturers are the largest end-user group, while Quality Control departments show robust demand.
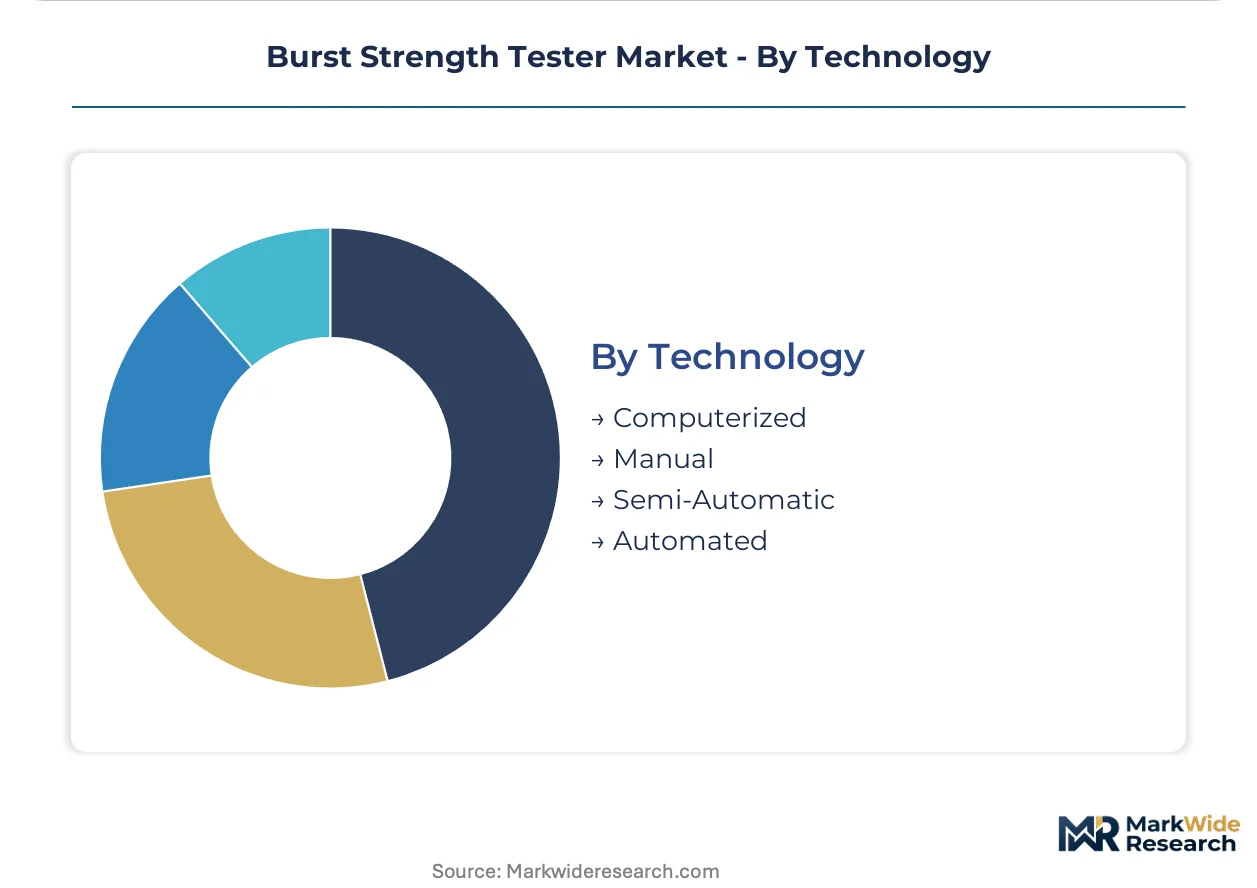
Technology:
The technological sophistication of burst strength testers ranges from basic manual operations to fully automated, data-driven systems.
- Computerized:These testers connect to external software for data acquisition, analysis, and reporting, enhancing measurement precision and traceability. The integration of cloud-based software for compliance reporting is restructuring the traditional sales model for these devices.
- Manual:Manual testers require direct operator involvement for sample clamping, pressure application, and result reading, offering a straightforward and economical solution. They are typically found in settings with lower testing volumes or budget constraints.
- Semi-Automatic:Semi-automatic testers automate some aspects of the testing process, such as pressure application, while still requiring operator intervention for sample handling. These devices balance automation benefits with operational simplicity.
- Automated:Fully automated testers handle sample loading, testing, and data recording with minimal human input, maximizing throughput and reducing variability. The packaging and plastics industries are key adopters, seeking to enhance testing accuracy and throughput.
The market shows a strong movement towards Automated and Computerized technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of burst strength testers is often concentrated in specific manufacturing hubs, while consumption is more widespread, driven by diverse industrial quality control needs. This creates a geographical divide between instrument supply and end-user demand for material validation. The global market reflects this dynamic, with key regions showing distinct growth patterns.
China
Demand for testers is substantial due to its vast manufacturing base and e-commerce growth. GB/T 454 standards are crucial for paper and board quality, mandating precise testing. Industrial zones like the Yangtze River Delta drive adoption in packaging, textiles, and advanced materials manufacturing.
Germany
Advanced manufacturing and a strong focus on engineering drive demand for precise burst strength validation. CE marking and other EU regulations ensure high testing standards for products entering the European market. The Rhine-Ruhr region's automotive and packaging industries utilize these instruments extensively for material characterization.
United States
E-commerce expansion and medical device packaging fuel significant demand for durable materials validation. ASTM D774 specifies testing protocols for paper products, ensuring material compliance. The Northeast corridor and California's tech manufacturing hubs require stringent material verification for product safety.
India
Rapid industrialization and a growing packaging sector, particularly for food and beverage, increase the need for quality control. BIS standards guide material testing and product certification across various industries. Manufacturing clusters in Gujarat and Maharashtra are adopting digital testers for enhanced accuracy.
Japan
High-tech manufacturing and a focus on advanced composites necessitate precise burst strength characterization. JIS standards ensure material reliability across industries, from electronics to automotive. The Kanto region's electronics and automotive sectors demand robust testing solutions for product development and quality assurance.
Burst Strength Tester Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized manufacturers and regional players address niche applications and cost-sensitive markets. This tiered structure reflects varying technological capabilities and geographic reach among market participants. Strategic archetypes include traditional hardware providers, integrated hardware-software solution developers, and application-specific specialists. Dominant competitive moves involve geographic expansion into emerging economies and portfolio diversification to include cloud-based analytics.
Thwing-Albert Instrument Company, with its long-standing reputation, exemplifies established players offering integrated software and hardware packages. PRESTO, a company specializing in application-specific testers, occupies a position serving the paper and packaging industries in emerging economies. Labthink International, leveraging advanced sensor technology, represents firms focused on global service networks and precise measurement capabilities.
| Leading Market Players |
|---|
| Thwing-Albert Instrument Company |
| James Heal |
| PRESTO |
| TESTEX |
| Asian Test Equipments |
| GESTER |
| Qualitest International |
| Pacorr |
| Labthink International |
| Others |
Cost & Logistics Intelligence
The widespread adoption of digital burst strength testers, moving beyond traditional mechanical models, simultaneously reshapes cost economics and concentrates supply in specialized electronics manufacturing hubs. This technological evolution influences both instrument production complexity and end-user procurement strategies.
Pricing Analysis
Cost-down pressure on mechanical burst strength testers accelerates because basic functionality faces commoditization. The dominant pricing model for advanced digital testers is a tiered subscription for software and data analytics, often bundled with the hardware. Price differentiation stems from sensor accuracy, software integration capabilities, and after-sales service levels. Manufacturers and R&D labs exhibit lower price sensitivity for high-precision instruments, while smaller quality control labs are most price-sensitive.
Supply Chain Analysis
Manufacturing of advanced burst strength testers rests on specialized sensor and micro-electronics producers in Germany and Japan. Key component dependencies include high-precision pressure transducers and integrated circuit boards. A structural risk involves single-source vulnerability for specialized hydraulic components. Downstream distribution runs through a network of regional instrument distributors and direct sales channels, especially for enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Burst Strength Tester market navigates a technology-transition phase, with advanced digital models increasingly replacing legacy mechanical and pneumatic instruments. This shift empowers data-driven quality control across diverse industrial applications.
For Market Incumbents:Extend existing customer relationships by offering integrated hardware and cloud-based software solutions for compliance reporting. This strategy counters the threat from specialized software providers and maintains market share against new entrants focusing on data analytics. Invest in R&D for machine learning integration to enhance predictive failure analysis capabilities. Control key distribution channels in established markets like Germany and the United States.
For New Entrants and Emerging Players:Capture market share by focusing on application-specific testers for biodegradable materials in industrializing economies. The food and beverage packaging sector in Southeast Asia represents a penetrable segment for robust, cost-effective solutions. A strong go-to-market angle involves direct sales with localized service support and compliance with national BIS standards in India. Target the underserved market for compostable packaging films.
For Investors and Strategic Acquirers:Re-rating potential sits with integrated hardware-software solution providers given the accelerating shift towards data-driven quality assurance. Long-term viability favors companies able to bundle advanced digital testers with ongoing calibration and analytics services. Acquisition targets include firms with proprietary sensor technology or strong cloud-based data platforms. A signal to watch is the increasing regulatory mandates for digital audit trails in packaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered predictive failure analytics | This enhances material quality control and reduces waste in manufacturing processes. |
| Expand sales and service networks in Southeast Asia | This addresses rising quality control needs in emerging food and beverage packaging sectors. |
| Integrate cloud-based compliance reporting software | This provides value-added services for regulated industries like medical device packaging. |
| Invest in advanced sensor technology for composites | This enables precise characterization of high-performance materials in automotive applications. |
| Offer comprehensive hardware-software service bundles | This shifts revenue models from one-time sales to recurring service subscriptions for end-users. |
Research Approach
Independent corroboration across industry association reports, materials science journals, and regulatory body publications underwrites the qualitative findings. Primary interviews with R&D directors, quality control managers, and instrument procurement specialists provided critical insights. Secondary data sources included company annual reports, trade statistics, and technical specifications from ISO and ASTM. A rigorous bottom-up and top-down triangulation process validated market size and growth estimates.
The analytical framework decomposed the rate of change by product type, application, end user, and technology across the modeling period. Segmentation dimensions modeled included material types like paper and plastics, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected digital solution adoption rates. Key forecast inputs included e-commerce growth and advanced material development.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and material science breakthroughs. Forecasts reflect assumptions regarding technological adoption and global economic stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
Humidity Testers Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Compression Testers Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
LCR Meter Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market