
 Coaxial Cable Market | 2026-2036
Coaxial Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Coaxial Cable Market Analysis
The coaxial cable industry is restructuring around a widening performance gap between aerospace-grade low-loss assemblies and mass-market RG-6 commodity reels. Prysmian Group leverages its vertically integrated copper and compound operations to control input costs across European broadband projects. TE Connectivity differentiates through precision connector systems that dominate military and test-measurement channels. Belden Inc. specializes in broadcast infrastructure cables that sustain premium pricing in stadium and studio deployments.
A coaxial cable consists of a central copper conductor, dielectric insulator, metallic shield, and outer jacket engineered to transmit radio frequency signals with controlled impedance, typically 50 or 75 ohms across specified frequency ranges. Its shielded construction minimizes electromagnetic interference, making it indispensable for video distribution, cellular backhaul, and precision instrumentation where signal integrity governs system performance. RG-6 dominates residential television and internet drops due to its balance of attenuation characteristics and installation flexibility, while RG-11 occupies margin-rich trunk line applications requiring longer unrepeatered spans. CCTV and security installations represent the fastest-growing application vector as municipal surveillance networks and commercial access control systems expand camera counts per site.
FCC broadband equity regulations shape United States demand by mandating minimum speed thresholds that preserve coaxial hybrid deployments in cost-sensitive rural markets. REACH and RoHS frameworks in Europe restrict halogenated flame retardants and heavy metals in cable compounds, forcing reformulation of jacket materials across export-oriented manufacturers. China's GB standards and MIIT certification requirements govern 5G infrastructure coaxial specifications, creating compliance barriers for uncertified suppliers. Stakeholders must monitor evolving spectrum reallocations and building code fire-rating requirements that could obsolete existing cable inventories or open replacement cycles.
Market Dynamics
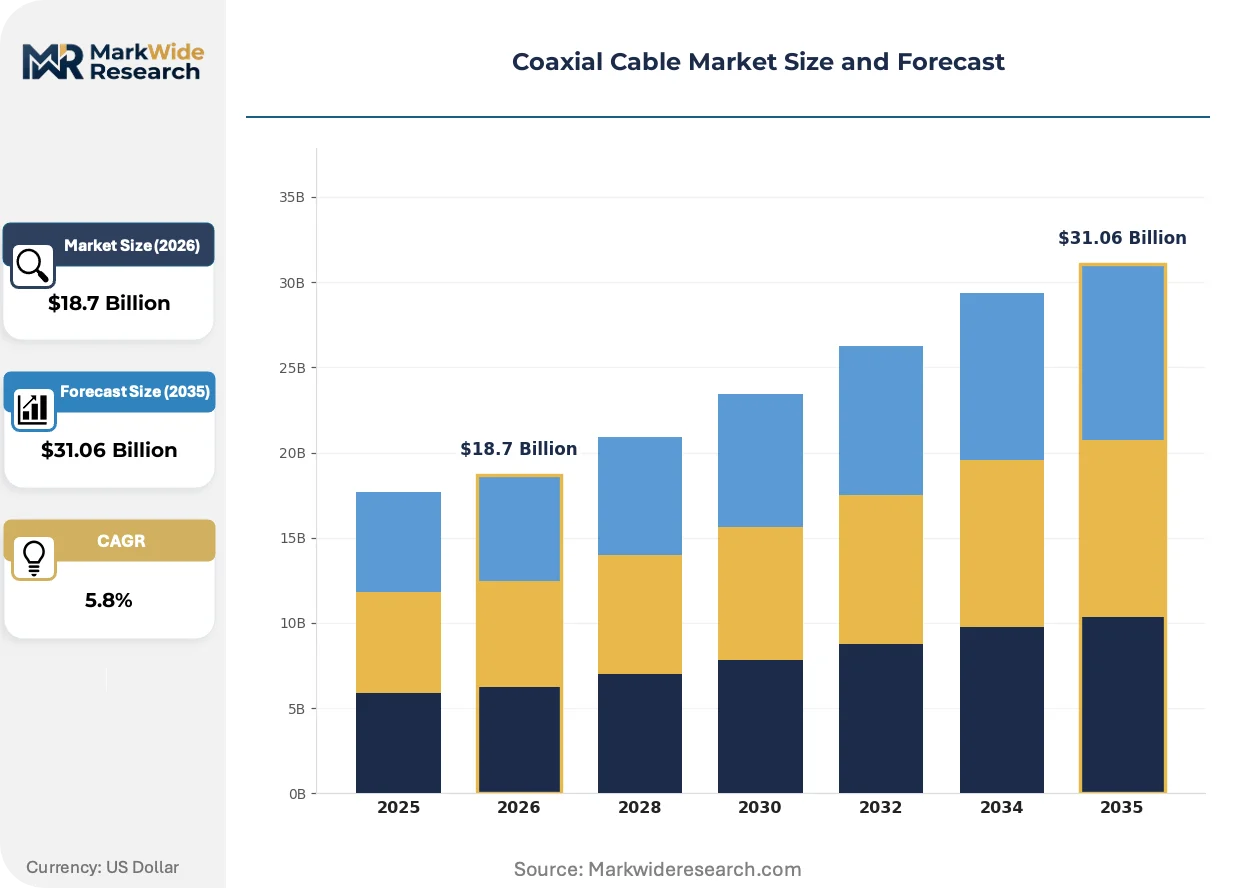
The coaxial cable market restructures around hybrid fiber-coaxial architectures that preserve copper last-mile infrastructure while fiber penetrates deeper into distribution networks. This technological tension between fiber displacement and coaxial persistence defines competitive positioning across telecommunications, broadcast, and security verticals.
Growth Catalysts
- 5G Base Station Buildouts:China's MIIT certification requirements for 5G infrastructure coaxial specifications are driving demand for high-performance RF assemblies in macro cell deployments.
- Rural Broadband Equity Mandates:The FCC's broadband equity programs in the United States preserve hybrid coaxial deployments in cost-sensitive rural markets where full fiber replacement remains uneconomical.
- Surveillance Network Densification:Municipal smart city video surveillance networks are expanding camera counts per site, requiring ruggedized outdoor coaxial runs for power-over-coax and HD video transmission.
Market Restraints
- Copper Price Volatility:Central conductor materials expose manufacturers to London Metal Exchange copper price swings that compress margin predictability on long-diameter trunk cables.
- Fiber Substitution Pressure:Passive optical network technology is displacing coaxial in greenfield residential deployments, constraining volume growth in premium RG-11 trunk segments.
- Halogenated Compound Restrictions:REACH and RoHS frameworks in Europe restrict halogenated flame retardants in jacket materials, forcing costly reformulation of legacy cable compounds.
Strategic Opportunities
- Aerospace-Grade Low-Loss Assemblies:Satellite ground station and unmanned aerial vehicle communication links require precision coaxial with attenuation specifications that sustain premium pricing tiers.
- India's Smart City Mission:Municipal surveillance and traffic management infrastructure under India's urban renewal programs represents underpenetrated demand for armored outdoor coaxial installations.
- Power-over-Coax Convergence:Integration of DC power transmission with RF signal carriage is enabling single-cable deployments in retrofit security installations where pulling additional conductors proves prohibitive.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized impedance matching and shielding effectiveness design expertise concentrates among aging workforce cohorts, constraining product development velocity.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of FCC, CE marking, and GB standard approvals extends time-to-revenue for new cable platforms targeting export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaxial Cable Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RG-6, RG-59, RG-11, RG-8 Application: Television, Internet, Telecommunications, CCTV End User: Residential, Commercial, Industrial, Educational Installation Type: Indoor, Outdoor, Underground, Aerial |
| Companies Covered | Prysmian Group, TE Connectivity, CommScope, HUBER+SUHNER, Times Microwave Systems, Belden Inc., Amphenol Corporation, LS Cable & System, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaxial Cable Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are reshaping how coaxial cables balance electrical performance with environmental compliance. Manufacturers reformulate dielectric and jacket compounds while preserving impedance stability across temperature extremes.
Expanded polytetrafluoroethylene (ePTFE) dielectric technology is expanding into aerospace and test-measurement applications demanding minimal signal loss at millimeter-wave frequencies. Defense contractors and satellite operators specify ePTFE-based assemblies for phase-stable performance in thermal cycling environments. This material migration is compressing market share for traditional polyethylene dielectrics in premium performance tiers.
The EU's RoHS recast and REACH SVHC candidate list restrictions on halogenated flame retardants are compelling jacket compound reformulations across export-oriented manufacturers. Cable producers substitute phosphorus-nitrogen intumescent systems for legacy brominated additives to maintain fire ratings while preserving European market access. Asian compound suppliers are accelerating R&D investment to match European incumbents' halogen-free portfolio breadth.
Security integrators are consolidating procurement around pre-terminated coaxial assemblies with factory-tested connector integrity, displacing field-terminated bulk cable purchases. This specification shift favors vertically integrated manufacturers with captive connector production over commodity reel distributors. The preference for tested assemblies is most visible in North American stadium and critical infrastructure deployments where installation labor costs exceed material differentials.
Coaxial Cable Market Segmentation
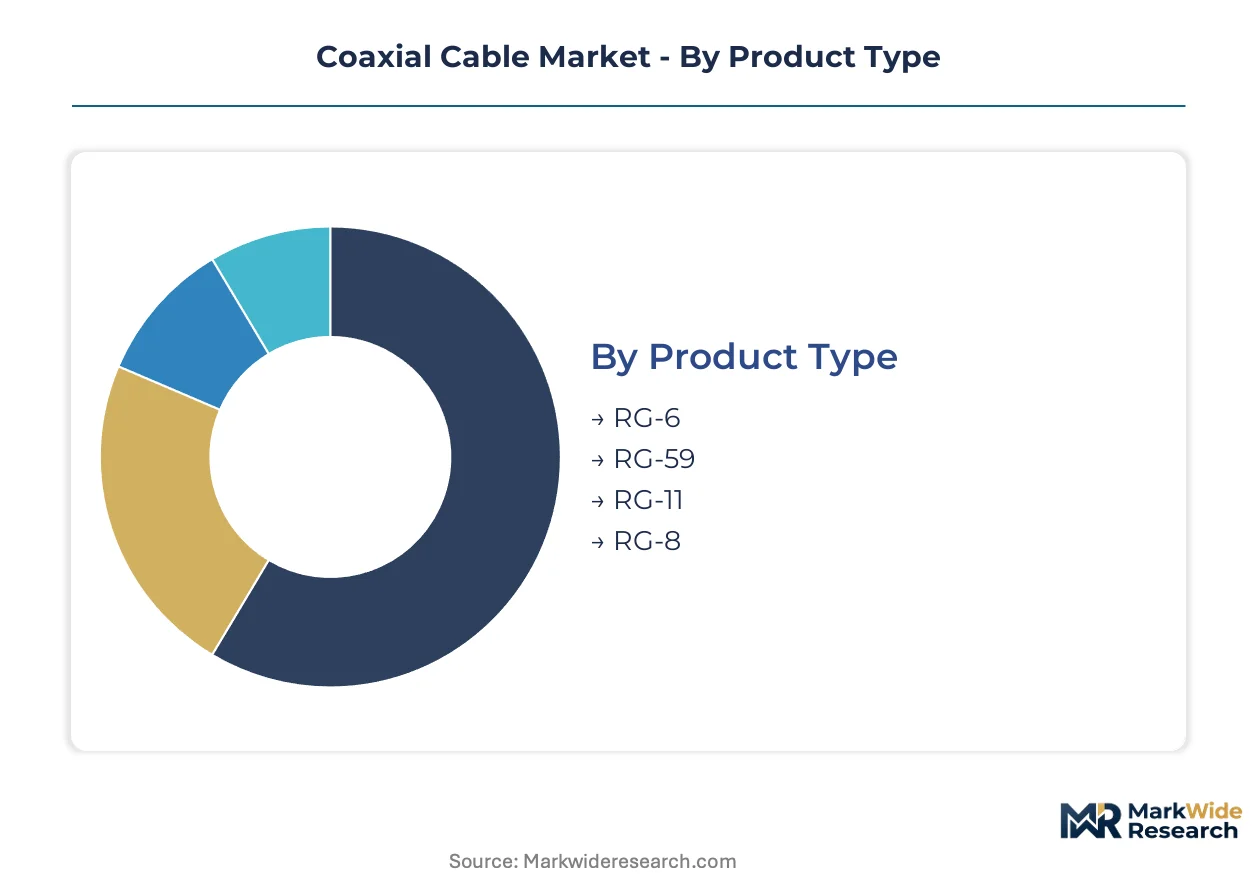
Coaxial cable procurement patterns diverge sharply between standalone residential drops and embedded infrastructure systems. Manufacturers configure conductor gauges, shield densities, and jacket compounds differently depending on whether cables terminate at consumer premises or integrate into complex network architectures.
Product Type:
Integration depth varies enormously across impedance-matched families, with some formats engineered for discrete subscriber drops and others for trunkline embedding within hybrid fiber-coaxial hierarchies.
- RG-6:This 75-ohm cable employs a 18 AWG copper-clad steel center conductor with foam polyethylene dielectric and dual or quad shielding. Residential broadband deployments in the United States under FCC equity programs specify RG-6 for last-mile drops where fiber replacement costs prove prohibitive.
- RG-11:Thicker 14 AWG conductor construction reduces attenuation across longer unrepeatered spans. Trunkline applications in China's 5G base station buildouts favor RG-11 for macro cell feeder connections where signal integrity governs network performance.
- RG-59:Legacy 20 AWG conductor format with higher loss characteristics. Legacy CCTV retrofits and short-run security installations in commercial buildings still specify RG-59 where existing conduit constraints prevent thicker cable pulls.
- RG-8:Heavy-duty 50-ohm construction for amateur radio and specialized RF transmission. Test-measurement laboratories and military ground stations specify RG-8 for high-power signal carriage.
Volume placements concentrate in RG-6; the faster expansion belongs to RG-11.
Application:
Cost tier differentiation separates commodity video distribution from precision telecommunications infrastructure where impedance stability commands premium positioning.
- Television:Broadcast headend-to-transmitter links and satellite downlink facilities require phase-stable coaxial with temperature-compensated dielectrics. Stadium and studio deployments sustain premium pricing through Belden's specialized broadcast infrastructure cables.
- CCTV:Power-over-coax convergence enables single-cable retrofit installations. Municipal smart city surveillance networks in India and China are expanding camera counts per site, requiring armored outdoor coaxial runs for HD video transmission.
- Internet:Hybrid fiber-coaxial architectures preserve copper last-mile infrastructure. Rural United States markets under broadband equity mandates maintain coaxial internet drops where full fiber replacement remains uneconomical.
- Telecommunications:Cellular backhaul and base station feeder connections demand precision RF assemblies. China's MIIT certification requirements govern 5G infrastructure coaxial specifications.
Revenue concentration sits with telecommunications infrastructure; CCTV climbs the fastest as surveillance densification accelerates.
End User:
Customer type determines specification rigor, with industrial and educational deployments imposing stricter fire-rating and shielding effectiveness standards than residential mass-market procurement.
- Residential:Mass-market RG-6 deployments for television and internet drops. Installation flexibility and cost sensitivity dominate procurement criteria in single-family and multi-dwelling unit construction.
- Commercial:Office buildings and retail complexes specify plenum-rated jackets for indoor runs. Access control systems and internal video networks drive coaxial demand in commercial real estate.
- Industrial:Harsh-environment specifications with armored jackets and extended temperature ranges. Manufacturing facilities and petrochemical plants require ruggedized coaxial for process control and safety monitoring.
- Educational:Campus-wide video distribution and security networks. K-12 and university procurement favors pre-terminated assemblies to minimize installation labor costs.
Unit volume leadership belongs to residential; industrial applications show the steepest expansion trajectory.
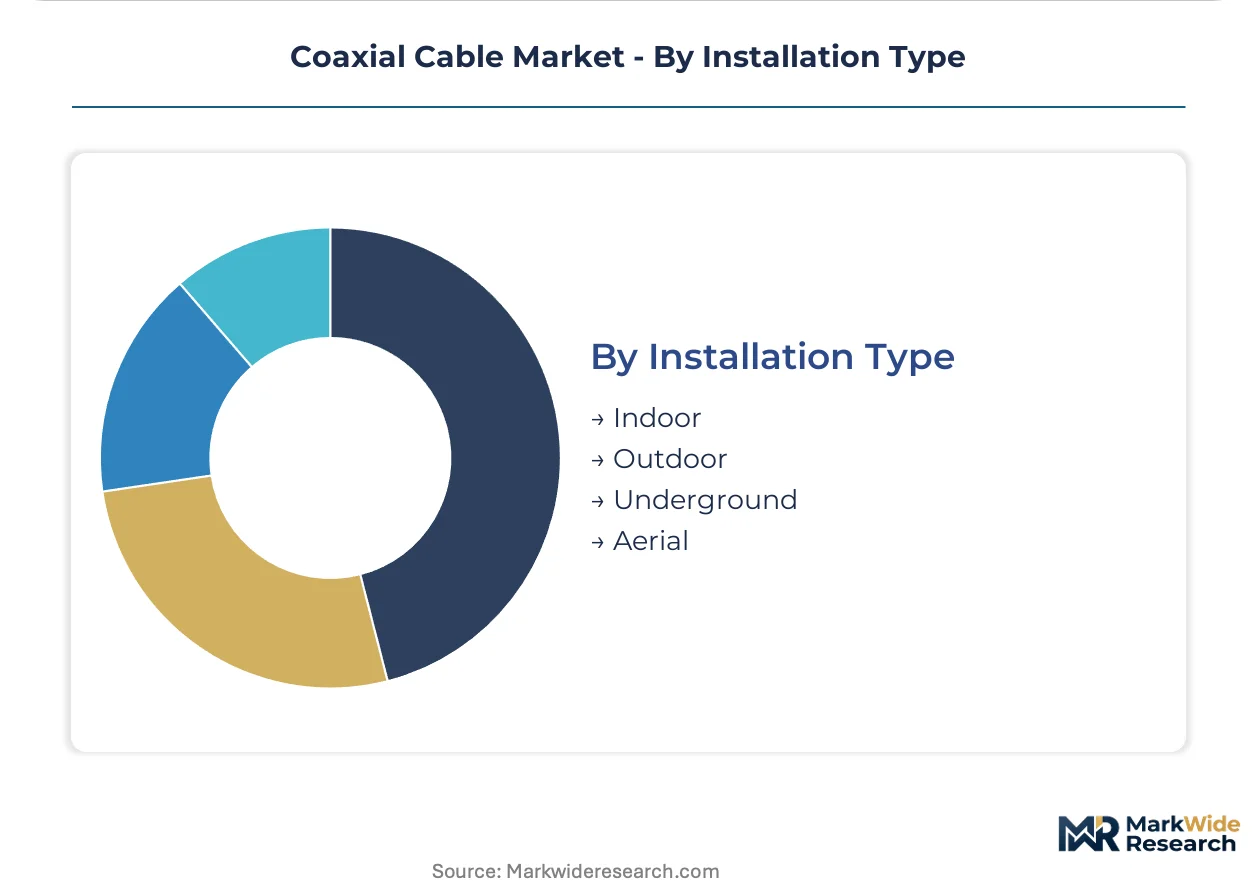
Installation Type:
Supply concentration patterns align with environmental exposure severity, as jacket compound formulations and mechanical protection requirements escalate from climate-controlled indoor spaces to aerial and underground deployments.
- Outdoor:UV-resistant polyethylene jackets and flooded core construction prevent moisture ingress. Smart city video surveillance networks specify outdoor-rated coaxial for municipal camera infrastructure.
- Underground:Direct-burial rated cables with metallic armor and water-blocking compounds. Utility and transportation infrastructure projects require underground coaxial for signal integrity across long unrepeatered spans.
- Indoor:Plenum and riser-rated jackets for building code compliance. Commercial and educational deployments concentrate procurement of indoor-rated coaxial for structured cabling systems.
- Aerial:Messenger-supported construction for pole-mounted installations. Rural broadband extensions and utility communications networks specify aerial coaxial where underground trenching proves cost-prohibitive.
Procurement volume clusters in indoor installations; outdoor specifications gain share fastest as surveillance network densification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors coaxial cable manufacturing capacity, with the Pearl River Delta cluster feeding both domestic 5G infrastructure and export demand for telecommunications-grade assemblies.
United States
Rural broadband equity mandates from the FCC preserve hybrid coaxial deployments in cost-sensitive markets where full fiber replacement remains uneconomical. The FCC's broadband equity programs channel investment toward network densification in underserved counties. Installation demand concentrates in Texas and the Southeast, where utility cooperatives extend aerial coaxial infrastructure.
China
MIIT certification requirements for 5G infrastructure specifications drive procurement of high-performance RF assemblies in macro cell deployments. GB standards govern coaxial specifications for base station buildouts, creating compliance barriers for uncertified suppliers. Manufacturing gravity sits in Guangdong province, where compound suppliers and cable fabricators cluster around Shenzhen's electronics corridor.
Germany
REACH and RoHS frameworks restrict halogenated flame retardants in jacket materials, forcing reformulation of legacy cable compounds for European market access. ECHA's SVHC candidate list pressures Asian compound suppliers to match European halogen-free portfolio breadth. Industrial demand centers in Baden-Württemberg, where automotive test facilities and precision instrumentation manufacturers specify phase-stable coaxial.
India
Municipal surveillance and traffic management infrastructure under the Smart City Mission generates underpenetrated demand for armored outdoor coaxial installations. BIS certification requirements and TRAI spectrum allocations shape procurement specifications for telecommunications infrastructure. Project deployment concentrates in Maharashtra and Gujarat, where urban renewal programs expand camera counts per site.
Coaxial Cable Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market that splits between integrated compound-to-cable operators and specialized assembly houses. Prysmian Group and Nexans anchor the integrated tier with captive copper and polymer operations, while TE Connectivity and Amphenol occupy precision connector-centric positions. Three archetypes dominate: vertically integrated European industrials, North American precision interconnect specialists, and Asian scale producers. Competitive moves center on halogen-free compound reformulation and pre-terminated assembly capabilities.
Among European-based integrated manufacturers, Prysmian Group and Nexans represent the compound-to-cable archetype with upstream control over conductor and jacket materials. TE Connectivity exemplifies the precision interconnect specialist model, with connector systems anchoring military and test-measurement channel positions. These three companies illustrate how competitive positioning splits between cost-controlled vertical integration and premium-tier impedance-matching expertise.
| Leading Market Players |
|---|
| Prysmian Group |
| TE Connectivity |
| CommScope |
| HUBER+SUHNER |
| Times Microwave Systems |
| Belden Inc. |
| Amphenol Corporation |
| LS Cable & System |
| Nexans |
| Others |
Supply Flow & Price Mechanics
REACH and RoHS frameworks in Europe gate qualified supply and premium-tier pricing access by mandating halogen-free jacket compounds that only certified compounders can formulate. Manufacturers without compliant formulations face exclusion from European telecommunications and broadcast infrastructure tenders, compressing their addressable market to commodity segments.
Pricing Analysis
Signal attenuation performance at millimeter-wave frequencies anchors value-based pricing tiers. Aerospace-grade ePTFE dielectric cables command substantial premiums over polyethylene-based RG-6 commodity reels due to phase stability specifications in thermal cycling environments. Price differentiation separates MIIT-certified 5G infrastructure assemblies from uncertified alternatives in China's base station buildouts. Cost compression in RG-6 residential drops is intensifying because copper price volatility and fiber substitution pressure squeeze margin predictability. Municipal procurement offices exhibit highest price sensitivity; defense contractors and satellite operators demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong province compound suppliers concentrated around Shenzhen's electronics corridor. Manufacturing gravity draws from China, South Korea, and Germany for precision dielectric extrusion equipment and copper conductor drawing lines. Raw material dependencies rest on London Metal Exchange copper cathodes, polyethylene and fluoropolymer resin feedstocks, and brominated flame retardant alternatives. Tariff exposure on Chinese-manufactured cable assemblies shipped to North American telecommunications infrastructure projects presents structural risk. Distribution runs through vertically integrated European industrials, North American precision interconnect specialists, and Asian scale producers serving distinct certification-tier markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified halogen-free compound production capacity represents the binding constraint propping premium-tier pricing, as European cable manufacturers scramble for compliant jacket material supply.
For Market Incumbents: To counter fiber-to-the-premises displacement in greenfield residential deployments, Prysmian Group and Nexans should deepen backward integration into captive copper smelting and halogen-free compound formulation to preserve margin structures. TE Connectivity must fortify military and test-measurement channel positions through precision connector R&D investment that sustains impedance-matching expertise scarcity. For New Entrants and Emerging Players: FCC broadband equity programs in the United States open a window for regional cable fabricators to capture rural hybrid coaxial deployment contracts where logistics costs disadvantage distant integrated producers. India's Smart City Mission surveillance infrastructure presents the most penetrable geography for armored outdoor coaxial specialists. A go-to-market angle emphasizing factory-tested pre-terminated assemblies with certified connector integrity addresses North American installation labor cost sensitivity. For Investors and Strategic Acquirers: MIIT certification approval timelines extending beyond historical norms is the leading indicator that Chinese 5G infrastructure coaxial specifications are tightening, favoring incumbent certification holders over new market entrants. The long-term viability window favors acquisition targets with established halogen-free compound portfolios and captive connector production capabilities. Watch for European compound suppliers accelerating R&D investment to match halogen-free portfolio breadth as the signal of certification barrier hardening.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Compound Reformulation | REACH and RoHS compliance preserves European market access for jacket material suppliers. |
| Pre-Terminated Assembly Expansion | Factory-tested connector integrity captures North American stadium and critical infrastructure procurement. |
| MIIT Certification Investment | GB standards compliance unlocks China's 5G base station buildout procurement channels. |
| Copper Conductor Backward Integration | Captive smelting operations buffer London Metal Exchange price volatility on trunk cable margins. |
| Power-over-Coax Convergence Development | Single-cable retrofit capability addresses municipal surveillance densification retrofit constraints. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with RF engineering directors, telecommunications procurement managers, compound supplier technical leads, and security systems integrators combined with FCC broadband equity program disclosures, MIIT certification databases, ECHA SVHC candidate list updates, and London Metal Exchange copper price series. Bottom-up segment sizing and top-down macroeconomic reconciliation validated volume and value estimates across the analysis window.
Data-stream reconciliation across product type, application, end user, and installation environment dimensions produced consistent growth trajectories. Impedance specifications, shielding effectiveness ratings, and temperature range certifications served as industry-specific forecast inputs. CAGRs were derived from segment-level volume projections and price trajectory assumptions without year-specific anchoring.
The model assumes a particular technology adoption path; alternative pathways for passive optical network fiber substitution would alter the outlook for RG-11 trunk cable demand. Forecasts reflect assumptions about copper price stability, regulatory certification timeline continuity, and 5G infrastructure deployment pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Lugs Market
Cables
Global Ethernet Cable Market
Cables
Cable Management Accessories Market
Cables
Europe Wire and Cable Market
Cables
Cable Detector Market
Cables
Asia-Pacific Premise Cable Market
Cables
Cable Accessories Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
GCC Cable Accessories Market
Cables
Mexico Wires and Cables Market
Cables
Submarine Cabling Systems Market
Cables
Polyurethane Cable Market
Cables
XLPE Cables Market
Cables
Copper Cable Market
Cables
Medium Voltage Cables Accessories Market
Cables
Shipboard Cable Market