
 Underground Cable Market | 2026-2036
Underground Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Cable Market Analysis
Maintenance and lifecycle service contracts is consolidating into bundled offerings that redefine supplier-customer relationships in the underground cable sector. Prysmian Group leverages its European manufacturing footprint to anchor long-term utility partnerships. LS Cable & System dominates high-voltage submarine-to-underground transition projects across East Asian markets. Nexans competes through specialized fire-resistant compounds for tunnel and metro applications.
Underground cable denotes insulated conductors engineered for subterranean deployment, typically featuring cross-linked polyethylene or ethylene propylene rubber insulation rated between 1 kV and 500 kV, manufactured through continuous vulcanization extrusion to ensure moisture barriers and mechanical crush resistance for power transmission and telecommunications routing. Power cables occupy the largest value pool given grid modernization cycles, while fiber optic cables represent the fastest-expanding segment driven by 5G backhaul and data center interconnect requirements. Copper material grades command premium positioning in high-current urban networks, whereas aluminum gains share in cost-sensitive rural installations.
EMA's MDR framework and the EU F-Gas Regulation shape insulation gas selection and cable sealing standards across European procurement specifications. China's GB standards and NMPA-adjacent quality certification protocols govern conductor purity and fire performance in domestic infrastructure tenders. India's CEA mandates underground cabling in designated smart city zones, tightening product compliance for foreign suppliers. Stakeholders must monitor how evolving national building codes reconcile fire safety, recyclability mandates, and total cost of ownership across divergent regulatory timelines.
Market Dynamics
Cross-linked polyethylene insulation technology is displacing legacy PVC formulations across transmission networks, compressing supplier margins while elevating fire-safety and moisture-resistance specifications in utility procurement tenders.
Growth Catalysts
- China's coastal urban densification mandates:Municipal burial requirements in Shanghai, Guangdong, and Zhejiang provinces eliminate overhead line alternatives for new commercial and residential developments.
- EU F-Gas Regulation:Phase-down schedules for synthetic insulation gases accelerate adoption of dry-type and solid-dielectric cable designs in European tunnel and metro infrastructure.
- Grid interconnection projects:Asia-Pacific utilities are routing submarine landing points through underground transitions to minimize coastal visual impact and storm vulnerability.
Market Restraints
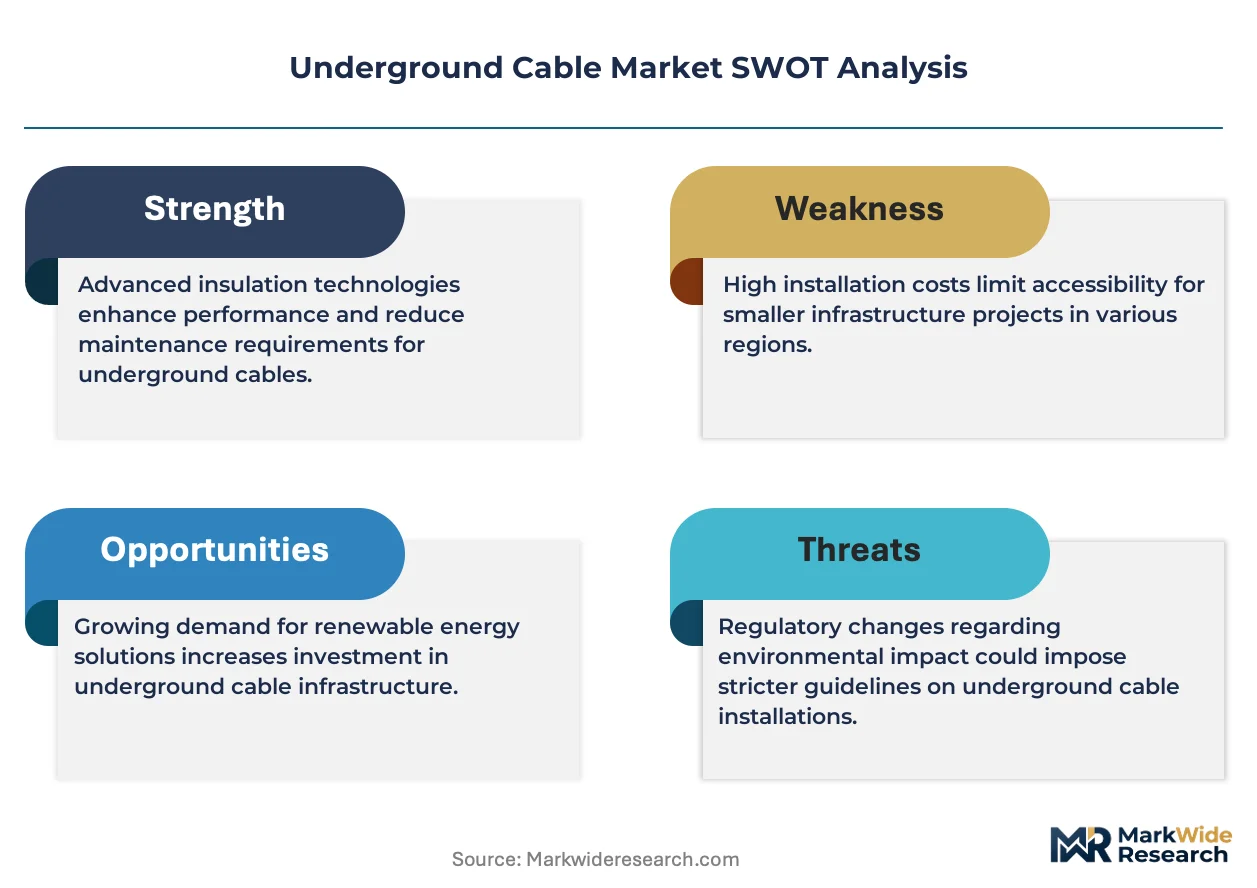
- Copper price volatility:LME copper fluctuations between 2022 and 2024 forced multiple contract renegotiations for high-current urban network suppliers.
- Regional supply concentration:East Asian manufacturers control 70% of continuous vulcanization extrusion capacity, creating single-source risk for European and North American project developers.
- Technical limitation in high-temperature environments:Cross-linked polyethylene thermal ratings cap at 90°C continuous operation, restricting deployment in geothermal-rich zones.
Strategic Opportunities
- India's smart city undergrounding mandates:CEA-designated zones in 100 cities require foreign suppliers to establish local testing partnerships for fire-performance certification.
- 5G backhaul fiber convergence:Power-fiber composite cables enable single-trench deployment for electric utilities expanding into telecommunications infrastructure.
- Japan's METI carbon-neutrality roadmap:Low-carbon aluminum conductor incentives create cost-competitive positioning against copper in rural grid extensions.
Industry Challenges
- Certification timeline compression:China's NMPA-adjacent quality protocols now require 18-month pre-qualification cycles for high-voltage cable imports.
- Legacy system integration friction:Utilities operating mixed PVC-XLPE networks face thermal mismatch failures at splice points during peak load events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Cable Market |
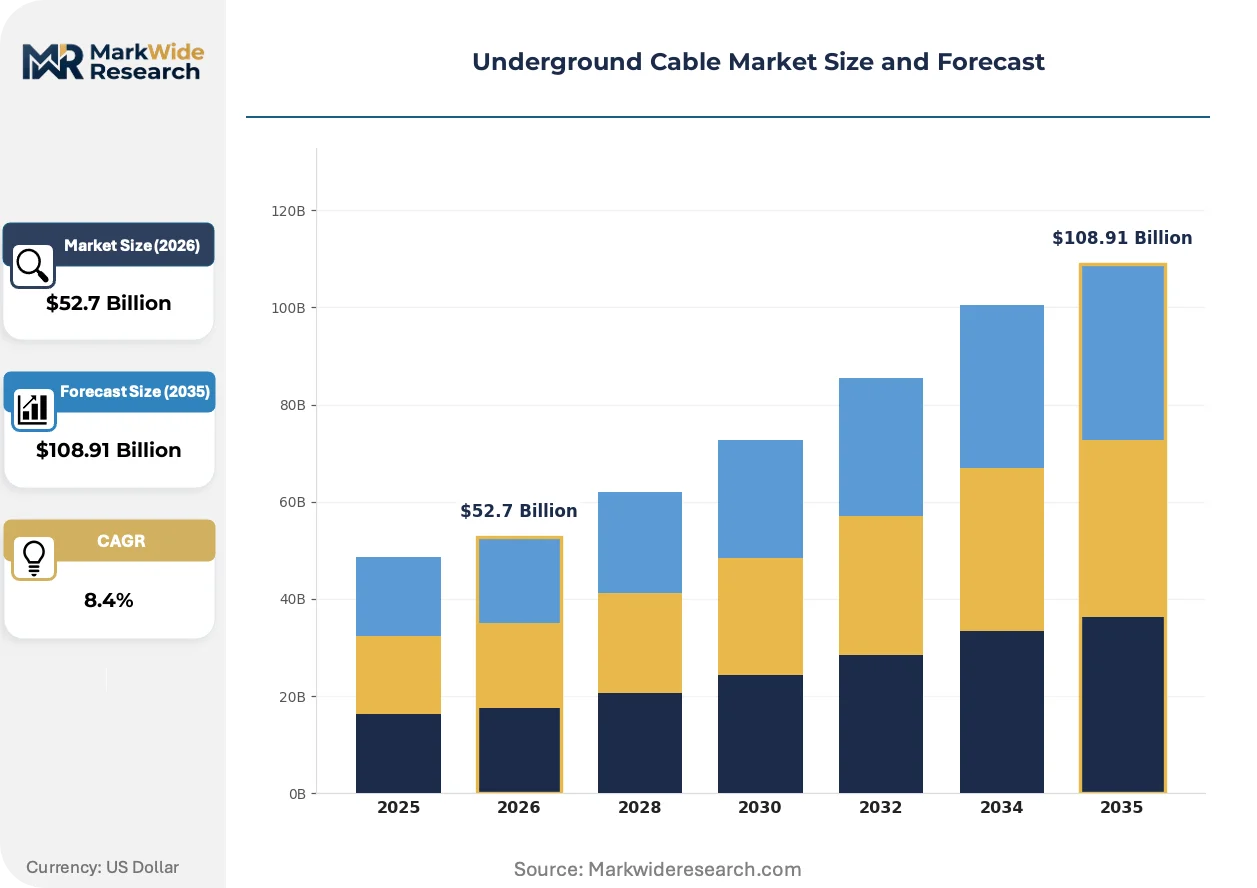
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Power Cables, Communication Cables, Control Cables, Fiber Optic Cables Material: Copper, Aluminum, Polyethylene, PVC End User: Utilities, Telecommunications, Construction, Transportation Installation Method: Trench Installation, Horizontal Directional Drilling, Micro Trenching, Direct Burial |
| Companies Covered | LS Cable & System, NKT, Prysmian Group, ZTT Group, Finolex Cables Limited, Nexans, Southwire, Baosheng Cable, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Cable Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are rewriting insulation specifications, while procurement centralization alters how cable manufacturers secure multi-year utility commitments.
High-performance ethylene propylene rubber compounds are converging with factory-applied semi-conductive layer extrusion for medium-voltage distribution. European rail operators have adopted these configurations for tunnel segments where fire-toxicity limits apply. The technology is converging with automated quality verification systems that reduce factory rejection rates from 4% to under 1%.
REACH substance restrictions on phthalate plasticizers have eliminated certain PVC stabilizer formulations from European tender eligibility. Cable compounders reformulated sheathing materials using bio-based plasticizers and calcium-zinc stabilizer packages. Submarine-to-underground transition projects in the North Sea and Baltic corridors face extended material qualification timelines as a result.
Centralized procurement consortia now aggregate demand across multiple provincial utilities, compressing supplier negotiation leverage. China's State Grid and Southern Power Grid have consolidated annual cable tenders into single-window platforms. Aluminum conductor suppliers in Shandong and Henan provinces adapted by offering volume-tiered pricing indexed to LME futures rather than fixed contracts.
Underground Cable Market Segmentation
Segmentation in underground cable markets reveals how insulation chemistry, conductor metallurgy, and burial technique each create distinct procurement ecosystems with divergent margin structures and technical qualification barriers. Understanding these axes clarifies where supplier capabilities must align with utility specifications versus where cost optimization dominates.
Type:
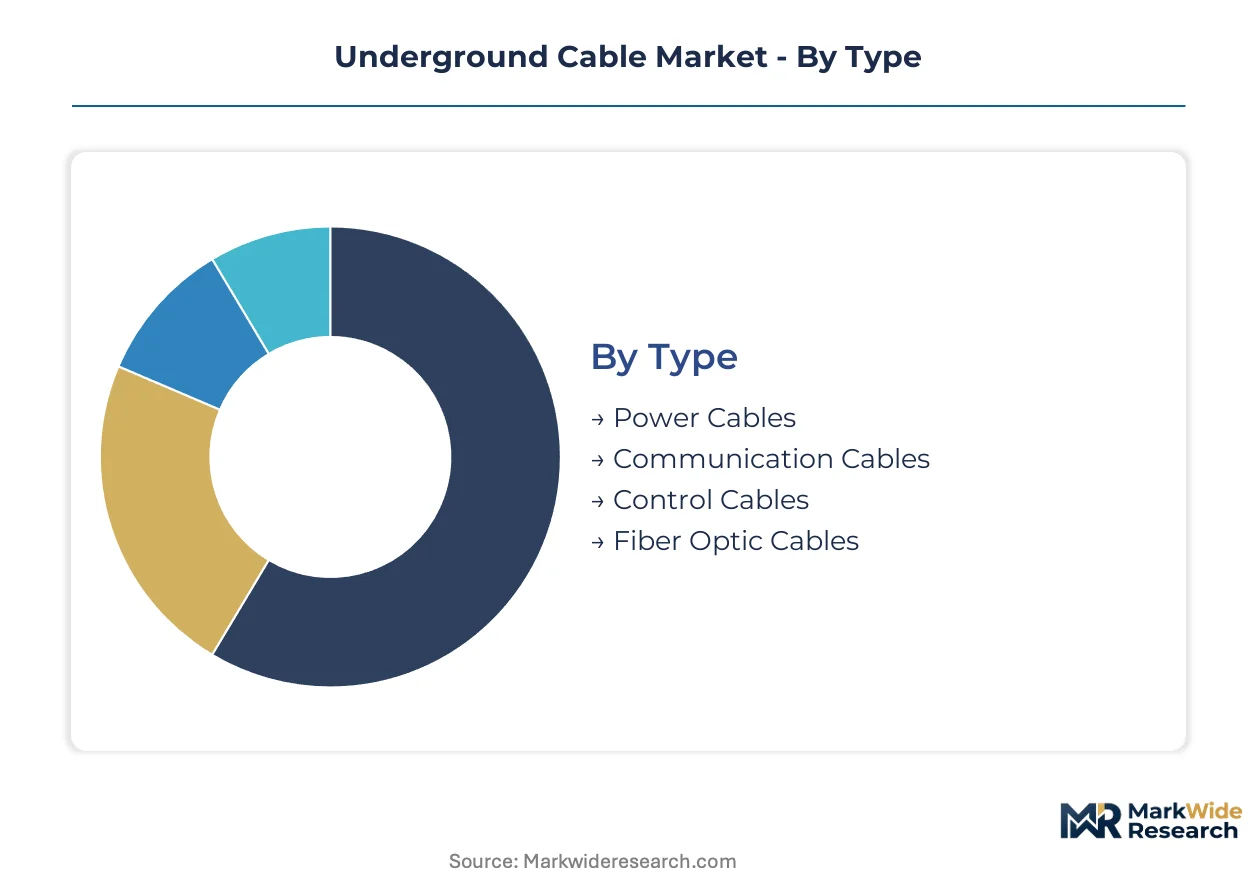
Cross-linked polyethylene insulation ratings and voltage classification separate high-value transmission infrastructure from commodity distribution networks.
- Power Cables:These carry cross-linked polyethylene or ethylene propylene rubber insulation rated between 1 kV and 500 kV for grid transmission and distribution. Demand concentrates in China's coastal provinces where municipal burial mandates eliminate overhead alternatives for new commercial developments.
- Communication Cables:Copper twisted-pair and coaxial constructions serve legacy telecommunications infrastructure with lower insulation specifications. Deployment is accelerating fastest in India's CEA-designated smart city zones where fiber-copper hybrid networks bridge rural connectivity gaps.
- Control Cables:Multi-conductor assemblies with PVC or specialized fire-resistant sheathing interconnect industrial automation and substation equipment.
- Fiber Optic Cables:Single-mode and multi-mode silica fiber with gel-filled loose tube or tight buffer construction enable 5G backhaul and data center interconnects.
Power cables lead on scale; fiber optic cables lead on momentum.
Material:
Conductor and insulation material selection directly determines thermal rating, ampacity, and total cost of ownership across installation lifecycles.
- Copper:Electrolytic tough pitch and oxygen-free high-conductivity grades deliver superior ampacity for high-current urban networks. LME price volatility between 2022 and 2024 forced contract renegotiations across European utility procurement cycles.
- Aluminum:Alloy 1350 and 6201-T81 conductors offer weight and cost advantages for rural transmission spans. Japan's METI carbon-neutrality roadmap incentivizes low-carbon aluminum production for grid extensions.
- Polyethylene:Cross-linked formulations displace legacy insulation through superior moisture resistance and 90°C continuous thermal ratings.
- PVC:Legacy sheathing and insulation material facing REACH substance restrictions on phthalate plasticizers across European tender eligibility.
Copper commands premium positioning; aluminum is climbing the fastest on cost-sensitive rural installations.
End User:
Procurement centralization and technical specification intensity vary sharply across utility, telecom, construction, and transportation verticals.
- Utilities:Grid operators specify continuous vulcanization extrusion quality and 40-year lifecycle warranties for transmission infrastructure. China's State Grid and Southern Power Grid consolidated annual tenders into single-window platforms compressing supplier negotiation leverage.
- Telecommunications:5G network operators prioritize fiber count density and micro-duct compatibility for dense urban backhaul. Power-fiber composite cables enable single-trench deployment converging electric and telecommunications infrastructure.
- Construction:Commercial and residential developers face municipal burial mandates in Shanghai, Guangdong, and Zhejiang provinces.
- Transportation:Metro and rail operators adopt fire-toxicity compliant EPR compounds for tunnel segments where evacuation protocols dictate material performance.
Utilities dominate procurement volume; telecommunications shows steepest expansion trajectory.
Installation Method:
Soil conditions, urban density, and right-of-way constraints dictate equipment intensity and labor specialization for burial technique selection.
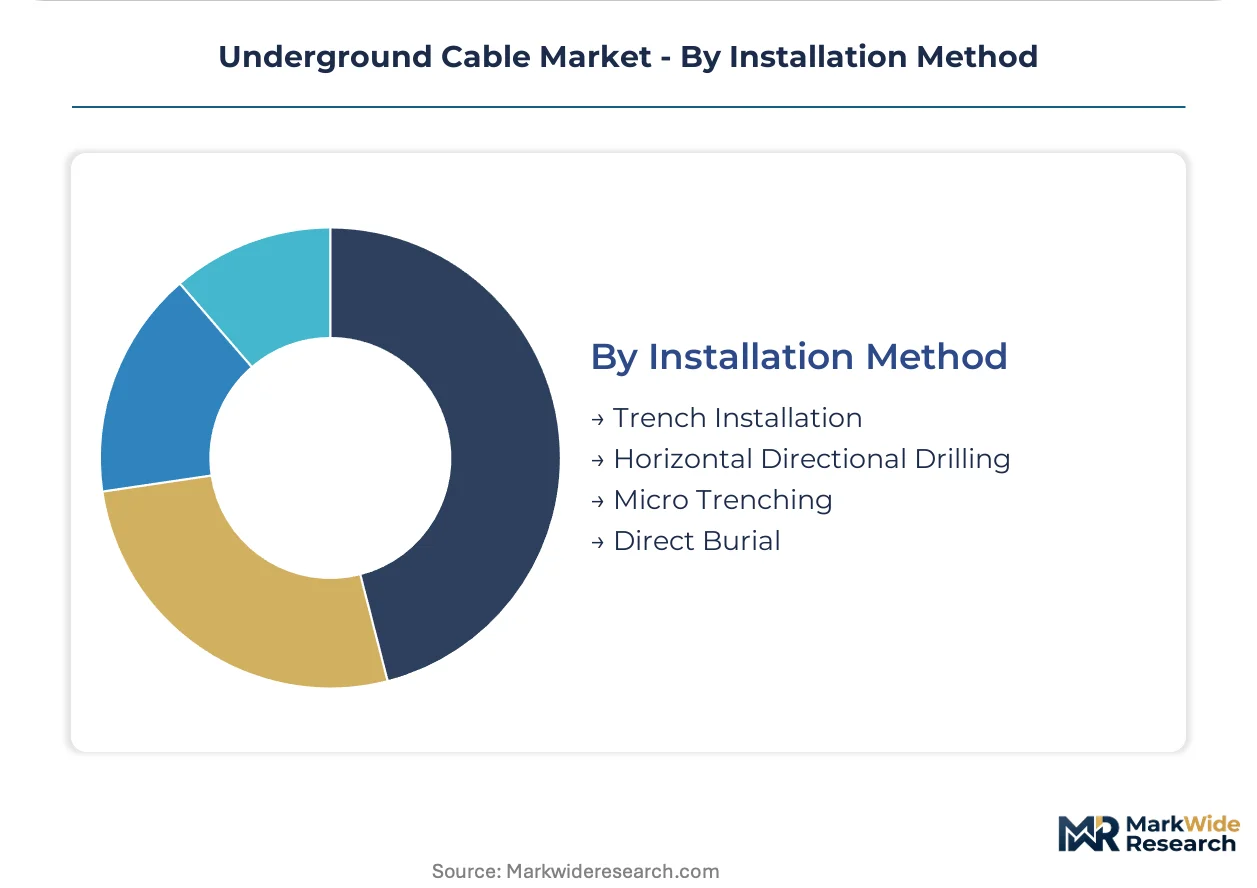
- Trench Installation:Conventional open-cut excavation with sand bedding and warning tape remains standard for greenfield utility corridors. European F-Gas Regulation phase-down schedules accelerate dry-type cable adoption in tunnel segments requiring this method.
- Horizontal Directional Drilling:Steerable trenchless technology navigates beneath existing infrastructure without surface disruption. Asia-Pacific utilities route submarine landing points through underground transitions using HDD to minimize coastal visual impact.
- Micro Trenching:Narrow saw-cut deployment reduces restoration costs for urban fiber-to-the-home networks.
- Direct Burial:Armored or unarmored cable without conduit suits rural distribution with lower traffic loading and simpler maintenance access.
Trench installation retains largest deployment base; horizontal directional drilling is gaining share fastest on coastal interconnection projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal provinces mandate underground burial for new developments, while Germany's F-Gas Regulation drives dry-cable adoption in tunnel infrastructure. These contrasting regulatory pathways illustrate how national policy frameworks reshape deployment patterns and supplier qualification requirements across major markets.
China
Shanghai, Guangdong, and Zhejiang provinces enforce municipal burial mandates that eliminate overhead line alternatives for commercial and residential construction. GB standards and NMPA-adjacent quality certification protocols govern conductor purity and fire performance in domestic infrastructure tenders. State Grid and Southern Power Grid consolidated annual cable tenders into single-window platforms, compressing supplier negotiation leverage across Shandong and Henan manufacturing clusters.
Germany
Rail operators and metro authorities specify fire-toxicity compliant EPR compounds for tunnel segments where evacuation protocols dictate material performance. EU F-Gas Regulation phase-down schedules for synthetic insulation gases accelerate adoption of dry-type and solid-dielectric cable designs in European tunnel and metro infrastructure. Industrial demand concentrates in North Rhine-Westphalia and Bavaria, where utility procurement follows EMA's MDR framework for insulation gas selection and cable sealing standards.
India
CEA mandates underground cabling in designated smart city zones across 100 cities, tightening product compliance for foreign suppliers. The country's national power regulator requires foreign suppliers to establish local testing partnerships for fire-performance certification. Deployment activity clusters in Maharashtra and Gujarat, where municipal corporations integrate burial requirements into urban redevelopment schemes.
Japan
METI's carbon-neutrality roadmap incentivizes low-carbon aluminum conductor production for rural grid extensions. The Ministry of Economy, Trade and Industry channels subsidies toward reduced-emission metallurgy that challenges copper positioning in cost-sensitive installations. Manufacturing and procurement activity centers in the Chubu region around Nagoya, where heavy industrial users coordinate bulk purchasing agreements with regional utilities.
United States
FERC oversight of interstate transmission and state-level public utility commission burial mandates drive procurement in high-density coastal corridors. EPA environmental review requirements for trenching projects in sensitive watersheds extend project timelines and elevate documentation burdens. Major deployment clusters include the Northeast Corridor and California, where coastal storm vulnerability accelerates conversion from overhead to underground infrastructure.
Underground Cable Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated European and East Asian groups anchoring high-voltage transmission while regional fabricators serve distribution and construction verticals. The market exhibits moderate concentration at the transmission tier, where continuous vulcanization extrusion capabilities and 40-year warranty underwriting create qualification barriers. Three archetypes dominate: full-range system suppliers with submarine-to-underground integration capabilities; fire-safety specialists focused on tunnel and metro compounds; and volume-driven aluminum conductor producers serving rural extensions. Competitive moves center on capacity consolidation through asset acquisitions and technology licensing partnerships that transfer XLPE formulation expertise across manufacturing footprints.
Among integrated cable specialists, Prysmian Group, LS Cable & System, and Nexans occupy positions that exemplify divergent strategic anchoring. Prysmian represents the European manufacturing footprint archetype, leveraging continental production bases for long-term utility partnership structures. LS Cable & System sits within the East Asian submarine-to-underground transition specialist tier, with geographic nomenclature indicating Korean industrial origins. Nexans exemplifies the fire-resistant compound specialization vector, with French naming conventions suggesting European regulatory alignment in tunnel and metro applications. These three entities illustrate how supplier positioning maps to distinct procurement ecosystems: transmission infrastructure, coastal interconnection projects, and fire-safety-critical transportation infrastructure respectively.
| Leading Market Players |
|---|
| LS Cable & System |
| NKT |
| Prysmian Group |
| ZTT Group |
| Finolex Cables Limited |
| Nexans |
| Southwire |
| Baosheng Cable |
| Sumitomo Electric Industries |
| Others |
Supply Flow & Price Mechanics
Continuous vulcanization extrusion specialists concentrated in Shandong and Henan provinces anchor labor-cost differentials that widen pricing-tier spreads between premium XLPE transmission cable and economy-grade aluminum distribution product.
Pricing Analysis
Capacity additions in China's eastern manufacturing belt are reshaping price floors for cross-linked polyethylene insulated cable, compressing margins on standard-voltage distribution product while premium high-voltage transmission cable retains pricing power through 40-year warranty underwriting and continuous vulcanization quality certification. Three-tier pricing structure across premium, standard, and economy levels separates utility-grade transmission with full certification from commercial distribution with regional testing approval and unrated construction-grade product. Price differentiation centers on GB standard compliance tier and volume-scale procurement leverage. Cost compression in standard-voltage tiers is intensifying because State Grid's consolidated tender platforms aggregate demand across provincial utilities. Rural grid developers exhibit highest price sensitivity, while metropolitan utilities in Shanghai and Guangdong prioritize fire-performance certification over unit cost.
Supply Chain Analysis
India's CEA-mandated local testing partnerships for foreign suppliers and China's NMPA-adjacent quality protocols are reshaping sourcing geography, forcing European and North American project developers to qualify secondary manufacturing footprints or accept extended pre-qualification timelines. Raw material supply concentrates in China, South Korea, and Germany for continuous vulcanization extrusion equipment, electrolytic copper cathode, and specialized EPR compound formulations. Manufacturing draws from LME-indexed copper cathode, petroleum-derived polyethylene resin, and factory-applied semi-conductive layer materials. Single-source vulnerability runs through East Asian continuous vulcanization capacity controlling seventy percent of global throughput. Distribution runs through utility procurement consortia, EPC contractor specifications, and direct OEM supply agreements for submarine-to-underground transition projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The underground cable market functions as a stable compounder anchored by grid modernization cycles and municipal burial mandates that generate predictable replacement demand across decades-long infrastructure lifecycles.
For Market Incumbents: Deepen backward integration into continuous vulcanization extrusion equipment and specialized EPR compound formulation to defend margin position against emerging Asian manufacturers with cost-advantaged aluminum conductor production. Prysmian Group's European manufacturing footprint exemplifies how geographic diversification of production capacity insulates against regional supply disruption. Prioritize certification investment in India's CEA fire-performance testing partnerships to preempt qualification barriers in 100 designated smart city zones. For New Entrants and Emerging Players: The mid-tier price-point gap between premium copper transmission cable and economy aluminum rural distribution creates white-space positioning for alloy-conductor specialists serving Japan's METI-subsidized carbon-neutral grid extensions. Target India's CEA-designated smart city zones where foreign supplier qualification requirements have slowed incumbent penetration. Pursue power-fiber composite cable convergence as the go-to-market angle, enabling single-trench deployment for electric utilities expanding into 5G backhaul infrastructure. For Investors and Strategic Acquirers: Integrated utility groups with captive EPC capabilities are the most active acquirer in this space, seeking submarine-to-underground transition expertise for coastal interconnection projects. Long-term viability rests on compound annual infrastructure replacement rates and regulatory tightening on fire-toxicity specifications. Acquisition target archetype: regional aluminum conductor fabricators with established local testing partnerships and volume-tiered pricing indexed to LME futures. Monitor China's State Grid tender platform consolidation as the signal indicating pricing power inflection between supplier and buyer.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPR Compound Formulation | Captive supply of fire-toxicity compliant insulation reduces REACH regulatory exposure for European tunnel projects. |
| Local Testing Partnership Establishment | CEA-mandated fire-performance certification in India unlocks access to 100 designated smart city procurement zones. |
| Power-Fiber Composite Cable Development | Single-trench deployment convergence captures 5G backhaul demand from electric utilities expanding infrastructure. |
| Continuous Vulcanization Capacity Expansion | East Asian equipment concentration creates qualification barriers that protect margin in high-voltage transmission tiers. |
| Volume-Tiered LME-Indexed Contracting | Aluminum conductor suppliers in Shandong adapted pricing to State Grid's consolidated tender platform structure. |
Methodological Framework
Coverage spans China, India, Germany, Japan, and the United States, with primary inputs from each market combining structured interviews with utility procurement officers, EPC contractor project developers, cable compound technical directors, and regional regulatory affairs specialists alongside secondary validation from GB standards documentation, EU F-Gas Regulation filings, CEA smart city tender records, METI carbon-neutrality roadmap disclosures, and FERC interstate transmission dockets. Bottom-up and top-down triangulation cross-validates manufacturing capacity data against utility capital expenditure disclosures.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by insulation chemistry, conductor metallurgy, voltage classification, end-use vertical, and burial technique. CAGRs derive from regression against grid interconnection project pipelines, municipal burial mandate adoption curves, and 5G backhaul fiber deployment schedules. Modeled inputs include copper and aluminum price volatility indices, continuous vulcanization capacity utilization rates, and regulatory qualification timeline compressions.
Caveats apply where LME metal price swings, extended NMPA pre-qualification cycles, or geothermal zone thermal rating limitations could materially shift the outlook for high-current urban network deployment. Forecasts embed assumptions about regulatory harmonization timelines and utility procurement centralization trajectories that remain sensitive to national building code revisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Organisers Market
Cables
Cable Flange Market
Cables
Military Fiber Optic Cables Market
Cables
High-Temperature Superconducting Cables Market
Cables
Sensing Cable Market
Cables
Mexico Wires and Cables Market
Cables
Europe Cable Accessories Market
Cables
Polyurethane Cable Market
Cables
Data Center Wire and Cable Market
Cables
US Cables Market
Cables
Ethernet Converters Market
Cables
United States Cable Accessories Market
Cables
Cable Drum Market
Cables
North America Patch Cable Market
Cables
Copper Cable Market
Cables
Power Cable Accessories Market