
 Cable Lugs Market | 2026-2036
Cable Lugs Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Lugs Market Intelligence
A multi-source procurement model for standardized components is hardening into strategic partnerships for application-specific lugs, especially in critical infrastructure. TE Connectivity Ltd. leverages its extensive portfolio to serve diverse end-markets from automotive to data centers. Schneider Electric SE specializes in integrated electrical systems where its lugs ensure component compatibility and system-level performance. Meanwhile, Panduit Corporation differentiates through its focus on high-performance network and industrial electrical infrastructure solutions, offering certified components for demanding environments.
A cable lug is a mechanical connector designed to terminate the end of an electrical cable, enabling its secure connection to a terminal block, busbar, or other equipment. Manufactured typically from high-conductivity electrolytic copper or aluminum, these components are crimped or soldered onto the cable to ensure a reliable electrical and mechanical bond. Copper lugs continue to dominate the market due to superior conductivity and corrosion resistance. Demand from renewable energy systems represents the fastest-growing application, outpacing mature industrial equipment sectors.
Product design and market access are governed by stringent international and regional standards. Compliance with International Electrotechnical Commission (IEC) 61238-1 is critical for performance validation. Separately, UL listing in the United States and CE marking under the Low Voltage Directive in Europe are mandatory for market entry. The EU's RoHS directive further restricts the use of hazardous substances in manufacturing. Stakeholders must now navigate the trade-offs between high-conductivity copper and lighter, cost-effective aluminum, especially in weight-sensitive applications.
Market Dynamics
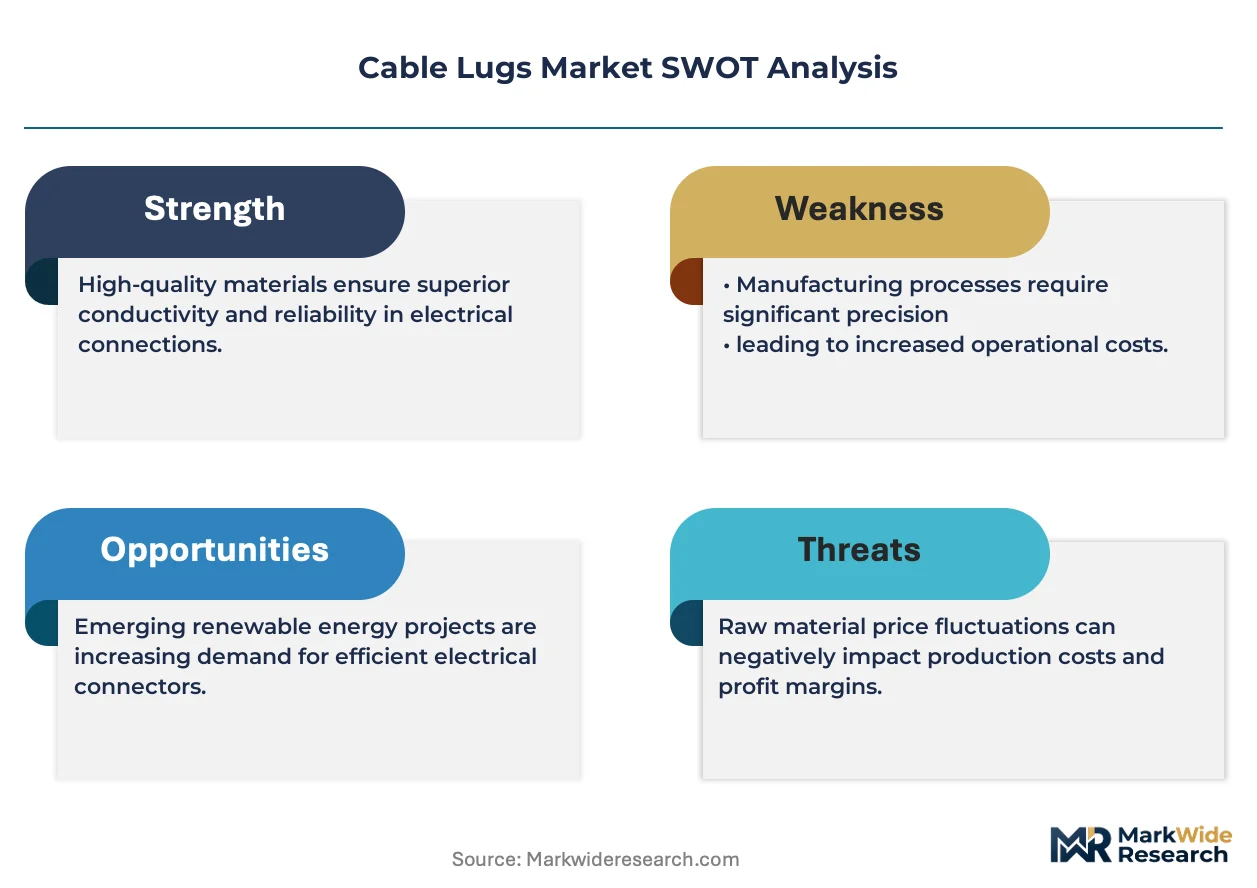
The market's central tension lies in material selection, balancing copper's superior conductivity against aluminum's cost and weight advantages. This trade-off is intensifying with demand from renewable energy and electric vehicle sectors, both requiring optimized performance and reliability in electrical connections.
Growth Catalysts
- Grid Modernization Mandates:Policies like the EU Green Deal compel upgrades to electrical grids, requiring vast quantities of high-reliability lugs for new substations and transmission lines.
- Electric Vehicle Infrastructure:The global expansion of EV charging networks and battery manufacturing creates dedicated demand for high-current, vibration-resistant lugs.
- Renewable Energy Deployment:Solar and wind farm construction, particularly in industrial clusters across China and Germany, directly consumes specialized lugs for panel and turbine connections.
Market Restraints
- Commodity Price Volatility:The costs of raw materials, especially high-conductivity copper and aluminum, are subject to global market fluctuations, directly impacting manufacturer margins and pricing stability.
- Material Substitution Risk:In weight-sensitive applications like automotive, the push for lighter components creates a substitution threat where aluminum lugs may displace heavier copper ones despite performance trade-offs.
- Complex Compliance Landscape:Adherence to a fragmented set of standards, including IEC for performance, UL for US access, and CE for Europe, adds significant testing costs and time-to-market delays.
Strategic Opportunities
- Energy Storage Systems:The growth of battery energy storage systems (BESS) alongside renewable projects opens a new application frontier for heavy-duty lugs designed for high-cycle battery bank connections.
- Smart Lug Development:Integrating sensors into lugs for temperature and vibration monitoring presents an opportunity to create value-added components for predictive maintenance in critical infrastructure.
- Emerging Market Electrification:Grid expansion projects in developing economies across Southeast Asia and Africa represent underpenetrated markets for standardized and application-specific cable lugs.
Industry Challenges
- Crimping Skill Scarcity:Ensuring reliable, low-resistance connections requires properly trained technicians, and a scarcity of these skills for high-voltage applications can lead to installation errors and system failures.
- Certification Bottlenecks:The lengthy process to achieve IEC 61238-1 and UL 486A-486B certifications for new lug designs can act as a bottleneck, slowing innovation and market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Lugs Market |
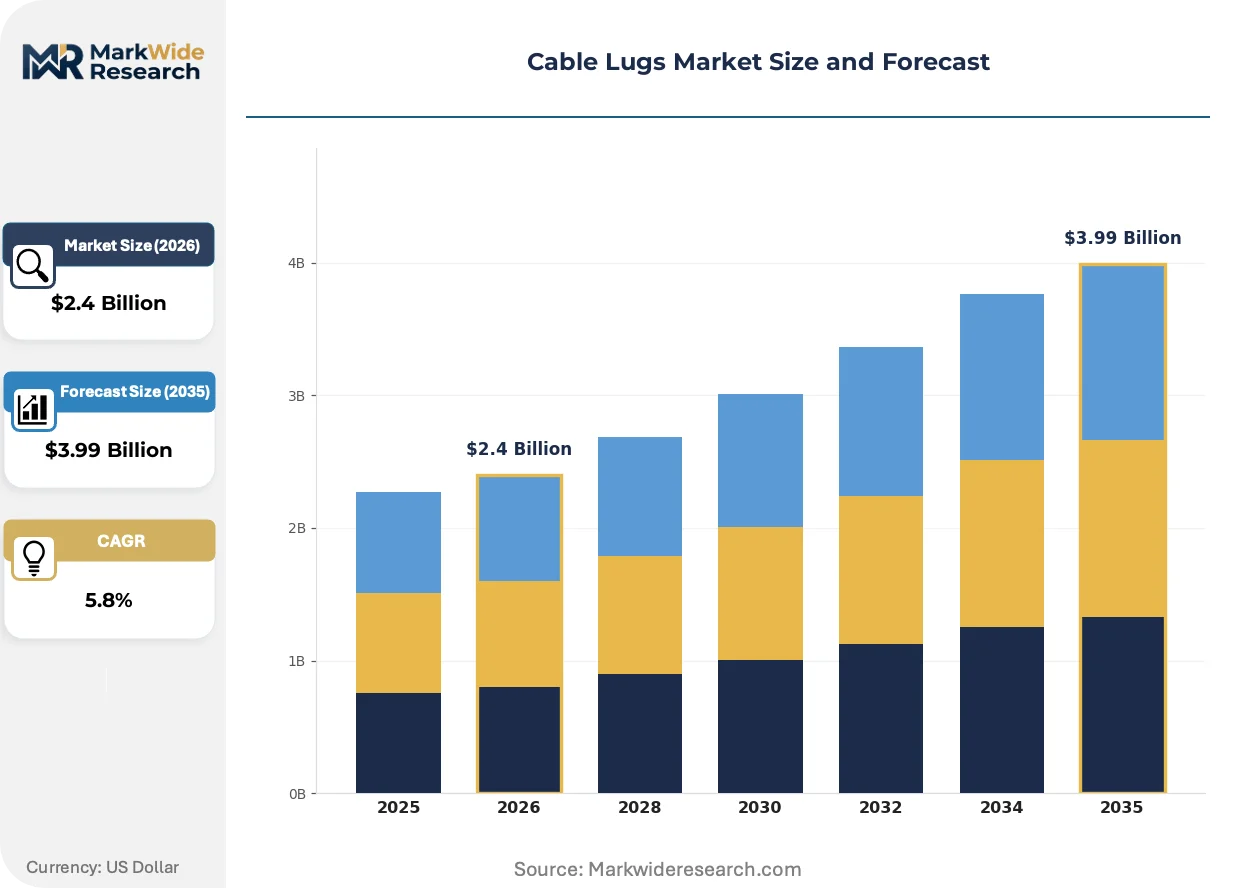
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Lugs, Aluminum Lugs, Insulated Lugs, Non-Insulated Lugs Application: Electrical Wiring, Industrial Equipment, Automotive Applications, Renewable Energy Systems End User: Manufacturers, Contractors, Electrical Distributors, Installers Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Eaton Corporation, Panduit Corporation, 3M Company, Hubbell Incorporated, TE Connectivity Ltd., ABB Ltd., Weidmüller Interface GmbH & Co. KG, Legrand SA, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Lugs Market Strategic Shifts & Innovations
Product development is pivoting from standardized components toward engineered solutions for extreme operating conditions. This shift is driven by the dual pressures of widespread electrification and the need for absolute reliability in next-generation power systems and industrial machinery.
Bimetallic lugs, which fuse an aluminum barrel with a copper palm, are a key innovation. Utilities and renewable energy developers adopt these components to join aluminum power cables to copper equipment terminals. This technology is electrifying the critical interface between dissimilar metals, preventing galvanic corrosion and ensuring long-term grid stability without costly component failures.
The EU's Restriction of Hazardous Substances (RoHS) directive directly influences material composition in the cable lug market. The regulation forces manufacturers to eliminate lead, cadmium, and other specified materials from their plating and soldering processes. This primarily impacts suppliers to the European automotive and electronics sectors, who must invest in compliant manufacturing techniques to maintain market access.
A behavioral change is underway as original equipment manufacturers move from sourcing individual components to procuring complete, factory-terminated cable assemblies. This model disrupts the traditional component distribution channel by favoring suppliers with system integration capabilities. The shift is most pronounced in the data center and industrial robotics industries, where certified, plug-and-play solutions accelerate project timelines.
Cable Lugs Market Segmentation
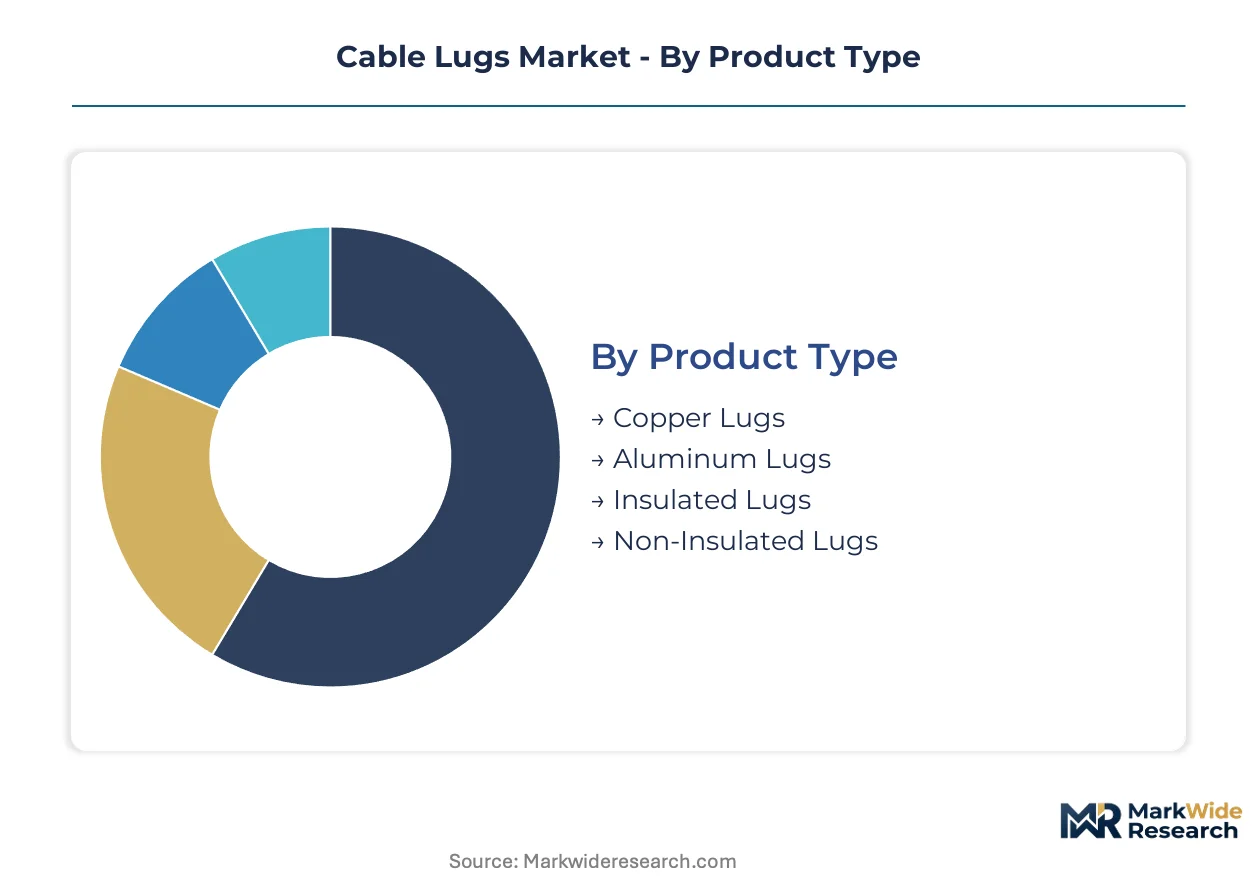
The cable lugs market segments across various technical specifications, application environments, and end-user requirements. Understanding these divisions helps stakeholders tailor product development and market strategies for optimal penetration. Each segment presents distinct demand drivers and compliance challenges.
Product Type:
The cable lugs market differentiates product offerings primarily through the core material and insulation specifications, directly impacting performance and application suitability.
- Copper Lugs:These connectors are manufactured from high-conductivity electrolytic copper, offering superior electrical performance and corrosion resistance. Demand remains concentrated in traditional power distribution and industrial machinery due to their reliability.
- Aluminum Lugs:Constructed from high-purity aluminum, these lugs provide a cost-effective and lighter alternative to copper, particularly in weight-sensitive applications. The electric vehicle sector and large-scale renewable energy projects increasingly utilize aluminum for cable terminations.
- Insulated Lugs:These lugs feature a pre-attached insulation sleeve, typically made from PVC or nylon, providing electrical isolation and strain relief. They are widely used in low-voltage electrical wiring and consumer electronics for safety.
- Non-Insulated Lugs:Designed without an integrated insulation layer, these bare metal lugs require external insulation after crimping. Heavy industrial applications and high-voltage power systems commonly employ non-insulated lugs.
Copper Lugs lead on scale due to established use; Aluminum Lugs lead on momentum driven by weight-sensitive applications.
Application:
Demand for cable lugs varies significantly across diverse application sectors, each presenting unique performance and regulatory requirements.
- Renewable Energy Systems:This segment includes solar farms, wind turbines, and battery energy storage systems, requiring specialized lugs for reliable power transmission in harsh environments. Deployment in Germany and China drives significant demand for these components.
- Industrial Equipment:Cable lugs are essential for connecting power and control circuits within factory automation, heavy machinery, and processing plants. This mature sector demands robust, vibration-resistant connectors for continuous operation.
- Electrical Wiring:This broad category encompasses residential, commercial, and institutional building wiring, utilizing standard lugs for secure connections in distribution panels and junction boxes. Compliance with local electrical codes is paramount.
- Automotive Applications:High-current, vibration-resistant lugs are critical for electric vehicle battery connections, charging infrastructure, and vehicle power distribution systems. This sector demands compact, lightweight solutions.
Renewable Energy Systems exhibit the steepest expansion trajectory, while Industrial Equipment maintains consistent, foundational demand.
End User:
The procurement and deployment of cable lugs are shaped by the distinct operational needs and purchasing patterns of various end-user groups.
- Manufacturers:Original equipment manufacturers (OEMs) integrate cable lugs directly into their products, including industrial machinery, electrical panels, and automotive components. They prioritize bulk purchasing and consistent quality.
- Contractors:Electrical contractors purchase lugs for installation in construction projects, grid modernization initiatives, and renewable energy site development. Their demand is project-based and often requires a wide variety of sizes.
- Electrical Distributors:These entities serve as intermediaries, stocking and supplying a broad range of cable lugs to smaller contractors, maintenance professionals, and retail customers. They focus on inventory management and logistics.
- Installers:Individual electricians and installation technicians purchase lugs for repair, maintenance, and small-scale projects. They often require readily available, standardized components.
Manufacturers drive large-volume, standardized procurement, whereas Contractors prioritize application-specific solutions and installation efficiency.
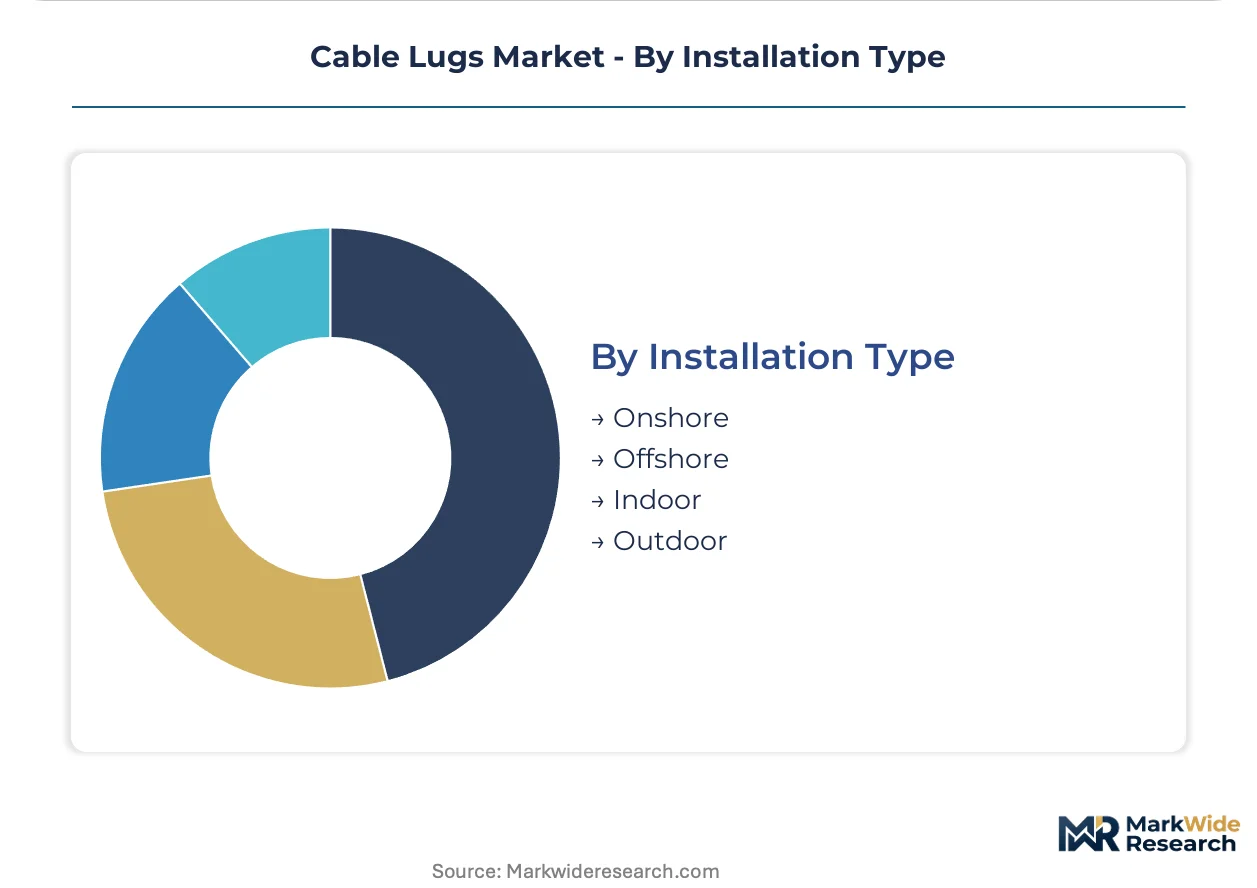
Installation Type:
Installation environments dictate specific lug characteristics, influencing material choices and sealing requirements for long-term reliability.
- Onshore:This category covers installations in land-based electrical infrastructure, industrial facilities, and commercial buildings. Standardized lugs are widely used, but grid modernization mandates require high-reliability components.
- Offshore:Marine and offshore wind farm installations demand corrosion-resistant, robust lugs capable of withstanding saltwater exposure and extreme weather. Specialized sealing and material treatments are critical for these environments.
- Indoor:Controlled indoor environments, such as data centers and industrial control panels, typically require standard insulated or non-insulated lugs. Temperature stability is a key consideration for performance.
- Outdoor:Outdoor installations, including power transmission lines and solar panel arrays, necessitate lugs with enhanced weather resistance, UV stability, and broad temperature tolerance. Durable materials are essential.
Onshore installations account for the largest volume, with Offshore projects demanding specialized, high-durability solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial centers in Germany and China drive significant demand for cable lugs, fueled by extensive renewable energy deployments and grid modernization initiatives. These components are critical for reliable electrical connections in new substations, transmission lines, and industrial facilities. Global policies and localized infrastructure projects shape the market's geographic distribution.
Germany
German industrial demand for cable lugs stems from factory automation and electric vehicle production. The EU Green Deal mandates extensive grid upgrades, requiring high-reliability connectors across the country. Bavaria, a hub for automotive and machinery manufacturing, sees substantial consumption of specialized lugs for its advanced industrial base.
China
China's vast renewable energy projects and EV charging network expansion create substantial demand for cable lugs. The nation's dual carbon goals accelerate investment in green infrastructure, necessitating robust electrical components. The Yangtze River Delta, a major manufacturing region, consistently consumes large volumes of lugs for diverse industrial applications.
United States
United States infrastructure modernization efforts and electric vehicle expansion drive cable lug procurement. The Inflation Reduction Act (IRA) supports domestic renewable energy projects, increasing demand for high-current lugs. Texas, with its significant energy sector and growing EV manufacturing, represents a key consumption area for these essential connectors.
India
India's ambitious grid expansion projects and renewable energy targets contribute to rising cable lug demand. The country's Production Linked Incentive (PLI) scheme encourages domestic manufacturing, including electrical components. Maharashtra, a prominent industrial state, experiences consistent consumption for its diverse manufacturing and infrastructure development.
Japan
Japanese manufacturers require cable lugs for advanced industrial equipment and automotive production. Policies from the Ministry of Economy, Trade and Industry (METI) promote energy efficiency and smart grid development, influencing lug specifications. The Kanto region, encompassing Tokyo, remains a central demand area for high-performance electrical connections.
Cable Lugs Market Key Industry Players
Global majors compete with regional champions across product innovation and market access within the cable lugs industry. The market structure exhibits a blend of highly diversified electrical component suppliers and specialized manufacturers catering to niche applications. Strategic archetypes include broad portfolio providers, performance-focused specialists, and value-oriented component fabricators. Companies frequently engage in strategic partnerships and portfolio diversification to expand their market footprint and address evolving customer needs.
Specialists in integrated electrical systems, such as Schneider Electric SE, exemplify providers focused on system-level performance and component compatibility across various applications. TE Connectivity Ltd. represents a major player offering an extensive portfolio that serves diverse end-markets, from automotive to data centers, emphasizing comprehensive solutions. Meanwhile, Panduit Corporation occupies a distinct position by concentrating on high-performance network and industrial electrical infrastructure solutions, offering certified components for demanding environments. These companies anchor different segments of the market through their distinct product strategies and market specializations.
| Leading Market Players |
|---|
| Eaton Corporation |
| Panduit Corporation |
| 3M Company |
| Hubbell Incorporated |
| TE Connectivity Ltd. |
| ABB Ltd. |
| Weidmüller Interface GmbH & Co. KG |
| Legrand SA |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
High-conductivity copper costs, as a primary raw material, ripple from global mining operations through manufacturing, ultimately influencing the per-unit transactional pricing for cable lugs across diverse end-markets. This cost sensitivity shapes procurement strategies and material selection throughout the value chain.
Pricing Analysis
Raw material input costs, particularly for copper and aluminum, directly influence the final pricing of cable lugs, creating pressure across the value chain. The dominant pricing model is contract-based long-term offtake for large manufacturers, while project-based transactional pricing serves contractors. Price differentiation stems from certification level, such as IEC or UL listings, and the volume scale of procurement. Pricing softness is evident due to material substitution risk, with contractors exhibiting higher price sensitivity than OEMs.
Supply Chain Analysis
Logistics and freight costs significantly impact the delivered price of cable lugs, especially for specialized components sourced globally. Geographic supply concentrates in China, Germany, and the United States, drawing from global raw material inputs like electrolytic copper and high-purity aluminum. Commodity price volatility represents a structural risk directly affecting material acquisition costs. Distribution runs through a network of electrical distributors, alongside direct sales channels to large OEMs and project-based contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable lugs market is evolving into a late-cycle quality story, driven by the demand for premium specifications in critical infrastructure and advanced electrification projects.
For Market Incumbents: To counter material substitution risk from lighter alternatives, incumbent manufacturers must strategically invest in bimetallic lug research and development. Reinforcing certification leadership, particularly for IEC 61238-1 and UL 486A-486B, secures market access and validates performance claims. Deepening strategic partnerships with renewable energy developers ensures long-term demand for high-reliability, application-specific components. Expanding capacity in key industrial clusters can also optimize supply chain resilience.
For New Entrants and Emerging Players: Capture white-space opportunities by focusing on smart lug development for predictive maintenance applications in critical infrastructure. The most penetrable segment lies in emerging market electrification projects across Southeast Asia and Africa, which require standardized yet certified components. A cost-effective go-to-market angle involves offering high-purity aluminum solutions with essential regional certifications. This approach allows new players to differentiate beyond traditional copper offerings.
For Investors and Strategic Acquirers: Roll-up economics work for specialized lug manufacturers because structural demand for high-reliability components is consolidating. Long-term viability rests on sustained grid modernization and the expansion of electric vehicle charging infrastructure over the next decade. Acquisition targets should include mid-sized firms with proprietary bimetallic technology or extensive certification portfolios. The signal to watch is the increasing integration of sensor-enabled lugs into critical power systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bimetallic Lug R&D | This initiative addresses galvanic corrosion in critical renewable energy and grid connections. |
| Expand Certification Portfolio (IEC, UL, CE) | Broadening compliance ensures market access and validates product reliability for global customers. |
| Develop Smart Lug Technology | Integrating sensors provides predictive maintenance capabilities for high-value industrial assets. |
| Target Emerging Market Electrification | Penetrating under-served regions unlocks new volume growth for standardized components. |
| Strategic Partnerships with Renewable Energy EPCs | Collaborations secure long-term contracts for specialized lugs in large-scale power projects. |
Research Approach
Multiple input streams — primary interviews, secondary research, and market intelligence — were reconciled to construct a comprehensive understanding of the cable lugs market. Discussions were held with electrical engineers, procurement managers, renewable energy project developers, and automotive component buyers. Secondary validation drew from industry association reports, government energy statistics, regulatory filings, and corporate financial disclosures. Both bottom-up and top-down triangulation methods ensured data accuracy.
Cross-referencing historical market data with expert panel input formed the basis of the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end user, installation type, and regional deployment. Compound annual growth rates were derived by extrapolating historical trends and incorporating insights from future capacity additions. Industry-specific forecast inputs included renewable energy capacity additions and electric vehicle production forecasts.
Commodity price volatility, regulatory shifts, and technological advancements are the dominant revision risks to the forecast. Forecasts reflect assumptions documented at the time of publication. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Data Center Wire and Cable Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Cable Flange Market
Cables
Ethernet Converters Market
Cables
HVDC Cables Market
Cables
Submarine Cables Market
Cables
North America HVAC Cables Market
Cables
EPR Cable Market
Cables
Radio Frequency Cables Market
Cables
Fire Resistance Cable Market
Cables
Sensing Cable Market
Cables
Europe Cable Management Market
Cables
Europe Wire and Cable Market
Cables
Electric Submersible Cable Sales Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Insulated Wire and Cable Market