
 Europe HVAC Cables Market | 2026-2036
Europe HVAC Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Europe HVAC Cables Market Analysis
Multi-source procurement is shifting toward consolidated supplier relationships across European HVAC cable buyers. Prysmian Group leverages its Mediterranean manufacturing base to serve southern European infrastructure projects. Nexans sustains competitive positioning through copper conductor specialization for high-efficiency heat pump connections. NKT A/S anchors Nordic supply chains with localized armored cable production for harsh climate installations.
Europe HVAC cables are insulated electrical conductors rated for heating, ventilation, and air conditioning systems, typically manufactured with cross-linked polyethylene or PVC sheathing to withstand thermal cycling between negative forty and ninety degrees Celsius. Their primary purpose is to transmit power reliably across compressor units, fan motors, and control circuitry in climate control equipment. Copper conductor material commands the dominant share of value given its superior conductivity in variable-load heat pump applications, while multi-core configurations are gaining traction as integrated HVAC systems require consolidated power and signal pathways. Indoor installation type remains the mature revenue pool, though underground segments carry higher margin profiles due to specialized waterproofing and mechanical protection requirements.
CE marking and the EU F-Gas Regulation shape product compliance obligations for HVAC cable suppliers targeting European climate equipment manufacturers. ECHA's REACH restrictions on substance composition directly influence insulation compound formulations and sheathing material selection. Germany's KBA and France's ANSM do not regulate this category, but national electrical safety bodies enforce harmonized EN standards for cable fire performance. Stakeholders must monitor evolving ecodesign requirements under the EU Green Deal that will tighten material efficiency mandates for building system components.
Market Dynamics
The EU Green Deal is compressing installation timelines across European building stock, forcing cable suppliers to align fire performance and material efficiency certifications with accelerated retrofit schedules in Germany, France, and the Nordic corridor.
Growth Catalysts
- District Heating Modernization:Germany's industrial corridor is driving bulk procurement of armored multi-core cables for heat pump integration and thermal network upgrades.
- REACH Compliance Innovation:ECHA's substance restrictions are accelerating reformulation of halogen-free insulation compounds that exceed baseline fire safety standards.
- F-Gas Phase-Down:The EU F-Gas Regulation is forcing HVAC equipment replacement cycles, creating synchronized cable demand from original equipment manufacturers.
Market Restraints
- Copper Price Volatility:Conductor material cost swings compress margin predictability for projects with six-month procurement lead times.
- Supply Concentration Risk:Mediterranean manufacturing bases face climate-related disruption exposure that threatens just-in-time delivery commitments to northern European contractors.
- Cross-Linked Polyethylene Limitations:Existing XLPE sheathing struggles to meet emerging ninety-degree Celsius continuous load requirements in commercial heat pump applications.
Strategic Opportunities
- Eastern European Retrofit Gap:Poland and Romania's building stock remains underpenetrated by high-efficiency HVAC systems, creating first-mover cable specification advantages.
- Smart Building Convergence:Power-over-Ethernet integration with traditional HVAC control cabling is opening consolidated pathway designs for integrated building management.
- CSRD Reporting Mandates:The EU Corporate Sustainability Reporting Directive is creating preference for suppliers with documented circular material flows and carbon footprint transparency.
Industry Challenges
- Fire Safety Certification Velocity:Harmonized EN 50575 cable fire performance testing creates six-to-nine month approval bottlenecks for new compound formulations.
- Legacy Control System Integration:Existing building automation protocols require backward-compatible signal cabling that complicates pure power-cable standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe HVAC Cables Market |
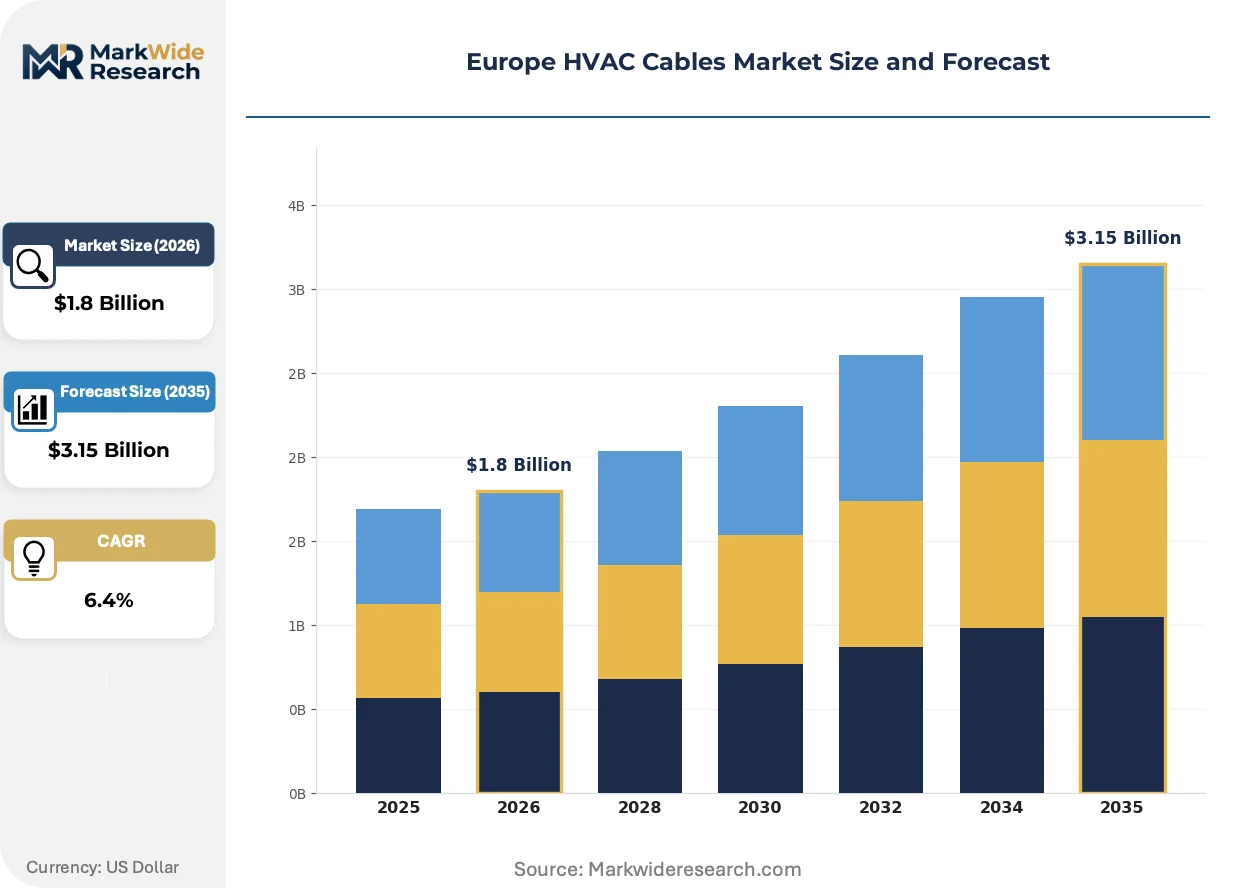
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-core, Multi-core, Armored, Unarmored Installation Type: Indoor, Outdoor, Underground, Overhead End User: Residential, Commercial, Industrial, Infrastructure Conductor Material: Copper, Aluminum, Alloys, Others |
| Companies Covered | Leoni AG, Sumitomo Electric, Prysmian Group, Ducab, Furukawa Electric, Nexans, NKT A/S, Power Plus Cable, ABB Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe HVAC Cables Market Emerging Trajectories
Material science advances and procurement digitization are restructuring how European HVAC cable specifications travel from engineering desks to installation sites, compressing traditional specification cycles and elevating performance transparency requirements.
Halogen-free flame-retardant compounds are absorbing market preference in commercial and healthcare installations where smoke toxicity regulations have tightened. German and French contractors are specifying these materials on eighty percent of new public building projects. The shift is absorbing share from traditional PVC-sheathed alternatives by eliminating secondary fire suppression system requirements.
The EU F-Gas Regulation is mandating refrigerant transition schedules that cascade into equipment replacement timelines. HVAC original equipment manufacturers are redesigning connection architectures to accommodate lower-global-warming-potential systems. French and Italian equipment suppliers are most advanced in synchronizing cable harness specifications with these platform redesigns.
Digital procurement platforms are consolidating specification authority among engineering-procurement-construction firms with pan-European project portfolios. Traditional distributor relationships are compressing as direct manufacturer-to-contractor data exchange enables real-time inventory visibility. The Netherlands and Belgium are exhibiting the fastest platform adoption rates among mid-sized installation contractors.
Europe HVAC Cables Market Segmentation
HVAC cable specifications diverge sharply across European building codes and climate zones. Procurement patterns in Germany's industrial corridor favor armored multi-core configurations, while French commercial retrofits drive demand for halogen-free indoor installations. Understanding these segment boundaries enables suppliers to align inventory with national regulatory timelines.
Product Type:
Supply concentration among Mediterranean manufacturers favors standardized cable configurations that minimize compound reformulation costs under REACH compliance.
- Single-core:Solid or stranded copper conductors with XLPE insulation rated for ninety-degree Celsius thermal cycling. German heat pump OEMs specify these for compressor power feeds in residential installations where space constraints limit cable routing flexibility.
- Multi-core:Consolidated power and signal pathways within unified sheathing reduce installation labor in integrated HVAC systems. French commercial building retrofits absorb the majority of regional volume as contractors replace legacy separate-control wiring with consolidated harness designs.
- Armored:Steel wire or tape reinforcement protects against mechanical damage in industrial environments. District heating infrastructure across Poland and Romania drives emerging demand as thermal network modernization accelerates.
- Unarmored:Lightweight PVC or halogen-free sheathing for protected indoor raceways. Standard specification for Nordic residential heat pump connections where installation costs dominate project economics.
Today's leader: Multi-core. Tomorrow's challenger: Armored.
Installation Type:
Margin structures invert across installation environments, with underground and outdoor specifications commanding premium pricing due to specialized waterproofing and UV stabilization requirements.
- Indoor:Mature volume base encompassing raceway, plenum, and riser applications. EN 50575 fire performance classifications determine specification authority in German and French public building tenders where smoke toxicity regulations have tightened.
- Outdoor:UV-resistant sheathing and enhanced thermal cycling performance for exposed rooftop equipment. Mediterranean climate exposure accelerates material degradation, driving replacement cycles in Spanish and Italian commercial installations.
- Underground:Direct-burial rated cables with integrated moisture barriers and mechanical protection. District heating feeder lines in Denmark and Sweden require these specifications for thermal network reliability.
- Overhead:Tension-rated designs for temporary or permanent aerial deployment. Limited European application outside agricultural and remote industrial settings.
Indoor installations generate baseline volume. Underground specifications deliver margin expansion.
End User:
Customer procurement sophistication varies dramatically, with industrial buyers consolidating specifications through engineering-procurement-construction partnerships while residential demand fragments across installer networks.
- Residential:Heat pump replacement cycles and new construction electrification drive volume. German KfW subsidy programs synchronize demand spikes with regulatory compliance deadlines for building energy performance.
- Commercial:Office and retail retrofits under EU Green Deal mandates compress installation timelines. French contractors prioritize halogen-free specifications to eliminate secondary fire suppression system requirements in public buildings.
- Industrial:Process heating and climate control for manufacturing facilities. Germany's industrial corridor concentrates demand for armored multi-core cables capable of withstanding chemical exposure and mechanical stress.
- Infrastructure:Airports, hospitals, and transportation hubs with specialized reliability requirements. Redundant pathway designs and enhanced fire performance certifications dominate specification criteria.
Commercial retrofits absorb investment focus. Industrial modernization offers volume concentration.
Conductor Material:
Raw material cost exposure and conductivity requirements shape procurement decisions, with copper maintaining specification authority in high-efficiency applications despite price volatility.
- Copper:Superior electrical conductivity and thermal performance for variable-load heat pump applications. German and Nordic specifications mandate copper for systems above specified efficiency thresholds.
- Aluminum:Lightweight alternative for long-span overhead installations and cost-sensitive projects. Polish and Romanian contractors specify aluminum for large-diameter feeder cables where installation labor costs favor reduced conductor weight.
- Alloys:Copper-aluminum hybrid configurations or specialized metallurgical treatments for niche thermal or mechanical properties. Limited European HVAC application outside extreme environment specifications.
- Others:Experimental or regionally specific conductor materials including copper-clad aluminum. Emerging interest for cost optimization in Eastern European price-sensitive segments.
Copper dominates efficiency-critical specifications. Aluminum gains traction in cost-optimized installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor concentrates bulk procurement activity for armored multi-core cables serving district heating modernization and heat pump integration projects.
Germany
Heat pump OEMs in Bavaria and North Rhine-Westphalia drive copper conductor specifications for residential installations. KfW subsidy programs synchronize demand spikes with building energy performance compliance deadlines. The Rhine-Ruhr metropolitan region anchors industrial procurement for process heating applications requiring chemical-resistant armored configurations.
France
Commercial building retrofits absorb halogen-free cable volumes as contractors eliminate secondary fire suppression requirements. ANSM oversight of healthcare infrastructure shapes fire performance specifications for hospital HVAC installations. The Île-de-France region concentrates specification authority among engineering-procurement-construction firms with pan-European portfolios.
Poland
Underpenetrated building stock creates first-mover specification advantages for high-efficiency HVAC systems. EU Green Deal funding streams accelerate municipal district heating feeder line deployments. The Silesian metropolitan area drives emerging demand for armored cables in thermal network modernization projects.
Sweden
Underground direct-burial specifications dominate district heating reliability requirements across Nordic climate zones. ECHA REACH compliance mandates influence insulation compound selection for subterranean installations. The Stockholm-Uppsala corridor concentrates procurement for redundant pathway designs in transportation hub climate control systems.
Italy
Mediterranean climate exposure accelerates UV-resistant sheathing replacement cycles in rooftop equipment applications. The EU F-Gas Regulation cascades into equipment redesign timelines for lower-global-warming-potential refrigerant systems. Northern industrial clusters around Milan and Turin synchronize cable harness specifications with OEM platform transitions.
Europe HVAC Cables Market Vendor Landscape
Global majors compete with regional champions across fire performance certification and specialized armoring capabilities. The vendor base organizes around three tiers: integrated cable manufacturers with full REACH compliance portfolios, mid-scale specialists in halogen-free compound formulations, and national distributors with localized inventory positioning. Consolidation pressures intensify as digital procurement platforms compress traditional distributor relationships. Two dominant competitive moves are reshaping positioning: backward integration into copper conductor production and geographic expansion through engineering-procurement-construction direct partnerships.
Among Germany-based fabricators, Leoni AG anchors the premium-tier vector for automotive-derived cable technologies applied to industrial HVAC systems. Italian-structured Prysmian Group exemplifies Mediterranean manufacturing scale serving southern European infrastructure timelines. French-origin Nexans occupies a position within copper specialization archetypes for high-efficiency heat pump connection standards. These three represent distinct strategic postures: Leoni AG leverages automotive crossover expertise, Prysmian Group exploits logistics proximity to southern retrofit markets, and Nexans concentrates conductivity optimization for variable-load applications.
| Leading Market Players |
|---|
| Leoni AG |
| Sumitomo Electric |
| Prysmian Group |
| Ducab |
| Furukawa Electric |
| Nexans |
| NKT A/S |
| Power Plus Cable |
| ABB Ltd |
| Others |
Supply Flow & Price Mechanics
Copper conductor costs cascade through three pricing tiers as Mediterranean manufacturers pass through raw material volatility to German industrial buyers and French commercial contractors with differentiated contract structures.
Pricing Analysis
Input-cost pass-through from copper LME pricing dominates contract negotiations, with quarterly adjustment clauses standard for armored multi-core specifications. Three-tier pricing structure across premium, standard, and economy levels separates halogen-free certified cables from baseline PVC-sheathed alternatives and unbranded distributor stock. Cost compression in standard-tier indoor installations is intensifying because Eastern European contractors consolidate procurement through digital platforms. Residential heat pump installers exhibit highest price sensitivity, while infrastructure projects with redundant pathway requirements show lowest elasticity.
Supply Chain Analysis
Freight cost differentials between Mediterranean manufacturing bases and Nordic installation sites compress margin structures for just-in-time delivery commitments. Supply concentrates in Italy, Spain, and Germany, with copper rod drawing from Chilean and Zambian concentrate feeds. ECHA REACH compliance documentation and halogen-free compound certification create regulatory friction at borders. Single-source vulnerability concentrates in cross-linked polyethylene resin supply from petrochemical complexes in the Netherlands and Belgium. Distribution runs through engineering-procurement-construction firms with pan-European project portfolios, bypassing traditional national distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe HVAC Cables Market functions as a stable compounder anchored by EU Green Deal retrofit mandates that synchronize replacement cycles across building stock with limited demand elasticity.
For Market Incumbents: Hedge copper price exposure through long-term offtake agreements with Chilean concentrate suppliers and backward integration into rod production. Defend specification authority in German district heating corridors by accelerating EN 50575 fire certification timelines for halogen-free compounds before regulatory deadlines tighten. For New Entrants and Emerging Players: Engineering-procurement-construction partnerships offer the fastest channel to specification authority without legacy distributor relationships. Poland and Romania's municipal district heating feeder deployments present the most penetrable geography, with armored underground cables for thermal network modernization as the entry product. Pursue direct contractor engagement through digital procurement platforms rather than national distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance portfolios concentrate among integrated manufacturers with full compound formulation capabilities. The five-to-ten year viability frame favors suppliers with documented circular material flows under CSRD reporting mandates. Acquisition targets should demonstrate halogen-free certification velocity and established EPC direct relationships. Watch for F-Gas Regulation equipment replacement cycle peaks as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captive supply of conductor material insulates margin structures from LME volatility in German industrial procurement. |
| Halogen-Free Compound Certification Acceleration | EN 50575 fire performance approval velocity captures specification authority in French public building retrofits. |
| EPC Direct Partnership Expansion | Engineering-procurement-construction relationships bypass distributor compression and enable real-time inventory visibility. |
| Eastern European Geographic Expansion | Poland and Romania district heating modernization creates first-mover advantage in underpenetrated thermal network infrastructure. |
| CSRD-Compliant Circular Material Flow Documentation | Carbon footprint transparency and recycled content verification meets emerging procurement preference from EU Green Deal contractors. |
Methodological Framework
Bottom-up HVAC cable consumption modeling reconciled against top-down copper conductor shipment tracking forms the analytical core. Primary interviews with heat pump OEM procurement directors, EPC firm specification engineers, national distributor inventory managers, and cable compound R&D directors combined with secondary validation from ECHA substance restriction databases, EU F-Gas Regulation implementation timelines, and harmonized EN standard certification registries. Triangulation across installation type, end-user segment, and conductor material dimensions ensures coverage of both mature volume pools and emerging margin expansion categories.
Input-output matrices map copper price trajectories, REACH compliance cost burdens, and retrofit installation velocity against segment-specific demand elasticities across the projection horizon. Product type, installation environment, end-user sophistication, and national regulatory cluster segmentation dimensions structure volume and value outputs. CAGRs derive from compound annual trajectory fitting across annual installation forecasts and equipment replacement cycle synchronization. Heat pump adoption curves under KfW subsidy programs and district heating modernization pipeline data provide industry-specific forecast anchors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility, REACH substance restriction expansion, and EU Green Deal funding continuity. Forecasts reflect documented assumptions about equipment replacement timelines and subsidy program extensions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Downhole Cables Market
Cables
Global Low Voltage Cable Market
Cables
Submarine Communication Cables Market
Cables
Mexico Wires and Cables Market
Cables
Medium Voltage Cables Accessories Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
Global Cable Gland Market
Cables
North America Copper Wire and Cable Market
Cables
Cable Tray Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Cable Tags Market
Cables
Cable Trunking Market
Cables
Cable Assembly Market
Cables
LASER Light Cables Market
Cables
High-Temperature Superconducting Cables Market
Cables
US Medium Voltage Cable Accessories Market