
 SATA Power Cable Market | 2026-2036
SATA Power Cable Market Size, Share, and Industry Trends Forecast 2026-2036
SATA Power Cable Market Insights
Aftermarket service revenue for legacy storage infrastructure is narrowing as cloud migration accelerates enterprise decommissioning schedules. Molex leverages its connector ecosystem dominance to sustain aftermarket lock-in with data center operators. Amphenol anchors its position through backward integration into precision stamping operations for 15-pin housings. TE Connectivity competes on thermal cycling reliability certifications that extend product replacement intervals in enterprise environments.
A SATA power cable is a 15-pin connector assembly that delivers +3.3V, +5V, and +12V DC power to serial ATA storage devices through insulated copper conductors with standardized crimp terminations. The cable's latching mechanism prevents accidental disconnection in vibration-prone server racks, while its compact form factor enables dense storage backplane configurations. Standard SATA and SATA III connector types occupy the mature volume tier where margin pools have compressed to assembly-labor differentials, while custom connector variants for blade server applications command premium positioning due to tooling amortization requirements. Application demand concentrates in SSD deployments where lower current draw has shifted design emphasis toward signal integrity rather than pure power carrying capacity.
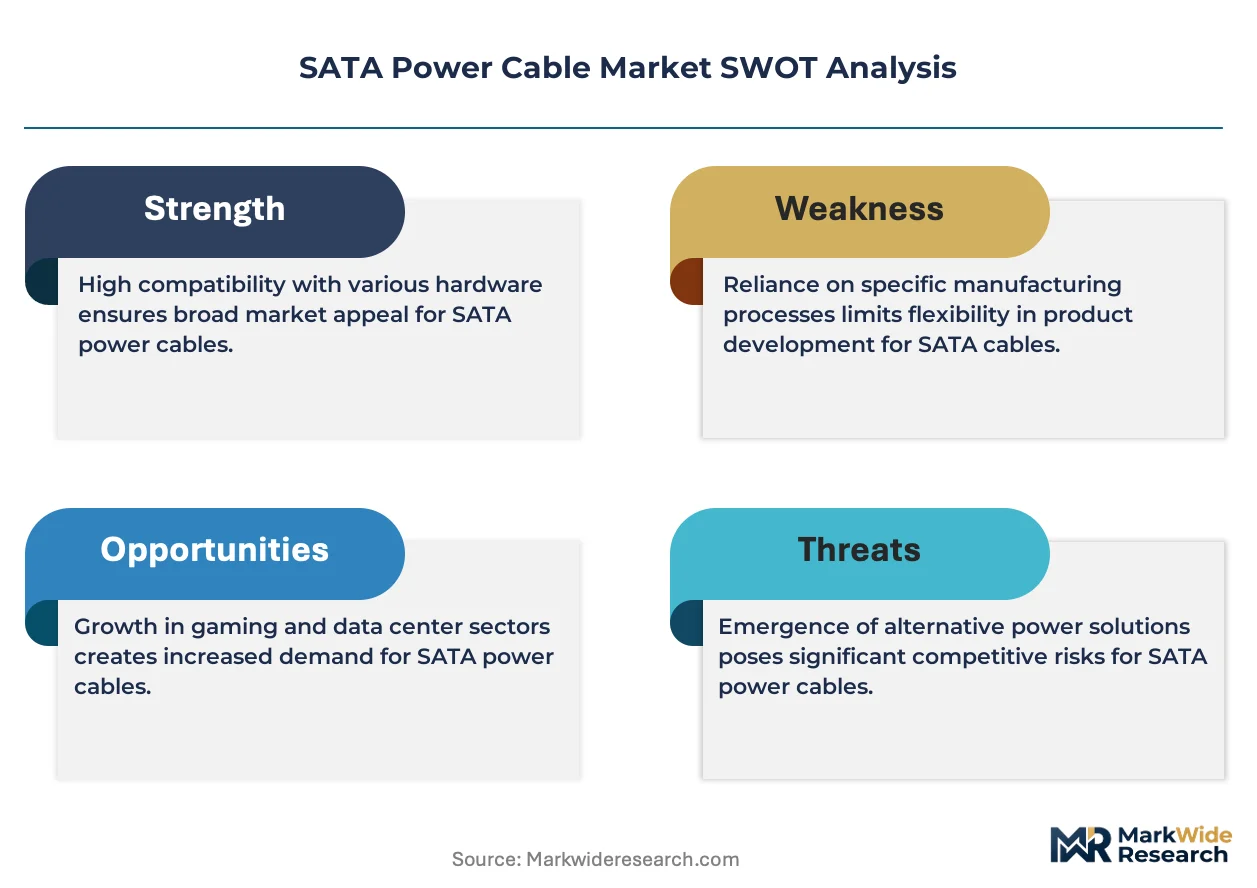
China's SAMR enforces GB 4943.1 safety standards that mandate flame-retardant jacketing materials for internal power cables, directly affecting supplier qualification costs for SATA power cable manufacturers serving the domestic market. The EU RoHS directive and REACH chemical restrictions limit cadmium and lead content in connector plating, pushing Furukawa Electric and other Asian suppliers toward tin-bismuth finish conversions. Stakeholders must monitor whether PCIe power delivery standards displace SATA power in next-generation enterprise storage architectures before committing to capacity expansion in crimping and overmolding equipment.
Market Dynamics
Enterprise storage refresh cycles in hyperscale data centers are compressing replacement intervals for power distribution components, while China's SAMR tightens material specifications through GB 4943.1 flame-retardant mandates that reshape supplier qualification economics.
Growth Catalysts
- Hyperscale data center expansion:Cloud infrastructure operators in Taiwan and South Korea are accelerating server rack deployments that require dense SATA power backplane configurations with latching connector reliability.
- EU RoHS and REACH chemical restrictions:These directives are pushing connector plating conversions toward tin-bismuth finishes, creating upgrade demand for compliant cable assemblies across European enterprise storage installations.
- SSD deployment density:Lower current draw in solid-state storage is shifting design emphasis toward signal integrity optimization, opening specification windows for premium cable variants with enhanced shielding.
Market Restraints
- Copper conductor cost volatility:Raw material price swings in insulated copper conductors compress assembly-labor margin pools that already dominate standard SATA cable economics.
- Supplier concentration in East Asian manufacturing clusters:Dense OEM supplier networks in Taiwan and South Korea create single-source vulnerability for data center operators requiring rapid cable replacement.
- PCIe power delivery substitution threat:Next-generation enterprise storage architectures may displace SATA power connectors entirely, freezing capacity commitment decisions for crimping and overmolding equipment investments.
Strategic Opportunities
- Blade server custom variants:Tooling amortization requirements for compact form-factor connectors create premium positioning windows for manufacturers with precision stamping capabilities.
- India's electronics manufacturing incentive schemes:PLI scheme benefits for component suppliers are attracting cable assembly investments to serve domestic server OEM demand.
- Japan's METI energy efficiency standards:These frameworks favor lower-resistance power delivery designs that premium SATA cable specifications can satisfy through enhanced conductor gauge configurations.
Industry Challenges
- GB 4943.1 certification timeline compression:China's SAMR enforcement of flame-retardant jacketing mandates is accelerating qualification costs for domestic market entry without guaranteed volume offsets.
- Legacy storage infrastructure decommissioning:Cloud migration is narrowing aftermarket service revenue windows, forcing cable manufacturers to defend replacement intervals through thermal cycling reliability certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SATA Power Cable Market |
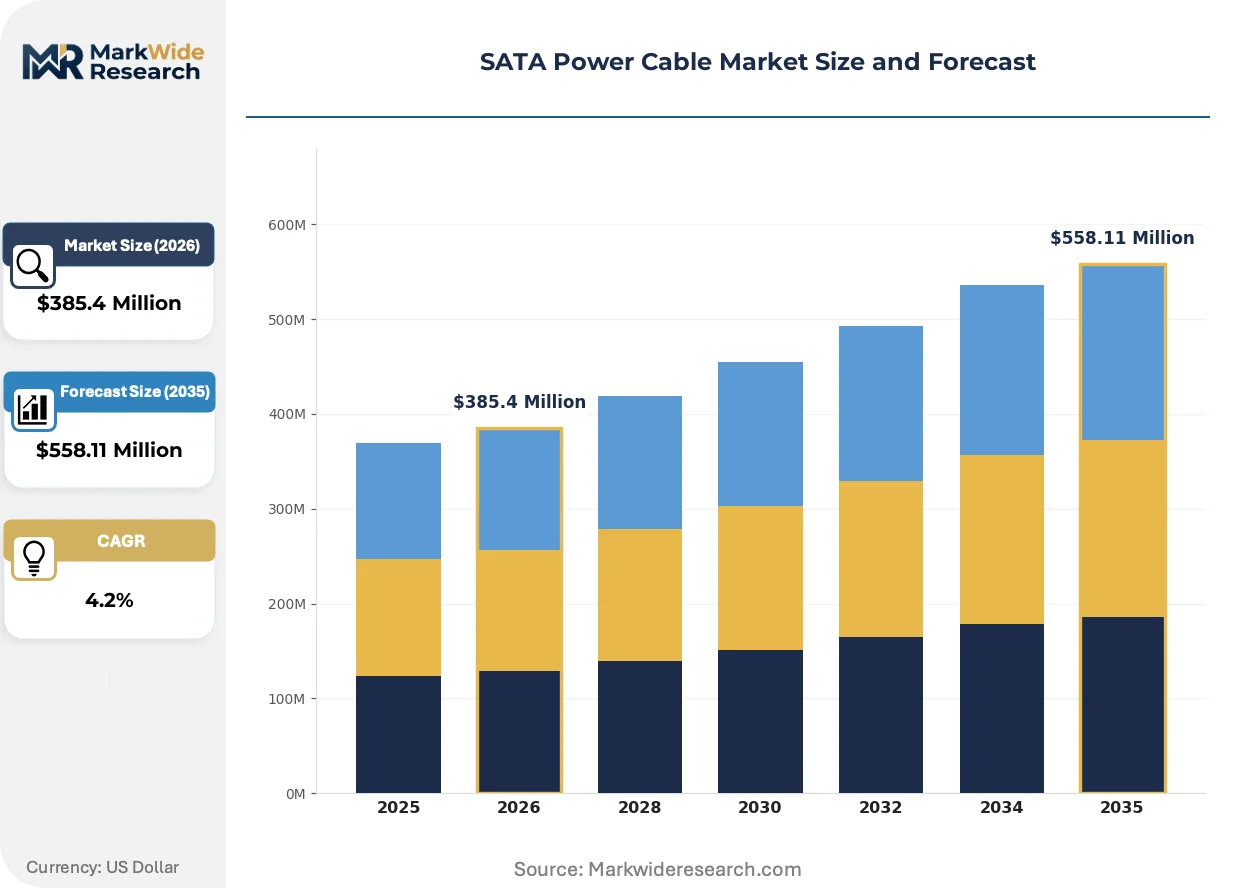
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard SATA, SATA III, SATA II, eSATA End User: Data Centers, Personal Computers, Laptops, Servers Application: SSD, HDD, Optical Drives, RAID Arrays Connector Type: 15-Pin, 7-Pin, 22-Pin, Custom Connectors |
| Companies Covered | Molex, Amphenol, TE Connectivity, 3M, Corsair, StarTech, Cable Matters, SilverStone Technology, Furukawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SATA Power Cable Market Trends and Innovations
Power delivery architectures for enterprise storage are fragmenting across competing standards, while material science advances and procurement model evolution reshape how cable assemblies are specified, sourced, and replaced in data center environments.
High-temperature thermoplastic jacketing compounds are hybridizing with traditional PVC formulations to meet GB 4943.1 flame-retardant requirements without sacrificing flexibility in dense server rack configurations. Taiwanese cable assemblers are adopting these materials fastest due to proximity to server OEM qualification labs. The technology is hybridizing cost structures across standard and premium product tiers as material differentiation supersedes pure labor arbitrage.
REACH chemical restrictions on cadmium and lead content in connector plating are forcing finish conversions that extend supplier qualification timelines by 6-12 months for European market access. ECHA enforcement has intensified documentation requirements for plating chemistry traceability. Asian suppliers serving EU data center operators are responding with dedicated tin-bismuth production lines and third-party certification investments.
Direct procurement relationships between hyperscale operators and cable assemblers are displacing traditional distribution channels for volume SATA power contracts. Cloud infrastructure buyers in South Korea are consolidating supplier panels to three qualified sources per specification tier. This concentration is most visible in Seoul's Songdo data center cluster, where operators negotiate multi-year frame agreements with backward-integrated connector manufacturers.
SATA Power Cable Market Segmentation
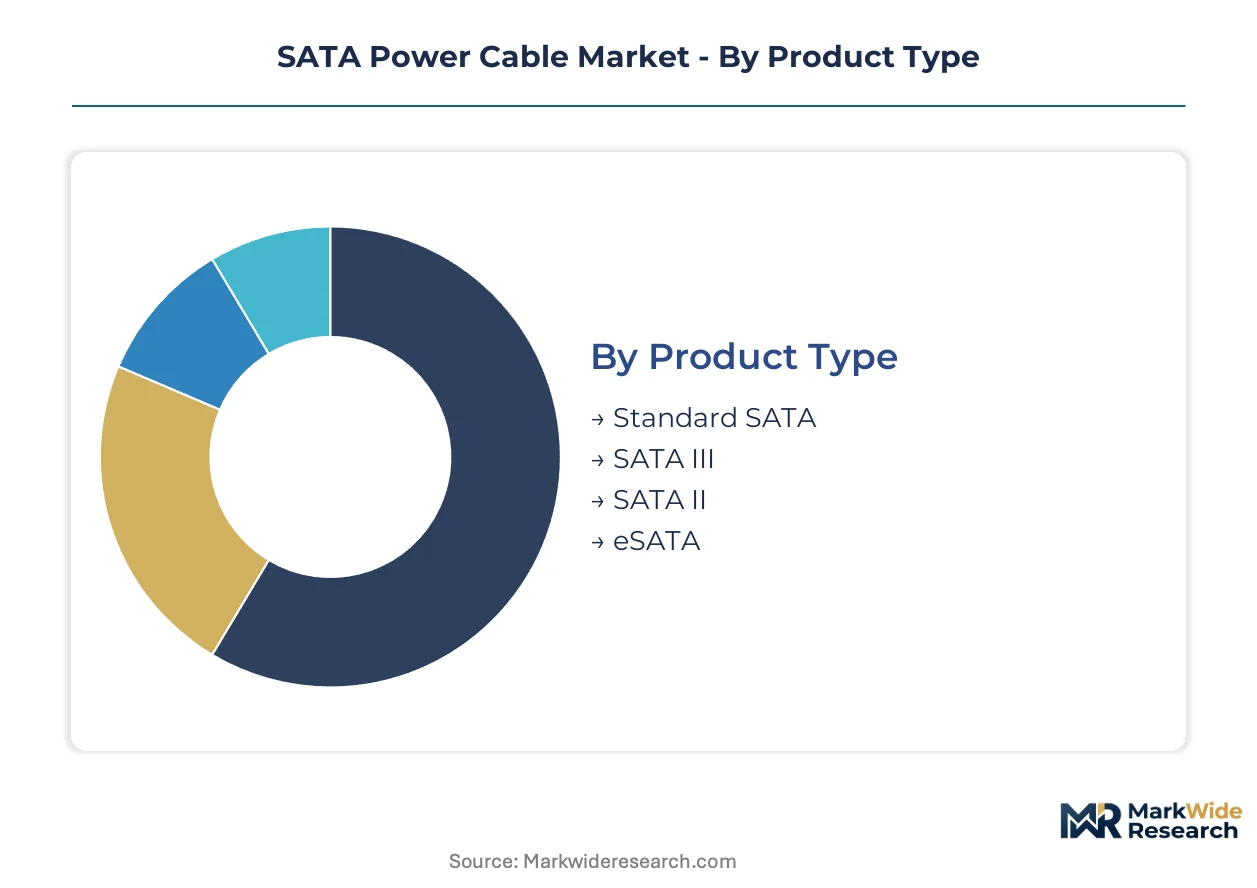
SATA power cable segmentation reveals how technical specifications fragment across deployment environments, from dense hyperscale racks to consumer laptops. Each dimension—product generation, end-user infrastructure, storage media type, and pin configuration—creates distinct margin pools and qualification barriers for cable assemblers.
Product Type:
Use-case spectrum spans legacy infrastructure maintenance to next-generation storage backplanes, with each generation carrying different certification burdens and replacement cycle dynamics.
- Standard SATA:The 15-pin connector assembly with +3.3V, +5V, and +12V rails dominates volume shipments for enterprise HDD deployments in Taiwan's server manufacturing corridor. Hyperscale operators specify these for replacement inventory, though margin pools have compressed to assembly-labor differentials.
- SATA III:6 Gbps signal integrity requirements drive specification emphasis toward shielded conductor configurations for SSD arrays in Seoul's Songdo data center cluster. Cloud infrastructure buyers negotiate multi-year frame agreements for these assemblies.
- SATA II:Legacy 3 Gbps infrastructure in maintained enterprise storage systems generates aftermarket demand with narrow replacement windows.
- eSATA:External shielded variants serve specialized industrial and surveillance storage applications requiring extended cable runs.
The dominant share belongs to Standard SATA, while SATA III is closing the gap fastest.
End User:
Customer-type concentration determines procurement sophistication, with direct hyperscale relationships displacing traditional distribution channels for volume tiers.
- Data Centers:Hyperscale operators in South Korea consolidate supplier panels to three qualified sources per specification tier, negotiating multi-year frame agreements with backward-integrated connector manufacturers.
- Servers:OEM qualification labs in Taiwan drive fastest adoption of high-temperature thermoplastic jacketing compounds meeting GB 4943.1 flame-retardant mandates.
- Personal Computers:Consumer desktop assembly demand concentrates in cost-driven supply chains with minimal customization requirements.
- Laptops:Compact form-factor constraints favor ultra-flexible conductor gauges with reduced current carrying capacity.
Data Centers command the largest procurement volumes, while Servers show the steepest expansion trajectory for premium cable variants.
Application:
Storage media technology shifts are redistributing design emphasis from pure power delivery toward signal integrity optimization.
- SSD:Lower current draw in solid-state storage enables thinner conductor gauges while demanding enhanced shielding for electromagnetic compatibility in dense backplane configurations.
- HDD:Mechanical drive power requirements sustain demand for standard 18 AWG conductor specifications in enterprise cold storage tiers.
- RAID Arrays:Multi-drive redundancy configurations require latching connector reliability certifications that extend replacement intervals.
- Optical Drives:Declining media format usage restricts demand to legacy system maintenance and archival infrastructure.
SSD applications generate the fastest specification evolution, while HDD maintains volume leadership in replacement markets.
Connector Type:
Pin configuration diversity reflects the tension between standardized interoperability and custom form-factor optimization for specialized chassis designs.
- 15-Pin:The standard power delivery housing with three voltage rails and three ground pins anchors enterprise procurement specifications across all major server OEM qualification programs.
- Custom Connectors:Blade server compact form-factors command premium positioning due to tooling amortization requirements and precision stamping capabilities.
- 7-Pin:Signal-only configurations serve specialized data transmission applications without power delivery requirements.
- 22-Pin:Combined power-and-data integrated connectors reduce component count in space-constrained laptop and small-form-factor designs.
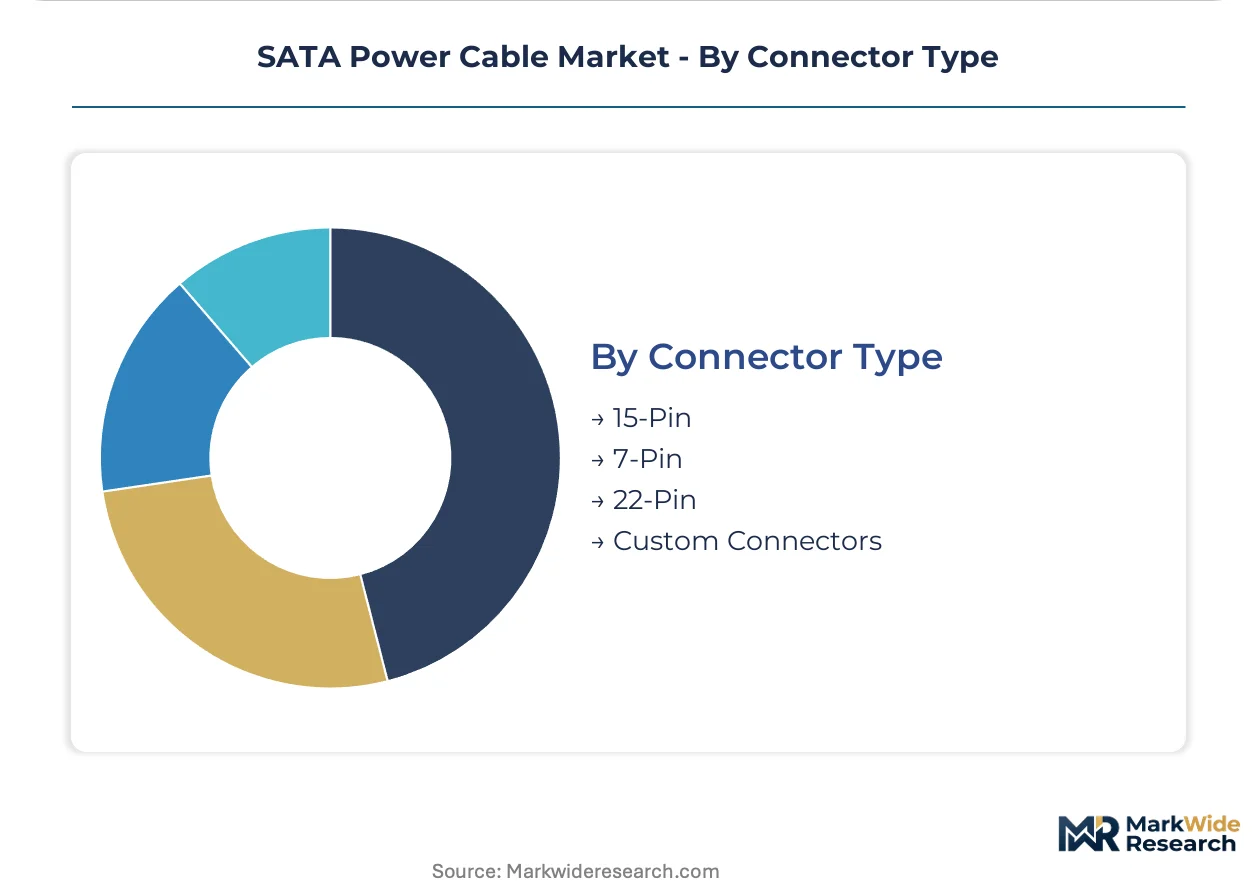
15-Pin connectors retain dominant specification share, while Custom Connectors capture the fastest margin expansion through tooling lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale operators in South Korea negotiate multi-year frame agreements with minimal price sensitivity, while consumer desktop assemblers in India drive aggressive cost-down cycles that compress assembly-labor margins to minimum viable thresholds.
United States
Enterprise data center operators in Northern Virginia's Ashburn corridor consolidate supplier panels for SATA power backplane configurations. The EPA's energy efficiency guidelines for data center infrastructure indirectly influence power delivery component specifications. Phoenix's emerging cloud campus cluster attracts cable assembly investments serving domestic hyperscale demand.
China
Server OEM qualification labs in Shenzhen and Suzhou accelerate adoption of high-temperature thermoplastic jacketing compounds. SAMR's GB 4943.1 flame-retardant mandates reshape supplier qualification economics for domestic market entry. Yangtze River Delta manufacturing clusters concentrate precision stamping capabilities for 15-pin connector housings.
South Korea
Cloud infrastructure buyers in Seoul's Songdo data center cluster negotiate direct procurement relationships displacing traditional distribution channels. The country's national electronics regulator enforces stringent electromagnetic compatibility standards for dense storage backplane configurations. Busan-Ulsan industrial corridor hosts backward-integrated connector manufacturers serving regional server OEM networks.
Japan
METI's energy efficiency frameworks favor lower-resistance power delivery designs that premium SATA cable specifications satisfy through enhanced conductor gauge configurations. Precision manufacturers in Nagoya's Chubu region maintain captive stamping operations for custom blade server connectors. Tokyo-based server OEMs drive specification evolution toward signal integrity optimization for SSD deployments.
Taiwan
Server OEM qualification labs in Taipei and Taichung drive fastest adoption of GB 4943.1-compliant materials for export-oriented production. The island's dense supplier networks create single-source vulnerability concerns for data center operators requiring rapid cable replacement. Hsinchu Science Park anchors connector ecosystem dominance through integrated design-to-assembly capabilities.
SATA Power Cable Market Competitive Landscape
Capability concentration sits with precision stamping specialists; scale advantage sits with diversified connector conglomerates. The market structures around three tiers: backward-integrated housing manufacturers, dedicated cable assemblers, and distributor-branded commodity suppliers. Two strategic archetypes dominate competitive positioning—tooling-locked custom variant specialists and thermal-cycling-certified enterprise reliability providers. Capacity commitment decisions freeze across the industry as PCIe substitution threats delay crimping equipment investments.
Among diversified connector conglomerates, Molex, Amphenol, and TE Connectivity exemplify distinct competitive anchors. Molex occupies a position emphasizing connector ecosystem breadth that sustains aftermarket relationships with data center operators. Amphenol represents the backward-integrated archetype through captive precision stamping capabilities for 15-pin housing production. TE Connectivity sits within the reliability-certification tier, competing on thermal cycling performance that extends replacement intervals in enterprise environments.
| Leading Market Players |
|---|
| Molex |
| Amphenol |
| TE Connectivity |
| 3M |
| Corsair |
| StarTech |
| Cable Matters |
| SilverStone Technology |
| Furukawa Electric |
| Others |
Pricing and Supply Chain Analysis
Taiwan's precision stamping clusters for 15-pin connector housings concentrate upstream capability, pushing margin pools downstream toward cable assemblers with GB 4943.1 certification and direct hyperscale relationships. Where housing production localizes determines who captures premium positioning in blade server custom variants versus commodity standard SATA tiers.
Pricing Analysis
Aftermarket service contracts for legacy enterprise storage infrastructure anchor lifetime value capture for incumbent cable manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal cycling certification grade and volume commitment scale. Cost compression in standard SATA tiers intensifies because assembly-labor arbitrage has eroded to minimum viable thresholds. Consumer desktop assemblers exhibit highest price sensitivity, while South Korean hyperscale operators in Seoul's Songdo cluster negotiate multi-year frame agreements with minimal price elasticity.
Supply Chain Analysis
Export-control restrictions on precision stamping equipment and copper conductor drawing technology limit technology transfer to emerging cable assembly jurisdictions. Manufacturing gravity centers on Taiwan, South Korea, and China's Yangtze River Delta, with raw material dependencies spanning insulated copper conductors, high-temperature thermoplastic compounds, and tin-bismuth plating chemistries. Single-source vulnerability concentrates in Taiwanese connector housing suppliers serving multiple server OEMs through dense qualification networks. Distribution runs through direct procurement relationships displacing traditional channel partners for volume hyperscale contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SATA power cable demand sits in early-cycle expansion as hyperscale data center buildouts in East Asian manufacturing corridors accelerate storage backplane deployments ahead of potential PCIe substitution. SSD density shifts and GB 4943.1 compliance requirements create specification windows for premium variant suppliers.
For Market Incumbents: Harden thermal cycling reliability certifications to extend replacement intervals and defend enterprise aftermarket revenue against cloud migration headwinds. Deepen backward integration into precision stamping operations for 15-pin housings to lock in blade server custom variant margins before tooling amortization requirements escalate qualification barriers. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized cable assembly corridor serving domestic server OEM demand before incumbent footprint solidifies. Target eSATA external shielded variants for industrial and surveillance storage applications requiring extended cable runs, where specification complexity deters commoditization pressure and hyperscale procurement consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated connector manufacturers with captive stamping capabilities and existing GB 4943.1 qualification timelines. Long-term viability hinges on positioning ahead of PCIe power delivery substitution inflection; the signal to watch is enterprise storage architecture refresh announcements from major server OEMs in Taiwan and South Korea.| Strategic Initiative | Industry Significance |
|---|---|
| GB 4943.1 Certification Investment | Flame-retardant jacketing compliance unlocks China's domestic server OEM procurement panels. |
| Tin-Bismuth Plating Line Conversion | REACH-compliant finish chemistry secures European data center operator qualification windows. |
| Direct Hyperscale Procurement Relationship | South Korean cloud infrastructure buyers consolidate supplier panels to three qualified sources. |
| High-Temperature Thermoplastic Material Adoption | Taiwanese assemblers leverage proximity to OEM labs for fastest GB 4943.1 compliance. |
| Blade Server Custom Connector Tooling | Precision stamping capabilities command premium positioning through amortization lock-in. |
Research Methodology
Cross-validation between primary interviews with data center procurement officers, server OEM qualification engineers, cable assembly plant managers, and connector housing technical directors anchors the qualitative findings. Secondary validation draws from SAMR GB standard filings, EU ECHA REACH documentation, hyperscaler capex disclosures, and customs trade data for insulated copper conductor flows. Bottom-up shipment estimates triangulate against top-down storage device production forecasts across the analysis window.
Calibration against historical replacement cycle patterns and hyperscale deployment announcements shapes the analytical framework. Segmentation dimensions span product generation, end-user infrastructure type, storage media technology, and connector pin configuration, with regional regulatory cluster as an additional modeled variable. CAGRs derive from installed base turnover rates and specification shift velocities, incorporating SSD penetration curves and enterprise storage refresh cadence as cable-specific demand drivers.
Stress conditions across copper price volatility, PCIe substitution timing, and GB 4943.1 enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hyperscale expansion continuity and regulatory compliance timeline stability. Material shifts in enterprise storage architecture standards or SAMR certification enforcement rigor would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Accessories Market
Cables
Europe Wire and Cable Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Global Industrial Automation Cable Market
Cables
Cable Market
Cables
Cable Tags Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
India Wire and Cable Market
Cables
Cable Lugs Market
Cables
Premise Cable Market
Cables
Class 1E Electric Cables Market
Cables
Cable Trunking Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Network Cable Tester Market
Cables
Power and Control Cable Market