
 3D Display Module Market | 2026-2036
3D Display Module Market Size, Share, and Industry Trends Forecast 2026-2036
3D Display Module Market Outlook
Asset-light leasing models for advanced lithography and bonding equipment are rewriting competitive entry barriers in 3D display module fabrication. Samsung Electronics leverages captive OLED pilot lines to sustain technology leadership in active 3D stacks. BOE Technology Group anchors massive domestic procurement in China through government-backed display foundry partnerships. Leia Inc. differentiates via light-field nanotechnology specialization, occupying premium autostereoscopic niches without competing on panel volume.
A 3D display module integrates optical layer stacks, backplane drivers, and parallax barrier or lenticular lens arrays to render depth-perceivable imagery without auxiliary eyewear, typically operating at refresh rates exceeding 120 Hz to suppress motion artifacts in stereoscopic modes. The primary purpose spans immersive visualization in surgical planning, automotive HUD integration, and interactive digital signage. OLED modules command structural margin premiums due to self-emissive pixel control enabling thinner optical stacks, while holographic technology represents the fastest-growing segment despite manufacturing immaturity. LCD retains volume dominance in education and budget healthcare deployments where cost sensitivity overrides depth fidelity requirements.
FCC electromagnetic interference standards in the United States, REACH substance restrictions in Europe, and China's GB 4943.1 safety mandates collectively shape module material selection, optical coating chemistry, and export market access protocols. EMA and FDA scrutiny of diagnostic display calibration is tightening certification requirements for medical imaging subsystems, directly influencing R&D allocation among healthcare-focused suppliers. Stakeholders must monitor divergence between regional electromagnetic compliance frameworks and emerging photobiological safety standards for near-eye autostereoscopic applications.
Market Dynamics
The 3D display module sector is being restructured by the migration from passive lenticular arrays toward active parallax-barrier OLED stacks, a shift that demands recalibration of bonding equipment depreciation schedules and foundry utilization rates across East Asian fabrication clusters.
Growth Catalysts
- GB 4943.1 Safety Mandates:China's tightening electromagnetic compatibility standards for display modules are accelerating domestic certification infrastructure investment, creating captive demand for locally compliant optical layer stacks.
- Automotive HUD Integration:Tier-1 suppliers in Germany and Japan are specifying 3D-capable windscreen projection modules for next-generation advanced driver-assistance platforms.
- Light-Field Nanotechnology Maturation:Advances in diffractive optical element fabrication are compressing minimum viable feature sizes for glasses-free depth rendering below 500 nanometers.
Market Restraints
- Input Cost Volatility:Indium tin oxide sputtering targets face price instability due to concentrated rare earth refining in Chinese state-controlled processing facilities.
- Technical Limitation:Viewing-angle-dependent crosstalk in autostereoscopic lenticular systems restricts effective sweet-zone width to 35-40 degrees in current-generation modules.
- Regulatory Friction:REACH substance restrictions on halogenated flame retardants in optical coatings force reformulation cycles that extend European market entry timelines by 8-14 months.
Strategic Opportunities
- Surgical Planning Visualization:Preoperative 3D anatomical modeling in South Korean university hospitals is creating specification pull for medical-grade autostereoscopic monitors with sub-millimeter depth accuracy.
- Interactive Digital Signage:Retail environments in Dubai and Riyadh are deploying gesture-responsive 3D wayfinding kiosks that bypass touchscreen hygiene concerns.
- Technology Convergence:Integration of eye-tracking infrared arrays with parallax barrier refresh logic is enabling dynamic viewpoint adaptation without hardware multiplication.
Industry Challenges
- Capex Intensity:Gen-8.5 OLED pilot lines for 3D stack validation require capital commitments exceeding $2 billion per facility, constraining mid-tier foundry participation.
- Certification Timeline Compression:FDA 510(k) pathways for diagnostic display subsystems now demand photometric calibration traceability to NIST-recognized standards, extending premarket submission preparation.
- IP Licensing Complexity:Patent thickets around micro-lens array alignment algorithms create royalty stacking risks for module assemblers sourcing components from multiple optical film vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Display Module Market |
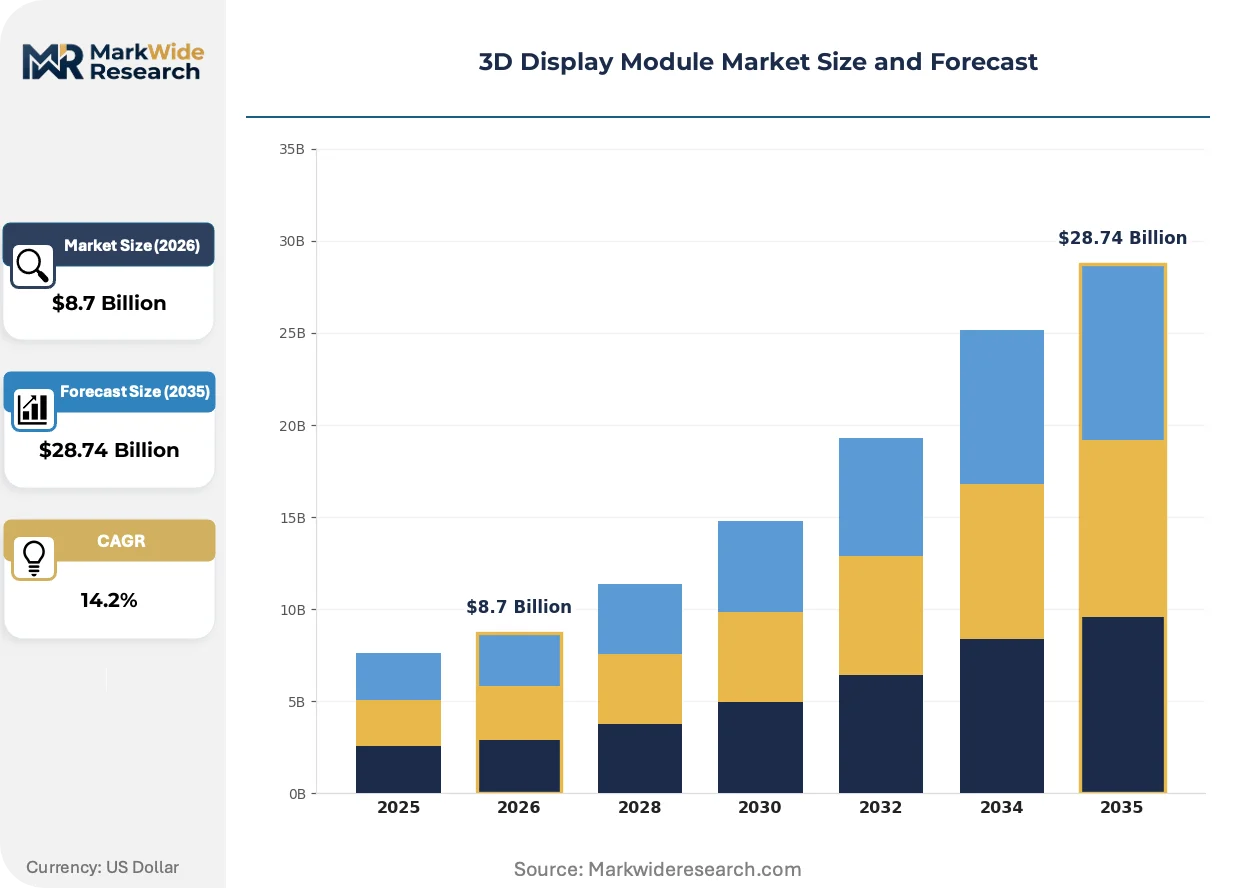
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, DLP, LCoS Technology: Passive 3D, Active 3D, Autostereoscopic, Holographic Application: Gaming, Medical Imaging, Advertising, Virtual Reality End User: Consumer Electronics, Healthcare, Education, Automotive |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Panasonic Corporation, Sharp Corporation, Toshiba Corporation, BOE Technology Group, AU Optronics, Leia Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Display Module Market Strategic Shifts
Active depth-control architectures are displacing static optical configurations across premium display tiers, while regulatory pressure on electromagnetic emissions and photobiological safety is rewriting material selection protocols for near-eye applications.
Quantum-dot color conversion layers are hybridizing with OLED backplanes to extend color gamut coverage while maintaining self-emissive pixel control essential for thin 3D optical stacks. Automotive HUD suppliers in Stuttgart and Toyota City are piloting these hybrid architectures for daylight-readable depth projection. The technology is hybridizing module stack designs previously segmented between LCD volume and OLED premium tiers.
EU F-Gas Regulation phase-down schedules are banning hydrofluorocarbon-based cleaning chemistries from display module fabrication, forcing South Korean and Japanese foundries to retrofit solvent recovery systems. The restriction compresses allowable process window tolerances for optical adhesive dispensing. Medical imaging subsystem vendors targeting European hospitals are absorbing compliance costs through dedicated cleanroom line segregation.
Hospital procurement committees are consolidating 3D surgical display purchasing through centralized biomedical engineering departments, displacing decentralized OR manager autonomy. Group purchasing organizations in Texas and California are negotiating multi-year service bundles that unbundle hardware from calibration maintenance. This concentration is most visible in US academic medical centers where diagnostic imaging volume justifies dedicated 3D visualization suites.
3D Display Module Market Segmentation
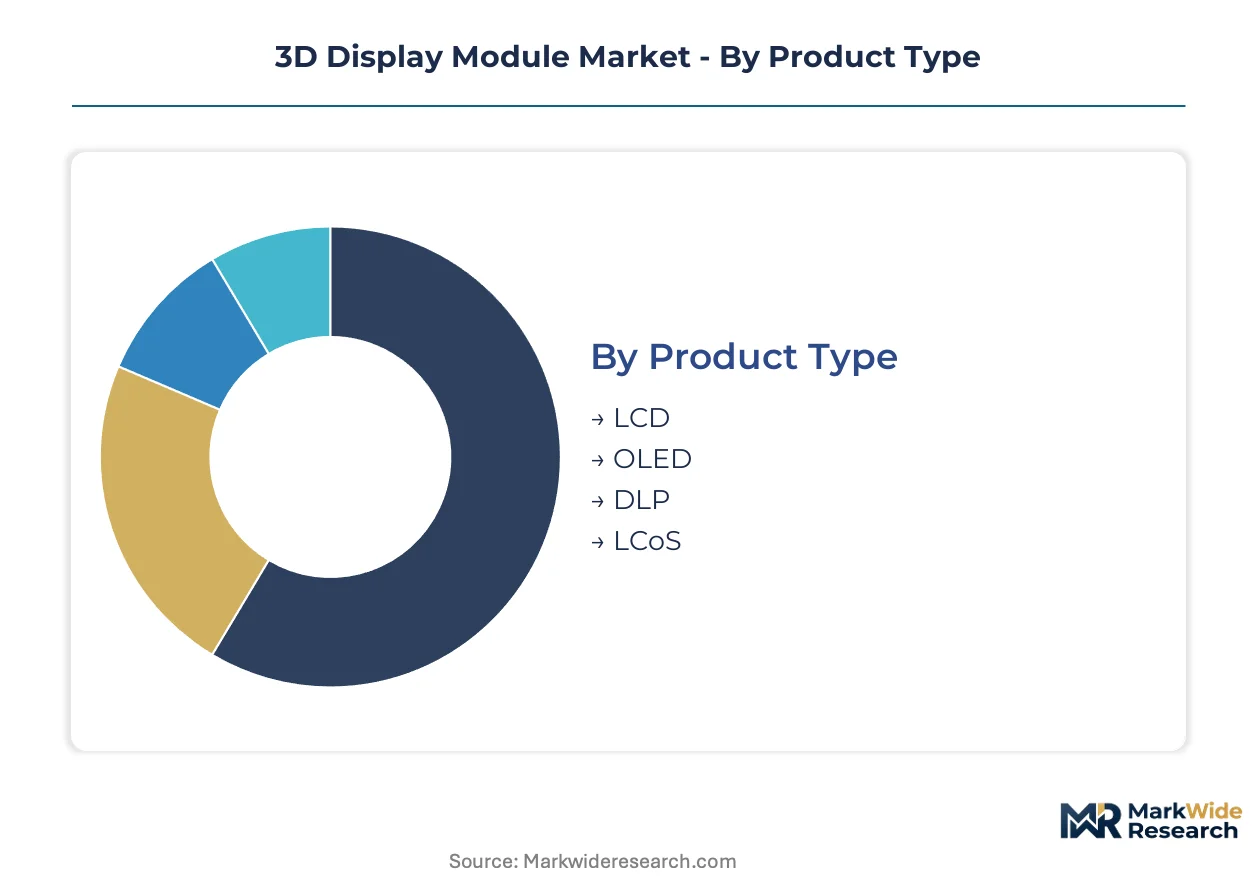
Module stack composition determines margin structure and certification pathway. Technology selection fixes optical complexity and foundry equipment requirements. Application verticals impose divergent refresh rate, luminance, and calibration standards.
Product Type:
Cost tier separates self-emissive architectures from backlit transmissive stacks, with direct implications for bonding equipment depreciation and optical layer thickness.
- OLED:Self-emissive pixel control eliminates backlight diffusion layers, enabling sub-2mm optical stacks with native 120Hz refresh. South Korean foundries concentrate Gen-6 capacity for premium autostereoscopic panels targeting automotive HUD integrators in Stuttgart and Toyota City. The technology commands structural margin premiums due to thinner form factors and superior motion artifact suppression.
- LCD:Transmissive architecture with edge-lit or direct LED backlighting dominates education and budget healthcare deployments where cost sensitivity overrides depth fidelity. Chinese panel fabs in Hefei and Chongqing anchor volume production, feeding procurement cycles for US academic medical centers and Indian digital classroom initiatives. Price compression is severe in this tier.
- DLP:Digital micromirror device projection enables large-format 3D rendering without panel size constraints, finding niche deployment in Saudi Arabian immersive advertising installations and Dubai retail atriums.
- LCoS:Liquid crystal on silicon reflective modulation supports near-eye applications with pixel densities exceeding 3000 ppi, serving pilot lines for AR headset developers in California and Tokyo.
OLED holds installed capacity. LCD is rotating up the share rankings in emerging market education procurement.
Technology:
Application context dictates whether eyewear-assisted depth rendering or glasses-free parallax control delivers acceptable user experience economics.
- Autostereoscopic:Parallax barrier and lenticular lens arrays render depth-perceivable imagery without auxiliary eyewear, requiring precise alignment tolerances below 5 micrometers during optical film lamination. South Korean university hospitals specify medical-grade monitors with sub-millimeter depth accuracy for preoperative anatomical modeling. The segment absorbs disproportionate R&D allocation due to viewing-angle crosstalk challenges.
- Holographic:Diffractive optical element fabrication compresses minimum viable feature sizes below 500 nanometers, enabling true wavefront reconstruction. German automotive suppliers in Stuttgart pilot windscreen projection modules for next-generation driver-assistance platforms. Manufacturing immaturity constrains yield rates at commercial scale.
- Active 3D:Shutter-glass synchronization with high-refresh backplanes retains dominance in premium gaming peripherals and VR tethered headsets.
- Passive 3D:Polarized filter systems persist in cinema exhibition and large-venue digital signage where eyewear distribution logistics are manageable.
Autostereoscopic holds installed capacity. Holographic is rotating up the share rankings.
Application:
End-use performance requirements stratify refresh rate specifications, color calibration protocols, and electromagnetic compliance testing intensity.
- Gaming:Consumer electronics OEMs specify 144Hz minimum refresh with sub-10ms motion-to-photon latency for competitive stereoscopic titles. Japanese and South Korean display foundries prioritize pilot line allocation for console-integrated 3D stacks. The segment accelerates adoption of active parallax-barrier OLED architectures.
- Medical Imaging:FDA 510(k) pathways demand photometric calibration traceability to NIST-recognized standards, extending premarket submission preparation. Texas and California academic medical centers consolidate purchasing through centralized biomedical engineering departments, unbundling hardware from multi-year calibration maintenance contracts.
- Advertising:Gesture-responsive 3D wayfinding kiosks bypass touchscreen hygiene concerns in Dubai and Riyadh retail environments, deploying light-field nanotechnology for depth rendering without eyewear.
- Virtual Reality:Near-eye autostereoscopic applications face tightening photobiological safety scrutiny from regulators, rewriting material selection protocols for optical coatings and LED emission spectra.
Gaming holds installed capacity. Medical Imaging is rotating up the share rankings.
End User:
Customer procurement sophistication determines whether module vendors compete on specification compliance, total cost of ownership, or ecosystem integration depth.
- Consumer Electronics:Smartphone and tablet OEMs in Shenzhen and Seoul drive volume demand for compact autostereoscopic panels, leveraging captive OLED pilot lines for technology leadership in active 3D stacks.
- Healthcare:EMA and FDA scrutiny of diagnostic display calibration tightens certification requirements, directly influencing R&D allocation among suppliers targeting hospital procurement committees.
- Automotive:Tier-1 suppliers in Germany and Japan specify 3D-capable windscreen projection modules for advanced driver-assistance platforms, requiring daylight-readable luminance exceeding 10000 nits.
- Education:Budget-constrained digital classroom deployments in India and Southeast Asia favor LCD-based 3D modules where cost sensitivity overrides depth fidelity requirements.
Consumer Electronics holds installed capacity. Healthcare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed display foundry partnerships in China and tightening electromagnetic compatibility mandates across multiple jurisdictions are redirecting module procurement toward certified domestic supply chains.
China
MIIT subsidies for Gen-8.5 OLED pilot lines accelerate capacity buildout in Hefei and Chongqing. GB 4943.1 safety mandates tighten certification timelines for optical layer stacks bound for consumer electronics OEMs. BOE Technology Group anchors massive domestic procurement through state-controlled panel fabrication partnerships.
South Korea
Samsung Electronics leverages captive OLED pilot lines to sustain technology leadership in active 3D stacks for automotive HUD integrators. MFDS scrutiny of diagnostic display calibration tightens requirements for medical imaging subsystems. Seoul Capital Area foundries concentrate Gen-6 capacity for premium autostereoscopic panels.
Japan
METI funding for light-field nanotechnology R&D compresses minimum viable feature sizes below 500 nanometers. JIS standards for electromagnetic compatibility shape export market access protocols for optical coating chemistry. Toyota City and Nagoya clusters pilot windscreen projection modules for next-generation driver-assistance platforms.
United States
FDA 510(k) pathways for diagnostic display subsystems demand photometric calibration traceability to NIST-recognized standards. FCC electromagnetic interference standards influence module material selection for near-eye autostereoscopic applications. California and Texas academic medical centers consolidate purchasing through centralized biomedical engineering departments.
Germany
EU F-Gas Regulation phase-down schedules ban hydrofluorocarbon-based cleaning chemistries from display module fabrication. REACH substance restrictions on halogenated flame retardants force reformulation cycles for optical coatings. Stuttgart Tier-1 suppliers specify 3D-capable windscreen projection modules requiring daylight-readable luminance exceeding 10000 nits.
3D Display Module Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiers. The vendor base separates into scale-driven panel fabricators, technology-agnostic assemblers, and nanotechnology specialists. Three archetypes dominate: captive foundry operators leveraging vertical integration, independent module houses sourcing optical films from multiple vendors, and light-field technology purists avoiding volume competition. M&A activity concentrates on optical film vendors and bonding equipment suppliers, while strategic partnerships between automotive Tier-1s and display foundries accelerate HUD qualification timelines.
Among East Asian fabricators, Samsung Electronics, LG Electronics, and Sony Corporation exemplify distinct competitive positions. Samsung Electronics occupies the captive foundry archetype through in-house OLED pilot line control. LG Electronics represents the diversified electronics conglomerate model with display module integration across consumer and automotive verticals. Sony Corporation anchors the premium imaging specialist tier, leveraging broadcast and cinema calibration expertise for medical and professional visualization subsystems. Leia Inc. sits within the nanotechnology purist category, occupying premium autostereoscopic niches without competing on panel volume.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Panasonic Corporation |
| Sharp Corporation |
| Toshiba Corporation |
| BOE Technology Group |
| AU Optronics |
| Leia Inc. |
| Others |
Value Chain & Pricing Dynamics
Hefei and Chongqing panel fabrication clusters anchor Chinese LCD volume production, feeding procurement cycles for Indian digital classrooms and US academic medical centers where cost sensitivity compresses module margins. This geographic concentration of backlit transmissive capacity creates asymmetric pricing power for foundries serving budget-tier education deployments, while OLED pilot line scarcity in South Korea sustains structural premiums for automotive HUD integrators requiring sub-2mm optical stacks.
Pricing Analysis
Certification level creates the primary spread across module tiers, with FDA 510(k) diagnostic-grade displays commanding substantial premiums over uncertified education panels. Three-tier pricing structure across premium, standard, and economy levels reflects vertical integration depth, captive OLED pilot lines, and after-sales calibration bundling. Cost compression in LCD education modules is intensifying because Chinese state-controlled rare earth refining concentrates indium tin oxide pricing leverage. Healthcare procurement committees show least price sensitivity due to reimbursement-protected diagnostic workflows, while Indian state education boards exhibit acute cost consciousness.
Supply Chain Analysis
Tariff exposure between Chinese optical film vendors and German automotive Tier-1s dominates supply chain risk calculus for HUD module qualification. Manufacturing concentrates in China, South Korea, and Japan, where Gen-6 and Gen-8.5 foundry capacity feeds divergent application tiers. Module stack assembly draws from indium tin oxide sputtering targets, diffractive optical elements, and quantum-dot color conversion layers. Single-source vulnerability persists in sub-500 nanometer diffractive optical element fabrication. Distribution runs through direct foundry partnerships for automotive and medical verticals, with spot procurement serving education and retail signage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autostereoscopic light-field maturation represents an early-cycle expansion story, with sub-500 nanometer feature size compression enabling glasses-free depth rendering in surgical planning and automotive HUD applications previously blocked by technical limitation.
For Market Incumbents: Build captive certification infrastructure as the defensive moat against emerging nanotechnology specialists. Samsung Electronics and BOE Technology Group should deepen backward integration into optical film lamination equipment to control sub-5 micrometer alignment tolerances. FDA 510(k) pathway expertise and EMA diagnostic calibration relationships constitute defensible switching costs. Capacity addition in South Korean Gen-6 OLED pilot lines protects automotive HUD allocation priority. For New Entrants and Emerging Players: Build out surgical planning visualization subsystems targeting South Korean university hospitals where specification pull for medical-grade monitors remains underserved. Gesture-responsive digital signage in Dubai and Riyadh retail environments offers penetrable white space with hygiene-conscious procurement committees. Light-field nanotechnology specialization enables premium autostereoscopic positioning without competing against volume panel economics. Licensing micro-lens array alignment algorithms from Japanese METI-funded research consortia provides credible technology access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors optical film vendors and bonding equipment suppliers over commodity panel fabricators. The five-to-ten year viability window rewards acquisition targets with holographic wavefront reconstruction IP and diffractive optical element fabrication yield expertise. Patent thickets around dynamic parallax barrier refresh logic with eye-tracking integration represent the inflection signal to monitor for royalty stacking consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Film Vendor Acquisition | Secures sub-5 micrometer alignment tolerance control for autostereoscopic lamination. |
| Gen-8.5 OLED Pilot Line Investment | Captures automotive HUD qualification priority with Stuttgart and Toyota City Tier-1s. |
| GB 4943.1 Certification Infrastructure | Unlocks Chinese domestic procurement through MIIT-compliant optical layer stacks. |
| Light-Field Nanotechnology Licensing | Accelerates holographic wavefront reconstruction yield without captive R&D cycles. |
| Hospital GPO Service Bundling | Consolidates Texas and California academic medical center purchasing through calibration-maintenance contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing display foundry engineering directors, automotive Tier-1 procurement managers, hospital biomedical engineering heads, and digital signage systems integrators. Secondary validation drew from SEC 10-K filings of panel fabricators, MIIT subsidy disclosure databases, FDA 510(k) premarket notification repositories, and EU F-Gas Regulation implementation reports. Bottom-up capacity modeling triangulated against top-down application demand sizing.
Calibration against historical foundry utilization rates and automotive HUD program launch timelines anchored the analytical framework across the projection horizon. Segmentation dimensions spanned module stack composition, depth rendering technology, end-use vertical performance requirements, and regional regulatory cluster compliance intensity. CAGRs were derived from installed capacity trajectories and application penetration curves. Forecast inputs included OLED pilot line depreciation schedules and REACH substance restriction reformulation cycle timelines.
Stress conditions across indium tin oxide price volatility, GB standards certification timeline compression, and automotive HUD program cancellation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding light-field nanotechnology yield maturation and holographic manufacturing scale readiness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Light Field Display Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Global Medical Display Market
Display Technologies
Global Embedded Display Market
Display Technologies
Commercial Display Market
Display Technologies
Global Projector Market
Display Technologies
Visual Computing Market
Display Technologies
Rugged Display Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Thin Display Technology Market
Display Technologies
OLED Panel Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
OLED Microdisplay Market
Display Technologies
Gaming Monitors Market