
 APAC Push Buttons and Signaling Devices Market | 2026-2036
APAC Push Buttons and Signaling Devices Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Push Buttons and Signaling Devices Market Outlook
Automotive supplier demand is decoupling from traditional manufacturing uptake across APAC. Eaton Corporation leverages its circuit protection integration to anchor premium push button sales to Japanese automotive OEMs. Honeywell International Inc. competes through hazardous-location certification depth, sustaining strong positioning in Australian energy sector installations.
Push buttons and signaling devices comprise electromechanical and capacitive interface components rated for IP65-IP67 ingress protection, designed to transmit operator commands and status alerts in noisy industrial environments. Panel-mounted configurations dominate volume, while capacitive technology captures expanding share from mechanical alternatives in hygiene-critical food processing applications across Southeast Asia. Audio alarms and indicator lights concentrate margin pools where explosion-proof certifications apply, particularly across India's refining sector and South Korean shipbuilding.
China's MIIT enforces GB standards for industrial control device reliability, while Japan's METI administers JIS certification for factory automation interfaces. Australia's Work Health and Safety regulations mandate audible signaling above ambient noise thresholds, shaping product specification requirements. India's BIS compulsory registration scheme for electronic components tightens market access for uncertified imports. Stakeholders must monitor divergence between China's GB evolution and IEC harmonization efforts to avoid compliance fragmentation across multi-country supply contracts.
Market Dynamics
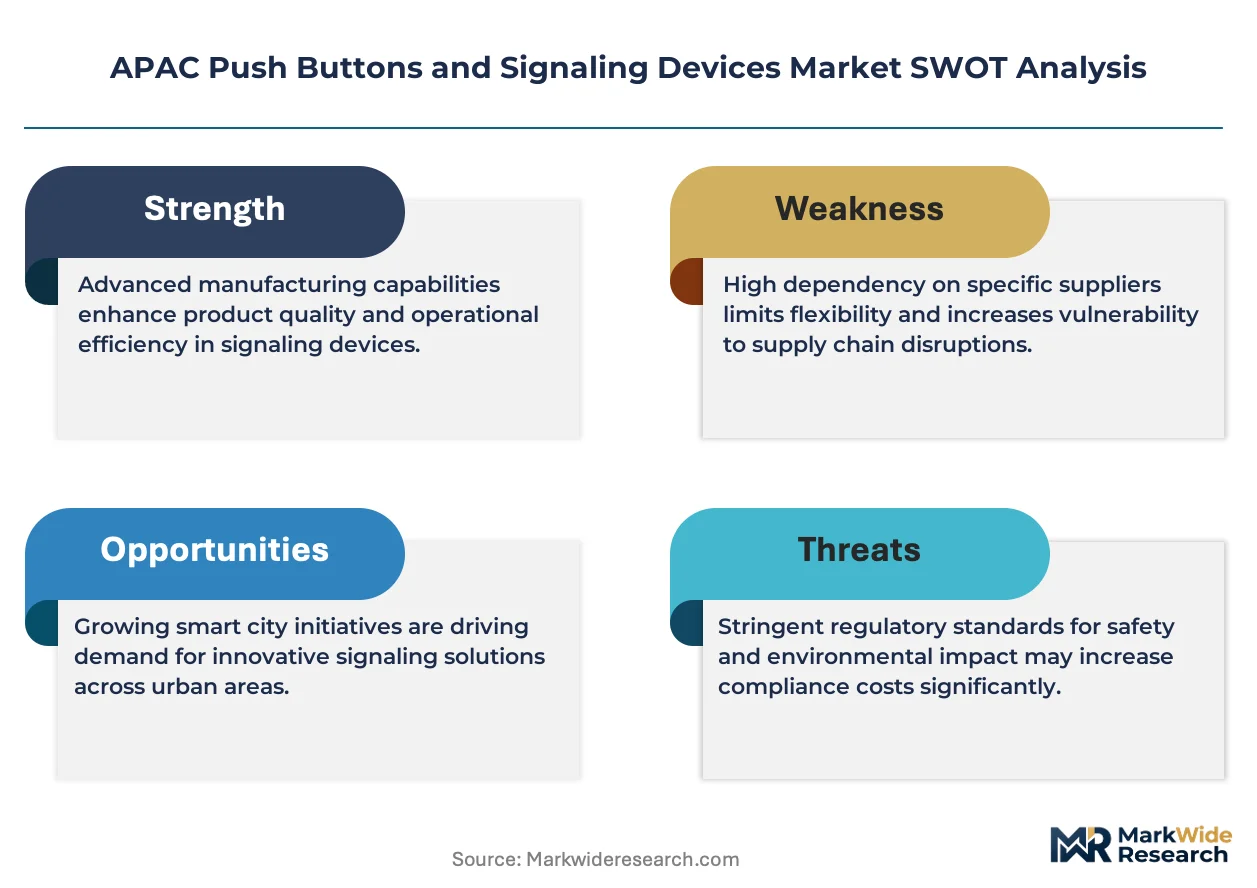
China's MIIT safety certification tightening is compressing supplier margins while accelerating consolidation among uncertified component manufacturers across the eastern coastal belt.
Growth Catalysts
- Automotive Electrification:Battery assembly lines in South Korea's Gyeonggi Province are ordering explosion-proof signaling arrays for cleanroom welding stations. Korean shipbuilders are retrofitting legacy vessels with IP67-rated marine indicator systems.
- MIIT GB Standards Enforcement:China's tightened industrial control device reliability requirements are forcing domestic manufacturers to upgrade electromechanical switch portfolios, creating replacement demand across Shenzhen and Dongguan supplier clusters.
- Food Processing Hygiene Mandates:Capacitive touch interfaces are displacing mechanical push buttons in Thai and Vietnamese seafood processing facilities where washdown protocols exceed IP65 thresholds.
Market Restraints
- Copper and Silver Contact Volatility:Electromechanical switch manufacturers face margin pressure from precious metal price swings affecting contact reliability specifications in high-cycle applications.
- Import Dependency for Semiconductor Components:Capacitive interface producers in India and Southeast Asia remain tethered to Taiwanese and South Korean chip supply, exposing lead time risk.
- Mechanical Switch Obsolescence Curve:Long service life of legacy panel-mounted indicators in established Japanese automotive plants slows replacement cycles despite new technology availability.
Strategic Opportunities
- Indian Refining Sector Modernization:Bharat Petroleum and Indian Oil Corporation expansion projects require ATEX-certified audible alarms and visual indicators for hazardous zone classification.
- Indonesian Palm Oil Automation:Remote plantation processing facilities present untapped demand for wireless signaling devices and battery-backed indicator systems.
- Dual Certification Convergence:Manufacturers harmonizing China's GB standards with IEC frameworks can streamline multi-country supply contracts for regional automotive tier-one suppliers.
Industry Challenges
- ATEX and IECEx Certification Backlogs:Testing laboratory capacity constraints in Singapore and Australia are extending time-to-market for explosion-proof product launches by four to six months.
- Legacy System Integration Complexity:Food processors in Malaysia and Thailand struggle to retrofit capacitive interfaces into existing PLC architectures without full control panel replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Push Buttons and Signaling Devices Market |
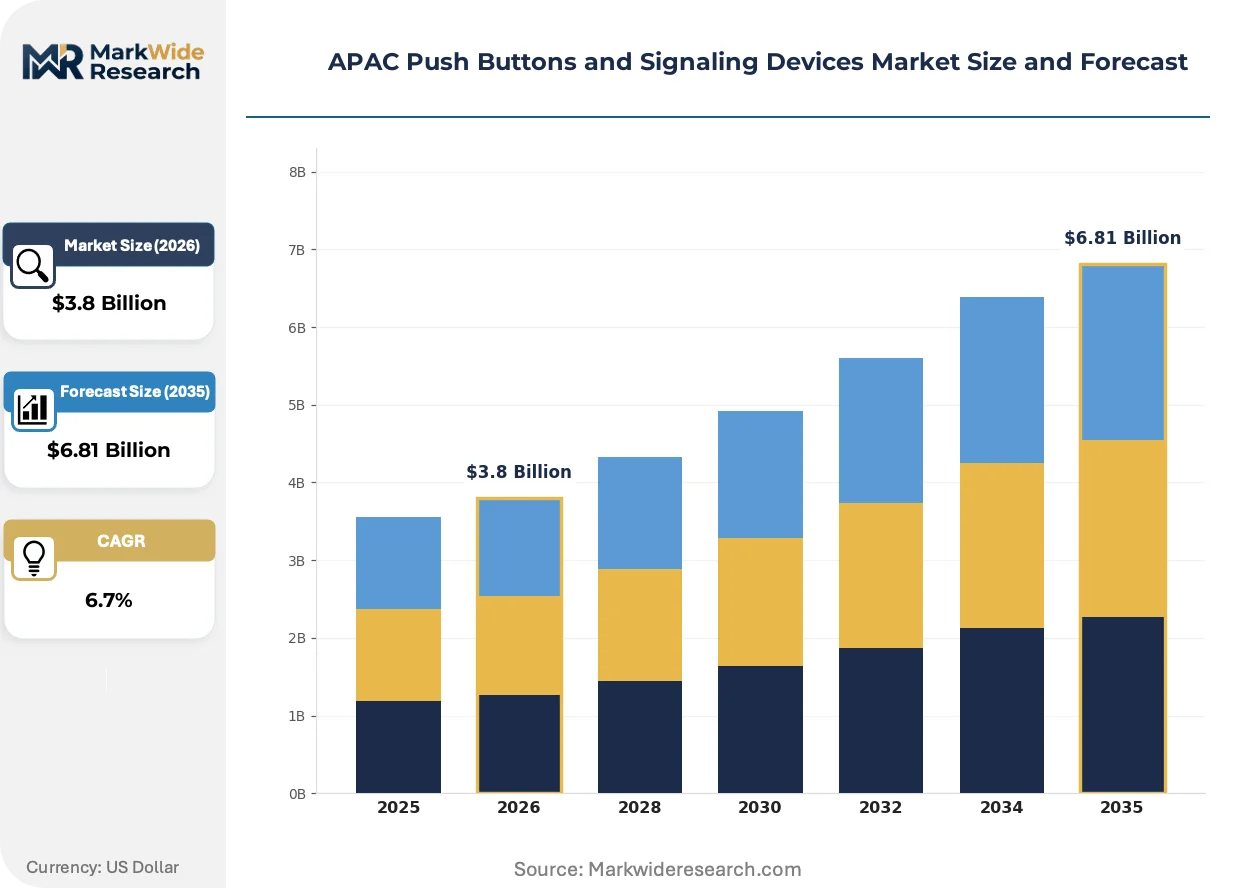
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indicator Lights, Push Buttons, Switches, Audio Alarms Technology: Mechanical, Capacitive, Electromechanical, Optical End User: Manufacturing, Automotive Suppliers, Aerospace, Energy Sector Installation Type: Panel Mounted, Handheld, Wall Mounted, Portable |
| Companies Covered | Eaton Corporation, Honeywell International Inc., ABB Ltd, Rockwell Automation, Federal Signal Corporation, Schneider Electric SE, Littelfuse, Patlite Corporation, Siemens AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Push Buttons and Signaling Devices Market Strategic Shifts
Interface technology is bifurcating between premium capacitive adoption in hygiene-critical sectors and cost-optimized electromechanical persistence in heavy industrial applications.
Capacitive touch technology is absorbing share from mechanical alternatives in Southeast Asian food processing and pharmaceutical cleanrooms where sealed surfaces eliminate contamination vectors. Thai and Vietnamese facility managers are specifying glass-fronted interfaces for washdown compliance. This transition is compressing mechanical switch margins in segments below IP67 requirements.
Australia's Work Health and Safety regulations now mandate audible signaling devices exceed ambient noise thresholds by ten decibels in mining and energy installations. Equipment specifiers in Western Australia's Pilbara region are retrofitting legacy visual-only systems with combined audio-visual units. The regulation is forcing distributors to clear non-compliant inventory ahead of enforcement deadlines.
Automotive tier-one suppliers in China and Japan are consolidating vendor lists around dual-certified manufacturers capable of delivering both GB-compliant and JIS-certified components from single production lines. Procurement teams at Denso and Bosch automotive divisions are reducing approved supplier counts by forty percent. This concentration is visible most acutely in Shanghai and Nagoya supplier qualification processes.
APAC Push Buttons and Signaling Devices Market Segmentation
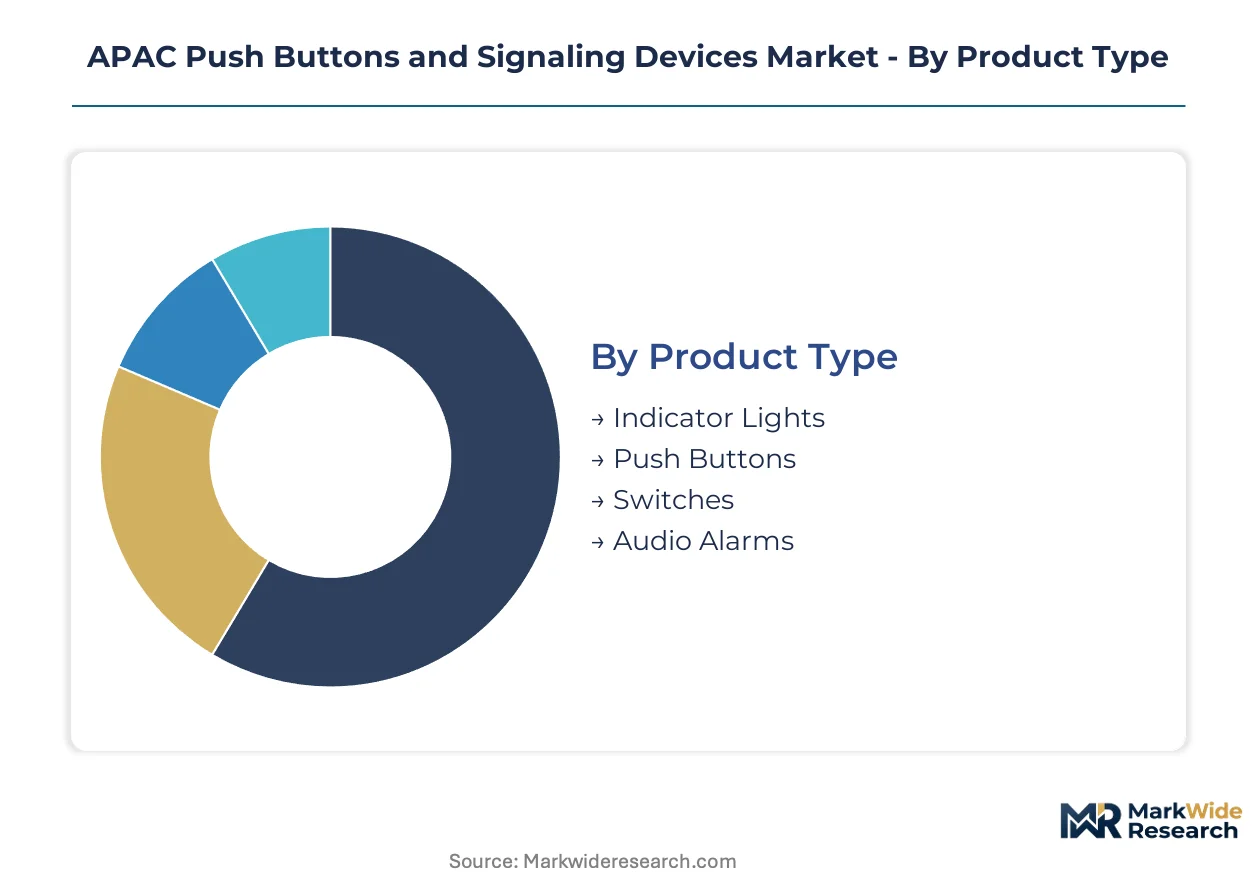
Segmentation in the APAC push buttons and signaling devices market reveals how technical specifications, installation constraints, and end-use environments shape procurement patterns across industrial automation. Product architecture and certification requirements vary sharply between heavy manufacturing installations and hygiene-critical food processing lines.
Product Type:
Customization intensity spans from commodity indicator lamps to engineered explosion-proof audio arrays, with standardization highest in basic visual signaling and lowest in hazardous-location certified systems.
- Push Buttons:Electromechanical and capacitive actuators rated for IP65-IP67 ingress protection transmit operator commands in noisy factory floors. China's automotive supplier clusters in Shanghai and Dongguan drive volume procurement of panel-mounted configurations with JIS certification for Japanese OEM integration.
- Indicator Lights:LED and incandescent status displays dominate panel-mounted installations across manufacturing automation lines. South Korean battery assembly facilities in Gyeonggi Province specify sealed glass-fronted variants for cleanroom welding stations where contamination control is paramount.
- Switches:Rotary, selector, and emergency stop configurations serve machinery control applications with long service life requirements.
- Audio Alarms:Piezoelectric and electromechanical sounders provide audible alerts in high-ambient-noise environments.
Most installed capacity flows through Indicator Lights. Expansion is steepest in Audio Alarms.
Technology:
Cost tiering separates mature electromechanical platforms from premium capacitive interfaces, with optical sensing occupying a narrow mid-band for specialized detection applications.
- Mechanical:Spring-return and maintained-contact switches with precious metal contacts deliver proven reliability in high-cycle automotive assembly applications. Legacy Japanese automotive plants retain these systems despite longer replacement intervals slowing upgrade adoption.
- Capacitive:Sealed glass or polymer touch surfaces eliminate physical actuators for washdown compliance in Thai and Vietnamese seafood processing facilities. METI safety guidelines and China's MIIT GB standards both address interface reliability for these hygiene-critical installations.
- Electromechanical:Hybrid architectures combining mechanical actuation with electronic signal conditioning bridge legacy and modern control systems.
- Optical:Infrared and laser-based presence detection enables non-contact signaling in explosive atmospheres.
Mechanical technology retains the largest installed base. Capacitive platforms are gaining share fastest in food and pharmaceutical segments.
End User:
Application environment dictates specification severity, with energy sector and aerospace procurement requiring ATEX/IECEx certification depth that manufacturing customers rarely demand.
- Manufacturing:General automation lines across China's eastern coastal belt consume standardized panel-mounted indicators and push buttons for PLC integration. MIIT GB standards enforcement is compressing supplier margins while forcing domestic manufacturers to upgrade reliability portfolios.
- Automotive Suppliers:Tier-one component manufacturers consolidate vendor lists around dual-certified producers capable of delivering GB-compliant and JIS-certified products from single production lines. Denso and Bosch procurement teams have reduced approved supplier counts substantially.
- Energy Sector:Australian mining and Indian refining operations mandate explosion-proof certifications with extended temperature ratings.
- Aerospace:MRO facilities and assembly plants require traceability documentation and extended qualification cycles.
Manufacturing accounts for the majority of unit volume. Automotive Suppliers show the steepest specification upgrade trajectory.
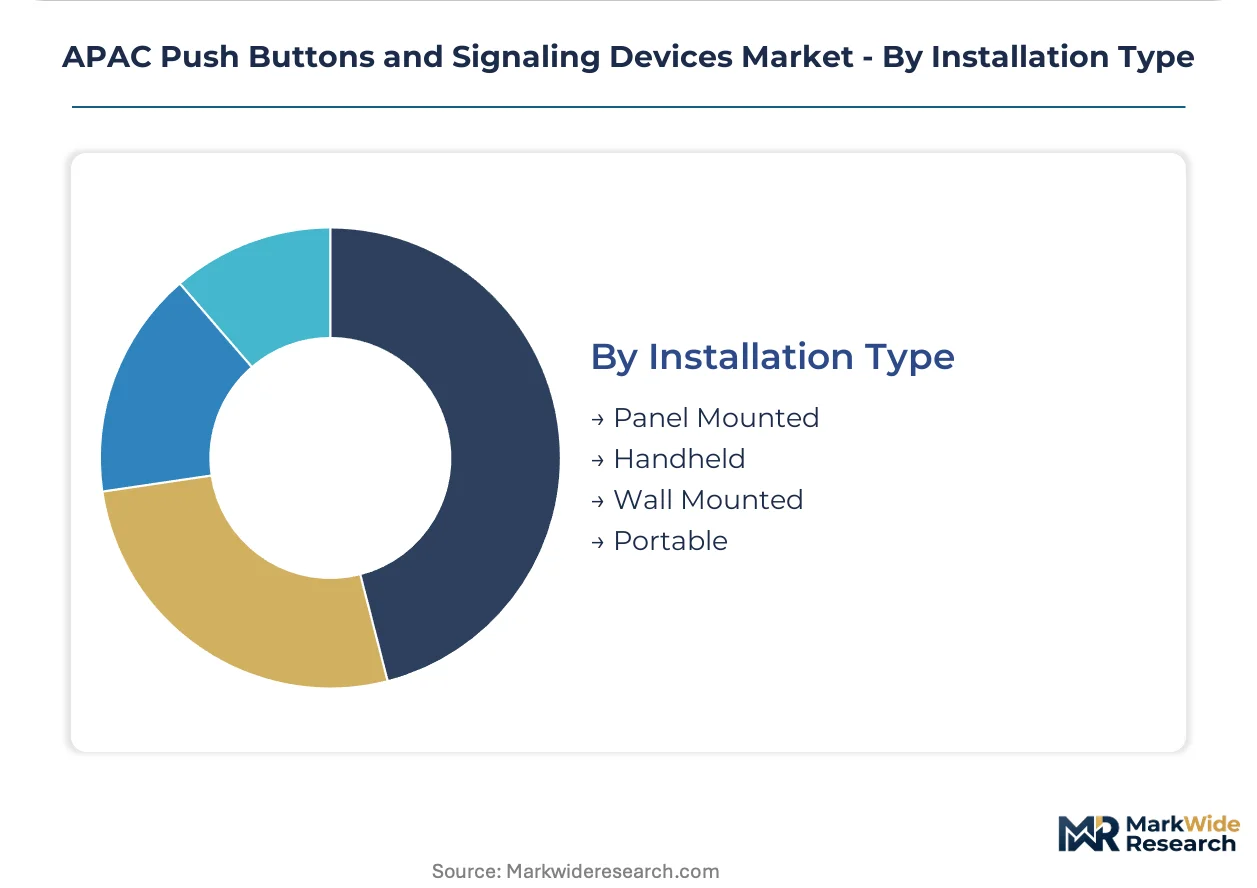
Installation Type:
Volume concentration favors fixed panel configurations, while portability premiums apply in remote Indonesian palm oil plantations and Australian mining camps lacking permanent infrastructure.
- Panel Mounted:Fixed-cutout installations dominate factory automation with standardized 22mm and 30mm diameters. Shenzhen and Dongguan supplier clusters specialize in high-volume production for China's electronics assembly plants.
- Handheld:Portable operator interfaces serve maintenance and commissioning applications with tethered or wireless connectivity.
- Wall Mounted:Enclosed stations provide distributed control points in large-scale process facilities.
- Portable:Battery-backed and wireless signaling devices address Indonesian palm oil processing facilities and remote Australian mining installations where fixed infrastructure is impractical.
Panel Mounted configurations handle most unit demand. Portable systems are expanding most quickly in Southeast Asian plantation automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern coastal manufacturing belt anchors regional demand for panel-mounted indicator lights and electromechanical switches, with automotive supplier clusters and electronics assembly plants driving procurement volume across Shenzhen, Dongguan, and Shanghai industrial zones.
China
MIIT safety certification tightening for industrial control equipment is forcing domestic manufacturers to upgrade electromechanical switch portfolios. GB standards enforcement creates replacement demand across Shenzhen and Dongguan supplier clusters, where electronics assembly plants and automotive tier-one operations concentrate bulk procurement of signaling devices.
Japan
Legacy automotive plants in Nagoya and Toyota City retain long-service-life mechanical switch installations, slowing replacement cycles despite new technology availability. METI administers JIS certification for factory automation interfaces, with Denso and Bosch procurement teams reducing approved supplier counts substantially around dual-certified producers.
South Korea
Battery assembly lines in Gyeonggi Province order explosion-proof signaling arrays for cleanroom welding stations. Korean shipbuilders retrofit legacy vessels with IP67-rated marine indicator systems. MFDS guidelines intersect with industrial safety protocols in pharmaceutical manufacturing zones around Seoul.
India
Bharat Petroleum and Indian Oil Corporation expansion projects require ATEX-certified audible alarms and visual indicators for hazardous zone classification. BIS compulsory registration scheme for electronic components tightens market access for uncertified imports, compressing lead times for capacitive interface producers tethered to Taiwanese chip supply.
Australia
Mining and energy installations in Western Australia's Pilbara region retrofit legacy visual-only systems with combined audio-visual units under Work Health and Safety regulations mandating audible signaling exceed ambient noise thresholds. Testing laboratory capacity constraints in Singapore and Australia extend time-to-market for explosion-proof product launches.
APAC Push Buttons and Signaling Devices Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers harmonize certification portfolios across GB and IEC frameworks. The vendor base concentrates around three tiers: diversified industrial conglomerates with circuit protection integration, hazardous-location certification specialists, and regional component fabricators serving domestic automotive clusters. Two strategic archetypes define positioning: dual-certified producers capable of delivering GB-compliant and JIS-certified products from single production lines, and explosion-proof specialists anchoring premium pricing in energy sector installations. Geographic expansion into Southeast Asian food processing and technology licensing for capacitive interface production represent the dominant competitive vectors.
Within the diversified industrial tier, Eaton Corporation and Honeywell International Inc. occupy positions shaped by their circuit protection and hazardous-location certification depth respectively. ABB Ltd anchors the automation-integrated segment, exemplifying the archetype of manufacturers consolidating vendor lists around dual-certified production capabilities. These three entities represent the competitive concentration visible in Shanghai and Nagoya supplier qualification processes, where procurement teams prioritize streamlined multi-country supply contracts over fragmented sourcing arrangements.
| Leading Market Players |
|---|
| Eaton Corporation |
| Honeywell International Inc. |
| ABB Ltd |
| Rockwell Automation |
| Federal Signal Corporation |
| Schneider Electric SE |
| Littelfuse |
| Patlite Corporation |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ATEX-certified explosion-proof arrays and commodity panel-mounted indicators manifests in both margin structures and supplier geography. Premium-tier producers anchor pricing power through hazardous-location certification depth, while cost-optimized electromechanical switches compete on volume scale across China's eastern coastal manufacturing belt.
Pricing Analysis
Input-cost pass-through from copper and silver contact volatility compresses margins for electromechanical switch manufacturers serving high-cycle automotive applications. Three-tier pricing structure across premium certified, standard industrial, and economy unbranded levels reflects divergence in certification investment and after-sales service bundling. Pricing pressure intensifies in the commodity tier as Chinese domestic manufacturers upgrade GB-compliant portfolios under MIIT enforcement. Automotive tier-one suppliers exhibit lowest price sensitivity, prioritizing dual-certification reliability over unit cost.
Supply Chain Analysis
Freight cost differentials between Taiwanese semiconductor chip sources and Southeast Asian capacitive interface assembly plants shape regional production economics. Supply concentration centers on China for electromechanical components, South Korea for explosion-proof marine systems, and Japan for precision mechanical switches. Raw material dependencies span copper-silver contact alloys, LED emitter substrates, and polymer sealing compounds. Single-source vulnerability in Taiwanese chip supply exposes lead time risk for capacitive producers. Distribution runs through authorized industrial distributors serving automotive clusters and direct OEM contracts for energy sector installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from Australia's Work Health and Safety retrofit mandates against India's BIS import restrictions, creating divergent pricing environments for certified versus uncertified signaling devices.
For Market Incumbents: Acquire certification testing capacity in Singapore and Australia to compress ATEX/IECEx time-to-market delays. Consolidate vendor qualification processes around dual-certified production lines serving Denso and Bosch procurement teams. Defensive positioning requires backward integration into semiconductor component sourcing to mitigate Taiwanese chip supply vulnerability. Capacity expansion in Vietnam addresses food processing hygiene mandate growth while hedging China margin compression. For New Entrants and Emerging Players: BIS compulsory registration in India opens a window for domestic assembly partnerships bypassing import dependency. Indonesian palm oil plantation automation presents the most penetrable white-space for battery-backed wireless signaling devices. Thai seafood processing facilities offer entry through capacitive touch retrofit specifications exceeding IP65 thresholds. Go-to-market execution should anchor on distributor partnerships with industrial automation specialists rather than direct OEM pursuit. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap dual-certified manufacturers capable of serving both GB and JIS standards from unified production. Long-term viability hinges on certification portfolio breadth across the five-to-ten year regulatory harmonization window. Acquisition targets should display established relationships with automotive tier-one procurement committees. The signal to watch is MIIT GB standard evolution toward IEC convergence, which would compress multi-country supply contract complexity and reward pre-positioned certification assets.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Harmonization Investment | Streamlines multi-country supply contracts for Denso and Bosch procurement teams. |
| Capacitive Interface Production Scale-Up | Captures Thai and Vietnamese food processing washdown compliance mandates. |
| Backward Integration into Contact Materials | Insulates margin from copper-silver price volatility in high-cycle applications. |
| Wireless Signaling Device Development | Addresses Indonesian palm oil plantation infrastructure gaps. |
| Testing Laboratory Joint Venture | Resolves Singapore and Australia ATEX/IECEx capacity constraints. |
Study Parameters
Bottom-up automotive and energy sector modeling reconciled against top-down component manufacturer shipment tracking forms the analytical core. Primary interviews with plant engineers, OEM procurement managers, aftermarket service heads, and industrial distributors combined with secondary validation from MIIT GB standard filings, JIS certification registries, and customs trade data. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation accuracy.
Historical trendline analysis of electromechanical switch replacement cycles and capacitive interface adoption curves informed projection frameworks. Segmentation dimensions span product architecture, certification tier, end-use environment, and regional regulatory cluster. CAGRs derive from installed base turnover rates and specification upgrade trajectories. Forecast inputs incorporate battery assembly line expansion in Gyeonggi Province and Australian mining retrofit mandates.
Revisions become necessary when semiconductor supply disruptions extend lead times beyond contractual penalties or when MIIT accelerates GB standard enforcement timelines. Forecasts reflect assumptions about certification harmonization progress and precious metal price stability. A model refresh is warranted upon material change in automotive electrification capital expenditure commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Differential Pressure Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Optical Switches Market
Switches
North America Medium Voltage Switchgear Market
Switches
Campus Switches Market
Switches
Europe Low Voltage Switchgear Market
Switches
Fusible Switches Market
Switches
Vibration Level Switch Market
Switches
Intelligent Power Switches Market
Switches
Cross Point Switch Market
Switches
Analog Switches Market
Switches
Global Switchgear Market
Switches
United States X by Wire Systems Market
Switches
Carrier Router Switch Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Global Electrical Switches Market