
 Outsourced Semiconductor Assembly and Testing Market | 2026-2036
Outsourced Semiconductor Assembly and Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourced Semiconductor Assembly and Testing Market Analysis
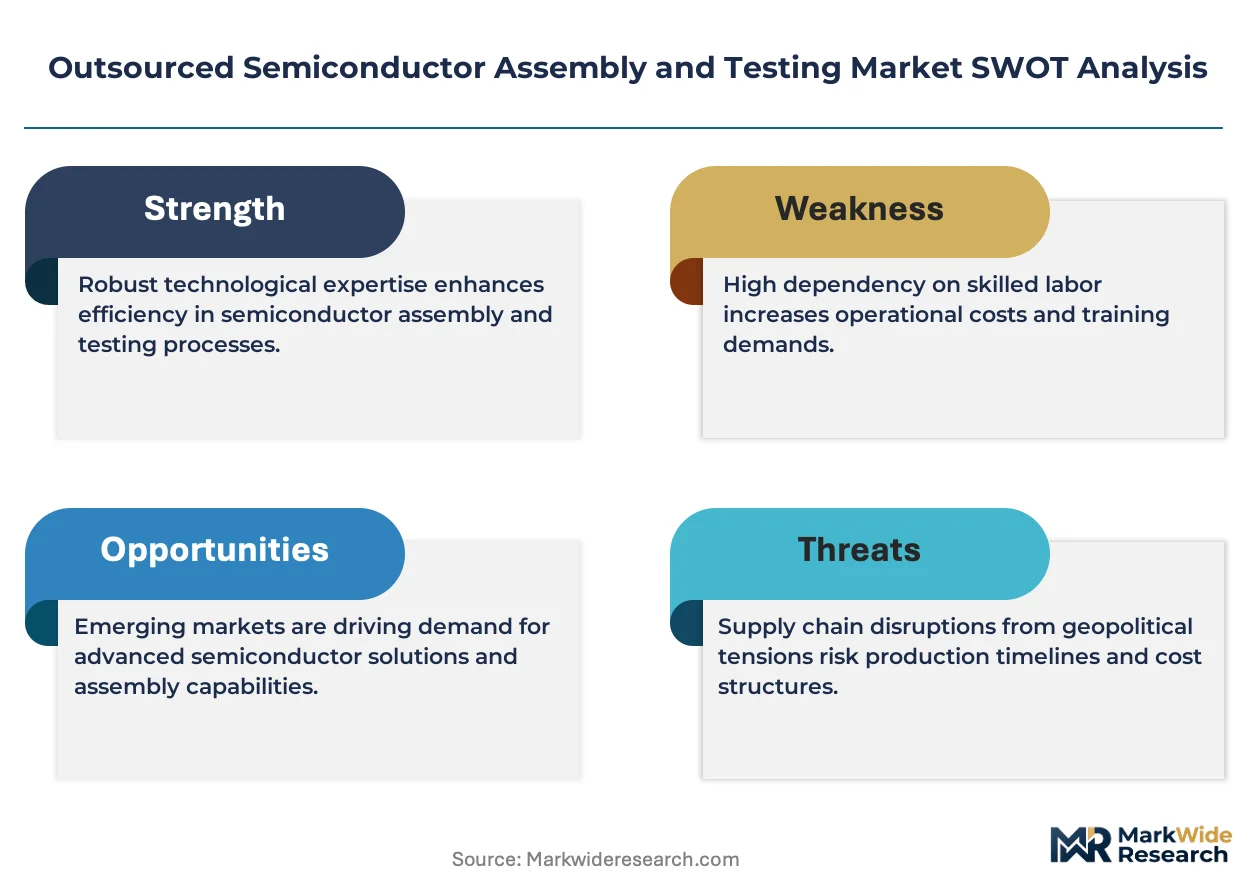
Asset-light foundry partnerships and equipment leasing programs is reconfiguring capital barriers for mid-tier OSAT entrants. ASE Technology Holding leverages its Hsinchu-based mega-site to dominate advanced fan-out wafer-level packaging. Amkor Technology anchors North American automotive qualification pathways through its Chandler, Arizona operations. JCET Group specializes in heterogeneous integration for Chinese fabless designers.
Outsourced semiconductor assembly and testing encompasses die attach, wire bonding, flip chip interconnect, final test, and burn-in services performed by third-party providers on silicon wafers and singulated dies. Wire bonding remains the workhorse interconnect method for cost-sensitive consumer ICs, though flip chip and TSV technologies command premium pricing in high-performance computing and AI accelerator packages. Packaging services capture the largest value pool within the service type dimension, while RF devices and sensors represent the fastest-expanding product categories driven by 5G infrastructure and IoT deployment.
FDA medical device semiconductor guidelines, EPA hazardous substance handling rules, and China's GB standards for electronic component reliability collectively shape qualification timelines and facility certification requirements. The EU F-Gas Regulation and REACH chemical restrictions further constrain molding compound and underfill material selections for European-bound shipments. Stakeholders must monitor how export control classifications and carbon border adjustments reshape geographic sourcing decisions for advanced packaging capacity.
Market Dynamics
Automotive electrification is compressing packaging qualification timelines while multiplying die counts per vehicle, forcing OSATs to reconfigure capacity allocation between consumer and mobility segments. This demand rotation is reshaping capital deployment priorities across the assembly and testing value chain.
Growth Catalysts
- China's Dual Carbon Mandates:MIIT emissions targets and NMPA semiconductor reliability standards are accelerating adoption of advanced thermal management packages in industrial and automotive applications.
- Heterogeneous Integration Demand:AI accelerator architects require chiplet-based assembly combining logic, memory, and photonics in single substrates, expanding substrate-level packaging services.
- 5G Infrastructure Deployment:RF front-end module complexity is driving flip chip and system-in-package volumes for base station and smartphone filter assemblies.
Market Restraints
- Equipment Lead Time Volatility:Advanced packaging tools from lithography to thermocompression bonders face 12-18 month delivery windows, constraining capacity expansion timing.
- Substrate Supply Concentration:ABF substrate production concentrates in Japan and Taiwan, creating input bottlenecks for high-density fan-out wafer-level packaging lines.
- REACH Chemical Restrictions:EU molding compound and underfill material constraints limit European-bound shipment qualification pathways for legacy package types.
Strategic Opportunities
- India's Semiconductor Ecosystem:PLI scheme incentives and Gujarat-Vedanta-Foxconn project momentum are attracting OSAT joint ventures for domestic fabless servicing.
- Medical Device Convergence:FDA semiconductor guidelines for implantable devices are opening specialized hermetic packaging and extended burn-in service lanes.
- Photonics-Electronics Hybrid Assembly:Silicon photonics transceivers require precision optical-electrical interconnect, creating premium service tiers distinct from standard IC packaging.
Industry Challenges
- Process Engineer Scarcity:Flip chip and TSV process optimization expertise concentrates among senior practitioners in Taiwan and South Korea, limiting knowledge transfer to emerging facilities.
- Automotive Qualification Duration:AEC-Q100 and AEC-Q104 certification timelines extend 18-24 months, locking capacity commitments before volume materializes.
- Cross-Border IP Protection:Advanced packaging know-how embedded in process recipes faces misappropriation risks during multi-site manufacturing coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outsourced Semiconductor Assembly and Testing Market |
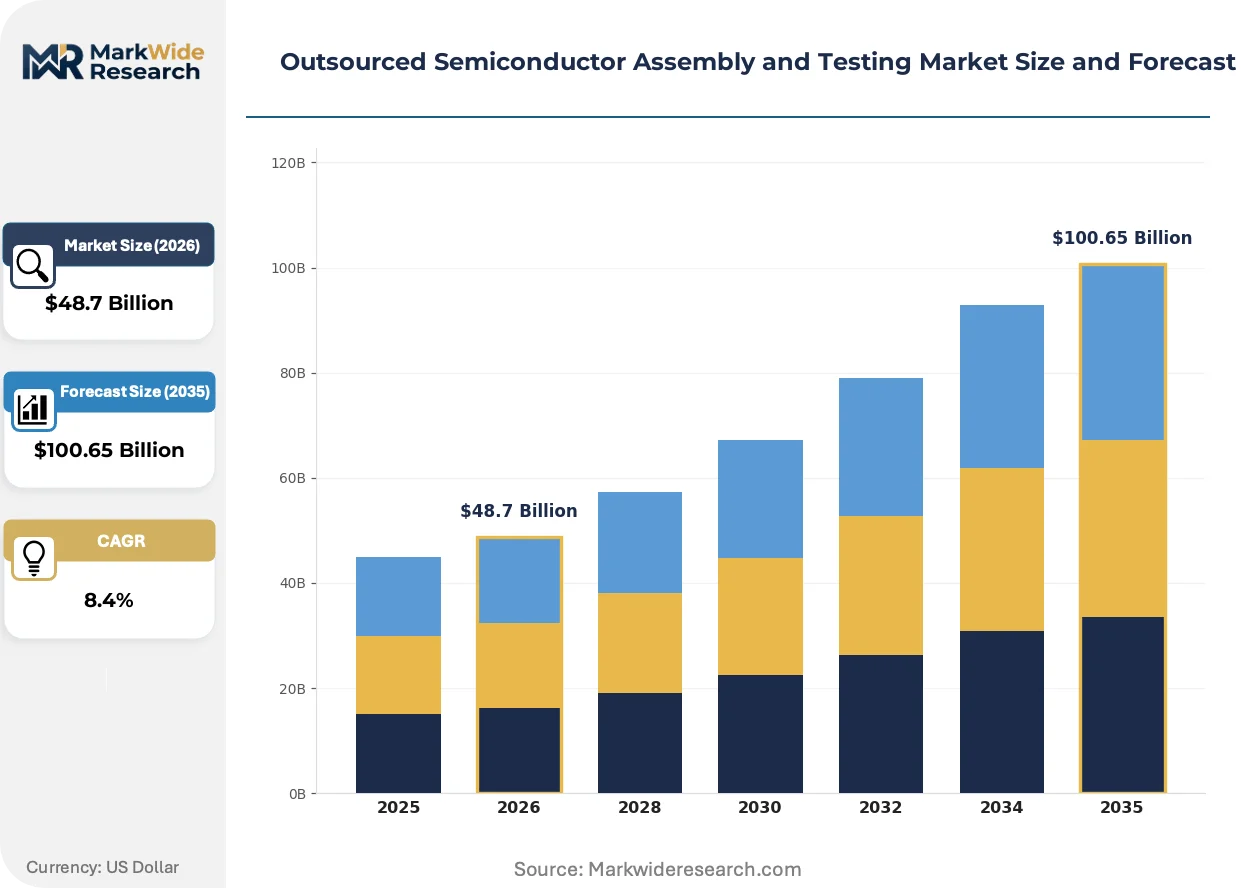
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Assembly, Testing, Packaging, Quality Assurance Technology: Wire Bonding, Flip Chip, Surface Mount Technology, TSV End User: Consumer Electronics, Automotive, Industrial, Telecommunications Product Type: ICs, MEMS, Sensors, RF Devices |
| Companies Covered | ASE Technology Holding Co. Ltd, Amkor Technology Inc., Powertech Technology Inc., ChipMOS Technologies Inc., King Yuan Electronics Co. Ltd, JCET Group Co. Ltd, Tongfu Microelectronics Co. Ltd, UTAC Holdings Ltd, Formosa Advanced Technologies Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourced Semiconductor Assembly and Testing Market Emerging Trajectories
Packaging technology trajectories are compressing interconnect pitch while expanding functional integration scope, redefining where value capture occurs in the semiconductor supply chain.
Hybrid bonding is collapsing the thermal and electrical gap between stacked dies, enabling memory-on-logic configurations for AI training accelerators. Hyperscalers and GPU architects are qualifying copper-to-copper interconnect at sub-10 micron pitch, displacing microbump architectures in high-bandwidth memory applications. This pitch compression is collapsing the traditional boundary between front-end fabrication and back-end assembly.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon use in plasma cleaning and etching processes, forcing equipment retrofits and alternative chemistry validation. OSATs serving European automotive and industrial customers must document fluorinated gas substitution pathways to maintain shipment eligibility. German and French-bound production lines are prioritizing fluorine-free plasma technologies ahead of regulatory deadlines.
Consolidated procurement through foundry-direct packaging partnerships is displacing traditional fabless-OSAT arm's length contracting. Apple, NVIDIA, and AMD are negotiating captive capacity within foundry-OSAT joint ventures, compressing merchant OSAT pricing leverage. This channel restructuring is most pronounced in Taiwan and Arizona, where TSMC-Arizona and Intel Foundry Services are integrating assembly into wafer supply agreements.
Outsourced Semiconductor Assembly and Testing Market Segmentation
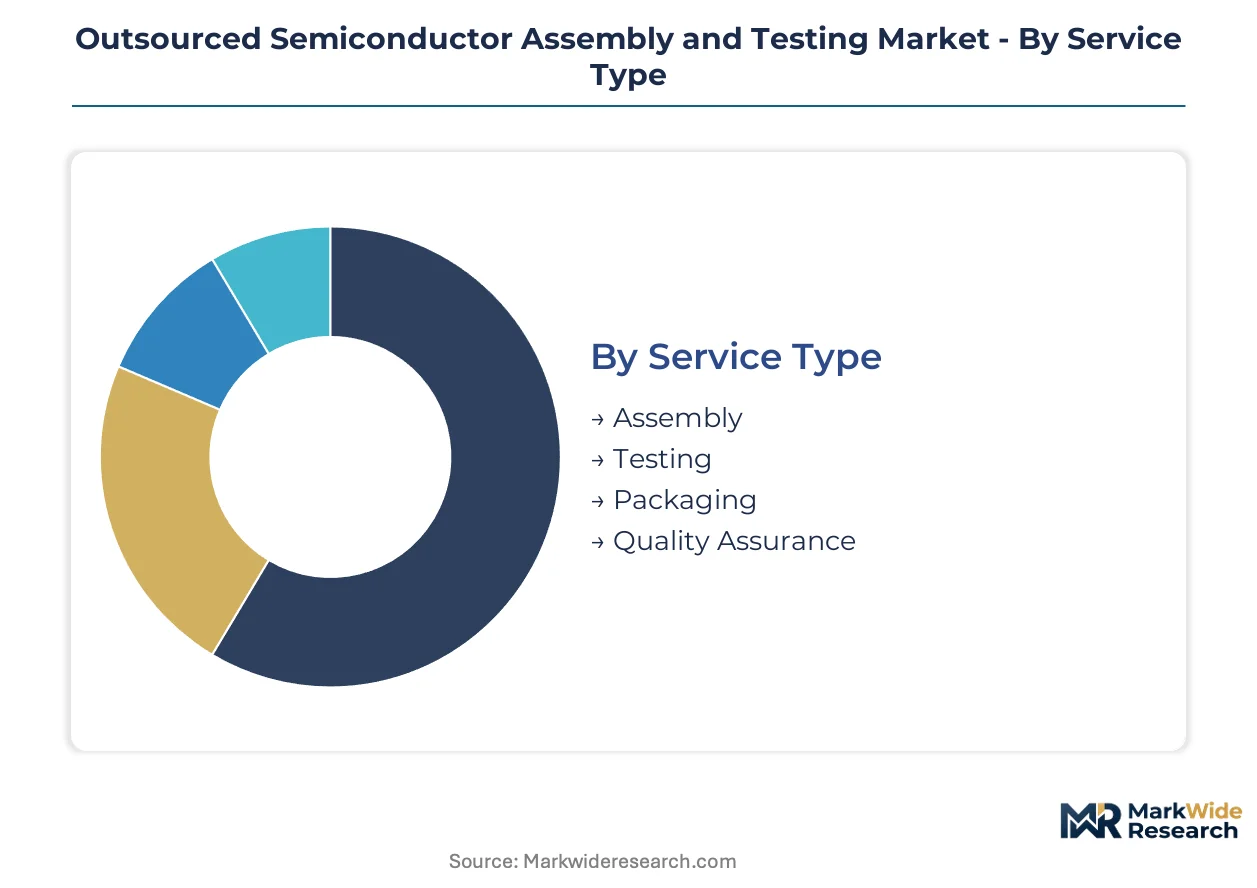
OSAT market segmentation reveals how packaging complexity, interconnect technology, and end-use reliability requirements stratify service pricing and capacity allocation. Each dimension captures distinct competitive dynamics that reshape vendor positioning across the assembly and testing value chain.
Service Type:
Cost tier differentiation separates commoditized high-volume services from premium qualification-intensive offerings.
- Assembly:Die attach, wire bonding, and flip chip interconnect operations constitute the foundational service layer. Automotive electrification in Germany and Japan is compressing qualification timelines while multiplying die counts per powertrain module.
- Testing:Final test, wafer probe, and burn-in services verify electrical performance and reliability specifications. Demand concentrates in Taiwan's Hsinchu cluster where ASE Technology Holding and Powertech Technology anchor advanced testing capacity for AI accelerators.
- Packaging:Encapsulation, molding, and thermal management integration protect die functionality. China's MIIT dual carbon mandates and NMPA semiconductor reliability standards are tightening thermal package specifications for industrial applications.
- Quality Assurance:Statistical process control, failure analysis, and traceability documentation ensure shipment compliance. FDA medical device semiconductor guidelines in the US and EU MDR requirements in Europe extend qualification pathways for implantable device packaging.
Assembly commands the established base. The steepest expansion runs through Testing.
Technology:
Application requirements for electrical performance, thermal dissipation, and form factor miniaturization dictate interconnect selection.
- Wire Bonding:Gold and copper wire interconnect remains dominant for cost-sensitive consumer ICs and legacy automotive packages. Volume concentrates in Malaysia and Thailand facilities serving ASEAN fabless designers.
- Flip Chip:Solder bump and copper pillar interconnect enable higher I/O density and superior electrical performance. AI accelerator architects at NVIDIA and AMD are qualifying flip chip configurations for HBM integration in Taiwan and Arizona.
- Surface Mount Technology:Passive component and small-outline package assembly addresses board-level integration requirements. 5G infrastructure deployment across South Korea and Finland is driving RF front-end module volumes.
- TSV:Through-silicon via technology enables vertical die stacking for memory-on-logic configurations. Heterogeneous integration demand from hyperscalers is expanding substrate-level packaging services in Japan and Taiwan.
Wire Bonding retains volume leadership. Flip Chip is climbing the fastest.
End User:
Customer type reliability requirements and qualification duration create distinct margin profiles across vertical segments.
- Consumer Electronics:Smartphones, wearables, and computing devices demand high-volume, cost-optimized packaging. Assembly volumes concentrate in China and Vietnam facilities serving Apple and Samsung supply chains.
- Automotive:Powertrain, ADAS, and infotainment systems require AEC-Q100 and AEC-Q104 certified packages. NHTSA safety mandates in the US and KBA type approval in Germany extend qualification timelines to 18-24 months.
- Industrial:Automation controllers, power electronics, and sensor modules need extended temperature range and hermetic sealing. China's GB standards for electronic component reliability shape facility certification requirements.
- Telecommunications:Base station infrastructure and optical networking equipment drive RF and photonics packaging complexity. 5G deployment across India under PLI scheme incentives and Japan's METI connectivity targets are expanding filter assembly volumes.
Consumer Electronics maintains the revenue base. Automotive is gaining share fastest.
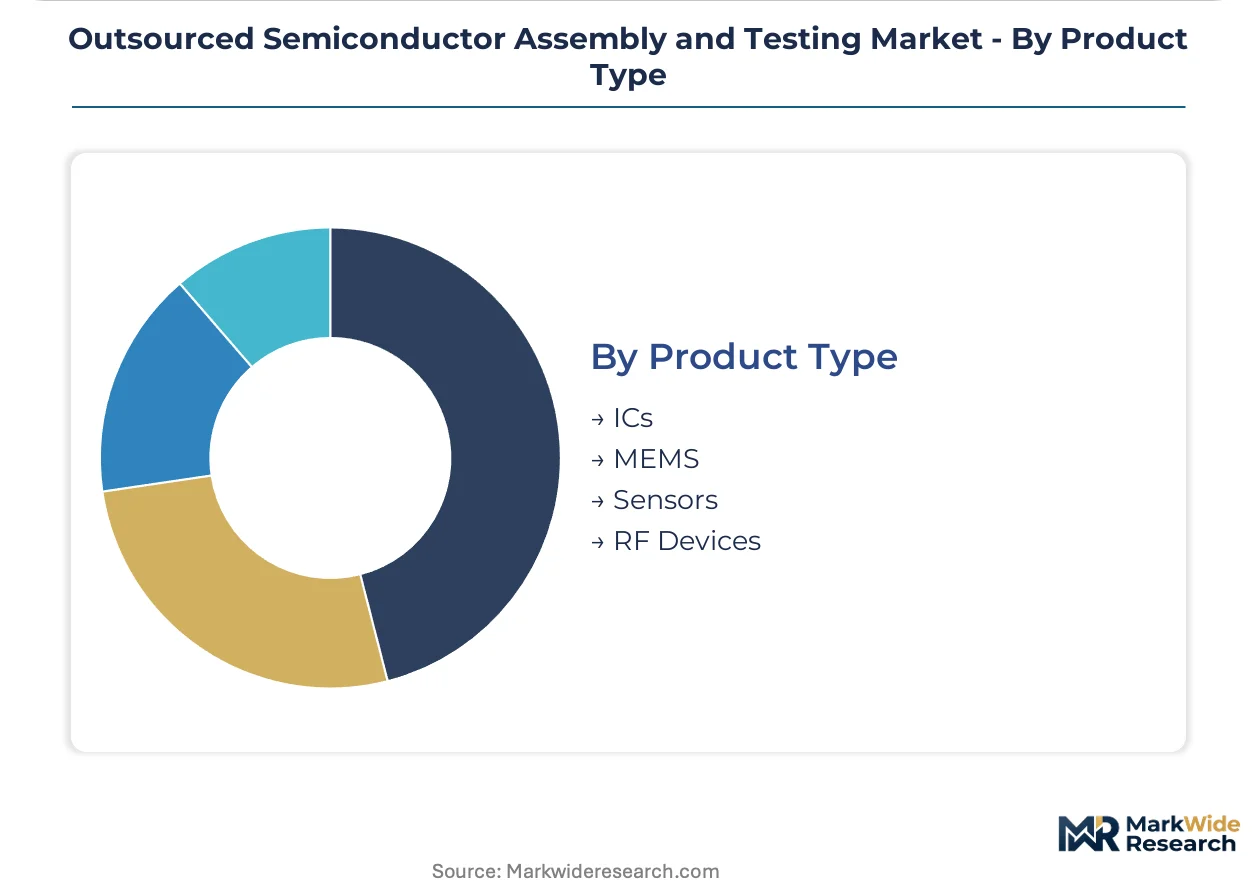
Product Type:
Maturity and supply concentration determine competitive intensity across device categories.
- ICs:Logic, memory, and analog integrated circuits represent the core packaging volume. Foundry-direct partnerships at TSMC-Arizona and Intel Foundry Services are displacing traditional fabless-OSAT arm's length contracting.
- MEMS:Microelectromechanical systems require specialized wafer-level packaging and cavity sealing. Automotive pressure sensors and consumer motion sensors drive qualification diversity across Bosch and STMicroelectronics supply chains.
- Sensors:Environmental, biometric, and position sensors need miniaturized packages with exposed sensing elements. IoT deployment in smart cities across Singapore and Barcelona is expanding environmental sensor volumes.
- RF Devices:Filters, amplifiers, and antenna switch modules demand tight tolerance assembly for signal integrity. 5G mmWave complexity in South Korea and US FCC spectrum allocations are driving flip chip and system-in-package adoption.
ICs anchor established revenue. RF Devices show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSAT capacity expansion tracks semiconductor fabrication investments, creating regional trade imbalances where packaging lags wafer output. Taiwan maintains substantial export surplus in advanced assembly services, while the United States and Europe import specialized packaging to support domestic fabless design houses.
Taiwan
Hsinchu Science Park anchors the world's densest advanced packaging cluster, serving AI accelerator and high-bandwidth memory demand from NVIDIA and AMD. MIIT dual carbon goals in neighboring China indirectly tighten thermal management specifications for cross-strait shipments. ASE Technology Holding and Powertech Technology operate mega-sites that dominate fan-out wafer-level packaging capacity.
China
JCET Group and Tongfu Microelectronics scale heterogeneous integration capacity for domestic fabless designers in Jiangsu and Anhui provinces. NMPA semiconductor reliability mandates and GB standards for electronic component certification extend qualification timelines for automotive-bound production. Yangtze River Delta cities cluster substrate-level packaging investments targeting industrial controller applications.
United States
Amkor Technology's Chandler, Arizona facility anchors North American automotive qualification pathways for AEC-Q100 and AEC-Q104 certified packages. NHTSA safety mandates and EPA hazardous substance handling rules shape facility certification for powertrain semiconductor shipments. Southwestern states concentrate federal CHIPS Act-funded packaging investments.
South Korea
Flip chip and TSV process expertise concentrates in senior engineering talent pools serving Samsung and SK hynix supply chains. MFDS medical device guidelines and METI-influenced automotive standards create dual qualification pressures for Seoul-based OSAT operations. Busan-Ulsan corridor hosts memory-on-logic packaging capacity for AI training accelerators.
Japan
ABF substrate production concentrates in Nagoya and Osaka prefectures, creating input bottlenecks for high-density fan-out wafer-level packaging lines serving global OSATs. METI connectivity targets for 5G infrastructure expand RF front-end module assembly volumes. JIS standards for electronic component reliability shape automotive semiconductor packaging specifications.
Outsourced Semiconductor Assembly and Testing Market Vendor Landscape
On the supply side, the industry is consolidating around mega-site operators with captive advanced packaging capacity. Tiered competitive positioning separates premium qualification-intensive automotive and medical device specialists from commodity consumer electronics assemblers. Two strategic archetypes dominate: integrated foundry-OSAT joint ventures and independent merchant packaging houses. Capacity expansion and strategic partnerships represent the dominant competitive vectors as equipment lead times stretch to 18 months.
Within the integrated tier, ASE Technology Holding Co. Ltd exemplifies the mega-site operator archetype through its Hsinchu-based concentration of fan-out wafer-level capacity. Amkor Technology Inc. occupies a position representing North American automotive qualification specialization. JCET Group Co. Ltd anchors the China-based heterogeneous integration segment serving domestic fabless designers.
| Leading Market Players |
|---|
| ASE Technology Holding Co. Ltd |
| Amkor Technology Inc. |
| Powertech Technology Inc. |
| ChipMOS Technologies Inc. |
| King Yuan Electronics Co. Ltd |
| JCET Group Co. Ltd |
| Tongfu Microelectronics Co. Ltd |
| UTAC Holdings Ltd |
| Formosa Advanced Technologies Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Taiwan's Hsinchu Science Park cluster compresses pricing leverage for automotive qualification-intensive packages while forcing buyers into longer-term capacity reservation contracts. This utilization squeeze transmits through substrate supply bottlenecks and equipment lead time volatility, reshaping how OSATs structure pricing tiers and procurement commitments across the assembly value chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across AEC-Q100 certification grade, volume scale, and geographic delivery cost. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified fan-out wafer-level packaging from commodity wire bonding services. Pricing pressure stems from foundry-direct packaging partnerships compressing merchant OSAT margins. Consumer electronics fabless designers exhibit highest price sensitivity; medical device OEMs with FDA implantable guidelines show lowest.
Supply Chain Analysis
Export control classifications restricting advanced lithography and thermocompression bonder flows constrain capacity expansion timing across Taiwan, South Korea, and the United States. ABF substrate production concentrates in Japan and Taiwan; molding compounds face REACH chemical restrictions for EU-bound shipments. Single-source vulnerability runs through substrate-level packaging inputs. Distribution runs through foundry-OSAT joint ventures and merchant house arm's length contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through foundry-direct packaging partnerships that displace traditional fabless-OSAT relationships, compressing pricing leverage for independent merchant houses.
For Market Incumbents: Harden captive substrate supply through backward integration into ABF laminate production or long-term offtake agreements with Japanese suppliers. Expand automotive qualification capacity in Arizona and Germany ahead of NHTSA and KBA timeline extensions. Defend against foundry-OSAT joint venture encroachment by deepening process engineering talent pools in Taiwan. For New Entrants and Emerging Players: India's Gujarat-Vedanta-Foxconn project corridor offers underpenetrated domestic fabless servicing potential under PLI scheme incentives. Target photonics-electronics hybrid assembly for silicon photonics transceivers where precision optical-electrical interconnect commands premium service tiers distinct from commoditized IC packaging. Pursue equipment leasing partnerships to circumvent capital barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced fan-out wafer-level packaging as lithography and thermocompression bonder lead times stretch. Long-term viability centers on mega-site operators with captive heterogeneous integration capacity and automotive qualification pathways. Monitor equipment delivery window compression as inflection signal for capacity-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Supply Securement | Long-term ABF laminate offtakes with Japanese suppliers insulate against input bottlenecks for high-density fan-out lines. |
| Automotive Qualification Expansion | AEC-Q100 and AEC-Q104 certified capacity additions in Arizona and Germany capture electrification-driven die count multiplication. |
| Photonics Hybrid Assembly Buildout | Silicon photonics transceiver packaging capabilities address hyperscaler datacenter interconnect demand with premium pricing. |
| India Joint Venture Formation | PLI scheme-aligned partnerships in Gujarat corridor access domestic fabless design house growth under Vedanta-Foxconn momentum. |
| Fluorine-Free Process Transition | EU F-Gas Regulation-compliant plasma cleaning retrofits maintain European automotive and industrial shipment eligibility. |
Methodological Framework
Initial hypotheses were tested against primary input from OSAT operations executives, fabless design house procurement leads, semiconductor equipment vendor technical directors, and automotive Tier 1 supplier quality engineers and refined through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K filings, SEMI equipment shipment databases, customs trade records, and NHTSA safety mandate documentation.
Demand-supply balance modeling across the projection horizon captured service type, interconnect technology, end-use reliability tier, and geographic production cluster segmentation. CAGRs were derived from capacity utilization trajectories and qualification timeline compression effects. Forecast inputs incorporated equipment lead time volatility and substrate supply concentration constraints.
Practitioners should monitor export control classification revisions and carbon border adjustment implementations for early signals of geographic sourcing disruption. Forecasts reflect assumptions on equipment delivery normalization and regulatory timeline adherence. Material shifts in foundry-OSAT partnership structures or REACH chemical restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market