
 Connector Kits Market | 2026-2036
Connector Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Connector Kits Market Outlook
High-performance thermoplastics are replacing traditional halogenated compounds in connector housings, and this material transition is repositioning cost structures across the supply base. TE Connectivity leverages captive compounding operations to secure resin supply continuity. Amphenol Corporation anchors its position through aerospace-grade qualification depth. Molex competes by dominating high-density board-to-board configurations in data infrastructure.
Connector kits are integrated assemblies comprising housings, contacts, seals, and retention hardware engineered to establish reliable electrical or optical interconnections between subsystems, typically rated for specific voltage, current, and environmental sealing levels. Their primary purpose is to reduce field assembly time and eliminate workmanship variability in critical signal and power distribution applications. Wire connectors and terminal blocks command the largest volume share due to their ubiquity across industrial equipment and building automation installations. Adapters represent the fastest-expanding category as modular system architectures proliferate in automotive and telecommunications equipment. Plastic and composite material segments attract margin concentration where weight reduction and corrosion resistance justify premium positioning.
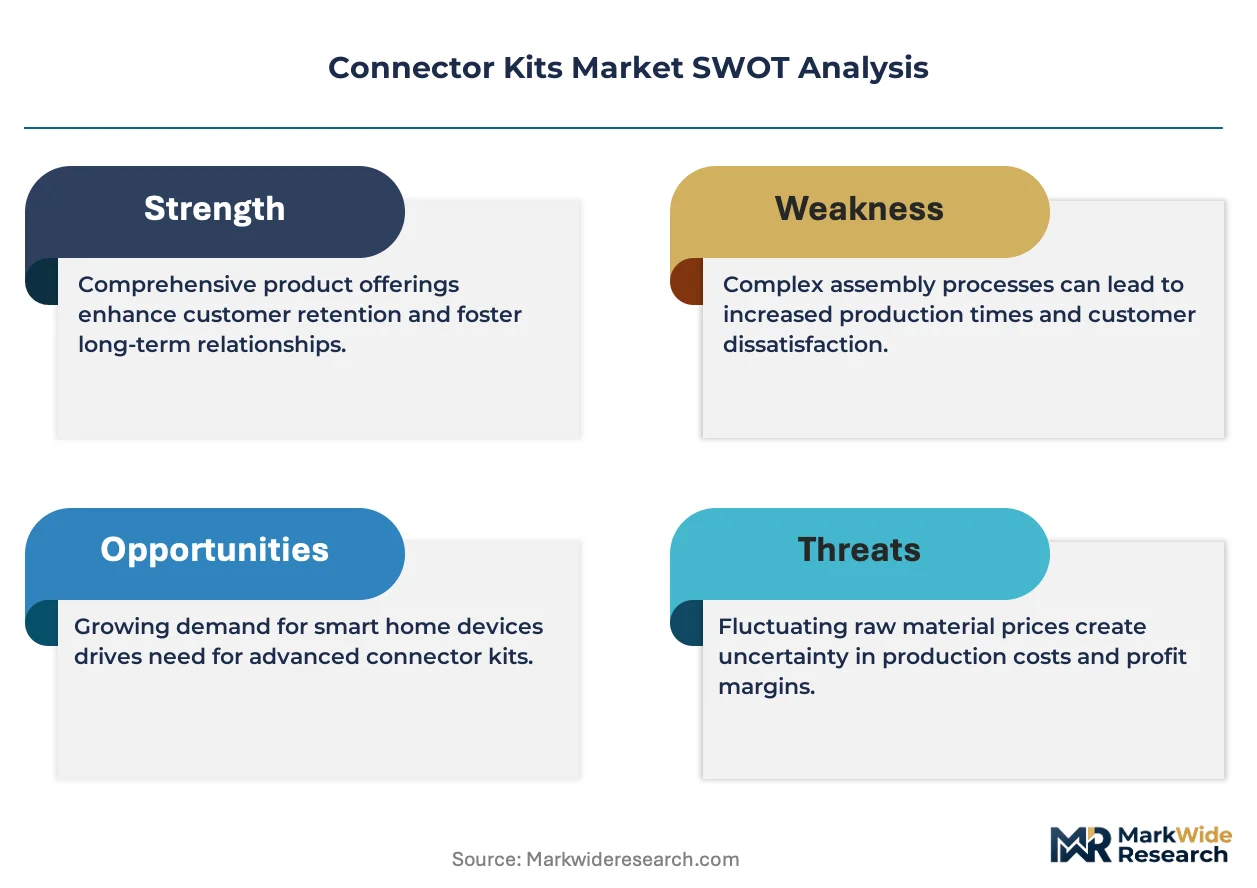
EPA regulations on persistent organic pollutants constrain halogenated flame retardant use in US-sold products, while REACH and RoHS in Europe mandate substance disclosure and restricted material elimination across connector supply chains. These frameworks elevate compliance costs for imported assemblies while creating preference windows for domestic manufacturers with certified material traceability. Stakeholders must monitor evolving substance restriction lists and pre-qualify alternative resin systems before regulatory deadlines compress sourcing flexibility.
Market Dynamics
Automotive electrification is electrifying connector specifications across voltage classes, forcing suppliers to requalify entire product families for 800V architectures while maintaining backward compatibility with legacy 12V and 48V systems.
Growth Catalysts
- EV Platform Standardization:Automotive OEMs are consolidating connector families across vehicle programs, creating volume pull for modular kit architectures that reduce SKU proliferation.
- REACH Substance Restrictions:ECHA's expanding candidate list of SVHCs is accelerating halogen-free thermoplastic adoption, opening preference windows for compounders with certified material traceability.
- German Industrial Automation Density:The concentration of robot OEMs and machine builders in Bavaria and Baden-Württemberg generates sustained demand for IP67-rated circular connector kits.
Market Restraints
- Engineering Resin Volatility:Polyamide and PBT compound prices fluctuate with benzene and butanediol feedstock costs, compressing margin predictability for mid-tier kit assemblers.
- Asian Molding Capacity Concentration:Over 60% of precision connector housing production sits in Guangdong and Jiangsu provinces, exposing supply continuity to regional logistics disruptions.
- Contact Plating Substitution Limits:Tin and nickel plating chemistries face performance ceilings in high-mating-cycle applications, constraining cost-down paths for standard-density connectors.
Strategic Opportunities
- Indian EV Component Localization:PLI scheme incentives for automotive electronics are drawing kit suppliers to establish compounding and molding operations near Chennai and Pune assembly corridors.
- Optical-to-Electrical Conversion:Data center transceiver integration is creating hybrid connector categories combining copper power and fiber signal in single housings.
- CE-MDR Certification Services:Medical device regulation complexity is opening paid advisory revenue streams for kit vendors with notified body relationships.
Industry Challenges
- High-Voltage Safety Certification:IEC 60664 and UL 1977 qualification timelines for 800V-rated kits extend 18-24 months, freezing product roadmaps.
- Legacy Interoperability Burden:Industrial retrofit markets demand mechanical compatibility with 30-year-old contact geometries, fragmenting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connector Kits Market |
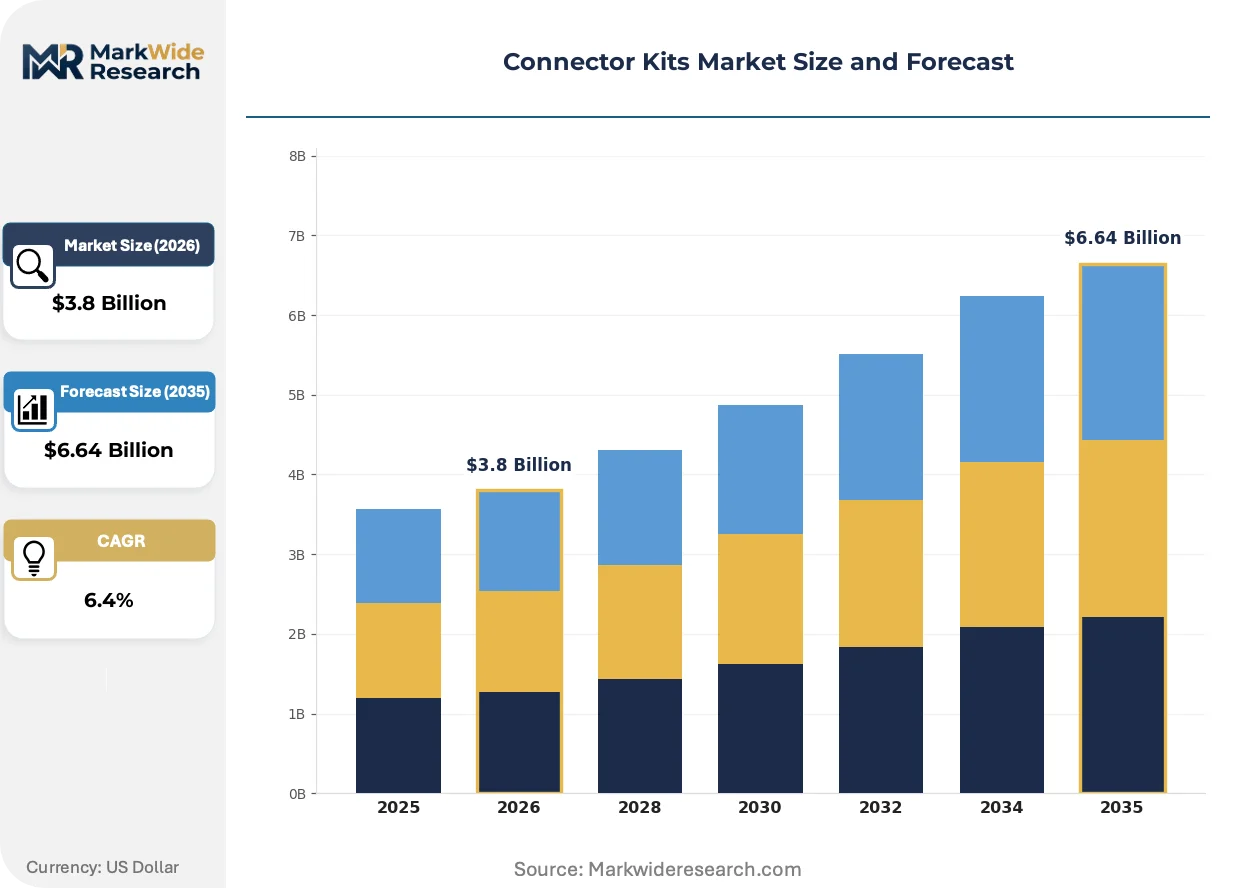
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Connectors, Terminal Blocks, Adapters, Junction Boxes Material: Plastic, Metal, Rubber, Composite End User: Automotive, Aerospace, Industrial Equipment, Consumer Electronics Connector Style: Plug-in, Screw Terminal, Soldering, Crimp |
| Companies Covered | TE Connectivity, Amphenol Corporation, Molex, Aptiv PLC, Phoenix Contact, Hirose Electric, Foxconn Interconnect Technology, Yazaki Corporation, Samtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connector Kits Market Strategic Shifts
Connector architecture is converging around modularity and intelligence, with suppliers embedding sensing and diagnostic capabilities directly into interconnection hardware.
High-voltage interlock loop (HVIL) circuitry is electrifying safety verification in automotive connector kits, eliminating separate wiring harnesses for isolation monitoring. Tier-1 suppliers are mandating HVIL integration for all high-voltage distribution components. This consolidation is electrifying competitive differentiation around firmware reliability and pin-level diagnostics.
EPA regulations on persistent organic pollutants are constraining brominated flame retardant use in US-sold connector housings, elevating phosphorus-based and mineral-filled alternatives. Compounders must reformulate entire resin portfolios while maintaining UL 94 V-0 ratings. Wire-to-board applications in appliance and HVAC equipment face the steepest requalification burdens.
Consolidated procurement of connector kits by platform engineering teams is displacing decentralized purchasing by individual subsystem groups. Automotive and industrial OEMs are awarding multi-year kit supply agreements to vendors with simulation and prototyping co-location capabilities. This concentration is most visible in Germany, where Volkswagen Group and Siemens AG have both centralized connector sourcing under chief procurement officers.
Connector Kits Market Segmentation
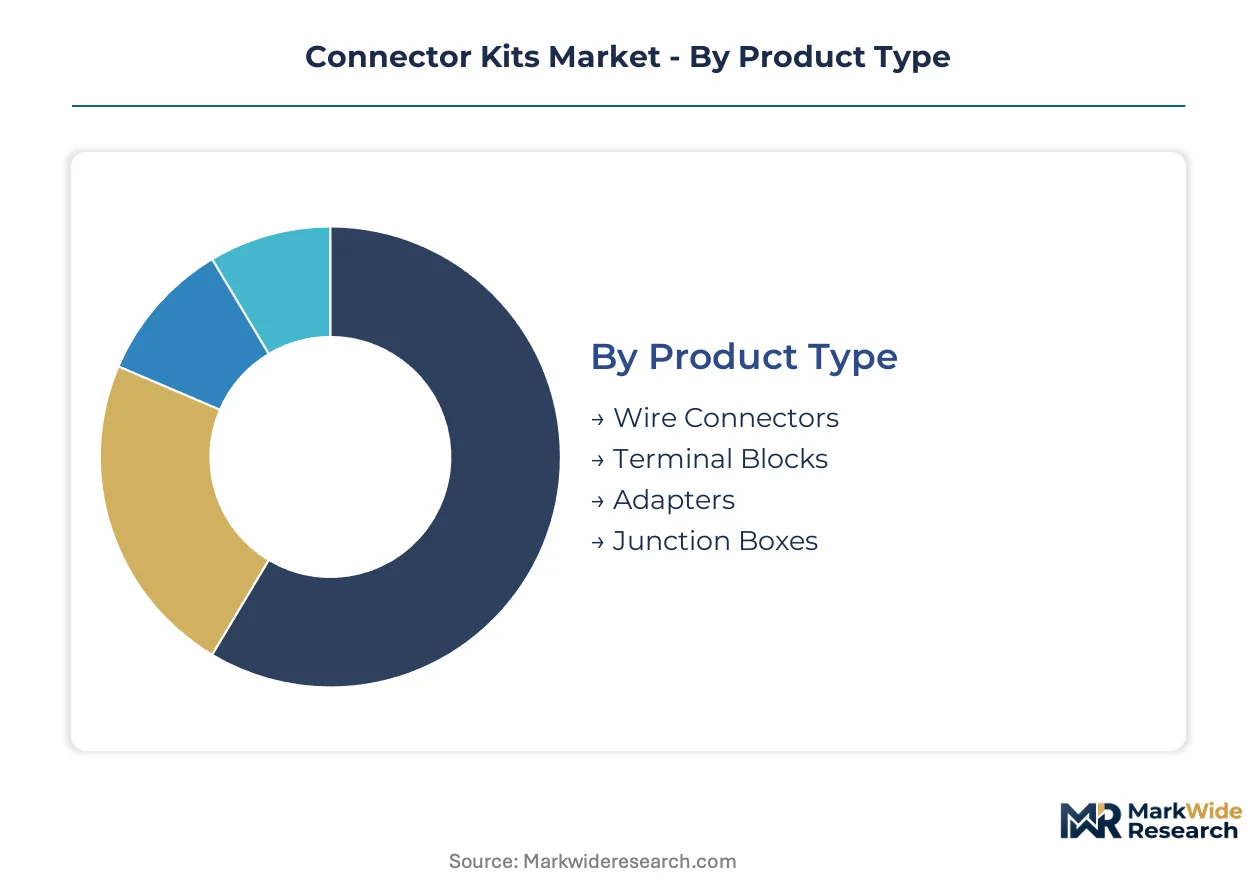
Connector kit segmentation reflects divergent integration depths across applications. Standalone terminal blocks serve distributed industrial controls, while embedded adapters integrate into compact automotive modules. Material and connector style choices further stratify supply chains by performance tier and assembly automation compatibility.
Product Type:
Standalone wire connectors dominate field-installation environments where modularity outweighs density, while embedded adapters concentrate in space-constrained automotive and telecom subsystems.
- Wire Connectors:Insulated housings with crimp or push-fit contacts rated for 600V and 105°C continuous operation. Demand concentrates in German automotive supplier parks and US industrial automation corridors, driven by modular repairability requirements in legacy equipment fleets.
- Adapters:Compact gender changers and protocol bridges enabling mechanical or electrical interface conversion between incompatible systems. Modular system architectures in automotive and telecommunications equipment are accelerating specification velocity for these components.
- Terminal Blocks:Screw-clamp or spring-cage connection points for DIN-rail mounting in control cabinets.
- Junction Boxes:Enclosed distribution nodes with multiple cable entry points for harsh-environment power splitting.
Wire connectors lead volumes today; adapters are gaining share fastest.
Material:
Cost tiers separate commodity thermoplastics from engineered compounds with certified traceability, with metal and composite options commanding premiums where thermal or structural loads exceed polymer limits.
- Plastic:Polyamide, PBT, and halogen-free thermoplastic housings dominate volume production. REACH substance restrictions and EPA persistent organic pollutant regulations are redirecting compound selection toward phosphorus-based flame retardant systems.
- Composite:Glass-fiber reinforced thermoplastics and thermoset hybrids balancing weight reduction with dimensional stability. Aerospace wire harnesses and racing automotive applications absorb most composite connector output due to vibration-damping requirements.
- Metal:Aluminum and zinc alloy shells for EMI shielding and mechanical ruggedization.
- Rubber:EPDM and silicone seals and overmolds for environmental ingress protection.
Plastic leads volumes today; composite is climbing the fastest.
End User:
Customer type determines qualification burden and contract structure, with automotive and aerospace demanding multi-year validation cycles while industrial and consumer electronics prioritize cost responsiveness.
- Automotive:High-voltage interlock loop (HVIL) integration and 800V architecture compatibility now standard for electrified powertrain connectors. Platform standardization across vehicle programs is consolidating kit specifications and lengthening supplier contracts.
- Industrial Equipment:IP67-rated circular connectors for factory automation and process control. Bavarian and Baden-Württemberg robot OEM density sustains demand for field-terminable kits with rapid deployment protocols.
- Aerospace:AS39029 contact qualification and outgassing-compliant materials for cabin and avionics systems.
- Consumer Electronics:Miniaturized board-to-board and wire-to-board configurations for appliances and personal devices.
Industrial equipment leads volumes today; automotive is expanding most quickly.
Connector Style:
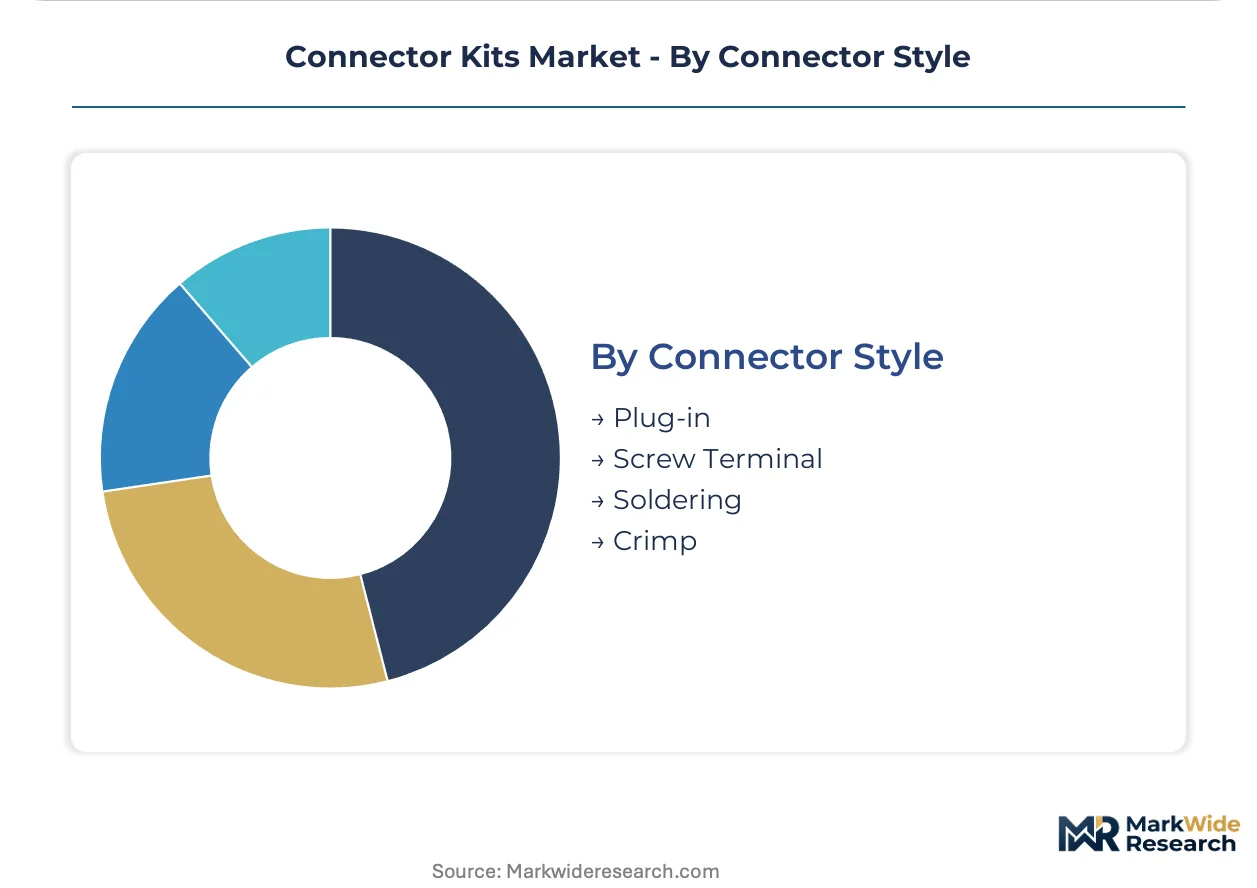
Assembly automation compatibility and field serviceability trade off across styles, with crimp and plug-in formats favoring high-volume manufacturing while screw terminals retain retrofit market presence.
- Crimp:Permanent compression connections applied with pneumatic or hydraulic tooling for consistent electrical resistance. Automotive wire harness automation and industrial cable assembly lines depend on crimp technology for throughput and repeatability.
- Plug-in:Tool-free mating with latching mechanisms for rapid assembly and hot-swapping. Data center infrastructure and modular industrial controls specify plug-in styles to minimize commissioning time and enable field replacement.
- Screw Terminal:Field-wirable clamp connections for maintenance-accessible junction points.
- Soldering:Permanent metallurgical bonds for high-density printed circuit board applications.
Crimp leads volumes today; plug-in is ascending fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier ecosystem in Bavaria and Baden-Württemberg anchors connector kit demand through electrification programs and industrial automation density.
United States
EPA regulations on persistent organic pollutants constrain halogenated flame retardant use in connector housings, forcing reformulation toward phosphorus-based alternatives. Industrial automation corridors in Michigan and Ohio sustain demand for IP67-rated field-terminable kits. NHTSA safety mandates accelerate high-voltage interlock loop integration across electrified powertrain platforms.
Germany
REACH substance restrictions and ECHA's expanding SVHC candidate list redirect material sourcing toward halogen-free thermoplastics with certified traceability. Volkswagen Group and Siemens AG have centralized connector procurement under chief procurement officers, consolidating multi-year supply agreements. Bavarian robot OEM density generates sustained demand for circular connector kits in factory automation applications.
China
Over 60% of precision connector housing production concentrates in Guangdong and Jiangsu provinces, exposing supply continuity to regional logistics disruptions. MIIT industrial standards and dual carbon goals pressure compounders toward low-carbon resin systems. Yangtze River Delta electronics manufacturing clusters absorb high-volume output for consumer electronics and telecommunications equipment.
India
PLI scheme incentives for automotive electronics draw kit suppliers toward compounding and molding operations near Chennai and Pune assembly corridors. BIS certification requirements elevate compliance costs for imported assemblies while creating preference windows for domestic manufacturers. Maharashtra and Tamil Nadu industrial corridors anchor emerging EV component localization momentum.
Japan
METI energy efficiency standards and industrial automation roadmaps sustain demand for high-reliability connection systems in precision manufacturing. Kanto and Kansai industrial belts concentrate aerospace-grade connector qualification expertise. JIS standards compliance creates technical barriers for non-domestic suppliers in medical and transportation applications.
Connector Kits Market Competitive Environment
Global majors compete with regional champions across certification depth and geographic proximity to OEM engineering centers. The vendor base stratifies into three tiers: integrated compounders with captive resin supply, specialized assemblers with aerospace or automotive qualification depth, and scale-driven manufacturers serving consumer electronics. Dominant competitive moves include backward integration into resin compounding and co-location of simulation capabilities with customer platform engineering teams.
Within the integrated tier, TE Connectivity exemplifies compounder-assembler convergence through captive thermoplastic operations. Amphenol Corporation and Molex occupy positions on opposite vectors of this landscape—Amphenol anchoring aerospace-grade qualification protocols, Molex representing high-density board-to-board specialization for data infrastructure. These three entities illustrate how certification breadth, material control, and application focus differentiate positioning.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Molex |
| Aptiv PLC |
| Phoenix Contact |
| Hirose Electric |
| Foxconn Interconnect Technology |
| Yazaki Corporation |
| Samtec |
| Others |
Value Chain & Pricing Dynamics
800V architecture qualification is compressing development timelines while concentrating procurement leverage among automotive OEMs with multi-year platform commitments. This voltage-class transition simultaneously elevates engineering-resin consumption and consolidates supplier selection around compounders with captive material traceability, fusing cost structure pressure with supply base narrowing.
Pricing Analysis
Engineering-resin feedstock volatility passes through to kit assemblers with 60-90 day lags, compressing margin predictability for mid-tier compounders lacking long-term benzene or butanediol contracts. Three-tier pricing structure across automotive-grade, industrial-standard, and consumer-economy levels separates UL 94 V-0 certified housings from commodity polyamide alternatives. Pricing pressure stems from Asian molding overcapacity in Guangdong province, where spot-market resin sourcing undercuts contract-based European supply. Industrial automation buyers exhibit highest price sensitivity due to retrofit market fragmentation, while aerospace qualification depth insulates Amphenol-tier suppliers from cost-down demands.
Supply Chain Analysis
AS39029 and IEC 60664 qualification gating restricts precision housing supply to Germany, China, and Japan, where notified-body relationships and metallurgical testing infrastructure concentrate. Raw material flows draw from Saudi aromatics for polyamide precursors, Chilean copper for contact plating, and German specialty chemical additives for halogen-free flame retardants. Single-source vulnerability sits with Guangdong-Jiangsu molding corridors exposed to Yangtze River logistics disruptions. Distribution runs through Tier 1 automotive harness assemblers and industrial distributor networks with regional stocking points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Connector Kits Market functions as a stable compounder anchored by automotive electrification's irreversible voltage-class escalation and regulatory-mandated material transitions.
For Market Incumbents: Deepen backward integration into phosphorus-based flame retardant compounding to secure resin supply continuity against REACH SVHC expansion. Lock multi-year platform engineering co-location contracts with Volkswagen Group and Siemens AG procurement centralization. Defensive priority rests on pre-qualifying alternative thermoplastic systems before ECHA candidate list deadlines compress sourcing flexibility. For New Entrants and Emerging Players: HVIL firmware integration capability offers entry wedge into automotive high-voltage distribution where Tier 1 mandates are electrifying safety verification consolidation. Target Indian PLI scheme corridors near Chennai and Pune for EV component localization with BIS certification as regulatory moat. Go-to-market angle centers on optical-electrical hybrid connector categories for data center transceiver integration. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier assemblers with automotive qualification depth but lacking captive resin supply. Long-term viability frames around 5-10 year automotive platform standardization windows and medical device CE-MDR advisory service attach rates. Signal to monitor: IEC 60664 qualification timeline compression indicating R&D resource fragmentation among legacy interoperability burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive phosphorus-based flame retardant supply secures REACH compliance continuity against ECHA SVHC expansion. |
| Platform Engineering Co-location | Simulation proximity to Volkswagen Group and Siemens AG procurement teams locks multi-year kit supply agreements. |
| HVIL Firmware Certification Investment | Tier 1 automotive mandates for high-voltage interlock loop integration consolidate supplier selection around diagnostic-capable vendors. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives near Chennai and Pune corridors capture EV component localization momentum with BIS certification preference windows. |
| Optical-Electrical Hybrid Development | Data center transceiver integration creates connector category expansion combining copper power and fiber signal in single housings. |
Study Parameters
Direct dialogue with Tier 1 automotive supplier procurement directors, industrial automation plant engineers, connector compounder R&D heads, and notified-body certification managers grounded qualitative findings. Secondary validation drew from SEC 10-K filings, ECHA SVHC candidate list updates, EPA persistent organic pollutant regulatory dockets, and MIIT industrial standard releases. Bottom-up and top-down triangulation cross-checked resin consumption models against automotive production database aggregates.
Top-down macroeconomic drivers and bottom-up segment-level unit economics converged across the analysis window. Segmentation dimensions modeled include product type, material grade tier, end-use industry, connector style, and regional production cluster. CAGRs derived from polynomial trend fitting of historical resin price elasticity and automotive electrification content-per-vehicle trajectories. Forecast inputs incorporated REACH substance restriction timeline probabilities and PLI scheme incentive disbursement schedules.
The model holds under stable automotive platform standardization momentum and ECHA regulatory timeline adherence; deviation in Guangdong logistics continuity or benzene feedstock shock would shift volume assumptions. Forecasts embed these boundary conditions without deterministic precision. A model refresh is warranted upon material change in IEC 60664 qualification timeline compression or Indian BIS certification requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
USB Type-C Market
Connectors
Pin Retainer Market
Connectors
Latin America Connector Market
Connectors
Liquid Cooling Connector Market
Connectors
PCI-E Connectors Market
Connectors
Global Automotive Connector Market
Connectors
Space Grade Connectors Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Australia Connector Market
Connectors
Underwater Mate Connectors Market
Connectors
High-Reliability Connectors Market
Connectors
Hazardous Location Connectors Market
Connectors
Heavy-Duty Connector Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Middle East Connector Market