
 Butyl Glycol Market | 2026-2036
Butyl Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Butyl Glycol Market Intelligence
Technical service contracts for solvent formulation support is hardening into a core revenue layer for butyl glycol suppliers. BASF SE leverages its integrated ethylene oxide derivatives network to anchor European supply reliability. Dow Chemical Company sustains North American manufacturing scale through Gulf Coast petrochemical infrastructure. Eastman Chemical Company differentiates via specialized grades for electronics-grade cleaning applications.
Butyl glycol, primarily 2-butoxyethanol, functions as a glycol ether solvent with a boiling point near 171°C and moderate evaporation rate, produced via ethoxylation of n-butanol with ethylene oxide for use in surface coatings, industrial cleaners, and printing inks. Paints and coatings applications dominate volume consumption as architectural and automotive refinish formulations require controlled flow and leveling properties. Cleaners represents the fastest-expanding application segment as institutional and industrial maintenance protocols shift toward water-based degreasing systems. Chemicals end users occupy the largest share of direct procurement, while automotive OEM coatings programs command premium pricing for specification-grade material.
EPA oversight under the Toxic Substances Control Act shapes permissible volatile organic compound content in consumer and industrial products, while REACH registration requirements in Europe govern chemical safety data and authorization thresholds for glycol ether substances. OSHA permissible exposure limits further constrain workplace handling protocols in manufacturing and application settings. Stakeholders must monitor regulatory tightening on reproductive toxicity classifications, as reclassification risk in major jurisdictions would force reformulation investments across coating and cleaning supply chains.
Market Dynamics
Formulation chemistry migration toward waterborne industrial coatings is compressing solvent selection windows, forcing glycol ether suppliers to demonstrate coalescing efficiency at lower VOC loadings while maintaining flash rust resistance and wet-edge control in high-humidity application environments.
Growth Catalysts
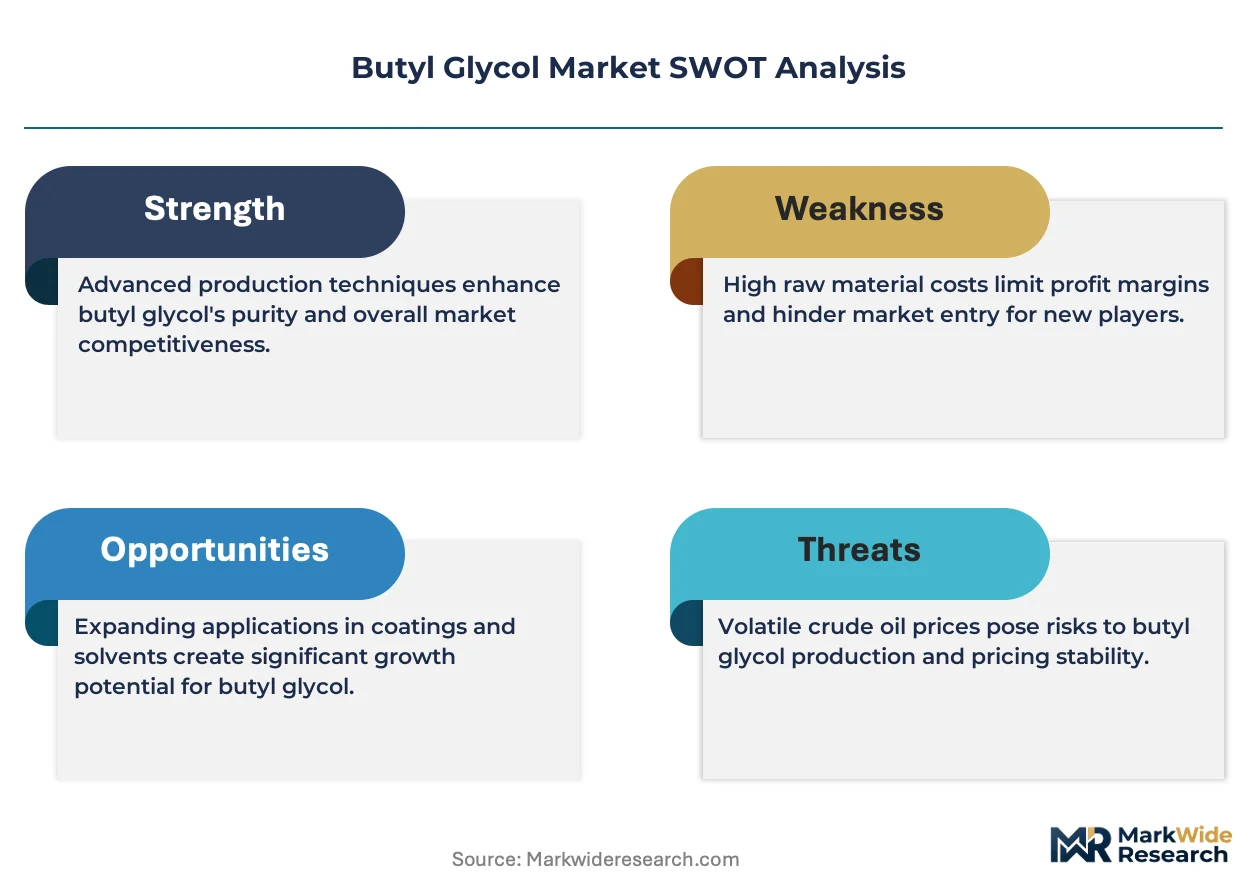
- REACH authorization thresholds:ECHA's tightening reproductive toxicity classifications for certain glycol ethers are redirecting formulators toward butyl glycol as a compliant alternative in European decorative and protective coatings.
- Water-based degreasing protocols:Institutional maintenance departments across North American manufacturing facilities are replacing solvent-heavy vapor degreasing with aqueous cleaning systems that rely on butyl glycol for soil suspension and rinse compatibility.
- Ethylene oxide derivative networks:Integrated petrochemical complexes on the US Gulf Coast and in Rotterdam-Antwerp maintain captive feedstock access that insulates regional supply chains from n-butanol spot market volatility.
Market Restraints
- N-butanol feedstock volatility:Propylene hydroformylation economics and competing plasticizer demand create input cost instability that compresses glycol ether margin structures without corresponding pricing power in commoditized coating solvent markets.
- Propylene glycol ether substitution:Lower-toxicity profile alternatives are capturing specification share in hand-wipe cleaners and consumer-facing applications where workplace exposure limits face tightening scrutiny.
- MEE enforcement in China:Ministry of Ecology and Environment inspections of ethoxylation facilities are creating intermittent supply disruptions and compliance capital requirements that disadvantage non-integrated producers.
Strategic Opportunities
- Electronics-grade cleaning:Semiconductor fabrication and display manufacturing in South Korea and Taiwan are creating demand for ultra-low metal content glycol ether specifications that command significant price premiums over industrial grades.
- India construction chemicals:BIS certification requirements for concrete admixtures and waterproofing membranes are expanding the addressable market for coalescing agents in cementitious coating systems.
- EU Green Deal procurement mandates:Public infrastructure projects exceeding specified contract values now require documented bio-based or recycled content in applied coating systems, creating incentive structures for renewable feedstock glycol ether development.
Industry Challenges
- Reproductive toxicology dossier preparation:Extended-term mammalian studies and read-across justifications for REACH Annex XV submissions demand specialized regulatory toxicology expertise that mid-scale producers struggle to retain.
- Legacy formulation recertification:Automotive OEM coating programs require 18-36 month qualification cycles for any solvent substitution, freezing specification positions and delaying revenue capture from improved product offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyl Glycol Market |
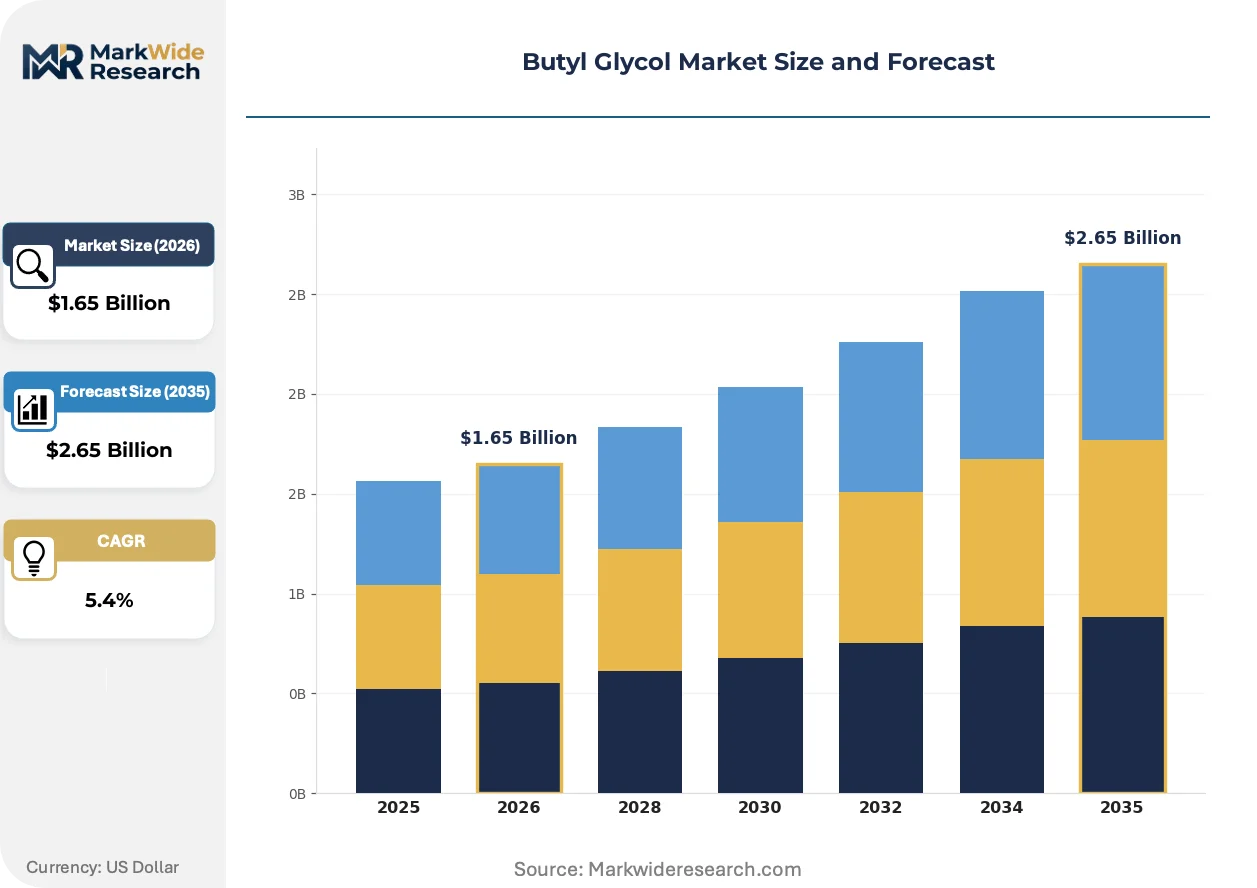
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Butoxyethanol, Ethylene Glycol, Acetic Acid, Others Application: Paints, Coatings, Cleaners, Inks End User: Chemicals, Automotive, Construction, Electronics Packaging Type: Drums, IBC Totes, Bags, Containers |
| Companies Covered | Eastman Chemical Company, Dow Chemical Company, BASF SE, LyondellBasell Industries N.V., Sasol Ltd., Lotte Chemical Corporation, Asia Pacific Petrochemicals Co Ltd, INEOS, Solventis Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyl Glycol Market Strategic Shifts & Innovations
Reactive diluent technologies and bio-attributed feedstock certifications are restructuring how coating manufacturers evaluate solvent total cost of ownership, shifting purchasing criteria from unit price to lifecycle regulatory risk and Scope 3 emissions accounting.
Hybrid glycol ether-ester compounds are absorbing formulation volume in high-solids industrial maintenance coatings where single-solvent systems previously dominated. Marine and protective coatings manufacturers in Northern Europe are adopting these materials to achieve required film build without exceeding VOC emission permits. The technology is absorbing market share from traditional butyl glycol in immersion service applications where enhanced hydrolytic stability reduces premature coating failure.
EPA TSCA Section 6 risk evaluations for 1,4-dioxane trace contamination in ethoxylated surfactants and solvents are forcing purification technology investments across US-based production assets. Facilities without molecular sieve or extractive distillation capabilities face product exclusion from consumer product and cosmetic ingredient supply chains. Cleaning compound manufacturers serving California's Proposition 65 enforcement environment are most affected, accelerating supplier qualification audits and contractual indemnification requirements.
Specification-grade procurement consolidation among multinational coatings formulators is concentrating volume with suppliers offering bundled solvent-additive packages and technical service support. Regional distributors in the US Midwest and German Ruhr industrial corridor are losing direct mill relationships as direct mill accounts centralize purchasing through integrated supply agreements. The shift is most visible in automotive refinish programs where single-source solvent supply contracts now span five-year terms with indexed pricing mechanisms.
Butyl Glycol Market Segmentation
Butyl glycol procurement patterns diverge sharply between specification-grade industrial buyers and volume-driven commodity consumers. Segmentation reveals how formulation chemistry constraints, regulatory thresholds, and supply chain reliability requirements partition the addressable market into distinct commercial battlegrounds.
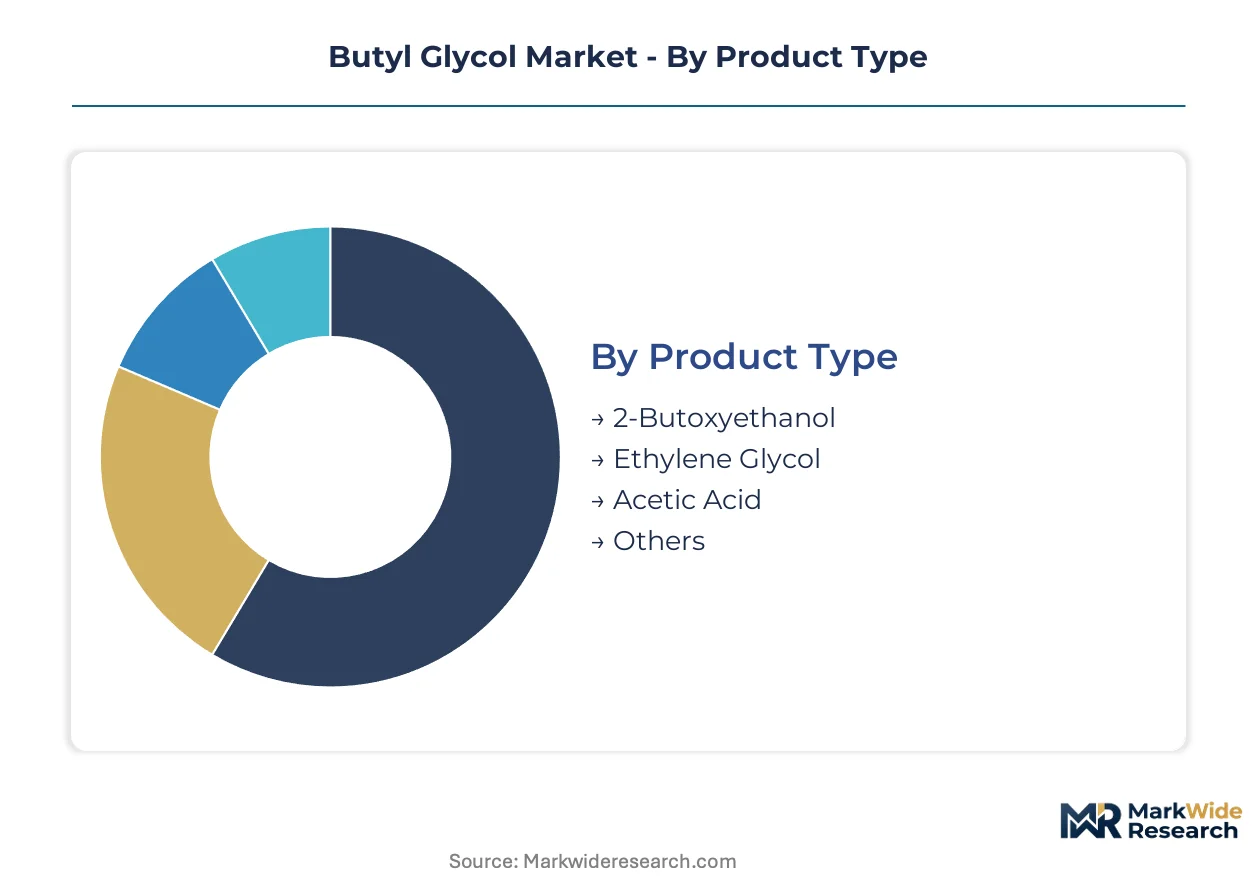
Product Type:
Volume concentrates in standard industrial grades, while premium pricing attaches to ultra-low metal content and bio-attributed certifications.
- 2-Butoxyethanol:The primary glycol ether specification with a 171°C boiling point and moderate evaporation rate, produced via ethoxylation of n-butanol with ethylene oxide. Paints and coatings manufacturers in China absorb the largest volumes as architectural and automotive refinish formulations demand controlled flow and leveling properties.
- Ethylene Glycol:A lower-molecular-weight diol functioning as a co-solvent and freezing point depressant in waterborne systems. Cleaners applications in North American manufacturing facilities are expanding most quickly as aqueous degreasing protocols replace solvent-heavy vapor systems.
- Acetic Acid:Esterification feedstock for glycol ether-acetate derivatives with enhanced hydrolytic stability.
- Others:Specialty glycol ether blends and customized coalescing agent packages for OEM qualification programs.
Today's leader: 2-Butoxyethanol. Tomorrow's challenger: Ethylene Glycol.
Application:
Formulation migration toward waterborne systems is redistributing volume across end-use categories.
- Paints:Architectural coatings dominate consumption as VOC regulations tighten across multiple jurisdictions. ECHA's REACH classifications and EPA TSCA enforcement are compressing solvent selection windows, forcing suppliers to demonstrate coalescing efficiency at lower loadings.
- Coatings:Industrial maintenance and protective formulations command premium pricing for specification-grade material. Marine coatings manufacturers in Northern Europe are adopting hybrid glycol ether-ester compounds to achieve required film build without exceeding emission permits.
- Cleaners:Institutional and industrial maintenance departments across North American manufacturing facilities are replacing solvent-heavy vapor degreasing with aqueous systems that rely on butyl glycol for soil suspension.
- Inks:Printing applications require controlled drying rates and substrate wetting in packaging and publication gravure systems.
Paints and Coatings anchor current procurement volumes. Cleaners is gaining share fastest as regulatory pressure intensifies on solvent-heavy alternatives.
End User:
Direct procurement scale varies dramatically between integrated chemical producers and specialized formulation houses.
- Chemicals:Integrated petrochemical complexes and specialty solvent blenders occupy the largest share of direct procurement, leveraging captive ethylene oxide derivative networks to insulate margins from n-butanol spot volatility.
- Automotive:OEM coatings programs command premium pricing for specification-grade material with 18-36 month qualification cycles that freeze supplier positions.
- Construction:Cementitious coating systems and concrete admixtures in India are expanding addressable demand as BIS certification requirements tighten.
- Electronics:Semiconductor fabrication and display manufacturing in South Korea and Taiwan are creating demand for ultra-low metal content specifications that command significant price premiums.
Chemicals producers dominate direct volume. Electronics represents the steepest expansion trajectory for premium-grade material.
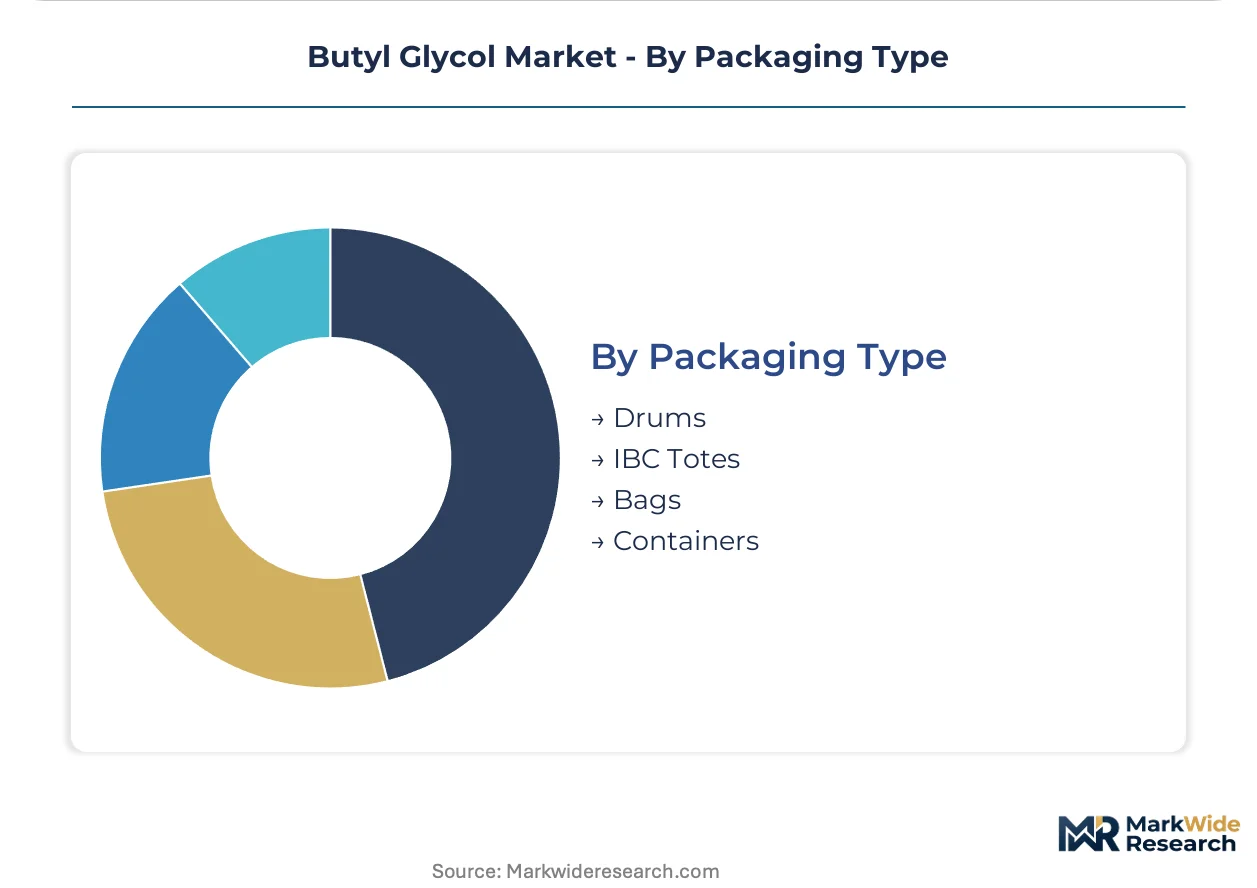
Packaging Type:
Logistics economics and handling safety protocols determine format selection across customer tiers.
- Drums:Standard 200-liter steel drums serve mid-volume coatings formulators and regional distributors with established material handling infrastructure.
- IBC Totes:Intermediate bulk containers reduce per-liter handling costs for high-throughput manufacturing facilities with dedicated solvent storage and dispensing systems.
- Bags:Flexible packaging for solid derivative products and pre-weighed additive packages in construction chemicals applications.
- Containers:Smaller format packaging for specialty grades, sample quantities, and electronics-grade specifications with contamination-sensitive handling requirements.
Drums and IBC Totes split industrial volume. Containers capture the electronics-grade premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs larger butyl glycol volumes than any other single country, while the United States maintains tighter specification standards that compress solvent selection windows for domestic formulators.
China
Industrial coatings output and construction activity sustain large-volume offtake across the Yangtze River Delta and Pearl River Delta clusters. Ministry of Ecology and Environment inspections of ethoxylation facilities create intermittent supply disruptions that disadvantage non-integrated producers. Shanghai and Jiangsu province host the densest concentration of architectural coatings manufacturing where waterborne formulation shifts accelerate glycol ether consumption.
United States
Automotive refinish programs and institutional maintenance departments drive specification-grade demand through the US Gulf Coast petrochemical corridor. EPA oversight under the Toxic Substances Control Act shapes permissible volatile organic compound content in consumer and industrial products. Texas and Louisiana maintain integrated ethylene oxide derivative networks that insulate regional supply chains from n-butanol spot market volatility.
Germany
Decorative and protective coatings manufacturers redirect formulations toward REACH-compliant alternatives as ECHA tightens reproductive toxicity classifications for competing glycol ethers. The EU Green Deal procurement mandates now require documented bio-based or recycled content in public infrastructure coating contracts. The Ruhr industrial corridor and Bavarian chemical clusters anchor continental supply reliability through Rotterdam-Antwerp feedstock integration.
South Korea
Semiconductor fabrication and display manufacturing create demand for ultra-low metal content glycol ether specifications that command significant price premiums over industrial grades. The national industrial regulator enforces workplace exposure limits that constrain handling protocols in manufacturing settings. The Gyeonggi-do province and Seoul Capital Area concentrate electronics-grade solvent consumption for flat-panel and memory chip production.
India
BIS certification requirements for concrete admixtures and waterproofing membranes expand the addressable market for coalescing agents in cementitious coating systems. Construction chemicals procurement concentrates among regional distributors serving infrastructure projects in Maharashtra and Gujarat. Mumbai and Ahmedabad industrial zones absorb growing volumes as formulation chemistry migrates toward waterborne systems in commercial building applications.
Butyl Glycol Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical complexes commanding volume positions while specialty blenders capture premium tiers. The vendor base concentrates around ethylene oxide derivative networks that provide captive feedstock access. Three archetypes dominate: integrated multinational chemical producers, regional solvent distributors with technical service capabilities, and specialty-grade purifiers serving electronics and pharmaceutical specifications. Capacity expansion and backward integration into n-butanol supply represent the dominant competitive moves as feedstock volatility compresses margin structures.
Among integrated multinational producers, BASF SE anchors European supply reliability through its ethylene oxide derivatives network, while Dow Chemical Company exemplifies scale-driven positioning through Gulf Coast infrastructure. Eastman Chemical Company occupies a specialty-grade position differentiated for electronics-grade cleaning applications. These three entities represent the structural poles of competition: feedstock-integrated volume, geographic manufacturing scale, and specification-grade purification capability.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Dow Chemical Company |
| BASF SE |
| LyondellBasell Industries N.V. |
| Sasol Ltd. |
| Lotte Chemical Corporation |
| Asia Pacific Petrochemicals Co Ltd |
| INEOS |
| Solventis Ltd |
| Others |
Cost & Logistics Intelligence
Electronics-grade certification premiums against commodity industrial grades create a bifurcated pricing landscape where supply chain configuration locks in margin capture. Buyers in South Korea and Taiwan absorb metal-content-purified material at substantial markups while Chinese architectural coatings manufacturers negotiate volume-driven standard-grade contracts. This divergence forces suppliers to maintain dual production footprints—specialized purification assets for semiconductor fabrication alongside commodity ethoxylation trains for construction chemicals.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard industrial grades as integrated petrochemical complexes expand ethylene oxide derivative output. Three-tier pricing structure across premium, standard, and economy levels stratifies by metal content certification and REACH registration completeness. Pricing pressure stems from n-butanol feedstock volatility propelling cost compression in commodity tiers. Chemicals end users exhibit highest price sensitivity; electronics-grade buyers accept premium positioning due to qualification lock-in.
Supply Chain Analysis
Ethylene oxide supply rests on US Gulf Coast and Rotterdam-Antwerp integrated complexes with captive feedstock access. N-butanol, ethylene oxide, and molecular sieve purification capacity constitute critical input dependencies. Single-source vulnerability concentrates in specialized electronics-grade purification assets serving South Korean semiconductor fabrication. Distribution runs through direct mill accounts for multinational coatings formulators and regional solvent distributors for mid-scale industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Butyl glycol has matured into a late-cycle quality story where specification-grade premiums now dominate value creation, driven by semiconductor fabrication demand for ultra-low metal content solvents.
For Market Incumbents: Acquire electronics-grade purification assets to anchor premium positioning against propylene glycol ether substitution in hand-wipe cleaners. BASF SE and Dow Chemical Company should deepen backward integration into n-butanol supply to insulate margins from propylene hydroformylation volatility. Defensive consolidation around REACH registration dossiers blocks mid-scale competitors from European specification access. For New Entrants and Emerging Players: Bio-attributed feedstock certification technology offers a technology-first wedge into EU Green Deal procurement mandates for public infrastructure coatings. Target India's construction chemicals segment where BIS certification requirements are expanding addressable demand for cementitious coating coalescing agents. A technical service partnership model with regional distributors bypasses direct mill account consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty-grade purifiers serving electronics and pharmaceutical specifications over commodity ethoxylation operators. Long-term viability favors assets with demonstrated semiconductor OEM qualification history and captive ethylene oxide derivative networks. Watch for EPA TSCA Section 6 enforcement acceleration on 1,4-dioxane trace contamination as inflection indicator for purification technology investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into N-Butanol Supply | Captive feedstock access insulates margin structures from propylene hydroformylation volatility in coating solvent markets. |
| Electronics-Grade Purification Capacity Expansion | Ultra-low metal content specifications for South Korean semiconductor fabrication command substantial premiums over industrial grades. |
| REACH Registration Dossier Completion | ECHA reproductive toxicity classifications block non-compliant competitors from European decorative coatings specification access. |
| Bio-Attributed Feedstock Certification | EU Green Deal procurement mandates create incentive structures for renewable content in public infrastructure coating systems. |
| Technical Service Contract Bundling | Specification-grade procurement consolidation among multinational formulators concentrates volume with suppliers offering solvent-additive packages. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned plant managers at ethoxylation facilities, procurement leads at coatings OEMs, distribution channel partners in the US Midwest and German Ruhr corridor, and technical R&D directors overseeing formulation chemistry migration. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical producers, and EPA TSCA regulatory filings. Bottom-up volume modeling and top-down market sizing triangulated demand estimates.
Segment-weighting across product grade, end-use industry, packaging format, and regional production hub anchored the analytical framework. CAGRs were derived from regression analysis against industrial coatings output, construction activity indices, and semiconductor fabrication capacity expansion across the analysis window. Industry-specific inputs included n-butanol spot price volatility, REACH authorization timeline assumptions, and MEE inspection frequency for Chinese ethoxylation assets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reproductive toxicity reclassification risk and propylene glycol ether substitution acceleration. Forecasts reflect documented assumptions on regulatory trajectory, feedstock cost structures, and qualification cycle duration. Material deviation in EPA enforcement patterns or ECHA classification timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ethyl Pyruvate Market
Solvents
Natural Distillates Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Pharmaceutical Solvent Market
Solvents
Mono Propylene Glycol Market
Solvents
Solvent Cement Market
Solvents
Global Xylenols Market
Solvents
1,2-Ethanedithiol Market
Solvents
Chloromethane Market
Solvents
Global Chloroform Market
Solvents
Green Solvents Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Asia-Pacific Ethane Market
Solvents
Electronic Cleaning Solvents Market
Solvents
Industrial Solvents Market
Solvents
Dimethyl Ether (DME) Market