
 Pharmaceutical Solvent Market | 2026-2036
Pharmaceutical Solvent Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Solvent Market Intelligence
Procurement authority for pharmaceutical solvents is shifting from individual research labs to the centralized purchasing departments of large pharmaceutical companies and contract manufacturers. BASF SE leverages its extensive production network to supply high-purity solvents at scale. Dow Inc. competes on specialized formulations for sensitive biologic drug manufacturing. Eastman Chemical Company differentiates through its portfolio of green and bio-derived solvent alternatives.
Pharmaceutical solvents are high-purity organic or inorganic liquids used to dissolve, suspend, or extract other substances during drug synthesis and formulation. These solvents must meet stringent purity specifications, often exceeding 99.9%, to prevent contamination of the final drug product. Ethanol remains a dominant product type due to its versatility and favorable safety profile in many applications. While formulation holds the largest share, the chromatography application segment is expanding rapidly with the growth of analytical testing.
The market operates under strict oversight from regulators like the US FDA and the European Medicines Agency (EMA). International Council for Harmonisation (ICH) guidelines, particularly Q3C for residual solvents, dictate acceptable limits and drive demand for higher-purity grades. Vendor selection increasingly hinges on the ability to supply sustainable, bio-based solvents that meet evolving regulatory purity standards without compromising performance.
Market Dynamics
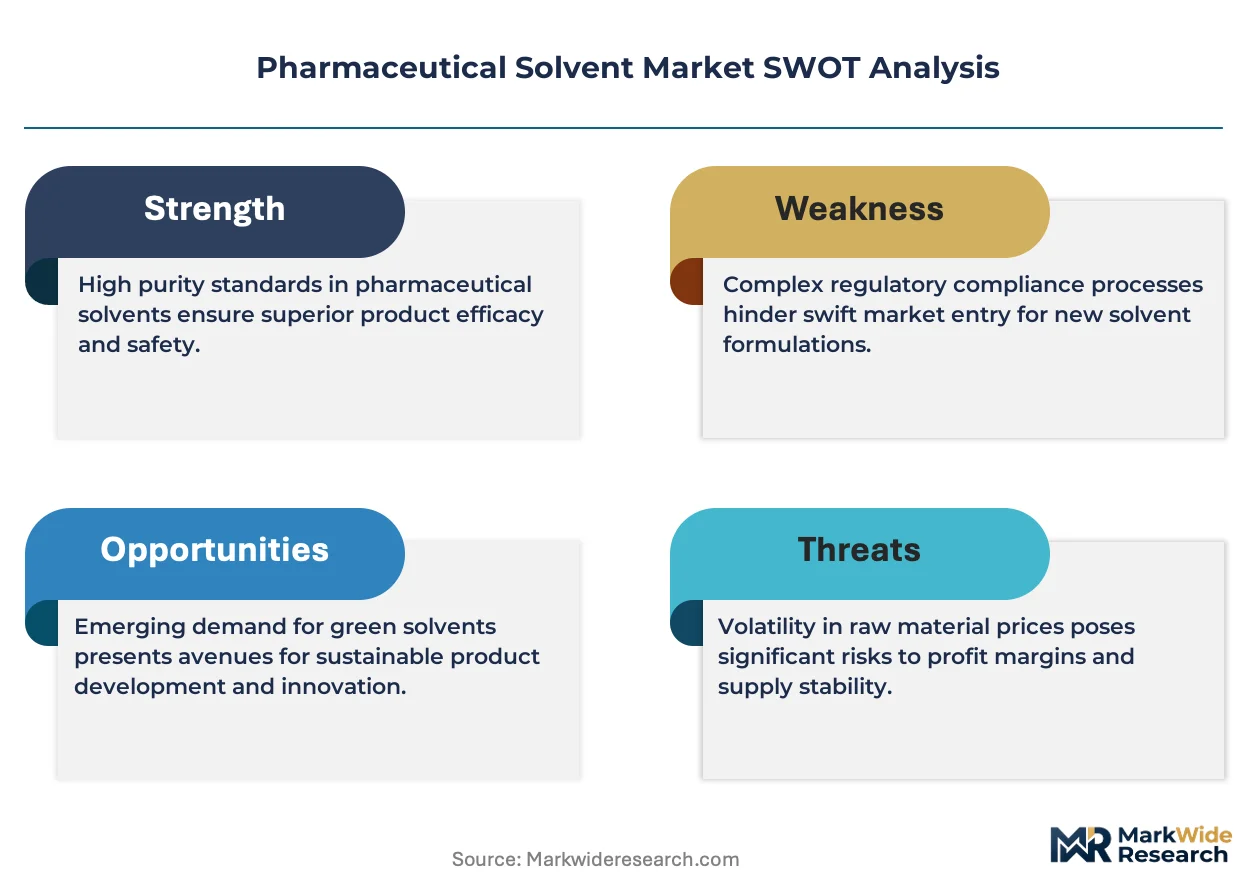
The market's structure is defined by the dual pressures of advanced biologic formulation needs and tightening purity mandates from global regulators. This dynamic forces manufacturers to balance solvent performance in sensitive applications against compliance with standards like ICH Q3C on residual solvents.
Growth Catalysts
- Advanced Biologics:The expansion of biologic drugs, including monoclonal antibodies and cell therapies, requires ultra-high purity solvents for complex synthesis, purification, and formulation steps, directly stimulating demand for premium grades.
- Regulatory Tightening:Stricter International Council for Harmonisation (ICH) Q3C guidelines are mandating lower residual solvent limits in final drug products, compelling manufacturers to adopt higher-purity and certified solvent grades.
- Manufacturing Concentration:The continued growth of pharmaceutical manufacturing clusters in geographies like India and Ireland concentrates solvent demand, creating opportunities for suppliers who can manage logistics and supply at scale in these regions.
Market Restraints
- Feedstock Volatility:Price fluctuations in petrochemical feedstocks, the primary raw material for most organic solvents, introduce cost instability and margin pressure for solvent manufacturers, which can be passed on to end-users.
- Regulatory Hurdles:The complex and lengthy solvent qualification process required by agencies like the US FDA and EMA for inclusion in new drug applications can slow the market adoption of novel or alternative solvents.
- Substitution Threats:Ongoing research into solvent-free manufacturing techniques and the development of aqueous-based drug formulations present a long-term substitution risk that could reduce solvent consumption in specific applications.
Strategic Opportunities
- Green Chemistry:Developing and marketing a portfolio of bio-based solvents derived from renewable sources allows suppliers to meet corporate sustainability mandates from large pharmaceutical clients and differentiate on environmental credentials.
- Analytical Segment Growth:The expanding use of high-performance liquid chromatography (HPLC) and mass spectrometry for quality control and R&D creates a specific, high-margin opportunity for solvents meeting stringent analytical purity specifications.
- Emerging Market Expansion:Penetrating nascent pharmaceutical manufacturing hubs in Southeast Asia and Latin America offers a new geographic frontier for growth as these regions build out their domestic drug production capabilities.
Industry Challenges
- Supply Chain Integrity:Maintaining a secure and fully traceable global supply chain that complies with Good Manufacturing Practice (GMP) standards across multiple jurisdictions is a significant operational and logistical challenge for suppliers.
- Capital Investment:Upgrading production facilities to consistently manufacture solvents that meet ever-increasing purity standards set by pharmacopeias like the USP and Ph. Eur. requires substantial capital expenditure.
- Specialized Talent Scarcity:A shortage of analytical chemists and process engineers with expertise in high-purity solvent handling and advanced residual solvent analysis techniques can hinder quality control and process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Solvent Market |
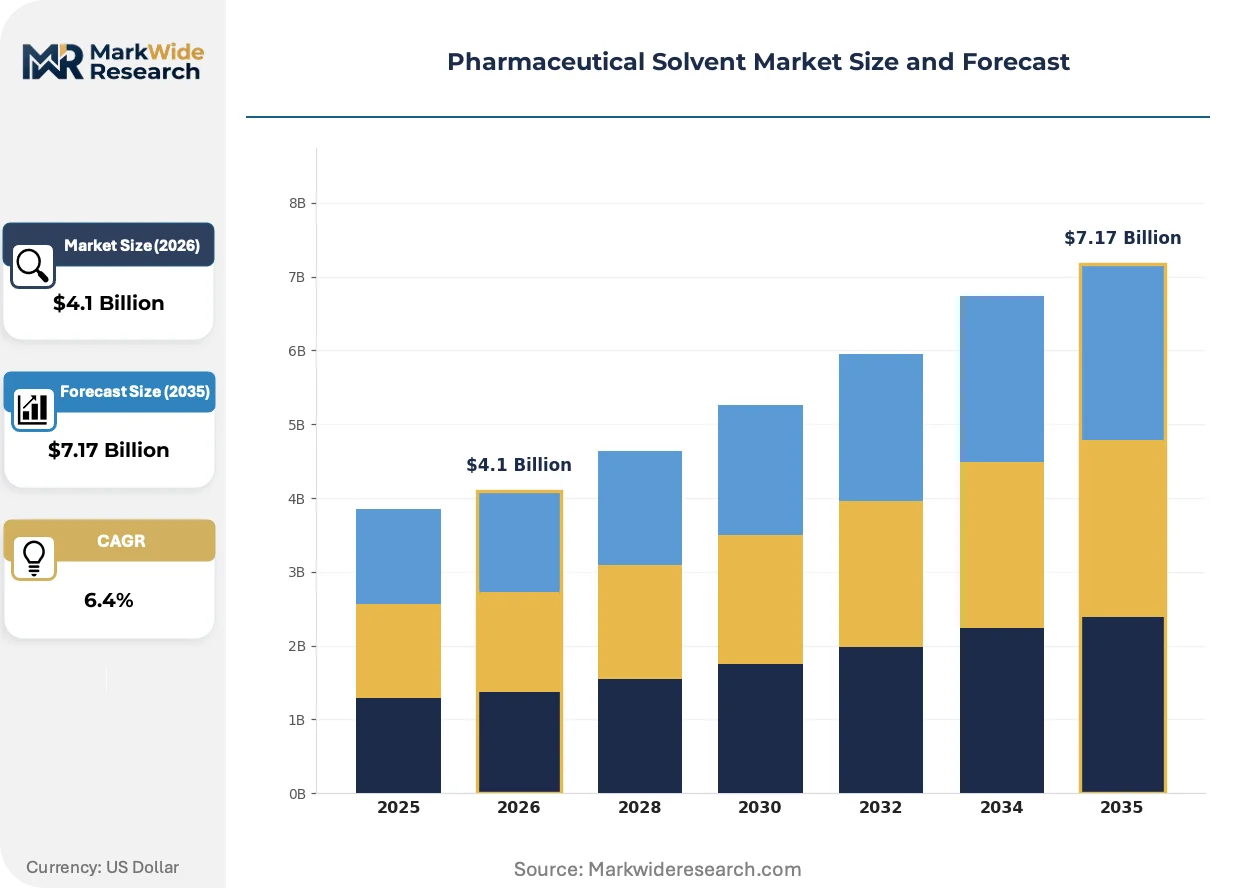
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water, Ethanol, Acetone, Hexane Application: Extraction, Formulation, Cleaning, Chromatography End User: Pharmaceutical Companies, Contract Manufacturers, Research Laboratories, Hospitals Packaging Type: Drums, Bottles, Tanks, Pails |
| Companies Covered | Thermo Fisher Scientific, Eastman Chemical Company, BASF SE, Ashland Global Holdings, LyondellBasell Industries, Merck KGaA, Dow Inc., Arkema S.A., Avantor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Solvent Market Strategic Shifts & Innovations
Innovation in the pharmaceutical solvent market is driven by the convergence of green chemistry principles with the analytical precision demanded by next-generation therapeutics. This is prompting significant evolution in both solvent composition and sourcing strategies across the value chain.
Bio-based solvents, derived from sources like corn or sugarcane, offer a sustainable alternative to traditional petrochemical-based products for certain applications. Large pharmaceutical manufacturers and their contract partners are adopting these green solvents for non-critical processes to improve their environmental footprint. This adoption of sustainable alternatives is consolidating the market around suppliers who can provide certified, renewable options without compromising required purity standards.
The European Chemicals Agency's (ECHA) enforcement of REACH regulations places greater scrutiny on the entire lifecycle of chemical substances, including solvents used in drug manufacturing. This directive requires extensive documentation on safety and environmental impact, increasing compliance costs for producers supplying the European Union. The excipients and API synthesis segments are most affected, forcing a reassessment of solvent portfolios to ensure compliance.
Centralized purchasing by large contract development and manufacturing organizations (CDMOs) is progressively replacing decentralized, lab-level procurement models. This consolidation of buying power favors large-scale solvent suppliers capable of offering volume-based pricing, global logistics, and harmonized quality documentation across multiple sites. This trend is most prominent within the major pharmaceutical manufacturing clusters of India, Ireland, and Switzerland.
Pharmaceutical Solvent Market Segmentation
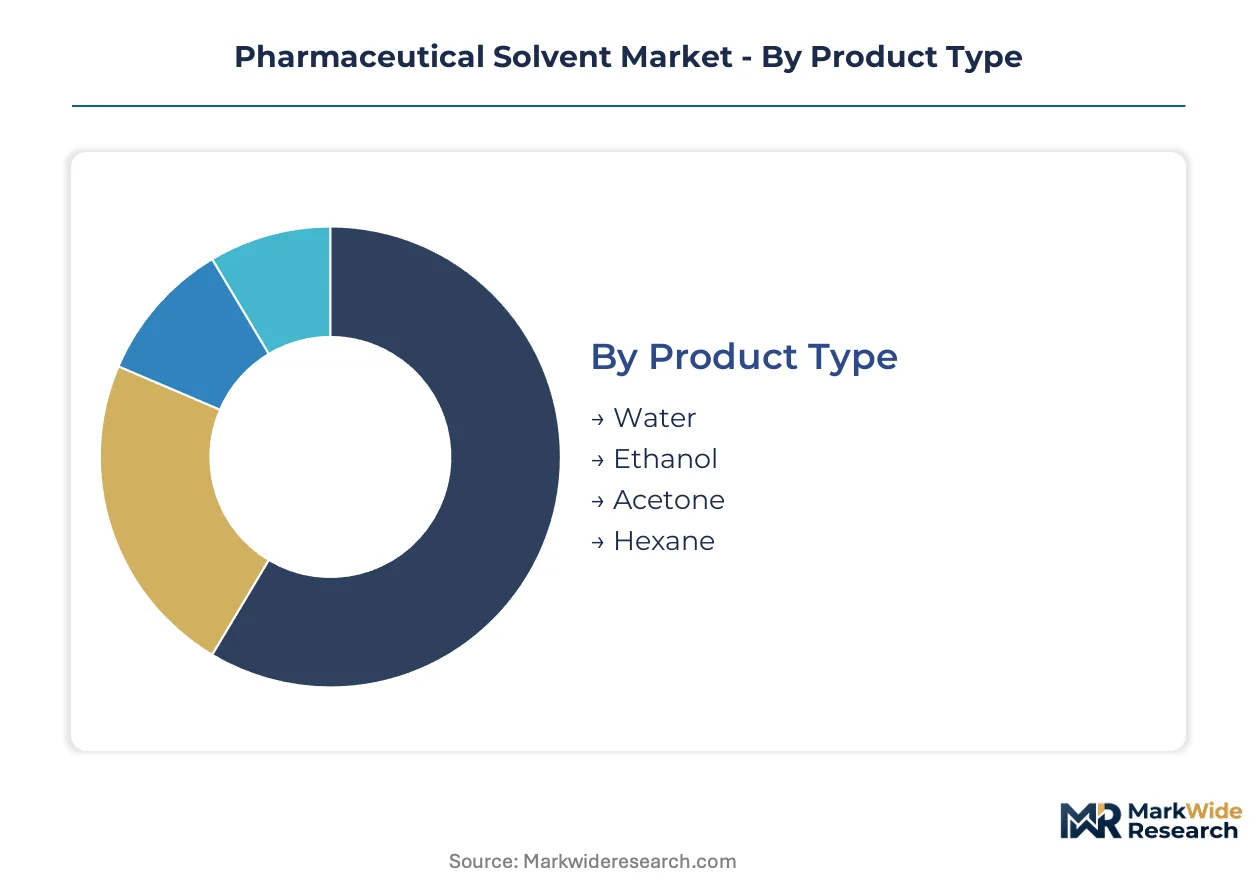
The pharmaceutical solvent market's segmentation highlights the diverse technical requirements and operational scales across drug manufacturing. Each segment reflects distinct purity standards, application-specific demands, and logistical considerations essential for product integrity and regulatory compliance.
Product Type:
The selection of pharmaceutical solvents hinges on specific chemical properties and required purity levels for diverse drug manufacturing processes.
- Water:Essential for sterile injectables and aqueous formulations, requiring extremely high purity grades like Water for Injection (WFI). Demand is concentrating in biologic drug manufacturing and aseptic processing facilities.
- Ethanol:A highly versatile solvent with a favorable safety profile, widely used in various drug forms, including oral solutions, topical preparations, and extraction processes. Demand is high in formulation and extraction, especially in regions with established pharmaceutical production like India.
- Acetone:A polar aprotic solvent, often used in API synthesis and cleaning processes for its strong dissolving power.
- Hexane:A non-polar solvent, frequently employed in extraction and purification steps for specific organic compounds in drug production.
Ethanol leads on scale; Water leads on momentum in advanced biologic formulations.
Application:
Each application within pharmaceutical manufacturing demands distinct solvent properties and purity standards.
- Formulation:Involves dissolving active pharmaceutical ingredients (APIs) and excipients to create the final drug product, requiring solvents that ensure stability and bioavailability. Demand is highest across all pharmaceutical manufacturing clusters, driven by the sheer volume of drug production.
- Chromatography:Utilizes high-purity solvents for analytical testing, quality control, and purification of complex molecules like biologics, demanding stringent purity specifications. This segment is expanding rapidly with the growth of analytical testing and R&D in biopharmaceuticals.
- Extraction:Isolates desired compounds from raw materials or reaction mixtures, often requiring specific solvent polarity for efficient separation.
- Cleaning:Removes residues from equipment and production lines, where solvents must be effective yet leave no harmful traces.
Formulation represents the largest volume consumption, while chromatography demonstrates the steepest expansion trajectory.
End User:
The operational scale and regulatory environment of end-users significantly influence solvent procurement and usage patterns.
- Pharmaceutical Companies:Large-scale drug producers requiring consistent, high-volume supply of certified solvents for in-house API synthesis and drug formulation. Procurement authority is shifting to centralized departments in these organizations, impacting supplier relationships.
- Contract Manufacturers:Provide specialized services for drug development and production, demanding flexible solvent portfolios that meet diverse client specifications and regulatory requirements. Their concentration in regions like Ireland and India drives significant solvent demand.
- Research Laboratories:Utilize solvents for drug discovery, preclinical testing, and analytical development, often requiring small quantities of highly specialized grades.
- Hospitals:Primarily use pharmaceutical-grade solvents for compounding medications, preparing sterile solutions, and for certain diagnostic procedures.
Large pharmaceutical companies dictate significant volume, while contract manufacturers increasingly shape procurement dynamics.
Packaging Type:
Packaging choices for pharmaceutical solvents are driven by considerations of volume, safety, and logistical efficiency.
- Drums:Standard industrial packaging for bulk quantities, typically 200-liter capacity, used for shipping and storing solvents in manufacturing facilities. They offer a balance of volume and manageability for many pharmaceutical operations.
- Tanks:Large-volume containers, including ISO tanks and dedicated storage tanks, used for high-volume solvent delivery and on-site storage, particularly beneficial for large pharmaceutical plants with consistent demand. This minimizes handling and reduces waste.
- Bottles:Smaller containers, ranging from milliliters to several liters, primarily used for laboratory-grade solvents, R&D, and specialized, high-purity applications.
- Pails:Intermediate-sized containers, typically 20-25 liters, offering a convenient option for medium-scale usage or specific batch processes in pharmaceutical production.
Drums remain a versatile option, while tanks facilitate high-volume, cost-effective solvent delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's expanding pharmaceutical manufacturing base drives substantial solvent demand, contrasting with the United States' focus on high-purity solvents for advanced biologics. Regulatory frameworks and local production capabilities significantly influence regional market dynamics. Specific regional clusters concentrate solvent consumption and supply.
United States
Demand for ultra-high purity solvents is driven by the robust biopharmaceutical sector and cell therapy advancements. The US FDA's stringent guidelines for residual solvents necessitate premium-grade products in drug formulation. Major pharmaceutical hubs like the Greater Boston area concentrate R&D and manufacturing, requiring specialized solvent portfolios.
Germany
European pharmaceutical production, particularly in Germany, relies on high-quality solvents for both API synthesis and complex drug formulations. ECHA's REACH regulations mandate comprehensive safety documentation for all chemical substances, impacting solvent selection. The Rhine-Main region, a key chemical and pharma cluster, sees consistent demand for certified solvents.
India
India's position as a global pharmaceutical manufacturing hub fuels high-volume demand for ethanol and other formulation solvents. The Central Drugs Standard Control Organization (CDSCO) enforces purity standards, influencing procurement decisions for local producers. Manufacturing clusters in Gujarat and Maharashtra are significant consumers of pharmaceutical-grade solvents.
China
Expanding domestic drug production and a growing biopharmaceutical industry drive China's need for diverse pharmaceutical solvents. The NMPA's evolving drug quality standards increasingly push for higher purity grades across the industry. Production facilities in the Yangtze River Delta region represent a large and growing market for these essential chemicals.
Ireland
Ireland's strong presence in biologic drug manufacturing necessitates specialized, high-purity solvents for advanced processes. The EMA's strict regulatory oversight impacts solvent qualification for both local and multinational pharmaceutical operations. The Cork region, a major pharmaceutical cluster, experiences concentrated demand for solvents used in bioprocessing.
Pharmaceutical Solvent Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in pharmaceutical solvents. The market exhibits a tiered structure, with large chemical producers offering broad portfolios alongside niche suppliers of ultra-high purity or bio-based alternatives. Strategic archetypes include integrated chemical giants, specialized solvent manufacturers, and green chemistry innovators. Companies frequently pursue capacity expansion and strategic partnerships to enhance their market presence and supply chain resilience.
Specialists in large-scale production and diversified chemical offerings include BASF SE, a German-based chemical company, and Dow Inc., an American multinational chemical corporation. BASF SE occupies a position as a high-volume supplier, leveraging its extensive global production network to meet diverse industrial demands. Dow Inc. represents a provider of specialized formulations, particularly for sensitive biologic drug manufacturing, focusing on performance and purity. Eastman Chemical Company, an American chemical company, anchors the segment for green and bio-derived solvent alternatives, aligning with evolving corporate sustainability mandates and regulatory pressures.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eastman Chemical Company |
| BASF SE |
| Ashland Global Holdings |
| LyondellBasell Industries |
| Merck KGaA |
| Dow Inc. |
| Arkema S.A. |
| Avantor Inc. |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility introduces cost instability for solvent manufacturers, which translates into variable pricing for pharmaceutical companies sourcing these critical inputs downstream. This dynamic forces a continuous re-evaluation of procurement strategies to balance cost efficiency with stringent purity requirements.
Pricing Analysis
Capacity additions in India are reshaping price floors for high-volume, standard-grade solvents, especially ethanol. The dominant pricing model for large pharmaceutical companies involves contract-based long-term offtake agreements, while specialized grades for research laboratories often utilize per-unit transactional pricing. Price differentiation stems from purity grade specifications (e.g., 99.9%+) and regulatory certifications like ICH Q3C compliance. Pricing pressure stems from centralized purchasing by large CDMOs, particularly for commodity solvents. Research laboratories exhibit the least price sensitivity for ultra-high purity, specialized analytical solvents.
Supply Chain Analysis
Petrochemical feedstock supply for organic solvents primarily draws from global oil and gas markets, introducing commodity price volatility as a significant structural risk. Geographic supply concentration for finished pharmaceutical solvents centers on manufacturing hubs in Germany, the United States, and China. Water for Injection (WFI) production relies on localized, highly purified water sources. Distribution runs through direct sales channels from large chemical producers like BASF SE and Dow Inc. to major pharmaceutical companies. Smaller, specialized distributors serve research laboratories and niche applications, managing logistics for diverse product portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical solvent market operates as a regulatory compounder, with International Council for Harmonisation (ICH) Q3C guidelines on residual solvents significantly driving demand for higher purity grades.
For Market Incumbents: Cement long-term supply agreements with major pharmaceutical manufacturing clusters in India and Ireland to secure volume stability. Invest in green chemistry research and development to mitigate substitution threats from solvent-free manufacturing techniques. Pursue advanced certification investments aligning with pharmacopeia standards like USP and Ph. Eur. Focus on integrating digital traceability solutions across the supply chain to meet Good Manufacturing Practice (GMP) requirements.
For New Entrants and Emerging Players: Launch specialized, high-purity solvent portfolios targeting the rapidly expanding chromatography application segment. Penetrate nascent pharmaceutical manufacturing hubs in Southeast Asia by offering localized technical support and streamlined regulatory qualification assistance. Develop bio-derived solvent alternatives for non-critical processes, leveraging a direct sales model focused on sustainability credentials. Target small-scale research laboratories requiring specialized, high-purity grades with strong technical service.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs are high and specialized expertise is fragmented. The market remains viable over the next decade, driven by advanced biologics and stringent purity mandates. Target niche specialists in bio-derived solvents or ultra-high purity analytical grades for acquisition. The signal to watch for market inflection is the accelerated adoption rate of sustainable solvent alternatives by major contract development and manufacturing organizations (CDMOs).
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Allows suppliers to meet corporate sustainability mandates from large pharmaceutical clients. |
| Capacity Expansion | Enables manufacturers to serve the high-volume demand from growing pharmaceutical clusters. |
| Long-term Supply Agreement | Secures stable solvent supply for pharmaceutical companies, ensuring production continuity. |
| Product Launch (Bio-derived Solvent) | Differentiates offerings and aligns with evolving environmental regulations like ECHA REACH. |
| Regulatory Approval Pathway Acceleration | Expedites market entry for novel solvent grades meeting stringent US FDA and EMA requirements. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and industry reports — were reconciled to construct a comprehensive market perspective. This included engaging with procurement managers, R&D chemists, regulatory affairs specialists, and plant managers across the pharmaceutical value chain. Secondary data sources, such as US FDA filings, EMA submissions, ECHA REACH documentation, and company financial reports, provided essential validation points for bottom-up and top-down triangulation.
Historical data and expert panel input were cross-referenced to establish the analytical framework over the projection horizon. The quantitative model segmented the market across product type, application, end-user, packaging type, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived from integrating historical growth trends with projected future market dynamics, incorporating factors like biologic drug pipeline expansion and ICH Q3C guideline updates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen supply chain disruptions or accelerated technological shifts. The analysis reflects assumptions regarding regulatory stability, raw material availability, and sustained demand from the biopharmaceutical sector. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Natural Distillates Market
Solvents
Fluorinated Solvents Market
Solvents
India High Purity Solvents Market
Solvents
Dimethyl Formamide Market
Solvents
2-Butanone Market
Solvents
Ethyl Acetate Market
Solvents
Oxygenated Solvents Market
Solvents
1, 1-Difluoroethane Market
Solvents
Nitroglycerin Market
Solvents
Piperylene Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Ketone-Based Solvents Market
Solvents
Glycerol Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Nitromethane Market
Solvents
Nitrobenzene Market